
 Europe Vitamin a Market | 2026-2036
Europe Vitamin a Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vitamin a Market Foresight
Market Context
Direct sales channels for pharmaceutical-grade vitamin A is fragmenting as compounders and feed integrators build alternative procurement routes. DSM leverages its backward integration into fermentation-based beta-carotene to secure supply continuity for European drug manufacturers. BASF SE anchors its position through petrochemical-derived retinol acetate and palmitate streams serving animal nutrition and cosmetics. Zhejiang NHU Co., Ltd. competes on synthetic vitamin A alcohol pricing, though ECHA registration burdens limit its direct market access.
Technical and Segment Dynamics
Vitamin A denotes a group of fat-soluble retinoids—principally retinol, retinal, and retinyl esters—synthesized either through beta-ionone chemistry or extracted from fish liver oils and plant carotenoids, with purity grades spanning 1 million to 2.5 million IU per gram for pharmaceutical applications. Synthetic retinol dominates volume flows into animal feed premixes, while microencapsulated forms command premium positioning in infant formula and dietary supplements where oxidative stability determines shelf life. Food fortification applications in dairy and flour milling represent a mature, price-sensitive segment with thin margins, whereas cosmetics-grade retinol for topical anti-aging formulations sustains higher value capture per kilogram.
Regulatory Environment
EMA pharmacovigilance frameworks and EFSA nutrient reference values govern maximum permitted levels in fortified foods and supplements across EU member states, while REACH registration requirements for synthetic intermediates filter non-compliant importers from the supply base. The EU Green Deal's chemical sustainability targets are pressuring manufacturers to demonstrate bio-based feedstock shares in vitamin A production. Stakeholders must monitor the trajectory of the EU AI Act's deployment rules for automated quality control systems in GMP-certified vitamin facilities.
Market Dynamics
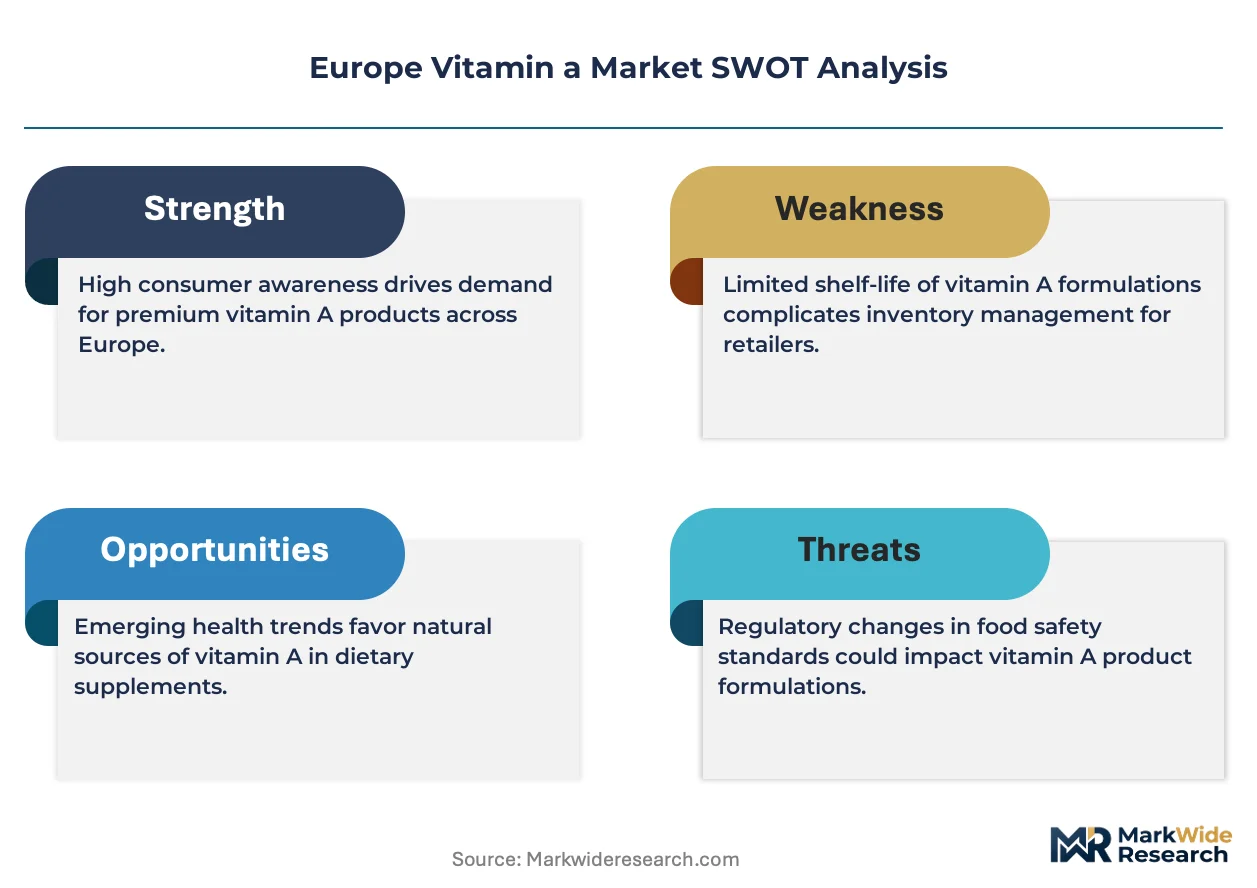
REACH registration burdens and EFSA novel food assessments are compressing the supplier base for synthetic vitamin A, forcing compounders toward fermentation-based beta-carotene alternatives and tightening purity benchmarks across pharmaceutical and feed applications.
Growth Catalysts
- EMA pharmacovigilance expansion:Stricter adverse-event reporting for retinoid-containing prescriptions drives demand for pharmaceutical-grade vitamin A with documented batch traceability.
- Animal feed premix standardization:EU-wide harmonization of vitamin A fortification levels in poultry and swine nutrition creates predictable offtake volumes for acetate and palmitate esters.
- Cosmeceutical microencapsulation:Lyophilized retinol formulations for topical anti-aging products command shelf-life premiums in French and German dermatology channels.
Market Restraints
- Beta-ionone feedstock volatility:Petrochemical-derived precursors face price swings tied to acetone and acetylene markets, squeezing margins for synthetic retinol manufacturers.
- Import concentration risk:Non-EU synthetic alcohol producers face ECHA registration delays, narrowing supply alternatives during peak demand cycles.
- Carotenoid substitution pressure:Beta-carotene and astaxanthin compete for antioxidant positioning in premium feed formulations, displacing retinyl esters in certain aquaculture applications.
Strategic Opportunities
- Polish and Romanian feed integrators:Underpenetrated compounder networks in Eastern Europe offer first-mover positioning for backward-integrated suppliers with REACH-compliant streams.
- Bio-based retinol certification:EU Green Deal chemical sustainability targets create premium positioning for fermentation-derived vitamin A with verified renewable feedstock shares.
- Direct-to-compounder digital platforms:B2B procurement portals bypass traditional distributor markups, capturing margin in Swiss and Dutch pharmaceutical clusters.
Industry Challenges
- GMP-audited facility scarcity:Qualified manufacturing sites for pharmaceutical-grade vitamin A concentrate in Basel and Lyon regions face capacity constraints and extended qualification timelines.
- Cross-border batch documentation:Divergent national implementations of EU FMD serialization requirements create compliance friction for multi-market supplement distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vitamin a Market |
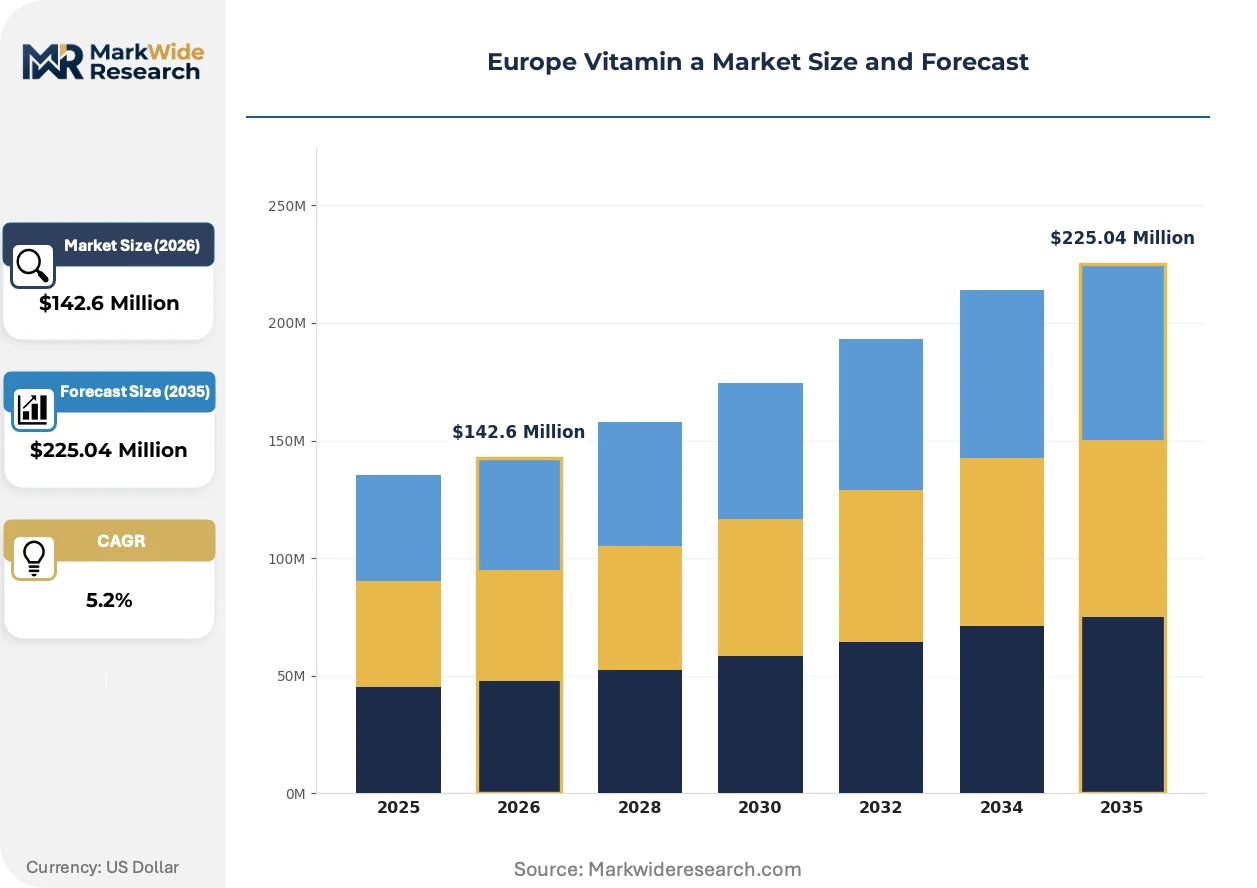
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $225.04 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
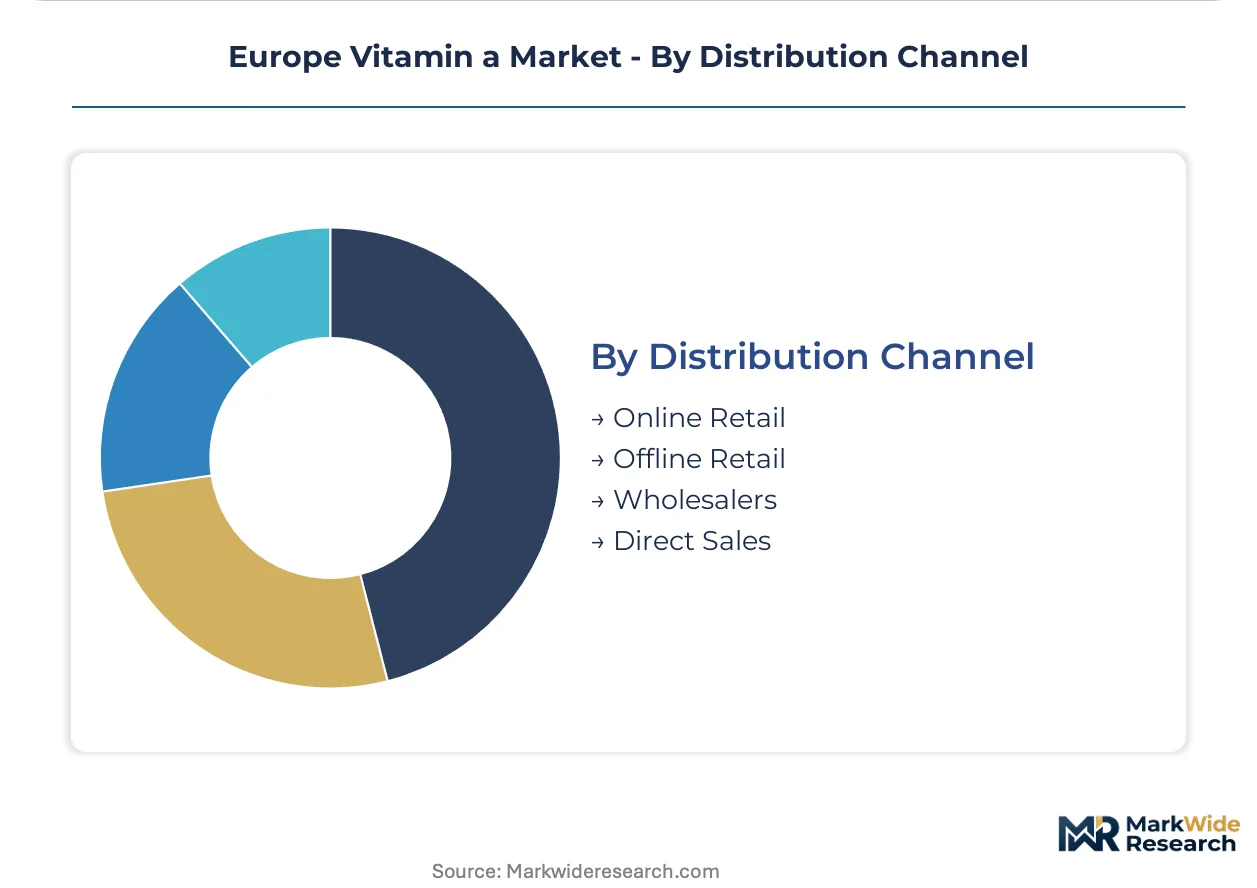
| Segmentation | Product Type: Natural, Synthetic, Microencapsulated, Beta-Carotene Application: Supplementation, Food Fortification, Cosmetics, Animal Feed End User: Pharmaceuticals, Food Industry, Cosmetics Sector, Veterinary Sector Distribution Channel: Online Retail, Offline Retail, Wholesalers, Direct Sales |
| Companies Covered | DSM, BASF SE, Zhejiang NHU Co., Ltd., Prinova Group LLC, Bluestar Adisseo Co., Ltd., BMP Bulk Medicines and Pharmaceuticals GmbH, CELLMARK AB, ParkAcre Ltd, Divi's Nutraceuticals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vitamin a Market Shifts & Advancements
Fermentation-based production methods and automated quality systems are recalibrating cost structures and compliance architectures across European vitamin A supply chains.
Continuous fermentation of beta-carotene using metabolically engineered yeast strains is collapsing the cost differential between synthetic petrochemical routes and bio-based alternatives. DSM and select contract manufacturers in the Netherlands and Germany are scaling these platforms for pharmaceutical-grade output. The technology is collapsing traditional volume premiums for natural-source vitamin A, forcing synthetic producers to defend position through acetate and palmitate purity grades.
EU AI Act deployment rules for automated quality control in GMP-certified facilities are mandating algorithmic validation protocols for retinol potency testing. EMA guidance on AI-assisted batch release is creating compliance templates that smaller compounders struggle to implement. Pharmaceutical manufacturers in France and Switzerland are prioritizing suppliers with pre-validated machine-vision inspection systems to accelerate regulatory filings.
Compounders in Germany and the Benelux are consolidating purchase volumes through preferred-supplier agreements with fermentation-based producers, displacing spot-market procurement of Chinese synthetic alcohol. Feed integrators in Denmark and Spain are mirroring this behavior, locking in multi-year contracts for beta-carotene-derived vitamin A. The shift is most visible in poultry nutrition, where oxidative stability specifications now favor microencapsulated forms with guaranteed shelf-life performance.
Europe Vitamin a Market Segmentation
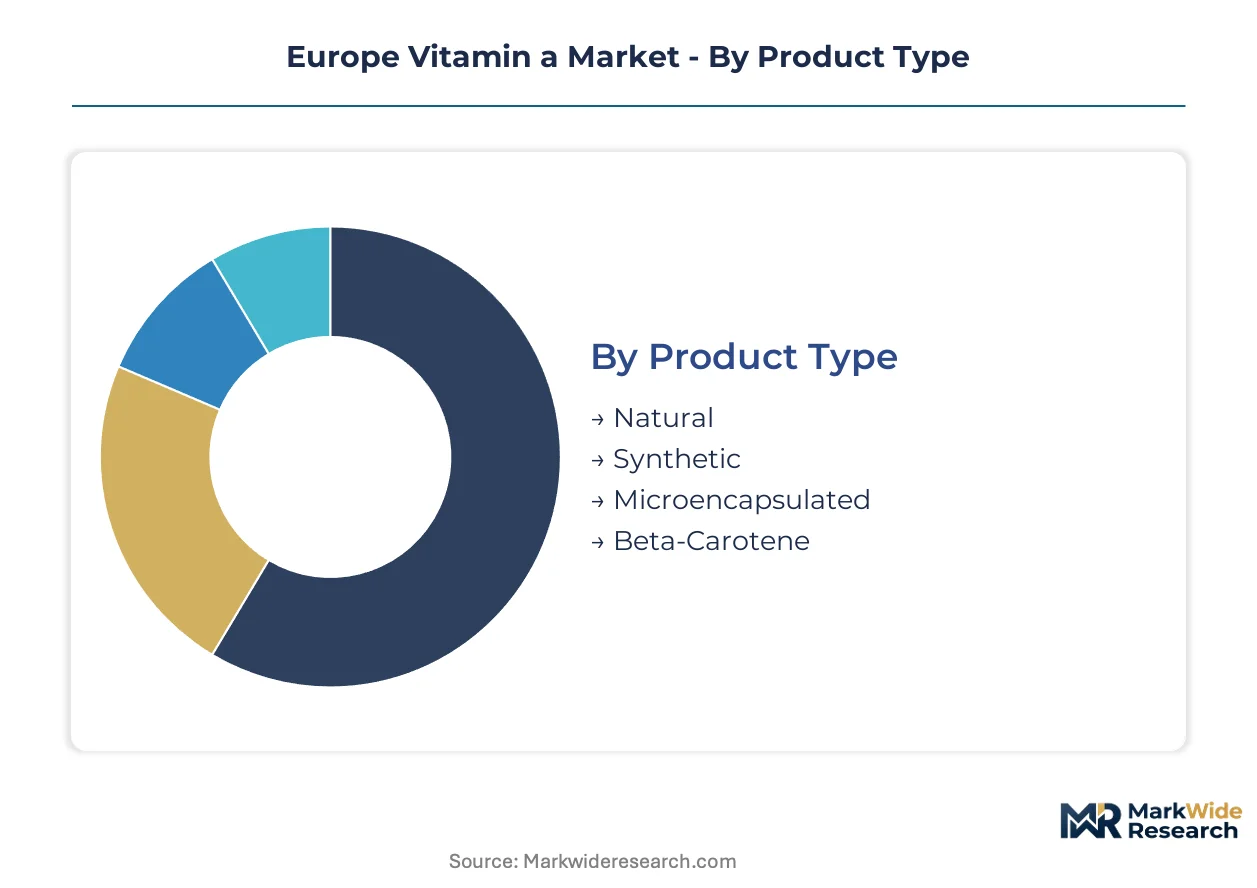
Segmentation in the Europe Vitamin A Market reveals how purity grades, regulatory pathways, and end-use specifications fragment procurement behavior across pharmaceutical, feed, and consumer channels. Manufacturers must align production configurations with distinct compliance architectures and margin profiles.
Product Type:
Cost tier differentiation separates commodity-grade synthetic retinol from premium-positioned natural and microencapsulated forms with verified oxidative stability.
- Natural:Extracted from fish liver oils and plant carotenoids, natural vitamin A carries EFSA novel food assessment burdens for new source approvals. Demand concentrates in German and French dietary supplement channels where clean-label positioning commands shelf-space premiums.
- Synthetic:Petrochemical-derived retinol acetate and palmitate dominate volume flows into animal feed premixes. Price volatility in beta-ionone feedstocks squeezes margins for European compounders dependent on acetone and acetylene precursor markets.
- Microencapsulated:Lyophilized retinol formulations with lipid-shell protection extend shelf life in infant formula and cosmeceutical applications.
- Beta-Carotene:Fermentation-derived provitamin A from engineered yeast strains collapses cost differentials against synthetic routes in REACH-compliant supply chains.
Synthetic retinol commands the established base. The steepest expansion runs through microencapsulated forms.
Application:
Application scope spans nutritional intervention, functional food systems, topical dermatology, and livestock productivity enhancement.
- Supplementation:Pharmaceutical-grade vitamin A concentrates at 1-2.5 million IU per gram serve prescription retinoid formulations and high-potency dietary supplements. EMA pharmacovigilance frameworks mandate batch traceability for adverse-event reporting, favoring suppliers with validated documentation systems.
- Food Fortification:Dairy and flour milling applications represent mature, price-sensitive demand with thin margins. EFSA nutrient reference values cap maximum permitted levels, compressing formulation flexibility for fortification integrators.
- Cosmetics:Topical anti-aging retinol commands value capture per kilogram through lyophilized and stabilized delivery systems.
- Animal Feed:EU-wide harmonization of poultry and swine nutrition standards creates predictable offtake volumes for acetate and palmitate esters.
Food fortification commands the established base. The steepest expansion runs through cosmetics applications.
End User:
Customer type determines specification intensity, with pharmaceutical and veterinary buyers imposing GMP-audited qualification requirements that consumer-facing sectors do not.
- Pharmaceuticals:Prescription retinoid manufacturers in Basel and Lyon clusters require pharmaceutical-grade concentrate with documented purity certificates. GMP-audited facility scarcity in these regions creates capacity constraints and extended supplier qualification timelines.
- Food Industry:Fortification integrators in dairy and milling prioritize cost-efficient synthetic retinol with basic stability specifications.
- Cosmetics Sector:French and German dermatology channels demand microencapsulated retinol with guaranteed shelf-life performance and oxidative stability data.
- Veterinary Sector:Feed compounders in Denmark and Spain lock in multi-year contracts for beta-carotene-derived vitamin A with EU feed hygiene regulation compliance.
Food industry procurement commands the established base. The steepest expansion runs through cosmetics sector uptake.
Distribution Channel:
Channel structure reflects margin capture strategies, with direct sales and digital platforms displacing traditional distributor markups in concentrated pharmaceutical clusters.
- Online Retail:B2B procurement portals enable compounders in Swiss and Dutch pharmaceutical hubs to bypass distributor markups and capture margin through direct supplier relationships.
- Offline Retail:Brick-and-mortar pharmacy and specialty store channels serve consumer supplement demand with established brand recognition.
- Wholesalers:Traditional distributors retain position in fragmented feed and food fortification markets where purchase volumes do not justify direct supplier negotiation.
- Direct Sales:Preferred-supplier agreements between fermentation-based producers and German-Benelux compounders consolidate procurement volumes and displace spot-market purchasing.
Wholesaler networks command the established base. The steepest expansion runs through direct sales channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western European pharmaceutical clusters command pricing premiums over Eastern European feed compounders, creating a two-tier procurement landscape that concentrates value capture in Basel and Lyon while volume flows concentrate in Polish and Romanian integrator networks.
Germany
Pharmaceutical-grade vitamin A demand concentrates around prescription retinoid formulations and infant formula fortification. EMA pharmacovigilance frameworks mandate batch traceability for adverse-event reporting, favoring suppliers with validated documentation systems. The Frankfurt-Rhine-Main corridor hosts GMP-audited compounding facilities facing capacity constraints and extended qualification timelines.
France
Cosmeceutical microencapsulated retinol drives premium positioning in dermatology channels, with lyophilized formulations commanding shelf-life premiums. ANSM oversight of cosmetic ingredient safety intersects with EFSA nutrient reference values for fortified food applications. The Lyon cluster anchors pharmaceutical-grade concentrate demand, with compounders consolidating procurement through preferred-supplier agreements.
Switzerland
Basel's pharmaceutical manufacturing density creates concentrated demand for 1-2.5 million IU per gram vitamin A concentrate with documented purity certificates. Swissmedic regulatory alignment with EU GMP standards streamlines cross-border supply into German and French markets. The region's GMP-audited facility scarcity intensifies competition for qualified manufacturing slots among retinoid formulators.
Poland
Feed integrator networks remain underpenetrated relative to Western European compounder density, offering first-mover positioning for REACH-compliant suppliers. Polish veterinary regulations align with EU feed hygiene standards while maintaining distinct national implementation timelines. Warsaw and Łódź logistics hubs facilitate distribution into Baltic and Eastern European poultry nutrition markets.
Netherlands
Fermentation-based beta-carotene production scales through Dutch contract manufacturing platforms, collapsing cost differentials against synthetic petrochemical routes. REACH registration compliance for bio-based intermediates filters non-compliant importers from direct market access. Rotterdam's port infrastructure handles bulk vitamin A acetate and palmitate ester flows for redistribution across Benelux feed premixers.
Europe Vitamin a Market Competitive Landscape
Backward-integrated fermentation specialists and petrochemical-derived retinol manufacturers split the market between bio-based premium positioning and synthetic volume efficiency. The supplier base compresses under REACH registration burdens and EFSA novel food assessment requirements, favoring compounders with captive production or long-term contract security. Three archetypes dominate: fermentation-based beta-carotene producers, synthetic retinol acetate/palmitate manufacturers, and microencapsulation specialists serving cosmeceutical channels. Competitive moves center on multi-year preferred-supplier agreements with German-Benelux compounders and capacity expansion in GMP-audited Basel-Lyon corridor facilities.
Within the fermentation-specialist tier, DSM anchors bio-based supply continuity for European drug manufacturers. BASF SE occupies a position across petrochemical-derived retinol streams serving animal nutrition and cosmetics applications. Zhejiang NHU Co., Ltd. exemplifies pricing-competitive synthetic alcohol positioning, though ECHA registration constraints limit its direct market access. These three represent the strategic archetype spectrum—bio-based integration, synthetic scale, and import cost leadership—that structures procurement alternatives for compounders navigating purity benchmark tightening.
| Leading Market Players |
|---|
| DSM |
| BASF SE |
| Zhejiang NHU Co., Ltd. |
| Prinova Group LLC |
| Bluestar Adisseo Co., Ltd. |
| BMP Bulk Medicines and Pharmaceuticals GmbH |
| CELLMARK AB |
| ParkAcre Ltd |
| Divi's Nutraceuticals |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp port corridor freight dynamics compress margins for acetate and palmitate ester shipments while amplifying price premiums for REACH-registered fermentation-derived vitamin A. Beta-ionone feedstock volatility from petrochemical precursor markets feeds directly into synthetic retinol pricing, forcing compounders toward bio-based alternatives with more stable cost structures.
Pricing Analysis
The customization-premium spread separates microencapsulated retinol formulations for cosmeceutical channels from commodity-grade synthetic acetate flowing into feed premixes. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and cosmetic-grade levels reflects purity certification intensity and EFSA compliance documentation. Cost compression in synthetic retinol is intensifying because beta-ionone precursor prices track acetone and acetylene commodity swings. Feed compounders in Eastern Europe exhibit highest price sensitivity, while Basel pharmaceutical manufacturers absorb premiums for batch-traceable concentrate.
Supply Chain Analysis
Dutch and German contract manufacturers hold dominant fermentation capacity for beta-carotene-derived vitamin A, with DSM anchoring pharmaceutical-grade output. Supply concentrates in the Netherlands, Germany, and Switzerland for REACH-compliant production, while China and India supply non-registered synthetic alcohol subject to ECHA delays. Beta-ionone, acetone, and acetylene feedstocks anchor synthetic route economics. Single-source vulnerability runs through GMP-audited facility scarcity in the Basel-Lyon corridor. Distribution runs through preferred-supplier agreements displacing spot-market procurement in German-Benelux compounder networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Vitamin A Market builds defensive moats through regulatory entrenchment, where REACH registration burdens and EFSA novel food assessments create multi-year barriers against non-compliant imports.
For Market Incumbents: Harden backward integration into fermentation-based beta-carotene to secure supply continuity against petrochemical feedstock volatility. Expand GMP-audited capacity in the Basel-Lyon corridor before qualification timelines extend further. DSM and BASF SE already anchor these positions; late movers face facility scarcity and extended EMA pharmacovigilance documentation requirements.
For New Entrants and Emerging Players: Pursue underpenetrated feed integrator networks in Poland and Romania where REACH-compliant suppliers remain scarce. Beta-carotene-derived vitamin A for poultry nutrition offers the most penetrable entry point, with oxidative stability specifications now favoring microencapsulated forms. A direct-to-compounder digital platform strategy bypasses traditional distributor markups in Swiss and Dutch pharmaceutical clusters.
For Investors and Strategic Acquirers: Fermentation-based mid-cap specialists with validated EU Green Deal bio-based certification represent the priority acquisition archetype. Long-term viability hinges on demonstrated renewable feedstock shares and pre-validated AI-assisted quality control systems for EMA batch release. Watch for EU AI Act deployment rule finalization as the inflection signal for compliance-cost escalation among smaller compounders.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Compliance | EMA pharmacovigilance frameworks mandate documented batch traceability for retinoid prescriptions. |
| Fermentation Capacity Expansion | Dutch contract manufacturing platforms collapse cost differentials against synthetic petrochemical routes. |
| Microencapsulation Technology Investment | Lyophilized retinol formulations command shelf-life premiums in French dermatology channels. |
| Preferred-Supplier Agreement Consolidation | German-Benelux compounders lock in multi-year contracts displacing spot-market Chinese synthetic alcohol. |
| AI-Assisted Quality Control Validation | EU AI Act deployment rules mandate algorithmic protocols for retinol potency testing in GMP facilities. |
Research Methodology
Operator-level perspectives from pharmaceutical procurement directors, feed compounder technical managers, and cosmetics formulation scientists anchored the qualitative base for this study. Primary interviews with DSM and BASF SE supply chain executives, Polish feed integrator purchasing leads, and Lyon-based GMP facility operators combined with secondary validation from EFSA novel food assessment databases, ECHA REACH registration filings, and EU Green Deal chemical sustainability progress reports. Bottom-up volume modeling across product type, application, and end-user segments triangulated against top-down macroeconomic indicators for the European pharmaceutical and animal nutrition sectors.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing for beta-ionone feedstock price volatility and ECHA registration timeline delays. Segmentation dimensions modeled include product purity grade, regulatory compliance tier, end-use application, and geographic procurement cluster. CAGRs derived from trend extrapolation of historical volume flows adjusted for EU feed hygiene regulation harmonization and cosmeceutical demand acceleration. Industry-specific forecast inputs incorporated EMA pharmacovigilance expansion timelines and fermentation yield improvement curves from Dutch contract manufacturing data.
Sensitivities concentrate around EFSA novel food assessment backlog durations, REACH registration renewal costs for synthetic intermediates, and EU AI Act compliance implementation speed for automated quality systems. Forecasts reflect assumptions on regulatory trajectory continuity and feedstock price correlation stability. Cross-checking against EMA adverse-event reporting database trends and Cefic chemical production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Vitamin B12 Drops Market
Vitamin Fortified
Vitamin E Market
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Delta-Tocopherol Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Global Vitamin Tonics Market
Vitamin Fortified
Vitamin D Market