
 Vegan Ingredients Market | 2026-2036
Vegan Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Ingredients Market Analytics
Plant protein formulation expertise is redrawing competitive boundaries across the supply chain. Ingredion leverages its starch and protein extraction infrastructure to anchor North American supply reliability. Perfect Day specializes in precision fermentation of whey-identical proteins without animal inputs. Roquette dominates pea protein processing capacity through its European manufacturing footprint.
Vegan ingredients comprise functional compounds derived from botanical, microbial, or cell-culture sources that replicate or replace animal-derived components in food systems, typically containing protein concentrations of 80-90% isolate purity for industrial applications. Plant-Based Proteins lead volume shipments due to established extraction infrastructure and cost-down curves in pea and soy fractions. Dairy Alternatives capture premium positioning as precision fermentation and enzymatic modification unlock functional parity with casein and whey in bakery and beverage matrices.
The FDA maintains GRAS notification pathways for novel plant proteins while the USDA oversees organic certification standards that shape ingredient procurement tiers. EU REACH and EFSA novel food assessments govern European market entry timelines for fermentation-derived proteins and emerging botanical extracts. Stakeholders must monitor evolving allergen labeling thresholds as novel protein sources complicate cross-contamination protocols and consumer transparency requirements.
Market Dynamics
Precision fermentation infrastructure is redrawing ingredient sourcing economics, compressing development timelines for animal-free proteins while fragmenting traditional commodity protein supply chains across food manufacturing networks.
Growth Catalysts
- EU Green Deal agricultural targets:Binding emission reduction mandates for European food manufacturers are accelerating plant-based protein adoption across bakery and beverage formulation lines.
- Precision fermentation scale-up:Industrial biotechnology advances are collapsing unit economics for whey-identical proteins, enabling functional parity in cheese and ice cream matrices without animal inputs.
- German processing hub concentration:Ingredient startups clustering around Berlin and Hamburg are creating dense supplier ecosystems that shorten R&D collaboration cycles for European food brands.
Market Restraints
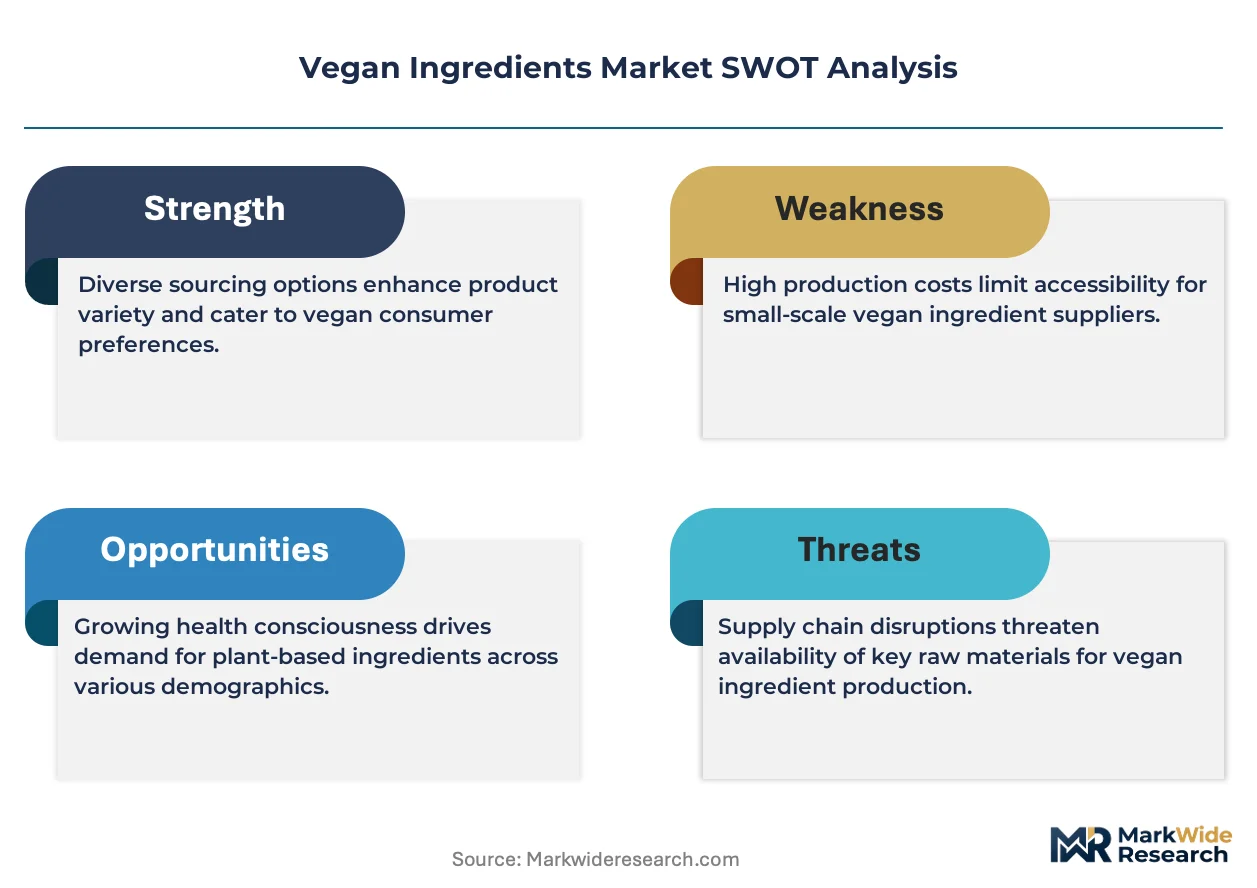
- Pea protein supply concentration:European processing capacity remains dominated by Roquette's manufacturing footprint, creating single-source vulnerability for mid-tier formulators.
- Novel food assessment timelines:EFSA regulatory pathways for fermentation-derived proteins extend market entry by 18-24 months, freezing capital deployment for biotech entrants.
- Soy fraction price volatility:Weather-driven harvest variability in South American growing regions transmits directly to isolate pricing, compressing margin predictability for budget-tier product lines.
Strategic Opportunities
- Precision fermentation-dairy hybrid platforms:Convergence of enzymatic modification and microbial protein production is unlocking textural performance previously unattainable in vegan cheese applications.
- Direct-to-manufacturer ingredient platforms:Bypassing traditional distribution layers, specialty protein suppliers are building captive procurement portals for mid-size European food producers.
- Organic certification tier expansion:USDA organic standards and EU organic regulations are creating premium procurement tiers that command 15-30% price multiples in clean-label product positioning.
Industry Challenges
- Cross-contamination protocol complexity:Novel protein sources are complicating allergen labeling thresholds, forcing manufacturers to rebuild sanitation validation systems for multi-ingredient production lines.
- Extraction equipment capex intensity:80-90% isolate purity requirements demand specialized membrane filtration and chromatography infrastructure that locks smaller formulators into toll-processing arrangements.
- Novel protein IP licensing friction:Patent thickets around precision fermentation strains are creating royalty stack burdens that distort competitive economics for second-wave entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Ingredients Market |
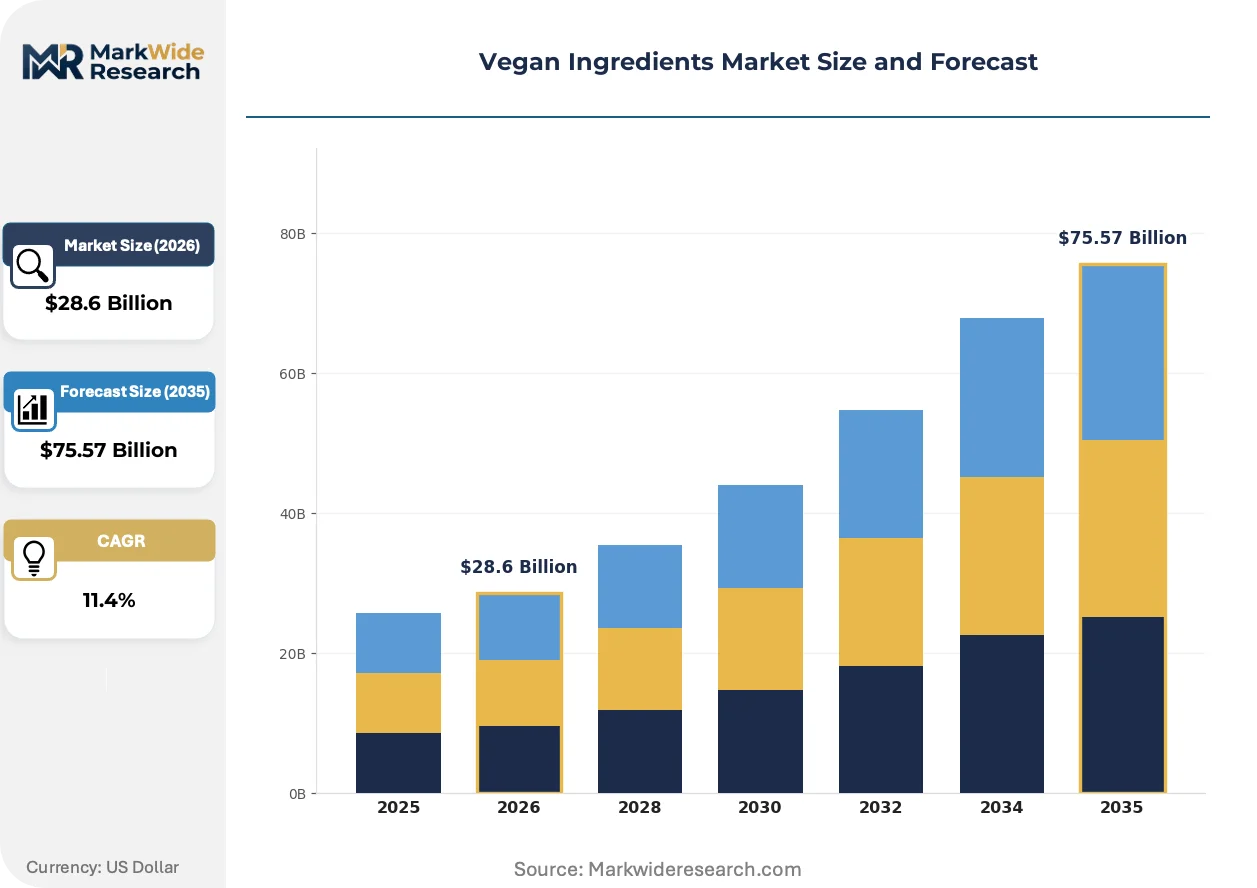
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Proteins, Natural Sweeteners, Vegetable Oils, Dairy Alternatives Application: Beverages, Snacks, Sauces, Bakery Form: Powder, Liquid, Granulated, Concentrate End User: Food Manufacturers, Restaurants, Retailers, Consumers |
| Companies Covered | International Flavors & Fragrances, Perfect Day, Ingredion, Novella Innovative Technology, Huel, Roquette, Quorn, Eclipse Ingredients, Burcon NutraScience Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Ingredients Market Evolving Landscape
Biotechnology-enabled protein production is fragmenting legacy commodity supply structures while regulatory frameworks race to catch up with ingredient innovation cycles. Three forces are compressing traditional development timelines.
Precision fermentation platforms are fragmenting conventional dairy protein supply chains by enabling functional whey and casein replication without herd-dependent inputs. Bakery and beverage manufacturers in Northern Europe are adopting these ingredients at pilot scale, with German and Dutch formulators leading integration into ice cream and cheese analog applications. The technology is fragmenting established supplier relationships as food brands build direct offtake partnerships with biotech producers.
EFSA novel food assessment pathways are tightening evidentiary requirements for fermentation-derived proteins, extending pre-market authorization timelines. This regulatory friction is concentrating first-mover advantages among firms that secured early dossier approvals, while later entrants face escalating toxicology study costs. Dairy alternative startups with 2022-2023 regulatory submissions are capturing shelf space that 2024 filers may not access until 2026.
Ingredient procurement is consolidating around sustainability-linked contracting, with European food manufacturers embedding carbon intensity metrics into supplier scorecards. Roquette and Ingredion are responding with farm-to-fork traceability platforms that document cultivation emissions for pea and potato protein fractions. Dutch and Danish food brands are most advanced in binding climate performance clauses into multi-year supply agreements.
Vegan Ingredients Market Segmentation
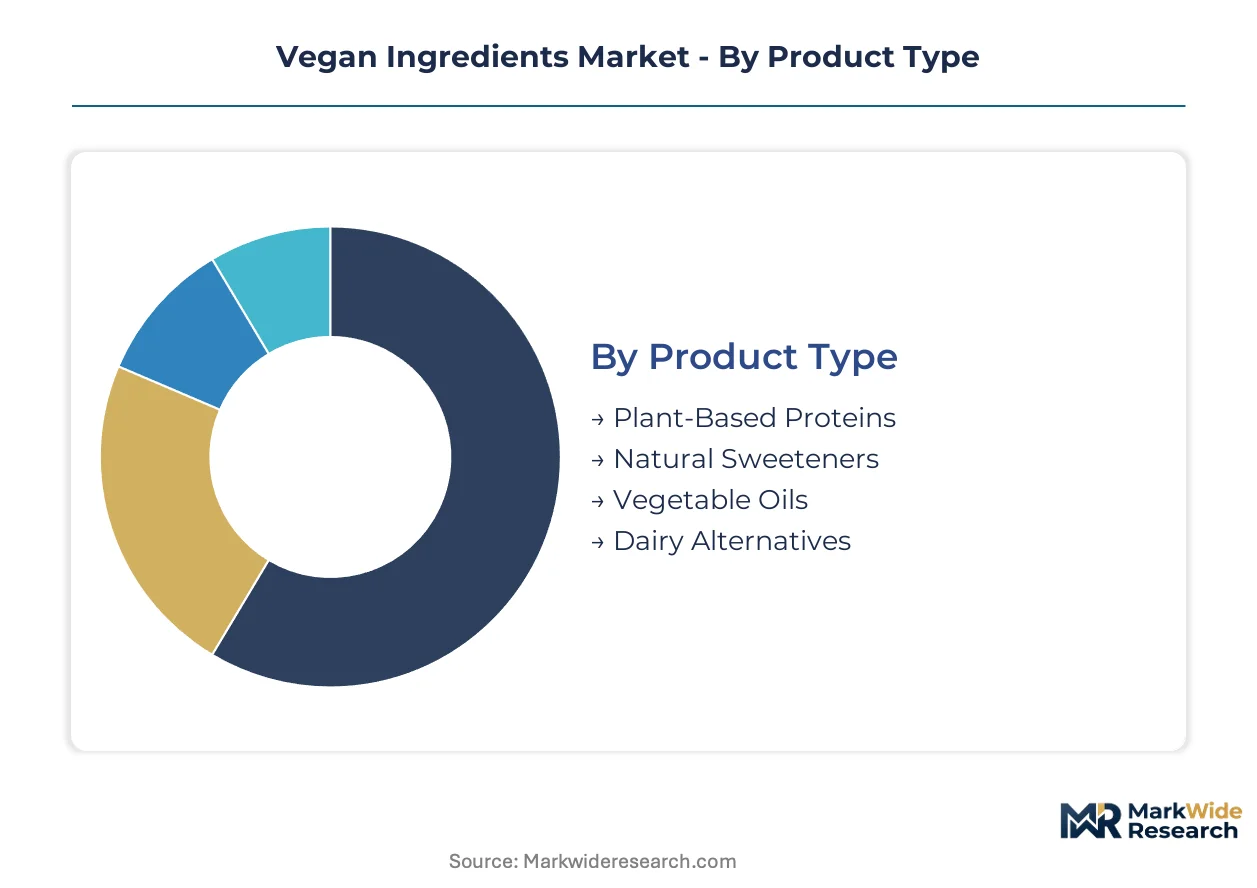
Channel configuration varies sharply across vegan ingredient categories. Powder forms dominate industrial procurement through direct manufacturer relationships, while liquid concentrates flow through foodservice distributors to restaurant chains.
Product Type:
Plant-based proteins and dairy alternatives move through divergent channel structures, with proteins flowing direct-to-manufacturer and dairy alternatives splitting between ingredient suppliers and finished goods distributors.
- Plant-Based Proteins:Isolates and concentrates with 80-90% protein purity specifications anchor industrial formulation in bakery and beverage matrices. German food manufacturers in Berlin and Hamburg processing corridors are scaling pea and soy fraction procurement to meet EU Green Deal procurement mandates.
- Dairy Alternatives:Precision fermentation-derived whey-identical proteins and enzymatically modified casein replacements achieve functional parity in cheese and ice cream applications. Dutch and Danish dairy alternative startups are securing direct offtake agreements with Northern European food brands, bypassing traditional ingredient distribution layers.
- Natural Sweeteners:Stevia and monk fruit extracts serve clean-label beverage reformulation.
- Vegetable Oils:High-oleic sunflower and algae oils supply frying and emulsification applications.
Plant-Based Proteins dominates installed base. Dairy Alternatives is where expansion concentrates.
Application:
Cost tier stratification separates premium positioning in beverages from volume-driven snack applications, with bakery occupying the mid-tier functional ingredient band.
- Beverages:Protein fortification and dairy alternative bases command premium formulation spending. Precision fermentation proteins are penetrating Dutch and German beverage manufacturer R&D pipelines for functional parity in ready-to-drink nutrition products.
- Bakery:Egg replacement and protein enrichment applications leverage pea and potato protein fractions for texture modulation. European bakery manufacturers are embedding carbon intensity metrics into supplier scorecards, favoring traceable farm-to-fork sourcing from Roquette and Ingredion platforms.
- Snacks:Extruded protein crisps and oil substitution drive commodity-scale procurement.
- Sauces:Emulsification and viscosity modification requirements favor specialized lipid and protein blends.
Bakery holds the deepest supplier integration. Beverages is climbing the fastest on precision fermentation adoption.
Form:
Supply concentration in powder processing creates single-source vulnerability, while liquid form manufacturing fragments across regional toll-processing networks.
- Powder:Spray-dried isolates with standardized particle size distribution enable consistent rehydration in industrial mixing equipment. Roquette's European manufacturing footprint concentrates pea protein powder capacity, forcing mid-tier formulators into captive procurement arrangements.
- Liquid:Ready-to-use protein suspensions and oil emulsions reduce hydration steps in continuous production lines. German ingredient startups around Hamburg are building direct-to-manufacturer portals for liquid concentrate supply to mid-size European food producers.
- Granulated:Controlled-release sweetener and protein formats suit tabletop and small-batch applications.
- Concentrate:Reduced-moisture protein and oil fractions optimize shipping economics for long-haul supply.
Powder dominates installed base. Liquid is where expansion concentrates.
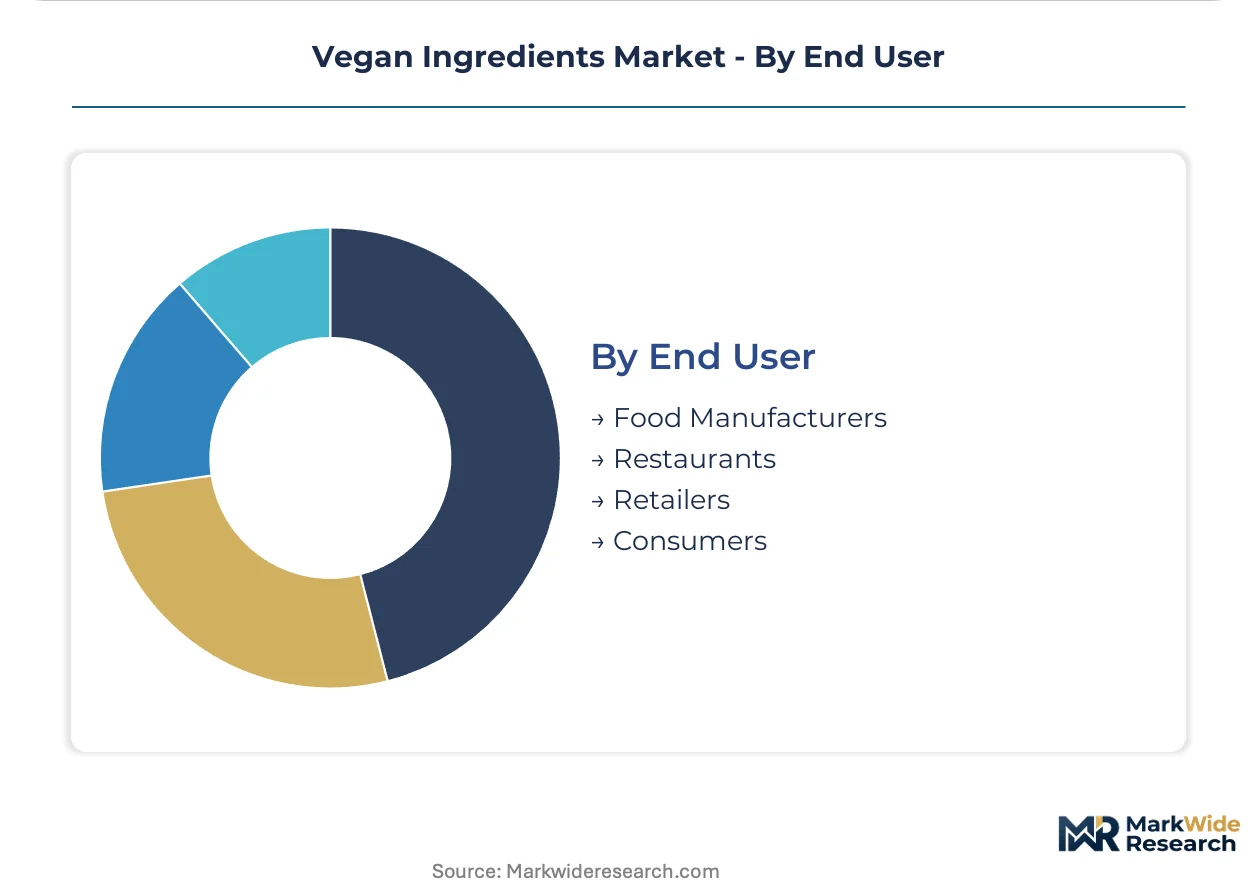
End User:
Customer type determines regulatory exposure depth, with food manufacturers facing full EFSA novel food compliance while retailers navigate downstream labeling obligations.
- Food Manufacturers:Industrial-scale formulators with multi-ingredient production lines face cross-contamination protocol complexity from novel protein sources. EFSA novel food assessment timelines of 18-24 months freeze capital deployment for fermentation-derived protein integration.
- Restaurants:Foodservice operators prioritize consistent supply reliability over ingredient provenance differentiation. Dutch and Danish restaurant chains are piloting precision fermentation dairy alternatives through direct distributor partnerships.
- Retailers:Private-label clean-label positioning commands 15-30% price multiples for organic-certified ingredient tiers.
- Consumers:Direct-to-consumer protein and sweetener sales remain niche, concentrated in specialty health channels.
Food Manufacturers dominates installed base. Restaurants is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys precision fermentation proteins for dairy alternatives at industrial scale, while the United States concentrates plant protein extraction for beverage fortification. China processes soy and pea fractions for cost-sensitive export markets. The Netherlands integrates carbon accounting into supplier procurement. France applies novel food regulations that delay biotech ingredient entry.
Germany
Precision fermentation scale-up and EU Green Deal procurement mandates drive ingredient demand. EFSA novel food assessments govern whey-identical protein authorization timelines. Berlin and Hamburg processing corridors cluster ingredient startups around Roquette manufacturing infrastructure.
United States
Plant protein extraction capacity and beverage manufacturer R&D pipelines anchor industrial demand. FDA GRAS notification pathways shape novel protein market entry protocols. Midwest processing facilities concentrate pea and soy fraction infrastructure for bakery and nutrition applications.
Netherlands
Carbon intensity metrics embedded in supplier scorecards and dairy alternative pilot programs reshape procurement patterns. EU REACH compliance requirements structure chemical safety documentation for botanical extracts. Dutch food brands in the Randstad region bind climate performance clauses into multi-year supply agreements.
France
Novel food assessment bottlenecks and traditional dairy sector resistance compress biotech protein adoption rates. EFSA toxicology study requirements extend pre-market authorization timelines. Paris-based formulators navigate regulatory friction while Lyon corridor manufacturers maintain conventional ingredient sourcing.
China
Soy fraction processing scale and export-oriented manufacturing capacity serve cost-sensitive global markets. SAMR food safety standards and GB certification requirements structure domestic ingredient quality tiers. Yangtze River Delta processing clusters concentrate isolate production for international bakery and beverage customers.
Vegan Ingredients Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with starch processors and fermentation biotech firms occupying distinct competitive bands. Roquette and Ingredion anchor the integrated processing layer through captive extraction infrastructure. Precision fermentation specialists and pea protein fractionators comprise the specialist tier. Capacity expansion and direct-to-manufacturer procurement portals represent the dominant competitive moves reshaping supplier relationships.
Among North American ingredient suppliers, International Flavors & Fragrances and Ingredion occupy positions within the integrated processing archetype, while Perfect Day exemplifies the precision fermentation specialist tier. These firms represent contrasting strategic approaches to animal-free protein production, with legacy processors leveraging existing infrastructure and biotech entrants building novel production platforms.
| Leading Market Players |
|---|
| International Flavors & Fragrances |
| Perfect Day |
| Ingredion |
| Novella Innovative Technology |
| Huel |
| Roquette |
| Quorn |
| Eclipse Ingredients |
| Burcon NutraScience Corporation |
| Others |
Value Network & Pricing Analysis
Roquette's European pea protein manufacturing footprint generates scale economies that compress unit costs for 80-90% isolate purity grades while simultaneously anchoring price floors through captive procurement arrangements. German food manufacturers clustering around Berlin and Hamburg processing corridors absorb these dynamics through multi-year supply agreements that embed volume-based tiering.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between ingredient suppliers and European food manufacturers, with spot purchases limited to emergency cover. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic-certified isolates from conventional grades and toll-processed commodity fractions. Cost compression in economy-tier soy isolates is intensifying because South American harvest variability transmits directly to margin predictability. Mid-tier formulators exhibit highest price sensitivity, while precision fermentation dairy alternative startups accept premium positioning for functional parity.
Supply Chain Analysis
Container availability fluctuations across Rotterdam-Antwerp-Hamburg trade lanes elevate inbound logistics costs for South American soy and Canadian pea fraction shipments. Supply concentrates in Germany, France, and the Netherlands for European processing, with raw material dependencies on Argentine soy harvests, Canadian yellow pea crops, and Chinese starch precursors. Single-source vulnerability runs through Roquette's dominant pea protein powder capacity. Distribution runs through direct-to-manufacturer portals for liquid concentrates and foodservice distributors for bakery applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EFSA novel food assessments creates defensive moats for first-mover fermentation biotech firms, with 18-24 month authorization timelines freezing capital deployment for followers.
For Market Incumbents: Secure precision fermentation strain patent portfolios before royalty stack burdens distort competitive economics for second-wave entrants. Anchor supply reliability through backward integration into membrane filtration infrastructure. Capture EU Green Deal procurement mandates by embedding farm-to-fork traceability platforms that document carbon intensity metrics for German food manufacturers.
For New Entrants and Emerging Players: Lead with direct-to-manufacturer ingredient platforms that bypass traditional distribution layers for mid-size European food producers. Target liquid concentrate supply to Dutch and Danish bakery manufacturers seeking reduced hydration steps in continuous production lines. Penetrate through sustainability-linked contracting that binds climate performance clauses into multi-year agreements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation specialists with secured EFSA dossier approvals and established offtake partnerships. Long-term viability rests on functional parity achievement in cheese and ice cream matrices without animal inputs. Acquisition target archetype: fermentation biotech firms with 2022-2023 regulatory submissions capturing shelf space ahead of 2024 filers. Signal to watch: EFSA toxicology study cost escalation as evidentiary requirements tighten.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Perfect Day's whey-identical protein production collapses unit economics for dairy alternatives. |
| Direct-to-Manufacturer Portal Launch | German ingredient startups around Hamburg shorten R&D collaboration cycles for European food brands. |
| Organic Certification Tier Expansion | USDA organic standards command 15-30% price multiples in clean-label positioning for retailers. |
| Backward Integration into Extraction Infrastructure | Ingredion's starch and protein extraction capacity anchors North American supply reliability. |
| Carbon Accounting Integration | Roquette's farm-to-fork traceability platforms document cultivation emissions for EU procurement scorecards. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with ingredient procurement managers, food manufacturer R&D directors, precision fermentation biotech executives, and EFSA regulatory affairs specialists; and secondary validation through FDA GRAS notification databases, EFSA novel food submission registers, EU REACH compliance documentation, and customs trade records for soy and pea fraction shipments. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, form, and end user dimensions.
Across the analysis window, forecast outputs reflect segmentation by plant-based protein versus dairy alternative categories, powder versus liquid form factors, and food manufacturer versus foodservice end user tiers. CAGRs derived from elasticity-adjusted volume projections incorporating EU Green Deal procurement mandate timelines and precision fermentation capacity buildout curves. Industry-specific inputs included EFSA novel food assessment pipeline tracking and Roquette manufacturing capacity utilization estimates.
The analysis sits within stated boundaries; outcomes outside sustained EU emission reduction mandate enforcement or precision fermentation strain viability breakthroughs would require recalibration. Forecasts reflect assumptions around regulatory pathway stability and agricultural commodity price normalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Gluten Free Flour Market
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
Food Amino Acids Market
Ingredients
Fermented Ingredients Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Europe Protein Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Yeast Flakes Market
Ingredients
Beetroot Powder Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Grape Seed Extracts Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
Cocoa Maker Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
South America Vegetable Oil Market