
 Lightweight Acoustic Floor Systems Market | 2026-2036
Lightweight Acoustic Floor Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Lightweight Acoustic Floor Systems Market Foresight
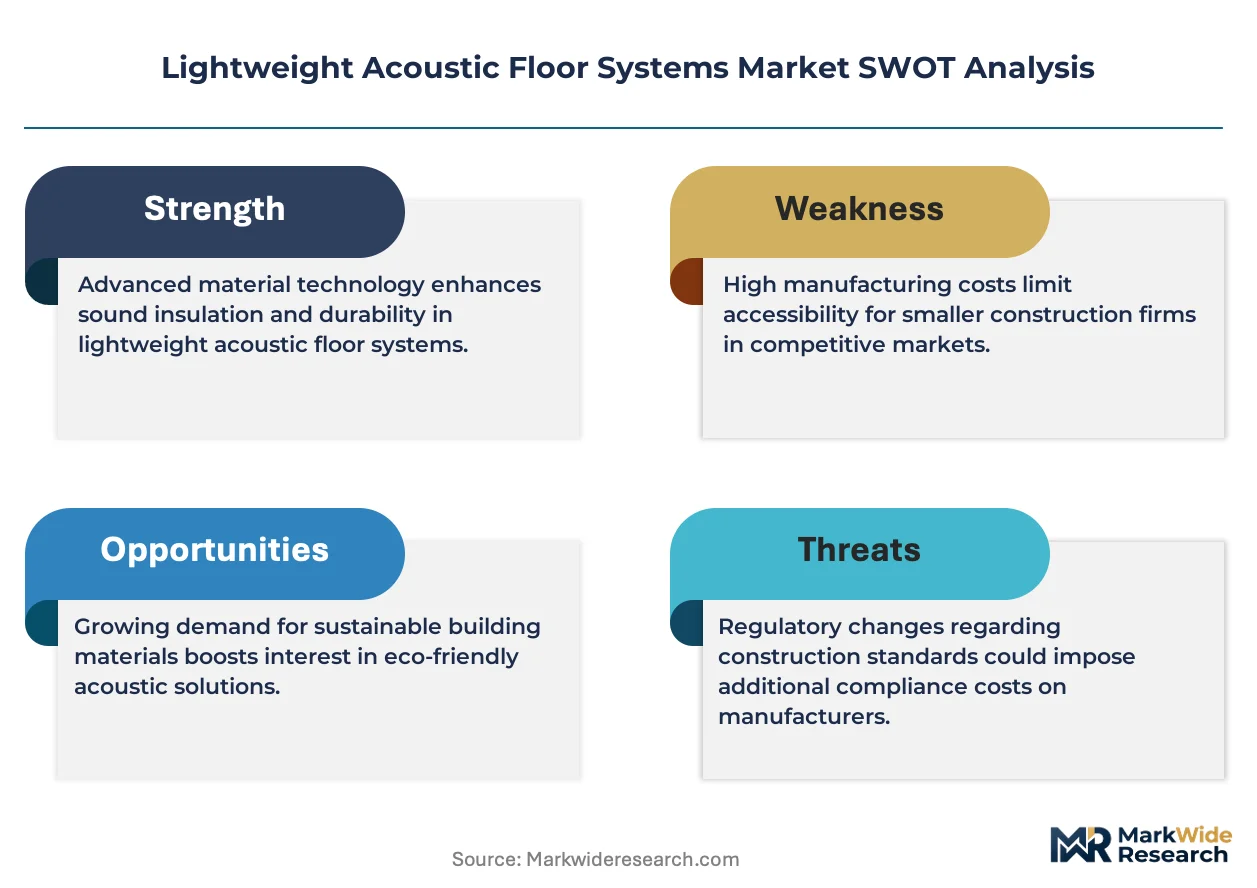
Platform licensing for acoustic performance modeling software is reshaping how building material suppliers capture recurring value. Saint-Gobain leverages its integrated building physics laboratories to anchor specification relationships with European architects. Kingspan Group competes through captive supply of insulated core boards that extend its control over finished floor assembly performance. Armstrong World Industries specializes in ceiling-floor system pairing, dominating cross-selling opportunities in commercial fit-outs.
Lightweight acoustic floor systems are engineered assemblies combining low-density substrates with viscoelastic or porous layers to achieve impact sound reduction indices of 50-65 dB at surface weights below 25 kg/m², primarily serving multi-occupancy buildings where structural load limits conflict with acoustic code requirements. Resilient underlayment leads product type value generation due to its compatibility with rapid floating installations in renovation cycles. The commercial application segment sustains premium pricing through specification-driven procurement tied to landlord lease obligations. Fiberglass material formulations are gaining specification share where fire resistance ratings intersect with acoustic targets.
EMA construction product standards, REACH substance restrictions on phthalate plasticizers, and CE marking under the Construction Products Regulation collectively determine material eligibility and market access across European member states. The EU Green Deal embodied carbon benchmarking is forcing reformulation of polymer-based underlayments toward bio-based or recycled feedstocks. Stakeholders must monitor how evolving EPBD renovation mandates redirect public procurement toward retrofit-optimized systems with demountable installation profiles.
Market Dynamics
The EU Green Deal embodied carbon benchmarking is compressing specification windows for polymer-based underlayments, forcing rapid reformulation toward bio-based feedstocks across German and Dutch multifamily residential pipelines.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:German and Dutch developers are accelerating floating floor assembly specifications to meet tightening construction material benchmarks.
- Heritage building conversion demand:Urban renovation corridors across France, the United Kingdom, and Scandinavia require mass-saving acoustic upgrades for structural load compliance.
- Resilient underlayment compatibility:Rapid floating installation methods align with compressed renovation cycles in commercial retrofit segments.
Market Restraints
- Phthalate plasticizer restrictions:REACH substance limitations on conventional polymer formulations increase reformulation costs and certification timelines.
- Supply concentration in insulated core boards:Captive supply structures by dominant building material suppliers limit price competition at the assembly level.
- Fire-acoustic performance trade-offs:Fiberglass formulations meeting dual certification requirements command material premiums that compress contractor margins.
Strategic Opportunities
- Demountable installation profiles:EPBD renovation mandates redirect public procurement toward retrofit-optimized systems with reversible assembly characteristics.
- Ceiling-floor system pairing:Cross-selling integration opportunities in commercial fit-outs create bundled specification pathways.
- Platform licensing for acoustic modeling software:Recurring revenue capture through building physics simulation tools anchors architect specification relationships.
Industry Challenges
- CE marking complexity under CPR:Multi-member state compliance variations create certification timeline fragmentation for pan-European product launches.
- Building physics integration:Specification relationships require in-house laboratory capabilities that mid-tier suppliers struggle to replicate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightweight Acoustic Floor Systems Market |
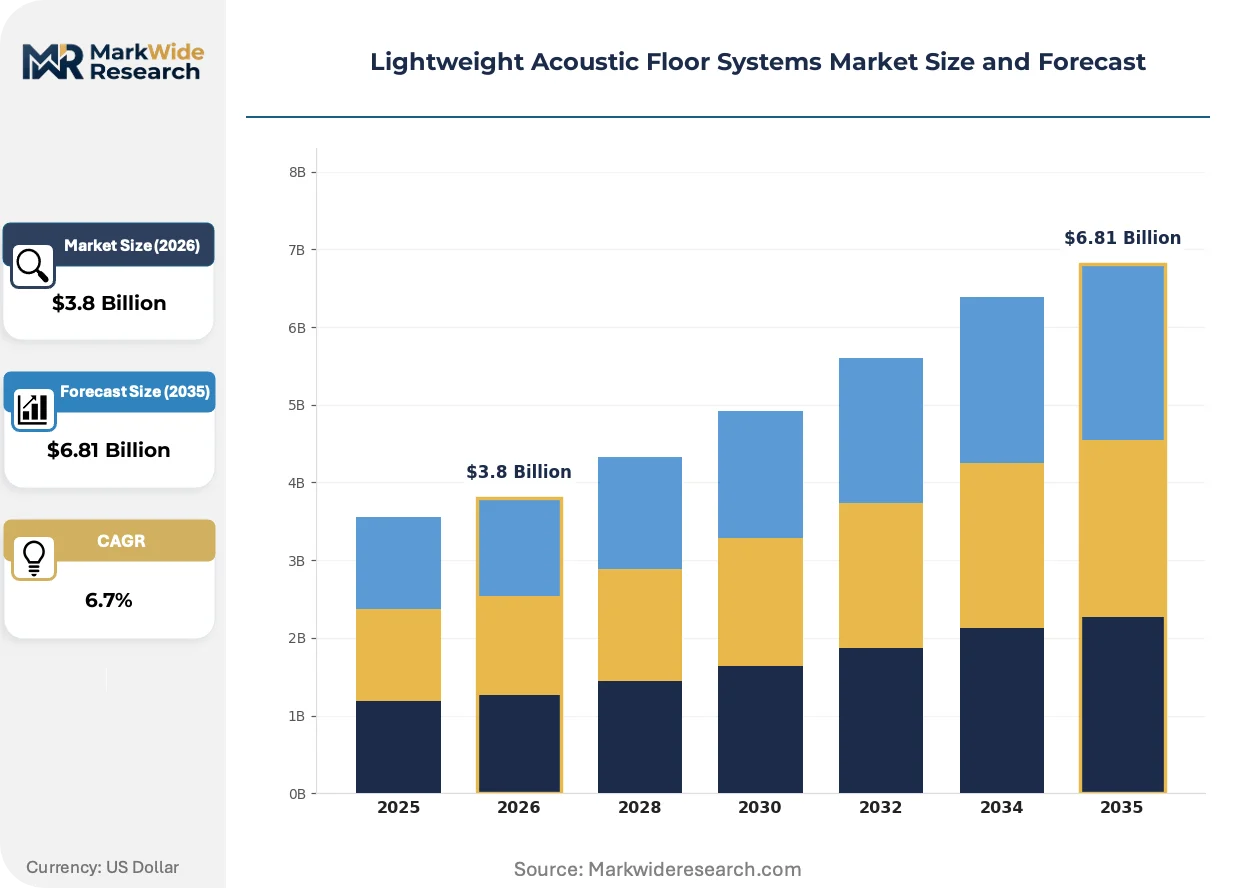
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Underlayment, Resilient Underlayment, Concrete Board, Acoustic Mats Application: Residential, Commercial, Industrial, Educational Installation Method: Glue-Down, Floating, Nail-Down, Stretch-In Material: Rubber, Carpet, Vinyl, Fiberglass |
| Companies Covered | Tarkett, Armstrong World Industries, Saint-Gobain, Forbo Flooring Systems, Möckel, USG Corporation, Rockwool International, Knauf Insulation, Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightweight Acoustic Floor Systems Market Shifts & Advancements
Material science convergence with digital specification tools is compressing traditional competitive moats. Three developments dominate the current transformation cycle.
Bio-based polymer underlayments derived from recycled feedstocks are rendering obsolete conventional petroleum-based resilient layers in German residential specifications. Multifamily developers in Berlin and Hamburg are mandating these formulations for new construction permits. The shift is compressing margin structures for legacy compound suppliers unable to pivot feedstock sourcing.
REACH substance restrictions on phthalate plasticizers are eliminating incumbent formulation pathways across EU member states. ECHA regulatory timelines are accelerating substitution investments by polymer compounders. French and British renovation contractors now face material availability constraints for legacy underlayment stocks.
Specification decisions are migrating toward integrated building physics platforms that simulate full assembly performance. Architects in Rotterdam and Copenhagen are bypassing traditional product catalogs for parametric acoustic modeling tools. This behavior shift concentrates influence with suppliers owning captive laboratory infrastructure and software licensing capabilities.
Lightweight Acoustic Floor Systems Market Segmentation
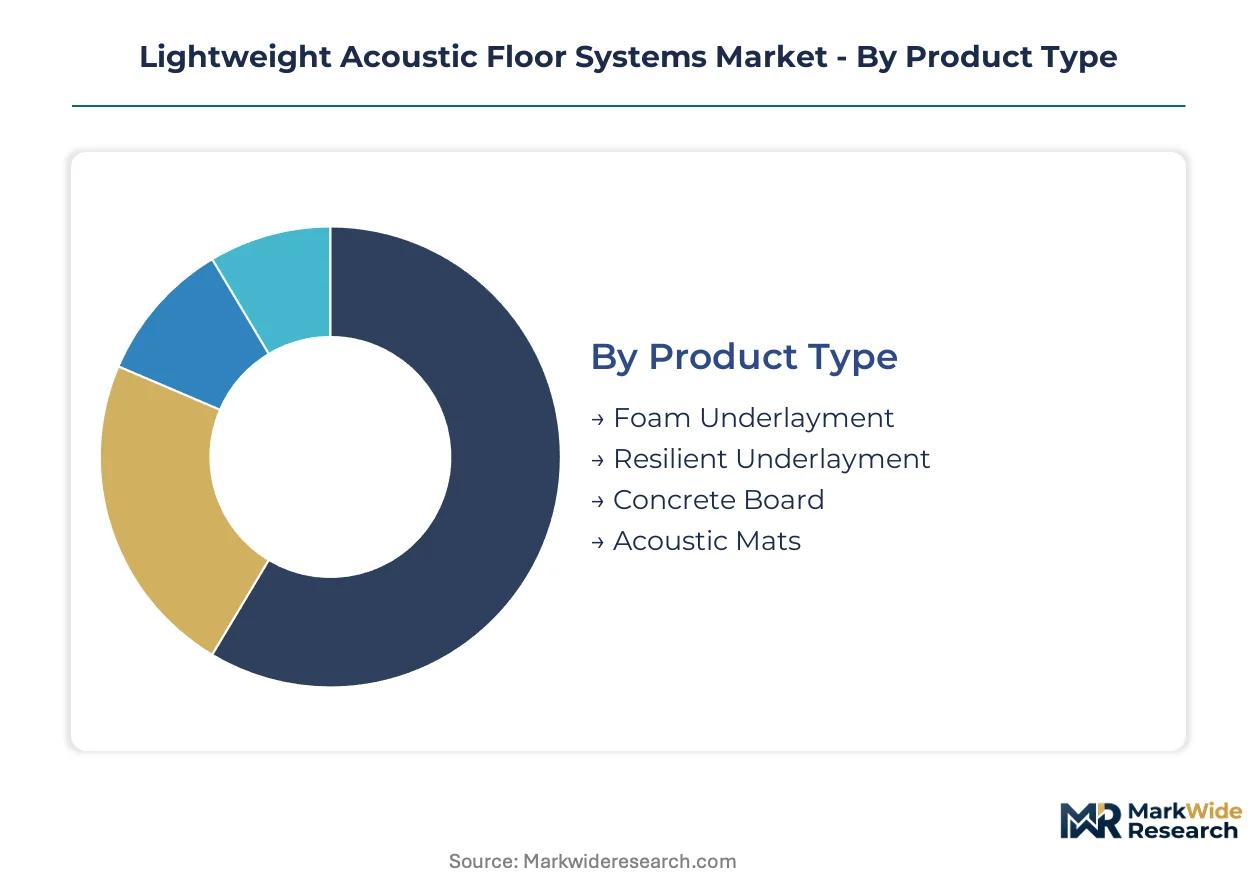
Specification pathways in acoustic flooring diverge sharply across building physics requirements, installation constraints, and regulatory compliance tiers. Understanding these dimensional splits reveals where procurement budgets concentrate and where reformulation investments deliver competitive shelter.
Product Type:
Cost tier differentiation separates commodity underlayments from engineered assembly systems with certified performance guarantees.
- Resilient Underlayment:Viscoelastic polymer or rubber-based layers engineered for impact sound reduction indices above 50 dB. German and Dutch multifamily developers specify these for floating floor assemblies under tightening EU Green Deal embodied carbon benchmarks.
- Foam Underlayment:Low-density polyethylene or polyurethane substrates offering basic acoustic dampening at entry price points. French and British renovation contractors deploy these where compressed project timelines prioritize rapid installation over premium performance ratings.
- Concrete Board:Cementitious panels with integrated acoustic isolation layers for mass-critical structural upgrades.
- Acoustic Mats:Thin-profile recycled rubber or textile composites for retrofit applications with severe height constraints.
Resilient underlayment commands the established base. The steepest expansion runs through foam underlayment as bio-based feedstock reformulation opens specification access in carbon-regulated jurisdictions.
Application:
Building occupancy codes determine acoustic performance thresholds and procurement authority structures.
- Commercial:Office, hospitality, and retail fit-outs where landlord lease obligations mandate documented sound transmission class ratings. Scandinavian property investors drive premium specification through long-hold asset management strategies.
- Residential:Multifamily apartments and condominiums with impact insulation class requirements varying by national building codes. Rotterdam and Copenhagen developers concentrate demand for demountable floating systems in renovation corridors.
- Educational:Schools and universities with extended durability requirements under public procurement frameworks.
- Industrial:Manufacturing and logistics facilities where acoustic treatment intersects with occupational exposure limits.
Commercial applications anchor revenue concentration through specification-driven procurement. Residential retrofits are climbing the fastest as EPBD renovation mandates redirect public funding toward mass-saving acoustic upgrades.
Installation Method:
Project delivery speed and reversibility requirements partition contractor capabilities and material eligibility.
- Floating:Interlocking or loose-laid assemblies requiring no mechanical fastening to structural substrates. Berlin and Hamburg developers mandate these for rapid renovation cycles where building occupancy cannot be interrupted.
- Glue-Down:Adhesive-bonded systems offering maximum acoustic contact but extended curing timelines and substrate preparation costs.
- Nail-Down:Mechanically fastened applications constrained by structural penetration restrictions in heritage conversions.
- Stretch-In:Tension-mounted carpet systems with integrated underlayment for commercial fit-out speed.
Floating installation dominates new specification as demountability becomes a procurement scoring criterion. Glue-down retains share in premium commercial segments where performance guarantees override speed priorities.
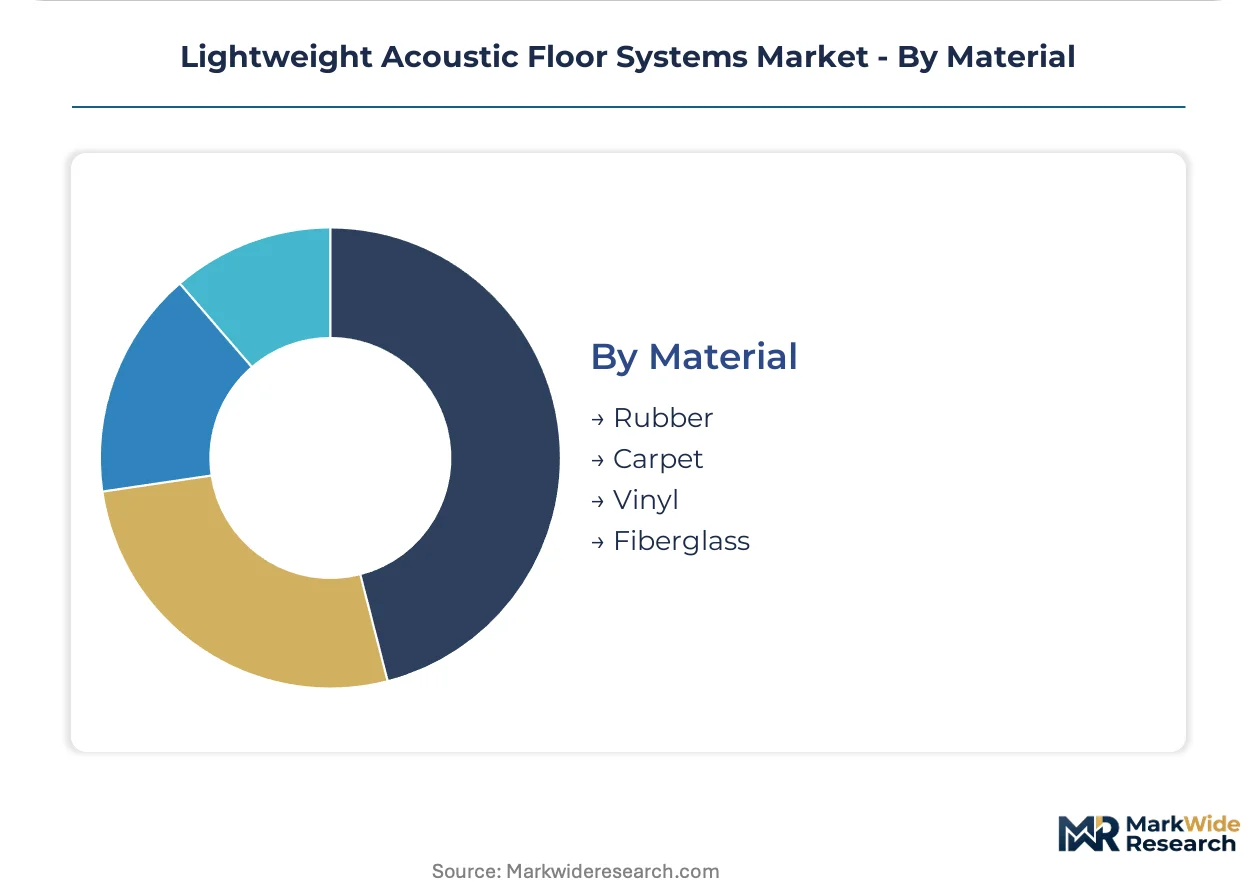
Material:
Feedstock chemistry determines regulatory compliance pathways and fire-acoustic performance trade-offs.
- Fiberglass:Mineral wool formulations achieving dual fire resistance and acoustic absorption certifications. REACH substance restrictions on polymer alternatives are redirecting specification toward these inorganic systems despite material premiums.
- Rubber:Natural and synthetic elastomer layers with proven durability in high-traffic commercial environments. ECHA regulatory timelines are accelerating substitution investments away from phthalate-plasticized compounds.
- Vinyl:PVC-based resilient layers facing reformulation pressure under EU Green Deal embodied carbon benchmarking.
- Carpet:Textile-faced systems with integrated acoustic backing for rapid commercial fit-out deployment.
Rubber formulations hold the installed base through proven performance histories. Fiberglass is gaining specification share fastest where fire-acoustic dual certification requirements intersect with polymer regulatory constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German multifamily developers exhibit the lowest price elasticity as EU Green Deal carbon thresholds tighten specification standards, while French renovation contractors face acute margin pressure from compressed project timelines and material availability constraints.
Germany
Berlin and Hamburg developers are mandating bio-based polymer underlayments for new construction permits as embodied carbon benchmarks harden. ECHA REACH substance restrictions are eliminating phthalate-plasticized compound pathways. The North Rhine-Westphalia industrial corridor hosts reformulation laboratories where compounders are accelerating substitution investments.
France
Paris and Lyon heritage conversion projects drive demand for mass-saving acoustic upgrades where structural load limits constrain traditional assemblies. The country's national building regulator enforces acoustic performance tiers through revised thermal and acoustic regulations. Île-de-France renovation contractors face material availability constraints as legacy underlayment stocks deplete.
Netherlands
Rotterdam developers concentrate procurement for demountable floating systems in dense urban corridors where building occupancy cannot be interrupted. CE marking under the Construction Products Regulation determines assembly eligibility for public housing tenders. The Randstad metropolitan cluster anchors specification relationships through integrated building physics platforms.
United Kingdom
London commercial property investors mandate documented sound transmission class ratings through landlord lease obligations. The country's building safety regulator enforces fire-acoustic dual certification requirements that compress contractor margins. Manchester and Birmingham renovation corridors prioritize rapid floating installation methods to minimize tenant displacement.
Sweden
Stockholm and Copenhagen architects are bypassing traditional product catalogs for parametric acoustic modeling tools. The Nordic Swan Ecolabel intersects with EU Green Deal benchmarks to privilege low-carbon feedstock formulations. Scandinavian property investors drive premium specification through long-hold asset management strategies in commercial fit-outs.
Lightweight Acoustic Floor Systems Market Competitive Landscape
Capability concentration sits with integrated building material conglomerates; scale advantage sits with specialized flooring and insulation fabricators. The market structures around three tiers: laboratory-anchored specification platforms, captive supply chains controlling core board production, and component specialists competing on installation speed. Dominant competitive moves include strategic partnerships with architect software platforms and backward integration into low-carbon feedstock sourcing.
Within the laboratory-anchored tier, Saint-Gobain and Kingspan Group exemplify divergent pathways to specification influence. Saint-Gobain occupies a position tied to integrated building physics infrastructure. Kingspan Group represents captive supply chain architecture extending control over finished assembly performance. Armstrong World Industries sits within the ceiling-floor system pairing specialization, anchoring cross-selling pathways in commercial fit-outs.
| Leading Market Players |
|---|
| Tarkett |
| Armstrong World Industries |
| Saint-Gobain |
| Forbo Flooring Systems |
| Möckel |
| USG Corporation |
| Rockwool International |
| Knauf Insulation |
| Kingspan Group |
| Others |
Supply & Pricing Matrix
Undercapacity in bio-based polymer feedstock production across Germany and the Netherlands is compressing supplier margins while amplifying pricing power for compounders with secured renewable supply contracts. This utilization squeeze forces buyers into longer-term offtake commitments to guarantee material eligibility under tightening EU Green Deal embodied carbon benchmarks.
Pricing Analysis
Platform licensing for acoustic performance modeling software generates recurring revenue streams that extend customer lifetime value beyond initial product sales. Three-tier pricing structure across premium, standard, and economy levels separates certified assembly systems with laboratory-backed guarantees from commodity underlayments competing on installation speed. Cost compression in entry-tier foam underlayments is intensifying because REACH reformulation timelines have stranded legacy compound inventories. French renovation contractors exhibit the highest price sensitivity due to compressed project timelines, while German multifamily developers show the lowest as carbon-regulated permitting requirements eliminate lower-cost alternatives.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for acoustic mat distributors serving British renovation corridors, straining working capital for mid-tier suppliers. Manufacturing concentration sits in Germany, France, and Belgium, with the North Rhine-Westphalia industrial corridor anchoring polymer compound production. Raw material sourcing draws from recycled rubber feedstocks, bio-based polyurethane precursors, and mineral wool fibers. Single-source vulnerability runs through insulated core board supply where Kingspan Group and Saint-Gobain maintain captive production. Distribution runs through specification-influencer channels where building physics laboratories and architect software platforms gatekeep procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ECHA REACH substance restrictions and EU Green Deal embodied carbon thresholds create certification barriers that compound over time, locking out suppliers lacking reformulation infrastructure.
For Market Incumbents: Build specification-lock moats by deepening captive laboratory capabilities that architects cannot replicate without capital intensity. Saint-Gobain's integrated building physics infrastructure exemplifies this defensive positioning. Acquire demountable installation profile patents ahead of EPBD renovation mandate expansion. Bio-based feedstock supply agreements represent the critical lever for margin defense as petroleum-based compound pathways face elimination.
For New Entrants and Emerging Players: Establish a beachhead in acoustic mat retrofit applications for heritage building conversions where height constraints eliminate incumbent assembly systems. French and British urban renovation corridors offer the most penetrable geography due to material availability constraints stranding legacy supplier inventories. Partner with parametric modeling software platforms to bypass traditional specification gatekeepers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among laboratory-anchored specification platforms with software licensing capabilities. Long-term viability across the analysis window favors suppliers with backward integration into low-carbon feedstock sourcing. Target acquisition archetypes include mid-tier compounders with stranded legacy formulations but established contractor relationships. Watch for inflection when ECHA accelerates phthalate substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstock Supply | Secures material eligibility under EU Green Deal carbon benchmarks for German residential pipelines. |
| Platform Licensing for Acoustic Modeling Software | Anchors architect specification relationships through recurring revenue capture in Rotterdam and Copenhagen. |
| Demountable Installation Profile Development | Aligns product portfolios with EPBD renovation mandates redirecting public procurement. |
| Laboratory Infrastructure Expansion | Replicates Saint-Gobain's building physics capabilities to gatekeep commercial fit-out specifications. |
| Strategic Partnership with Architect Software Platforms | Bypasses traditional product catalogs as parametric tools displace catalog-based specification. |
Research Methodology
Desk research of ECHA regulatory filings, EU Construction Products Regulation documentation, and national building code repositories preceded structured interviews with polymer compound R&D directors, architect specification leads, multifamily developer procurement officers, and acoustic testing laboratory managers. Secondary validation drew from customs trade data for acoustic material imports, SEC 10-K disclosures from listed building material conglomerates, and national renovation permit databases. Bottom-up demand modeling triangulated against top-down construction spending forecasts.
Assumptions held fixed include ECHA REACH substance restriction timelines and EU Green Deal embodied carbon benchmarking implementation. Variables included EPBD renovation mandate acceleration scenarios and bio-based feedstock cost curves across the projection horizon. Segmentation dimensions encompassed product type, installation method, material chemistry, and application sector with regional regulatory cluster overlays. CAGRs derived from regression analysis against historical construction permit volumes and acoustic upgrade retrofit rates. Industry-specific inputs included sound transmission class certification timelines and floating floor assembly adoption curves.
Sensitivities concentrate around ECHA regulatory acceleration, bio-based polymer feedstock cost volatility, and EPBD mandate expansion timing. Forecasts reflect documented assumptions on substitution investment rates and specification behavior migration toward software platforms. Macroeconomic construction cycle downturn, regulatory timeline compression, or breakthrough alternative acoustic technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market