
 United Arab Emirates Diagnostic Imaging Equipment Market | 2026-2036
United Arab Emirates Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Diagnostic Imaging Equipment Market Analytics
Buyer consolidation among hospital networks in Dubai and Abu Dhabi is repositioning procurement leverage toward integrated health systems. GE Healthcare anchors its presence through service infrastructure spanning the Emirates. Siemens Healthineers differentiates via magnetic resonance imaging specialization for neurology applications. Fujifilm Holdings Corporation competes on digital radiography portfolios tailored to outpatient facility workflows.
Diagnostic imaging equipment encompasses systems that generate visual representations of internal body structures for clinical diagnosis, utilizing electromagnetic radiation, magnetic fields, or acoustic energy with spatial resolution thresholds measured in millimeters. These technologies enable non-invasive detection of pathological conditions across tissue types, supporting treatment planning and intervention guidance. Computed tomography systems lead current revenue pools due to trauma and oncology screening volumes, while 3D imaging technology captures the fastest expansion trajectory driven by surgical planning adoption. Ultrasound product types retain strong positions in cardiology and obstetrics applications where real-time functional assessment proves critical.
MOHAP enforces equipment licensing standards that mandate radiation safety protocols and image quality benchmarks for all deployed modalities. The UAE's alignment with IEC technical standards for electromagnetic compatibility shapes import requirements and manufacturer compliance investments. FDA-cleared systems receive accelerated recognition under bilateral regulatory cooperation frameworks. Stakeholders must monitor evolving AI-enabled diagnostic software classification rules that will determine whether algorithmic enhancements trigger separate approval pathways from base hardware platforms.
Market Dynamics
Hospital network consolidation across Dubai and Abu Dhabi is concentrating procurement leverage into fewer decision-making centers, fundamentally altering how equipment manufacturers negotiate contracts and deploy service infrastructure across the Emirates.
Growth Catalysts
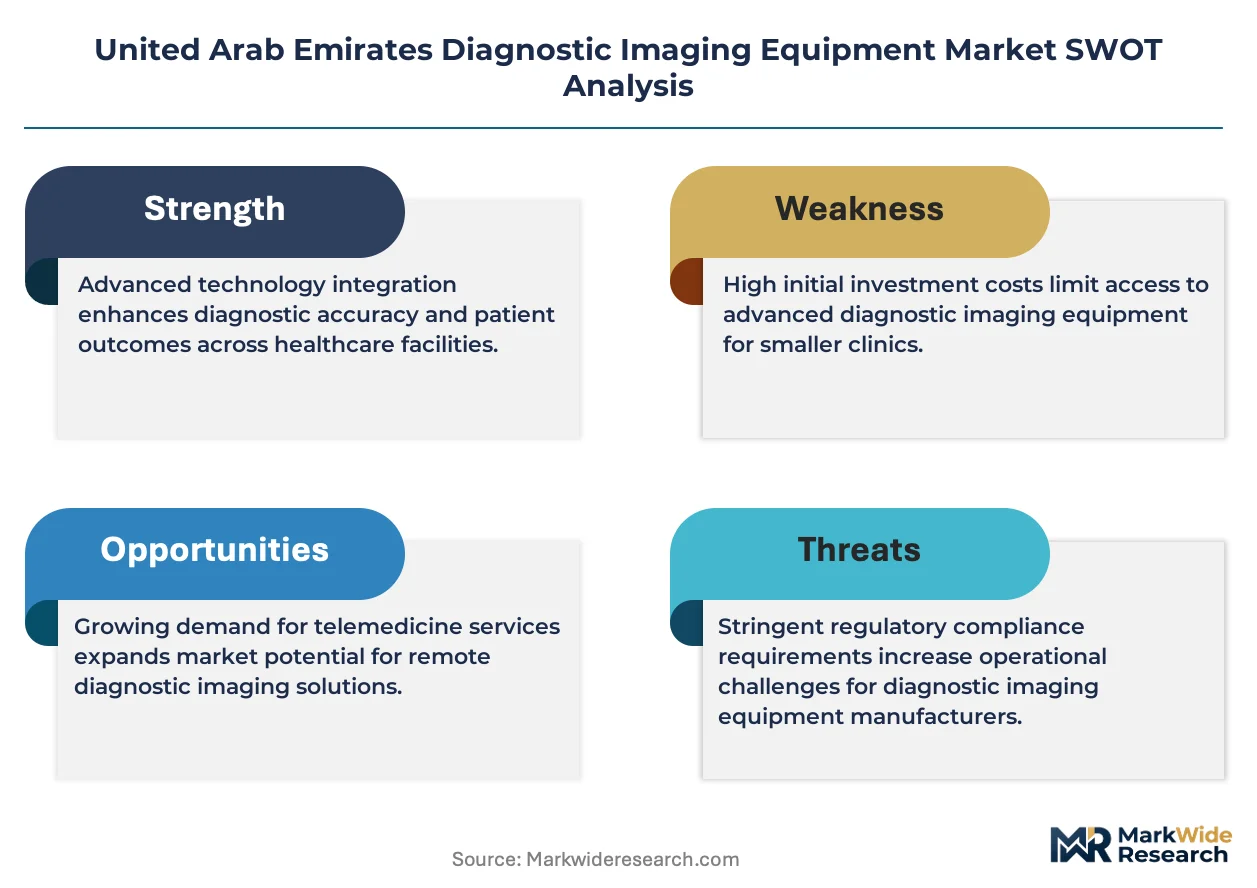
- MOHAP Licensing Mandates:Mandatory radiation safety protocols and image quality benchmarks are accelerating replacement cycles for aging modalities in tertiary care centers.
- Medical Tourism Corridors:Dubai Healthcare City and Abu Dhabi's Cleveland Clinic Abu Dhabi are driving demand for premium imaging capacity to serve international patient flows.
- AI-Enabled Reconstruction:Deep learning algorithms for CT and MRI noise reduction are shortening scan times and expanding throughput capacity at major hospital networks.
Market Restraints
- Import Dependency:Heavy reliance on European and North American OEMs for high-field MRI and PET-CT systems creates currency exposure and extended lead times.
- Radiologist Workforce Constraints:Limited domestic training pipeline for specialized imaging interpretation creates bottlenecks in equipment utilization rates.
- Capital Intensity Thresholds:Cyclotron installation requirements for PET radiotracer production restrict molecular imaging adoption to only the largest health systems.
Strategic Opportunities
- Sharjah and Northern Emirates Penetration:Secondary cities remain underserved for advanced modalities, presenting first-mover positioning for outpatient imaging chains.
- Point-of-Care Ultrasound Expansion:Emergency departments and intensive care units are adopting handheld systems for bedside hemodynamic assessment.
- Teleradiology Infrastructure:Federal investments in health information exchange platforms enable centralized interpretation services across dispersed facility networks.
Industry Challenges
- Integration Complexity:Legacy PACS architectures in established hospitals resist seamless incorporation of AI-enabled diagnostic overlays without middleware investments.
- Service Engineer Scarcity:Specialized training for superconducting magnet maintenance and linear accelerator repair outpaces local technical education capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Diagnostic Imaging Equipment Market |
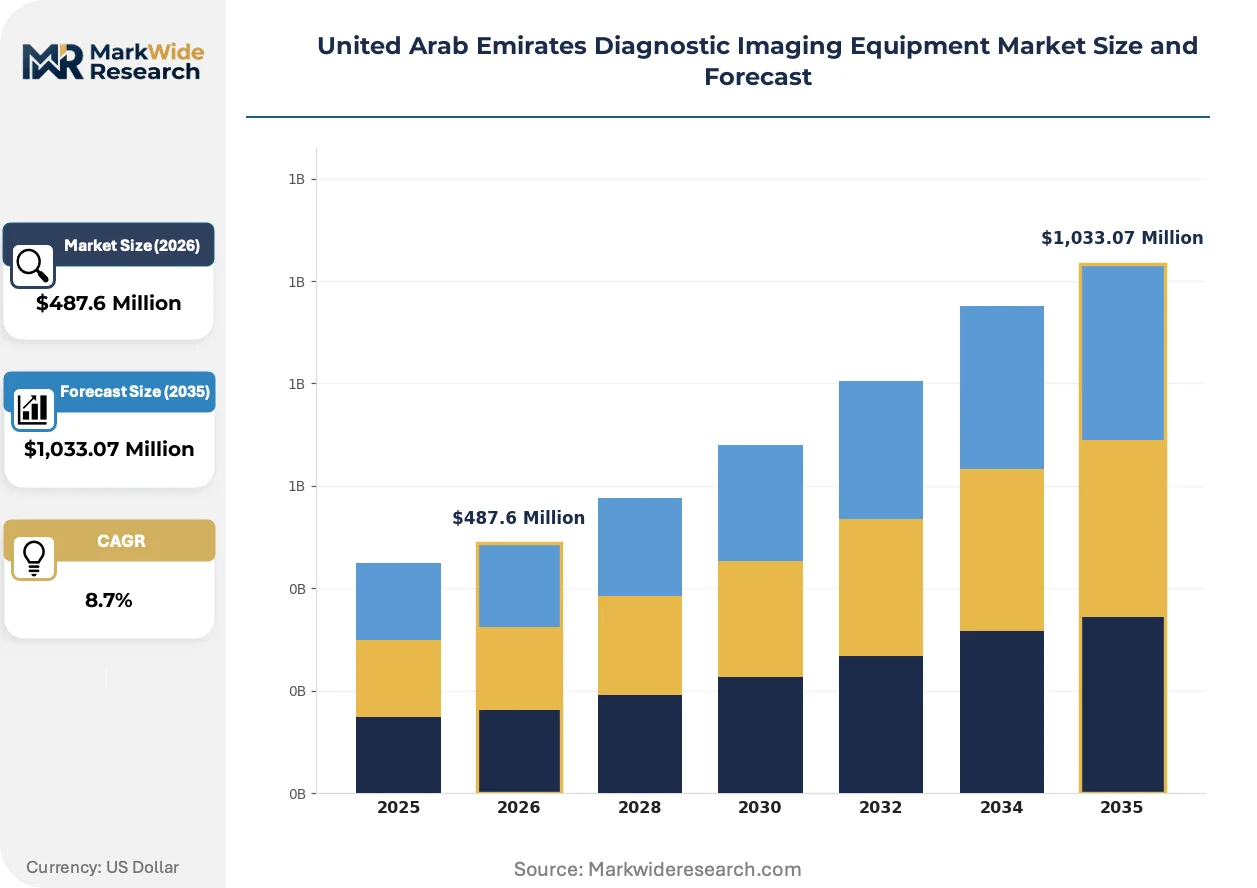
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Resonance Imaging, Computed Tomography, Ultrasound, X-ray Technology: Digital Radiography, Computed Radiography, Fluoroscopy, 3D Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Facilities Application: Oncology, Neurology, Cardiology, Orthopedics |
| Companies Covered | Hologic Inc, Canon Medical Systems Corporation, GE Healthcare, Carestream Health, Fujifilm Holdings Corporation, Siemens Healthineers AG, Esaote SpA, Toshiba Corporation, Koninklijke Philips N V, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Diagnostic Imaging Equipment Market Evolving Landscape
Digital transformation of radiology workflows is compressing the gap between image acquisition and diagnostic reporting, with artificial intelligence and cloud infrastructure converging to restructure how imaging services are delivered across the Emirates.
Photon-counting detector technology is modularizing CT system architecture by replacing energy-integrating detectors with semiconductor-based direct conversion layers. Tertiary hospitals in Dubai are piloting these systems for cardiac and pulmonary imaging protocols. The shift is modularizing hardware upgrade pathways, allowing detector subsystem replacement without full gantry replacement.
MOHAP's alignment with IEC 60601 electromagnetic compatibility standards is harmonizing import requirements with European technical benchmarks. Equipment vendors must demonstrate compliance with unified safety protocols before market entry. Radiology departments are responding by consolidating procurement specifications to match these transnational standards.
Consolidated purchasing through integrated health systems is displacing individual hospital negotiations across Abu Dhabi's SEHA network and Dubai's DHA-affiliated facilities. Group procurement offices now dictate service level agreements and training commitments. This concentration is most visible in Dubai, where three health systems control the majority of advanced modality acquisitions.
United Arab Emirates Diagnostic Imaging Equipment Market Segmentation
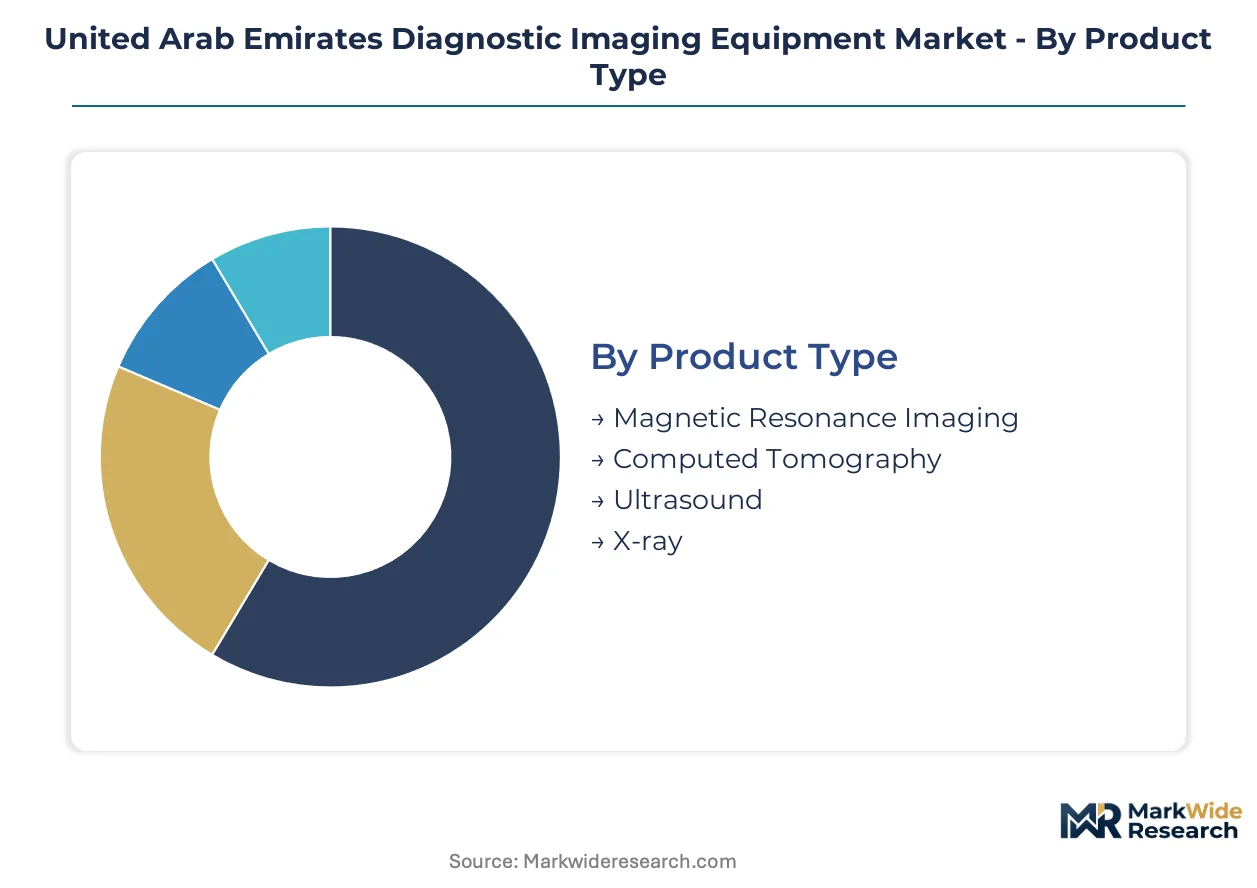
Segmentation of the United Arab Emirates diagnostic imaging equipment market reveals how capital allocation, clinical workflow requirements, and regulatory compliance intersect to shape procurement patterns across Dubai and Abu Dhabi's consolidated health networks. Understanding these divisions enables equipment vendors to align product portfolios with the specific technical and economic constraints governing each customer category.
Product Type:
Capital intensity varies dramatically across modalities, with superconducting MRI systems requiring 5-10 times the upfront investment of digital X-ray platforms and carrying substantial ongoing helium and service contract obligations.
- Computed Tomography:Multi-slice CT systems with 64- to 320-detector configurations generate cross-sectional anatomical datasets using rotating X-ray sources and detector arrays. Demand concentrates in tertiary trauma centers across Dubai's Rashid Hospital and Abu Dhabi's Sheikh Khalifa Medical City, driven by emergency department throughput requirements and MOHAP-mandated radiation dose monitoring protocols.
- Magnetic Resonance Imaging:Superconducting systems utilizing 1.5T and 3.0T field strengths produce high-contrast soft tissue visualization through radiofrequency pulse sequences and gradient magnetic field manipulation. Sheikh Shakhbout Medical City and Cleveland Clinic Abu Dhabi anchor demand for advanced neurology and cardiac MRI protocols, constrained by specialized shielding requirements and cryogenic infrastructure investments.
- Ultrasound:Piezoelectric transducer systems operating across 2-18 MHz frequency ranges enable real-time anatomical and hemodynamic assessment without ionizing radiation exposure.
- X-ray:Fixed and mobile radiographic systems utilizing tungsten anode X-ray tubes remain the most deployed modality across outpatient networks and primary care facilities.
Computed Tomography absorbs the bulk of installed capacity; 3D Imaging-enabled CT configurations are expanding most quickly across surgical planning departments.
Technology:
Technology segmentation tracks the digitization depth of image capture and reconstruction workflows, distinguishing legacy analog-to-digital conversion from direct digital detection and volumetric rendering capabilities.
- 3D Imaging:Volumetric reconstruction algorithms generate isotropic datasets from multi-detector CT and digital tomosynthesis acquisitions, enabling multiplanar reformatting and virtual endoscopic navigation. Dubai Healthcare City surgical centers and Abu Dhabi's SEHA network orthopedic departments drive adoption for preoperative planning and implant templating, supported by MOHAP's quality benchmarking for complex intervention outcomes.
- Digital Radiography:Flat-panel detector systems with cesium iodide or gadolinium oxysulfide scintillation layers convert X-ray photons directly to digital signals without intermediate cassette processing. Outpatient imaging chains across Sharjah and the Northern Emirates prioritize these systems for throughput efficiency and reduced operational footprint.
- Computed Radiography:Photostimulable phosphor plate systems requiring mechanical scanning and laser stimulation persist in cost-sensitive facility upgrades.
- Fluoroscopy:Continuous X-ray image acquisition systems with pulsed exposure modes support interventional radiology and gastrointestinal contrast studies.
Digital Radiography dominates replacement cycles across established hospital networks; 3D Imaging is climbing the fastest among newly commissioned tertiary facilities.
End User:
End user segmentation reflects the divergence between high-acuity inpatient settings requiring 24/7 modality availability and distributed outpatient networks prioritizing accessibility and rapid turnaround.
- Hospitals:Acute care facilities with emergency departments, surgical suites, and intensive care units require comprehensive modality portfolios with redundant capacity and immediate availability. Dubai's DHA-affiliated hospitals and Abu Dhabi's SEHA network concentrate procurement leverage through centralized group purchasing offices, mandating multi-year service agreements and clinical training commitments from vendors.
- Diagnostic Centers:Dedicated imaging facilities without inpatient beds focus on scheduled outpatient procedures and elective screening programs. Medical tourism corridors around Dubai Healthcare City drive premium positioning for these centers, constrained by MOHAP licensing requirements for radiation safety officers and medical physicist staffing.
- Outpatient Facilities:Primary care clinics and specialty practices embed point-of-care ultrasound and basic radiography for immediate clinical decision-making.
- Research Institutions:Academic medical centers and clinical trial sites deploy specialized high-field MRI and hybrid PET-MR systems for experimental protocols.
Hospitals command the largest share of capital equipment budgets; Diagnostic Centers are gaining share fastest as medical tourism infrastructure expands.
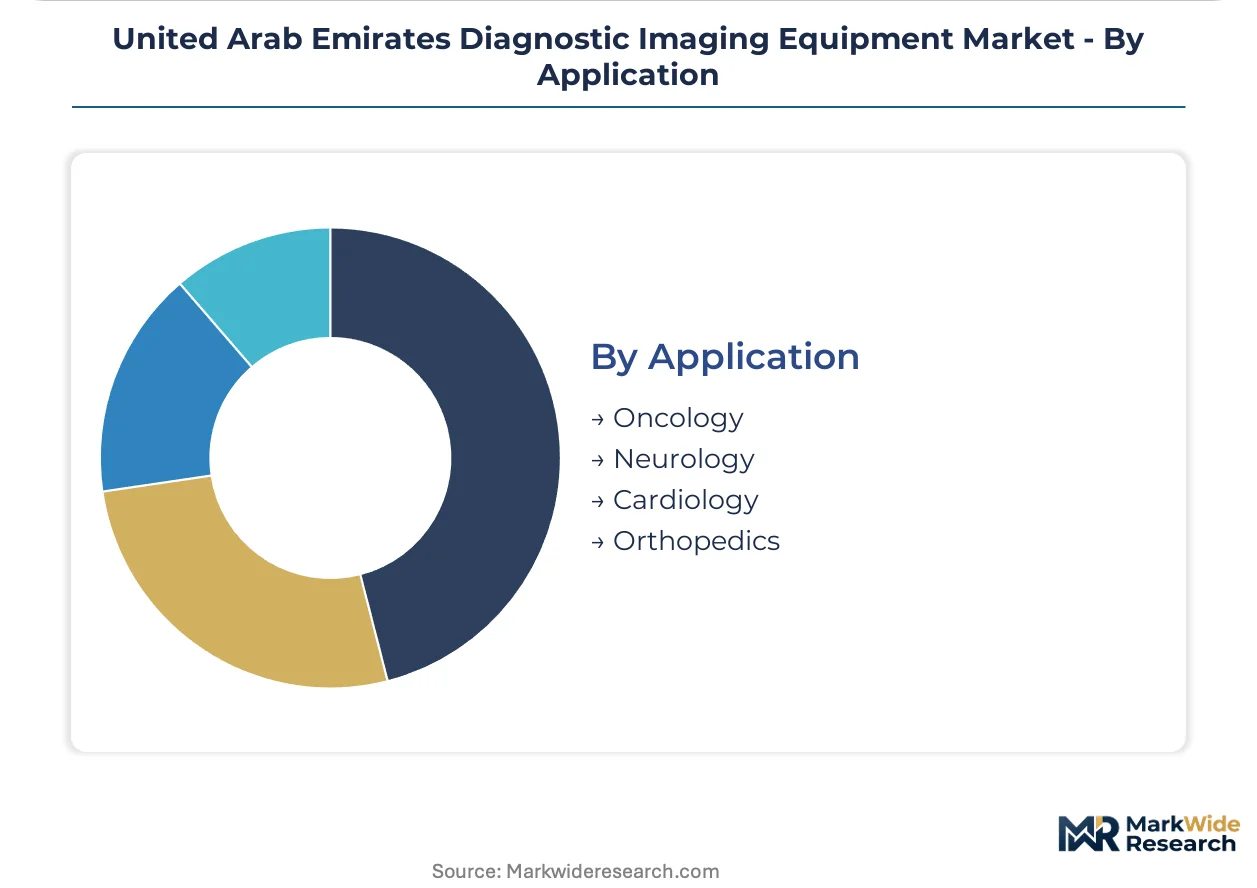
Application:
Application segmentation aligns modality specifications with anatomical targets and disease-state prevalence patterns across the Emirates' patient population.
- Oncology:Staging and treatment response monitoring drives demand for PET-CT and multiparametric MRI systems with dedicated radiation oncology integration. Tawam Hospital's oncology center in Al Ain and Dubai Hospital's cancer institute anchor demand, constrained by cyclotron availability for fluorodeoxyglucose radiotracer production and nuclear medicine specialist workforce limitations.
- Cardiology:Coronary CT angiography and cardiac MRI stress testing require ECG-gated acquisition protocols and specialized post-processing software. Cleveland Clinic Abu Dhabi's cardiovascular institute and Dubai's American Hospital drive adoption for non-invasive coronary assessment, supported by MOHAP's accreditation standards for cardiac imaging centers.
- Neurology:Functional MRI and diffusion tensor imaging for stroke and neuro-oncology applications demand advanced gradient performance and neurovascular coil arrays.
- Orthopedics:Weight-bearing CT and musculoskeletal MRI protocols support sports medicine and joint replacement programs across the Emirates.
Oncology absorbs the greatest modality investment per procedure; Cardiology is expanding most quickly as non-invasive coronary assessment protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Dubai and Abu Dhabi's tertiary care corridors, where medical tourism infrastructure and consolidated hospital networks drive procurement volumes for advanced imaging modalities.
Dubai
Dubai Healthcare City and Rashid Hospital anchor demand for 3D-enabled CT and cardiac MRI systems serving international patient flows. MOHAP's radiation safety protocols mandate dose monitoring infrastructure for all deployed modalities. Three integrated health systems control the majority of advanced equipment acquisitions through centralized group purchasing offices.
Abu Dhabi
Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City drive premium imaging capacity for neurology and cardiovascular applications. SEHA's consolidated procurement leverage dictates multi-year service agreements and clinical training commitments from vendors. Sheikh Shakhbout Medical City anchors demand for 3.0T MRI systems requiring specialized shielding investments.
Sharjah
Secondary care facilities in Sharjah remain underserved for advanced modalities, presenting positioning opportunities for outpatient imaging chains. MOHAP licensing requirements for radiation safety officers constrain rapid facility expansion. Medical imaging centers concentrate along the Dubai-Sharjah corridor to capture overflow demand.
Northern Emirates
Ras Al Khaimah, Fujairah, and Ajman lack dedicated PET-CT and high-field MRI capacity, forcing patient transfers to Dubai and Abu Dhabi. Federal health information exchange investments aim to enable teleradiology coverage across dispersed networks. Private imaging operators are piloting mobile CT units for rural access.
Al Ain
Tawam Hospital's oncology center anchors molecular imaging demand constrained by cyclotron availability for radiotracer production. The city's geographic isolation from Dubai and Abu Dhabi creates distinct procurement patterns for equipment redundancy. SEHA network integration is standardizing imaging protocols across Al Ain's hospital facilities.
United Arab Emirates Diagnostic Imaging Equipment Market Competitive Landscape
North American and European producers anchor the premium systems tier; Japanese and Korean specialists hold positions in digital radiography and ultrasound segments. The vendor structure concentrates around integrated health system procurement offices in Dubai and Abu Dhabi, with service infrastructure and training commitments functioning as primary differentiation vectors. Three strategic archetypes dominate: full-modality portfolios with captive service networks, specialized MRI or CT technology developers, and digital X-ray platform competitors. Equipment manufacturers pursue multi-year managed service contracts and detector subsystem upgrade pathways as dominant competitive moves.
Within the premium-tier vector, GE Healthcare and Siemens Healthineers exemplify full-modality competitors with established UAE service infrastructure. Fujifilm Holdings Corporation occupies a position among digital radiography specialists targeting outpatient workflow efficiency. These three anchors represent distinct strategic postures: comprehensive modality coverage with integrated service, advanced MRI specialization for neurology applications, and cost-optimized digital X-ray platforms for high-throughput screening environments.
| Leading Market Players |
|---|
| Hologic Inc |
| Canon Medical Systems Corporation |
| GE Healthcare |
| Carestream Health |
| Fujifilm Holdings Corporation |
| Siemens Healthineers AG |
| Esaote SpA |
| Toshiba Corporation |
| Koninklijke Philips N V |
| Others |
Value Network & Pricing Analysis
Photon-counting detector modularization is simultaneously collapsing CT upgrade economics and concentrating procurement leverage among Dubai and Abu Dhabi's integrated health systems, compressing margins on legacy energy-integrating platforms while elevating premium-tier pricing power for semiconductor-based direct conversion architectures.
Pricing Analysis
Volume concentrates in mid-tier 64-128 slice CT configurations where SEHA and DHA group purchasing offices extract standardized service commitments, while margin pools shift toward 3.0T MRI and PET-CT systems where Cleveland Clinic Abu Dhabi and Sheikh Shakhbout Medical City absorb premium positioning. Price differentiation hinges on MOHAP licensing tier and bundled training depth, with radiation safety officer certification requirements adding compliance premiums. Cost compression in digital radiography intensifies as Fujifilm and Carestream Health compete on outpatient throughput metrics. Diagnostic centers in Dubai Healthcare City demonstrate lowest price sensitivity; primary care networks in Sharjah and Northern Emirates drive hardest bargain on mobile X-ray platforms.
Supply Chain Analysis
Refurbishment flows for superconducting magnets and CT gantries create secondary equipment channels serving Northern Emirates facilities, with remanufactured systems from European and North American OEMs circulating through independent service organizations. Supply concentrates in Germany, Japan, and the United States for high-field MRI superconducting wire and PET detector crystals. Raw material dependencies span helium for magnet cooling, lutetium-based scintillators for PET-CT, and rare-earth elements for gradient coils. Single-source vulnerability persists for 3.0T magnet production where only two global facilities maintain qualified manufacturing. Distribution runs through SEHA and DHA centralized procurement offices with direct-to-hospital logistics for installation-critical modalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE diagnostic imaging market sits in a technology-transition phase where AI-enabled reconstruction algorithms are displacing legacy iterative reconstruction workflows, compressing scan times and reshaping throughput-based procurement calculations across Dubai and Abu Dhabi's tertiary networks.
For Market Incumbents: Anchor service infrastructure density as the primary defensive moat against emerging teleradiology platforms and AI-native diagnostic software entrants. Deepen captive supply of helium reclamation and cryogenic maintenance capabilities to lock in MRI service contract renewals. Counter GE Healthcare and Siemens Healthineers' installed base advantages by accelerating detector subsystem upgrade pathways that extend CT system lifecycles without full gantry replacement.
For New Entrants and Emerging Players: Capture point-of-care ultrasound white space in emergency departments and intensive care units where handheld systems enable bedside hemodynamic assessment without radiologist workflow integration. Target Sharjah and Northern Emirates outpatient imaging chains as the most penetrable geography, constrained only by MOHAP radiation safety officer staffing requirements. Lead with teleradiology infrastructure partnerships that federal health information exchange investments are priming for centralized interpretation services.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap imaging service specialists with captive maintenance capabilities and SEHA or DHA contract relationships. Long-term viability favors operators with backward integration into radiotracer production or AI-enabled diagnostic software stacks. Monitor MOHAP's evolving classification rules for algorithmic enhancements as the critical inflection signal determining whether AI overlays trigger separate approval pathways from base hardware platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Reconstruction Partnership | Deep learning algorithms for CT and MRI noise reduction shorten scan times at Rashid Hospital and Cleveland Clinic Abu Dhabi. |
| Detector Subsystem Upgrade Pathway | Photon-counting detector replacement extends CT lifecycle without full gantry replacement across SEHA network facilities. |
| Teleradiology Infrastructure Investment | Federal health information exchange platforms enable centralized interpretation services for Northern Emirates dispersed networks. |
| Helium Reclamation Captive Supply | In-house superconducting magnet cooling recovery secures MRI service contract renewals against independent service organizations. |
| MOHAP Licensing Pre-Certification | Early radiation safety protocol alignment accelerates market entry for AI-enabled diagnostic software classifications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across hospital procurement committees, biomedical engineering directors, GPO contracts managers, and radiology department heads. Secondary sources encompassed MOHAP licensing databases, SEHA and DHA procurement disclosures, IEC 60601 compliance registries, and import tariff schedules. Bottom-up modality installation tracking and top-down health system capital expenditure analysis were triangulated against tertiary care capacity expansion announcements.
Granularity-level modeling operated at the intersection of product type, technology tier, end-user facility class, and clinical application, with geographic disaggregation across Dubai, Abu Dhabi, Sharjah, Northern Emirates, and Al Ain. CAGRs were derived from installed base evolution and replacement cycle compression under MOHAP mandates. Forecast inputs incorporated medical tourism patient flow projections and AI-enabled reconstruction adoption curves across surgical planning departments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cyclotron availability for PET radiotracer production and radiologist workforce pipeline expansion. Forecasts reflect documented assumptions regarding SEHA and DHA procurement consolidation trajectories and IEC alignment timelines. Practitioners should monitor MOHAP's AI-enabled diagnostic software classification rules and federal teleradiology infrastructure deployment milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Mexico Digital Radiology Market