
 Global Very Narrow Aisle Trucks (VNA Truck) Market | 2026-2036
Global Very Narrow Aisle Trucks (VNA Truck) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Very Narrow Aisle Trucks (VNA Truck) Market Outlook
Dealer and direct-service networks is reconfiguring how VNA trucks reach end users in mature markets. Toyota Material Handling leverages its captive distribution to sustain premium positioning across North American warehouse accounts. Jungheinrich anchors European demand through specialized configurations for high-bay cold storage facilities. Anhui Heli competes aggressively on manufacturing scale in Asian logistics corridors.
Very Narrow Aisle Trucks are purpose-built material handling vehicles designed to operate in aisles measuring 1.5 to 1.8 meters, utilizing articulated steering or turret heads to retrieve pallets at heights exceeding 12 meters in dense racking environments. Electric VNA trucks dominate current procurement flows as lithium-ion battery packs displace lead-acid systems across warehouse fleets. Automated VNA trucks represent the fastest-expanding product category, though manual and semi-automated variants still occupy the largest installed base in cost-sensitive retail distribution. Order picking and storage applications together capture the majority of unit demand, with margin pools concentrating in fuel cell and advanced AC motor configurations for multi-shift operations.
FCC equipment authorization requirements shape radio-frequency control systems in US-deployed units, while CE marking and the EU Machinery Directive govern structural safety and electromagnetic compatibility for European sales. China's GB standards and MIIT equipment certifications create distinct compliance thresholds for imported VNA trucks entering domestic logistics parks. Stakeholders must monitor divergence between regional battery certification regimes and automation safety protocols as procurement specifications harden.
Market Dynamics
Lithium-ion battery chemistry is compressing fleet replacement cycles across warehouse operations, forcing capital allocation toward electrified narrow-aisle configurations and away from internal combustion alternatives.
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics operators in Germany and the United States are retrofitting existing warehouses with 15-meter racking systems that demand VNA truck penetration.
- EU Machinery Directive compliance:Automated safety protocols under CE marking are accelerating replacement of pre-2020 manual fleets in European cold storage networks.
- Lithium-ion energy density:Battery pack improvements are enabling continuous multi-shift operation without battery swap infrastructure, reshaping total cost of ownership calculations.
Market Restraints
- Cobalt and lithium price volatility:Raw material input swings are compressing margin pools for battery pack assembly and extending OEM quoting timelines.
- Supply concentration in Chinese cell manufacturing:Cylindrical cell production clusters in Jiangsu and Fujian provinces create geographic single-point vulnerability for non-Asian fleet operators.
- Lead-acid residual value collapse:Secondary market pricing for legacy battery systems is rendering trade-in economics unfavorable for small fleet operators.
Strategic Opportunities
- Indian cold chain underpenetration:Temperature-controlled warehousing in Maharashtra and Gujarat remains below 15% automated material handling penetration, creating white space for VNA truck deployment.
- Fuel cell hybrid configurations:Hydrogen fuel cell range extenders paired with lithium-ion buffers are emerging as a configuration for 24-hour pharmaceutical distribution centers.
- US Inflation Reduction Act credits:Clean commercial vehicle tax incentives are narrowing the first-cost gap between battery-electric and internal combustion VNA trucks for qualifying fleet operators.
Industry Challenges
- Automation technician scarcity:Maintenance networks lack sufficient capacity for laser guidance calibration and sensor fusion diagnostics on automated VNA units.
- Legacy WMS integration friction:Warehouse management systems deployed before 2018 require middleware development to communicate with automated truck fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Very Narrow Aisle Trucks (VNA Truck) Market |
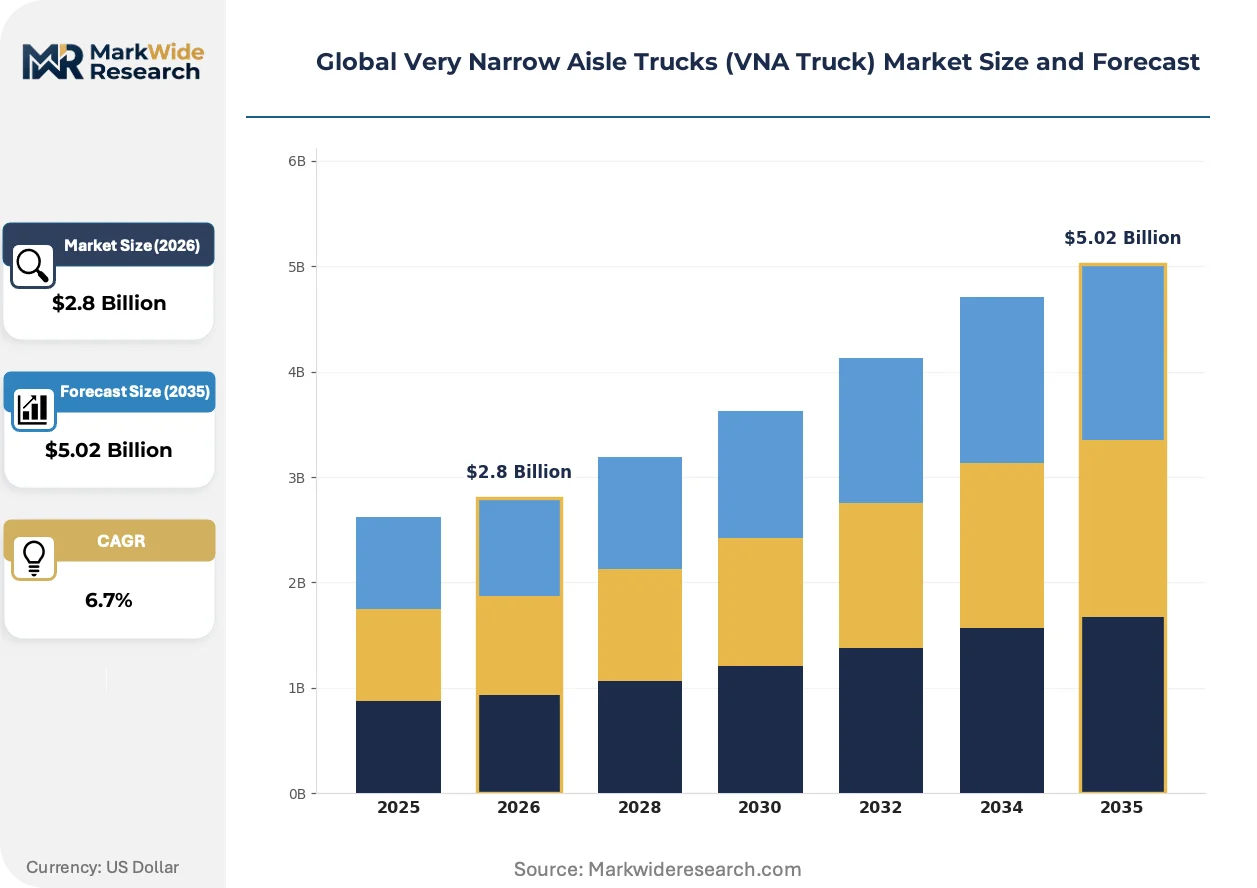
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual VNA Trucks, Electric VNA Trucks, Automated VNA Trucks, Hybrid VNA Trucks End User: Warehouse, Retail, Manufacturing, Logistics Technology: Battery Powered, Fuel Cell, AC Motor, DC Motor Application: Storage, Order Picking, Inventory Management, Material Handling |
| Companies Covered | Mitsubishi Logisnext, Hyundai Construction Equipment, Toyota Material Handling, Crown Equipment, Manitou Group, KION Group, Anhui Heli, Raymond Corporation, Jungheinrich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Very Narrow Aisle Trucks (VNA Truck) Market Strategic Shifts
Control system architectures and powertrain configurations are undergoing simultaneous transformation, compressing product lifecycles and fragmenting supplier tiers across the material handling value chain.
Lithium iron phosphate battery packs are rendering obsolete lead-acid systems in high-rotation warehouse environments. Cold storage operators in the Netherlands and Denmark are completing full fleet conversions within 18-month windows. The chemistry shift is compressing maintenance revenue pools for traditional battery service providers while elevating thermal management system requirements.
China's MIIT equipment certification framework is tightening electromagnetic compatibility testing for radio-frequency controlled VNA trucks entering domestic logistics parks. The GB standards revision is extending type-approval timelines by four to six months for European and Japanese OEMs. Domestic manufacturers with pre-certified control architectures are capturing share in tier-one Chinese e-commerce fulfillment centers.
Third-party logistics providers are consolidating fleet procurement decisions at regional headquarters rather than warehouse-level managers. The concentration of buying authority is compressing supplier negotiation cycles and elevating telematics integration requirements as table stakes. German automotive parts distributors and US pharmaceutical wholesalers are exhibiting the most pronounced centralization patterns.
Global Very Narrow Aisle Trucks (VNA Truck) Market Segmentation
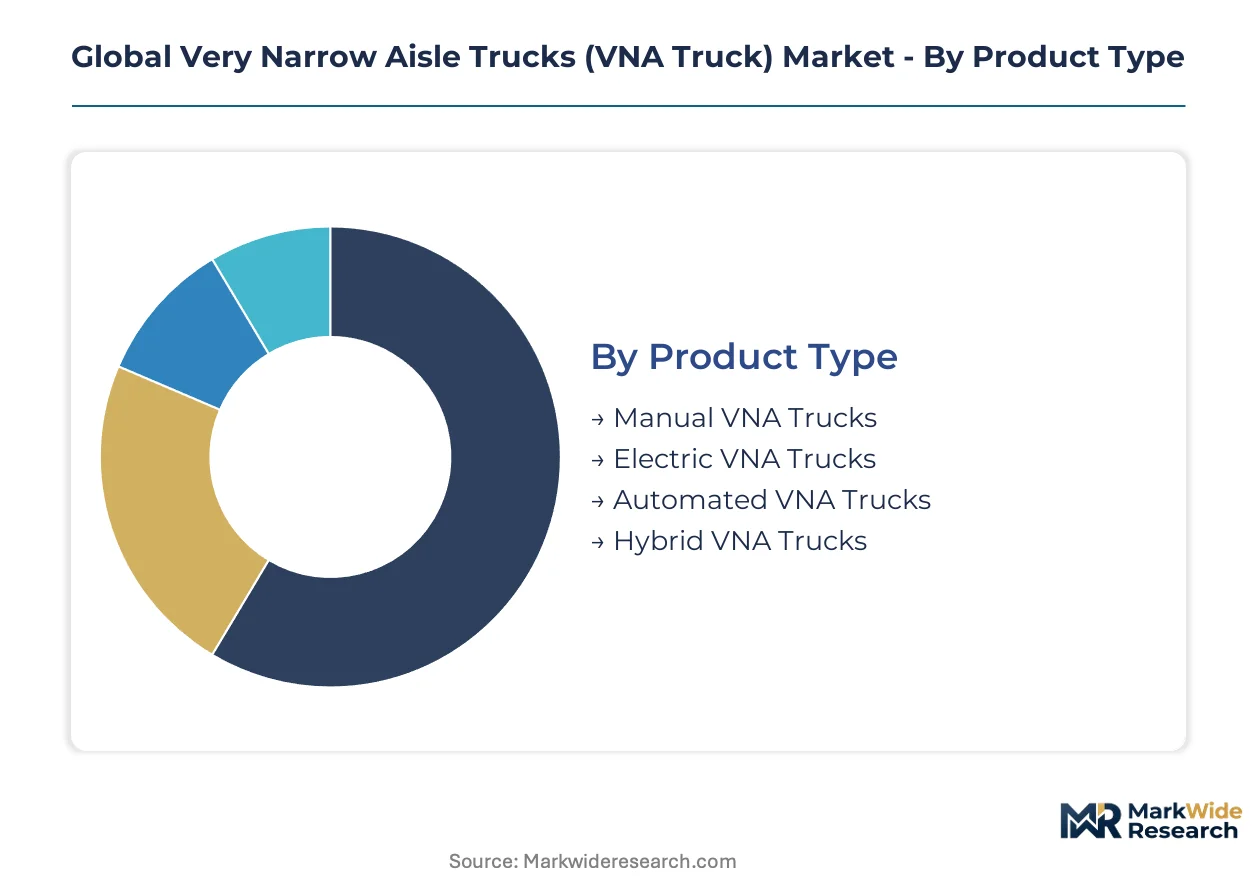
VNA truck procurement splits across four structural dimensions that determine service intensity, technology investment, and fleet replacement cadence. Understanding these segment boundaries clarifies where margin pools concentrate and where standardization pressures erode pricing power.
Product Type:
After-sales-service intensity varies dramatically across powertrain and automation configurations, with automated units demanding specialized technician networks while manual variants rely on conventional maintenance.
- Manual VNA Trucks:Operator-controlled steering and lift mechanisms dominate legacy installed bases in cost-sensitive retail distribution. Demand concentrates in Indian and Southeast Asian logistics corridors where labor arbitrage sustains lower automation penetration and capital constraints delay fleet electrification.
- Electric VNA Trucks:Battery-electric powertrains with lithium-ion or lead-acid chemistry now constitute the primary procurement flow for warehouse fleet replacements. German and US third-party logistics operators are completing 18-month conversion windows as total cost of ownership calculations favor electrification over internal combustion alternatives.
- Automated VNA Trucks:Laser-guided or vision-based navigation systems enable unmanned operation in high-density racking above 12 meters. Momentum concentrates in Dutch and Danish cold storage networks where labor scarcity and precision requirements justify premium automation investments.
- Hybrid VNA Trucks:Dual-power configurations combining battery storage with fuel cell range extension serve 24-hour pharmaceutical distribution centers. Deployment remains concentrated in Japanese and South Korean facilities where hydrogen infrastructure investment precedes broader commercial adoption.
Electric VNA trucks hold the largest share; momentum sits with automated configurations.
End User:
Capital allocation cycles and racking height requirements create distinct demand profiles across facility types, with warehouse operators outspending retail on automation intensity.
- Warehouse:High-bay distribution centers exceeding 15-meter racking drive specification requirements for turret-head and articulated steering configurations. E-commerce fulfillment density in Germany and the United States is retrofitting existing facilities with VNA-compatible storage systems.
- Retail:Back-of-store replenishment and micro-fulfillment centers prioritize compact turning radius over maximum lift height. Demand clusters in urban logistics corridors where floor space constraints favor narrow-aisle density over conventional forklift maneuverability.
- Manufacturing:Just-in-time component delivery to assembly lines requires precise load positioning and integration with production scheduling systems. Automotive parts distributors in Bavaria and Michigan exhibit pronounced centralization of fleet procurement decisions.
- Logistics:Third-party operators serving multiple clients demand telematics integration and rapid reconfiguration between pallet dimensions. Consolidation of buying authority at regional headquarters is compressing supplier negotiation cycles.
Warehouse applications dominate unit volume; logistics providers are climbing fastest on automation penetration.
Technology:
Powertrain selection determines energy infrastructure requirements, maintenance intervals, and regulatory compliance pathways across operating environments.
- Battery Powered:Lithium-ion chemistry with thermal management systems has displaced lead-acid as the default specification for multi-shift operations. Cold storage operators in the Netherlands are completing full fleet conversions within compressed timelines.
- Fuel Cell:Hydrogen proton-exchange-membrane systems paired with lithium-ion buffers enable continuous operation without charging downtime. Pharmaceutical distribution centers in Japan and South Korea are piloting configurations for 24-hour throughput requirements.
- AC Motor:Alternating-current drive systems with regenerative braking reduce energy consumption and maintenance versus DC alternatives. High-rotation warehouse environments in Germany specify AC configurations for three-shift durability.
- DC Motor:Direct-current architectures persist in price-sensitive segments and legacy fleet replacements where controller compatibility constrains upgrade paths. Residual demand concentrates in emerging markets with established DC service infrastructure.
Battery-powered systems command the largest installed base; fuel cell configurations are expanding most quickly in premium cold chain applications.
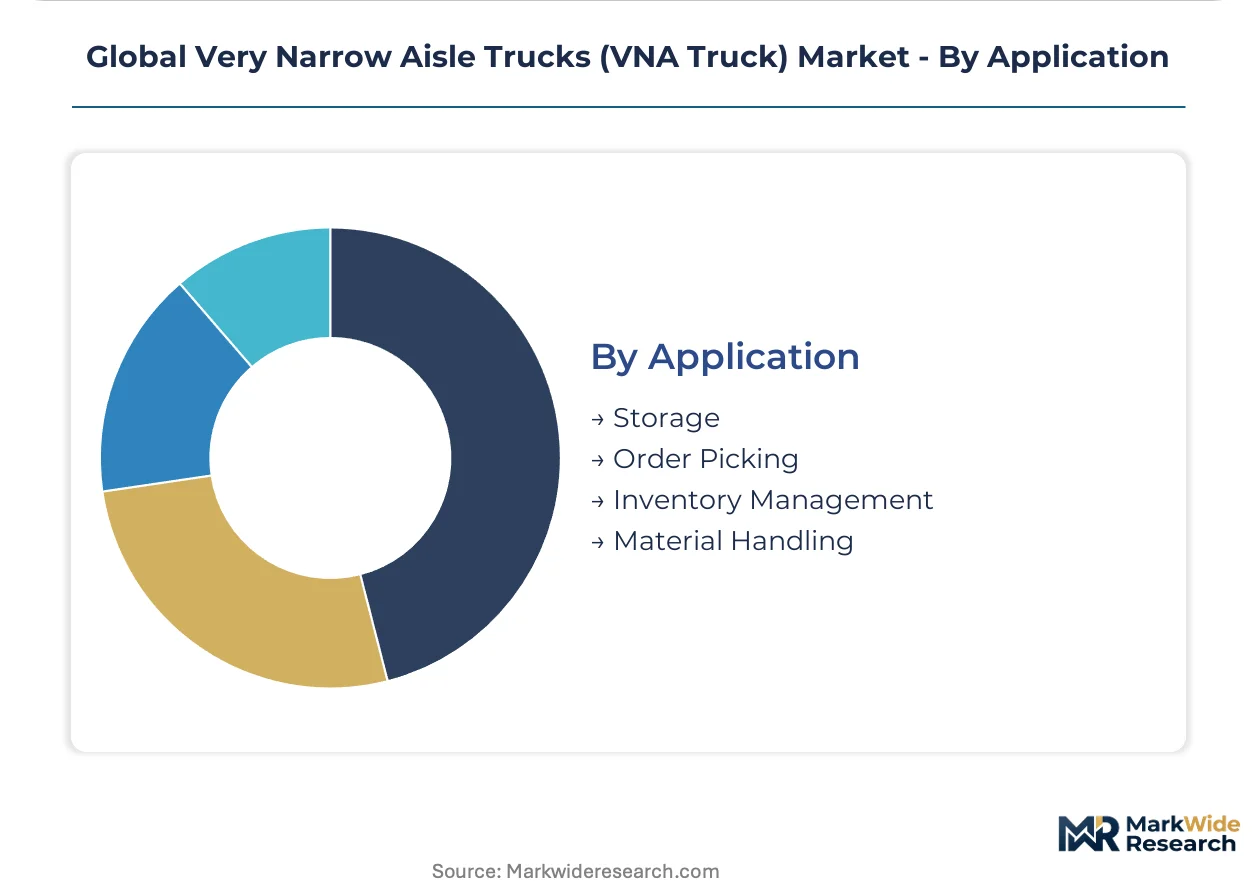
Application:
Task-specific performance requirements shape truck specification, with storage and order picking together capturing the majority of fleet deployment.
- Storage:High-density pallet put-away and retrieval at heights exceeding 12 meters demands precise mast stability and aisle guidance systems. German automotive parts distributors are retrofitting 15-meter racking systems that require specialized VNA penetration.
- Order Picking:Operator-to-goods workflows with elevated platforms and ergonomic controls prioritize cycle speed over maximum lift capacity. E-commerce fulfillment centers in the United States specify configurations optimized for single-item retrieval density.
- Inventory Management:Cycle counting and stock verification applications integrate RFID or vision systems for real-time accuracy. Deployment concentrates in pharmaceutical and electronics verticals where traceability requirements exceed general merchandise standards.
- Material Handling:Cross-docking and staging operations require rapid lateral movement with reduced emphasis on vertical reach. Retail distribution centers utilize these configurations for trailer loading and temporary buffer storage.
Storage applications hold the largest share; order picking is gaining share fastest on e-commerce fulfillment density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container terminals and integrated hinterland rail links underpin Europe's densest warehouse automation corridor, while Shanghai Yangshan Port's smart logistics zone anchors Asia-Pacific VNA truck deployment.
United States
Inland Empire distribution centers serving Los Angeles-Long Beach port complex are retrofitting 15-meter racking systems for e-commerce fulfillment density. OSHA warehouse safety standards and FCC equipment authorization requirements shape radio-frequency control system specifications. Chicago's automotive parts distribution corridor exhibits pronounced centralization of fleet procurement decisions at regional headquarters.
Germany
Bavarian automotive parts distributors and Ruhr Valley cold storage networks drive specification requirements for high-bay turret-head configurations. CE marking under the EU Machinery Directive and REACH chemical compliance accelerate replacement of pre-2020 manual fleets. Hamburg's port-centric logistics parks concentrate automated VNA truck deployment for pharmaceutical distribution.
China
Yangtze River Delta e-commerce fulfillment centers in Jiangsu and Zhejiang provinces demand MIIT-certified radio-frequency control architectures. GB standards revision extends type-approval timelines for imported equipment while elevating electromagnetic compatibility thresholds. Shenzhen's electronics logistics corridor favors domestic manufacturers with pre-certified control systems.
Japan
Kanto region pharmaceutical distribution centers pilot hydrogen fuel cell range extenders paired with lithium-ion buffers for 24-hour throughput. METI clean energy incentives and JIS standards for industrial machinery shape procurement specifications. Osaka-Kobe manufacturing belt integrates just-in-time component delivery with automated VNA truck fleets.
Netherlands
Randstad cold storage operators complete full lithium iron phosphate fleet conversions within compressed 18-month windows. EU Green Deal carbon reduction targets and F-Gas Regulation compliance accelerate electrification timelines. Venlo's logistics corridor serves as the primary entry point for automated material handling equipment entering European distribution networks.
Global Very Narrow Aisle Trucks (VNA Truck) Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying battery packs, mast assemblies, and guidance sensors. The vendor base organizes around three archetypes: full-line material handling conglomerates with captive distribution, regional specialists in high-bay cold storage configurations, and scale-driven Asian manufacturers competing on production volume. Consolidation pressures intensify as telematics integration and automation safety protocols elevate technical barriers. Strategic moves center on backward integration into lithium-ion cell supply and geographic expansion through specialized dealer networks.
Among Japanese industrial conglomerates, Mitsubishi Logisnext and Toyota Material Handling exemplify platform integrators with established captive distribution across North American and European warehouse accounts. KION Group, headquartered in Germany, occupies a position within the European specialist tier for high-bay automation configurations. Chinese manufacturers including Anhui Heli represent scale-driven competitors leveraging manufacturing concentration in Asian logistics corridors.
| Leading Market Players |
|---|
| Mitsubishi Logisnext |
| Hyundai Construction Equipment |
| Toyota Material Handling |
| Crown Equipment |
| Manitou Group |
| KION Group |
| Anhui Heli |
| Raymond Corporation |
| Jungheinrich |
| Others |
Value Chain & Pricing Dynamics
Jiangsu and Fujian provinces host cylindrical lithium-ion cell production clusters that feed battery pack assembly for VNA truck OEMs, concentrating upstream pricing power among Chinese cell manufacturers and compressing margin pools for European and North American fleet operators.
Pricing Analysis
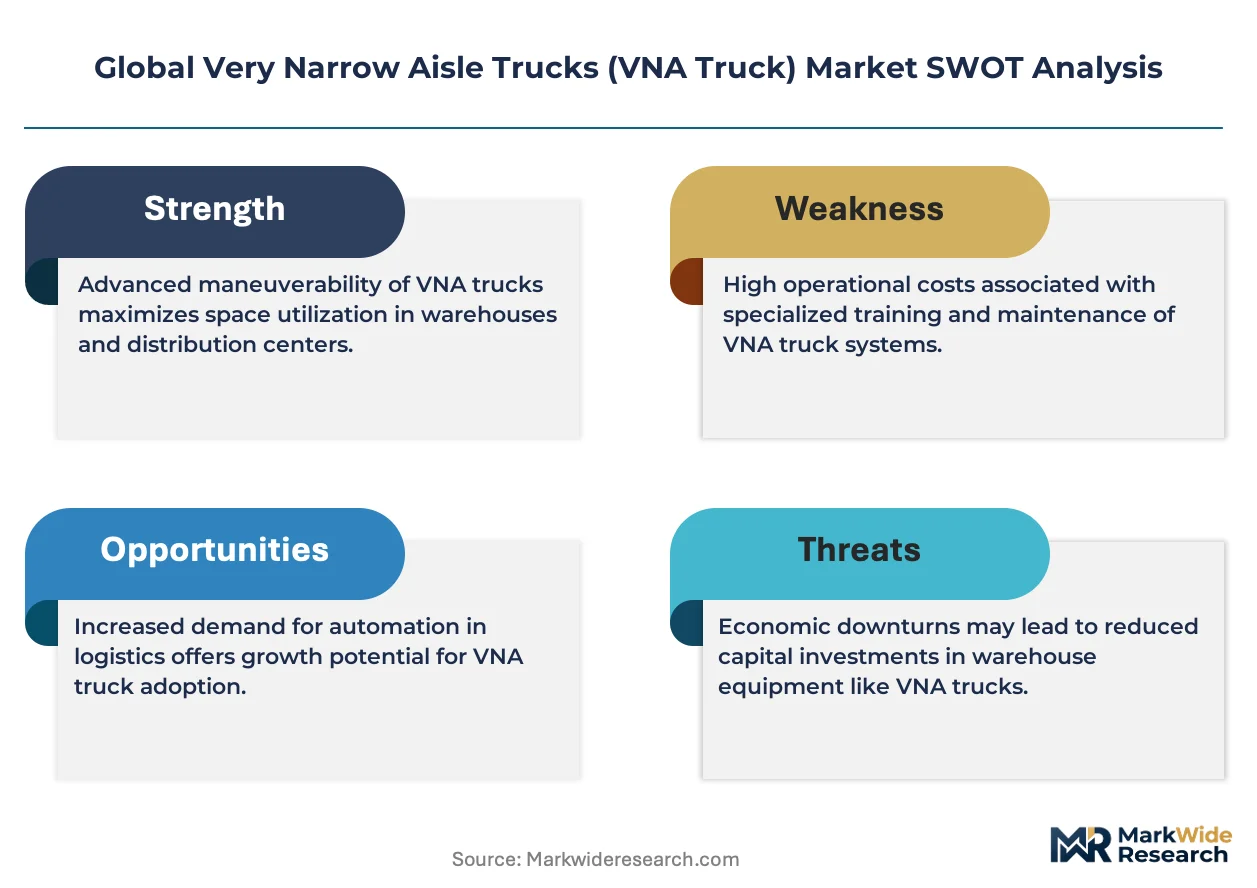
Volume-discount tiering structures separate premium automated configurations with telematics integration from standard electric units and economy manual variants. Price differentiation rests on certification grade—CE-marked and FCC-authorized systems command premiums over uncertified alternatives—and after-sales service bundling. Cost compression in economy tiers is intensifying because lead-acid residual value collapse erodes trade-in economics. Third-party logistics providers with consolidated regional procurement show lowest price sensitivity; small fleet operators in Southeast Asia exhibit highest.
Supply Chain Analysis
Export-control regimes on radio-frequency guidance systems and laser navigation components limit technology flows from Japanese and German specialists to Chinese assembly operations. Geographic supply concentration centers on China for lithium-ion cells, Germany for precision mast assemblies, and Japan for sensor fusion modules. Raw material dependencies draw from cobalt and lithium carbonate feedstocks, high-grade steel for masts, and rare-earth elements for AC motors. Single-source vulnerability in Jiangsu cell manufacturing creates geographic chokepoint risk. Distribution runs through captive OEM service networks in mature markets and specialized dealer channels in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global VNA truck penetration sits at early-cycle expansion, with e-commerce fulfillment density driving fleet upgrades from conventional forklifts to narrow-aisle configurations faster than replacement schedules alone would justify.
For Market Incumbents: Harden automation safety protocol certification to defend against emerging Chinese OEMs with pre-certified MIIT architectures. Deepen backward integration into lithium-ion cell supply to offset cobalt price volatility. Anchor premium positioning through captive distribution networks that lock in multi-year service contracts.
For New Entrants and Emerging Players: Pursue Indian cold chain automation gaps in Maharashtra and Gujarat, where temperature-controlled warehousing remains below automated material handling penetration thresholds. Target fuel cell hybrid configurations for 24-hour pharmaceutical distribution centers in Japan and South Korea. Lead with telematics-native platforms that bypass legacy WMS integration friction.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with guidance sensor and thermal management IP over pure-play assemblers. Long-term viability across the projection horizon rests on lithium-ion chemistry control and automation software stack ownership. Acquisition target archetype: regional specialists in high-bay cold storage with certified European distribution networks. Signal to watch: divergence between regional battery certification regimes accelerating OEM consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium-Ion Cell Supply | Captive battery production insulates margin pools from cobalt price volatility and Jiangsu supply concentration. |
| MIIT Certification Pre-Approval for Chinese Market Entry | Pre-certified control architectures bypass four-to-six-month type-approval delays under revised GB standards. |
| Telematics Platform Integration with WMS Middleware | Native API connectivity resolves legacy warehouse management system friction for pre-2018 deployments. |
| Fuel Cell Hybrid Configuration Development | Hydrogen range extenders paired with lithium-ion buffers serve 24-hour pharmaceutical throughput requirements. |
| Specialized Dealer Network Expansion in India | Dedicated cold storage service infrastructure captures underpenetrated automation demand in Maharashtra and Gujarat. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors at third-party logistics operators, maintenance heads at cold storage networks, and OEM product managers; and secondary validation through customs trade records, SEC filings of listed material handling conglomerates, MIIT equipment certification databases, and EU Machinery Directive compliance registries. Bottom-up unit shipment modeling triangulated against top-down warehouse automation investment flows.
Forecast inputs considered powertrain technology transitions, automation penetration curves, and regional regulatory divergence across product type, end user, technology, and application segments. CAGRs were derived from installed base replacement cycles and greenfield warehouse automation capex trajectories. Industry-specific inputs included lithium-ion chemistry adoption rates and fuel cell infrastructure readiness by geography.
Sensitivities concentrate around raw material price volatility in battery supply chains and divergence between regional electromagnetic compatibility standards. Forecasts reflect documented assumptions on fleet electrification timelines and e-commerce fulfillment density trajectories. Material shifts in Chinese export control enforcement on guidance system components or abrupt cobalt supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
Auto Parts Manufacturing Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Global Truck Refrigeration Unit Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Air Springs Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Aluminium Extrusion Market