
 Global Truck Refrigeration Unit Market | 2026-2036
Global Truck Refrigeration Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Truck Refrigeration Unit Market Intelligence
The increasing dominance of large, third-party logistics providers over independent owner-operators is redrawing competitive positioning. These large fleet buyers prioritize total cost of ownership, reliability, and telematics integration over initial unit price. Carrier Transicold leverages its extensive global service network to support major logistics partners. Thermo King differentiates with advanced multi-temperature zone systems for complex cargo requirements, while Denso Corporation specializes in compact, efficient units for smaller urban delivery vehicles.
A truck refrigeration unit is a self-contained system, typically powered by diesel or electricity, engineered to maintain a precise temperature inside an insulated truck body. These systems are defined by their cooling capacity and ability to hold set points for extended durations, crucial for preserving temperature-sensitive goods. While diesel units still hold a significant share, electric units represent the fastest-growing product type. The perishable food transport application continues to dominate volume, but pharmaceutical logistics offers higher-margin opportunities.
Regulatory frameworks are a primary force shaping product development. The US EPA's SNAP program, the EU's F-Gas Regulation, and China's MEE energy efficiency standards all mandate a shift away from high global warming potential refrigerants. These rules compel manufacturers to invest in alternative technologies like electric and hybrid systems. The critical decision for fleet operators now revolves around managing the capital expenditure for compliant technologies against future regulatory and operational risks.
Market Dynamics
The central tension in the truck refrigeration unit market is the simultaneous push from stringent environmental regulations for low-GWP refrigerants and the pull from pharmaceutical logistics for higher-precision, failure-proof temperature control, forcing a rapid evolution in system technology.
Growth Catalysts
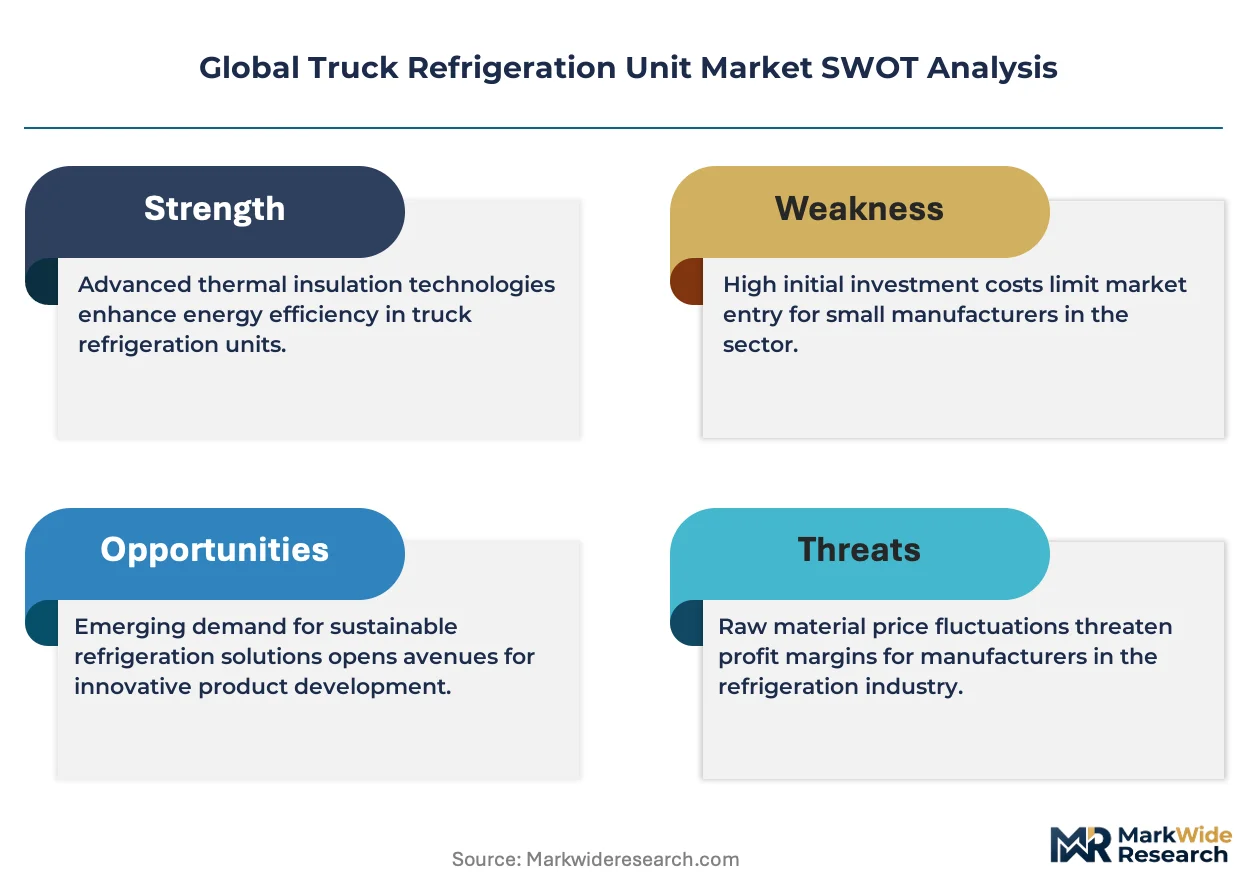
- Regulatory Mandates:The EU's F-Gas Regulation and the US EPA's SNAP program are creating a mandatory replacement cycle, compelling fleet operators to invest in new units that use environmentally compliant, low-GWP refrigerants.
- Pharmaceutical Logistics Expansion:The global distribution of biologics and vaccines requires advanced multi-temperature zone units with validated data logging, driving demand for premium, high-reliability systems beyond the needs of food transport.
- Indian Cold Chain Investment:Significant government and private investment in India's cold chain infrastructure, supported by policies like the PLI scheme, is fueling large-scale procurement for modernizing the food and pharmaceutical transport fleet.
Market Restraints
- High Capital Costs:The significant price premium for all-electric and advanced hybrid refrigeration systems over conventional diesel units acts as a major barrier to adoption, particularly for smaller fleet operators and independent owner-operators.
- Infrastructure Gaps:The lack of widespread, high-capacity charging infrastructure for all-electric trucks and refrigeration units limits their viability for long-haul routes, confining their use primarily to urban and regional distribution.
- Technical Limitations:Current battery technology constraints on energy density and performance in extreme ambient temperatures pose reliability challenges for all-electric units on demanding, multi-day routes, slowing their displacement of diesel power.
Strategic Opportunities
- Telematics and AI Integration:Developing subscription-based services that use AI for predictive maintenance and route optimization offers a new revenue stream while providing fleet managers with tools to reduce total cost of ownership.
- Ultra-Low Temperature Systems:A niche opportunity exists in engineering specialized cryogenic or ultra-low temperature units for the transport of cell and gene therapies, a high-value segment with exacting temperature requirements.
- Last-Mile Electrification:Designing compact, lightweight, and efficient electric units for small to medium-sized delivery vehicles addresses the growing demand for zero-emission solutions in urban logistics and e-commerce grocery delivery.
Industry Challenges
- Technician Skill Gaps:A persistent shortage of technicians trained to service and repair the complex electronics and battery systems of modern electric and hybrid refrigeration units is straining global service networks and increasing vehicle downtime.
- System Integration Complexity:Ensuring seamless data communication between new, feature-rich refrigeration units and the diverse, often proprietary, fleet management software platforms used by logistics customers presents a significant technical hurdle.
- Regulatory Fragmentation:Manufacturers must manage product development and supply chains to comply with a patchwork of differing refrigerant and energy efficiency standards across the EU, US, and China, increasing design and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Truck Refrigeration Unit Market |
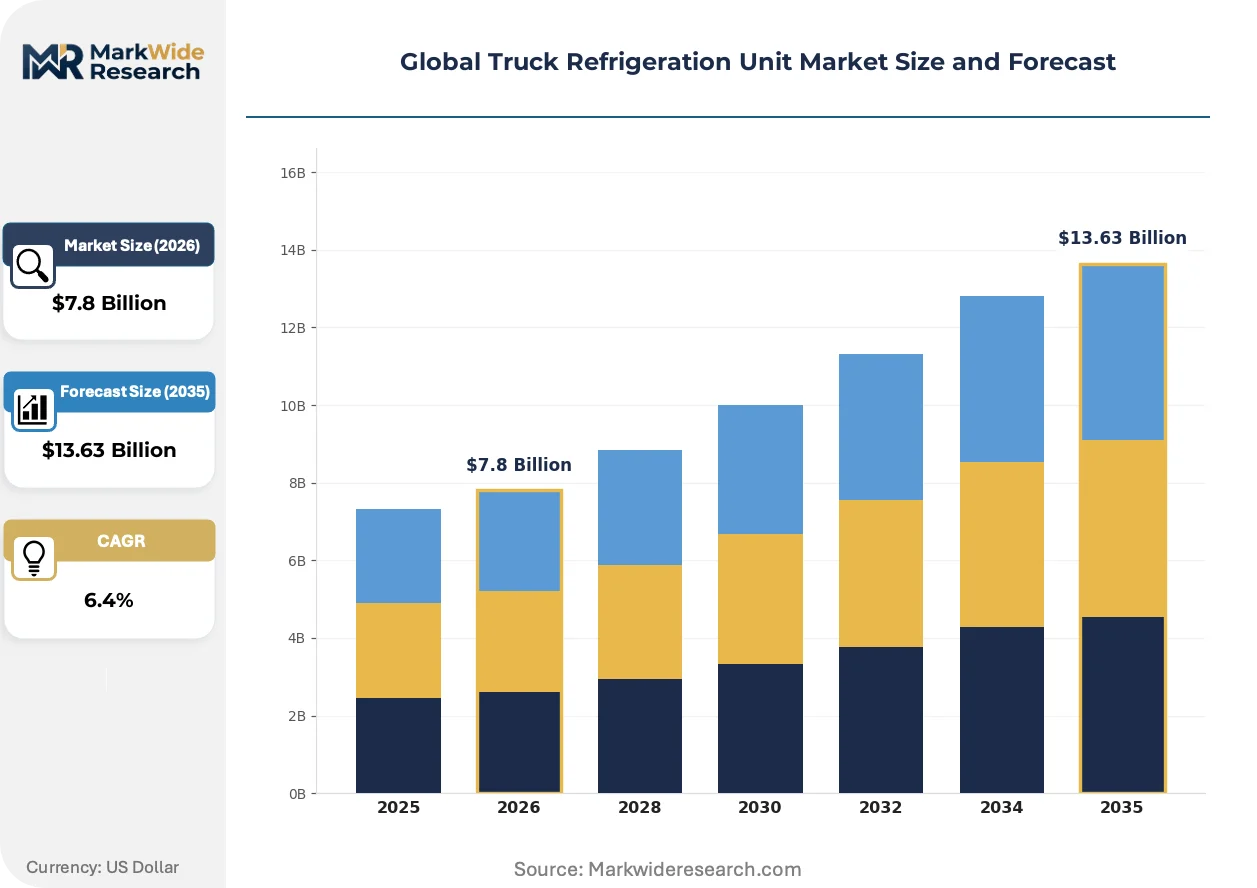
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Units, Diesel Units, Hybrid Units, Absorption Units Application: Perishable Food Transport, Pharmaceutical Logistics, Floral Delivery, Frozen Seafood Carriage End User: Logistics Providers, Cold Storage Warehouses, Courier Services, Food Retail Chains Technology: Vapor Compression, Thermoelectric Cooling, Cryogenic Refrigeration, Evaporative Cooling |
| Companies Covered | Webasto Group, Mitsubishi Heavy Industries Thermal Systems, Carrier Transicold, Subros Limited, Zanotti, Thermo King, Denso Corporation, Klinge Corporation, Daikin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Truck Refrigeration Unit Market Strategic Shifts & Innovations
Product innovation is defined by the dual pursuit of zero-emission operation to meet urban air quality rules and the integration of sophisticated telematics to provide auditable proof of temperature integrity for high-value cargo like pharmaceuticals.
All-electric refrigeration technology, which uses a dedicated battery pack or the truck's traction battery, is a key innovation. Last-mile and regional delivery fleets are the primary adopters, driven by access to depot charging and the need to operate in urban low-emission zones. This technology is fragmenting the traditionally monolithic diesel-powered market into a spectrum of specialized electric solutions tailored for specific vehicle sizes and duty cycles.
The EU's F-Gas Regulation is a powerful force compelling a systemic shift in refrigerant technology. Its aggressive phasedown schedule for hydrofluorocarbons (HFCs) makes investment in alternative, low-GWP refrigerants like CO2 (R-744) or hydrofluoroolefins (HFOs) a non-negotiable reality. This shift most heavily impacts long-haul fleet operators, who must balance the higher upfront costs and new maintenance protocols of compliant systems against significant regulatory and business continuity risks.
A notable shift in purchasing behavior involves moving from one-time hardware acquisitions to long-term, bundled service contracts. This model disrupts the standard unit sale by offering "temperature-as-a-service," which includes the equipment, telematics, predictive maintenance, and uptime guarantees for a fixed periodic fee. This trend is most prominent among large third-party logistics providers in North America and Europe seeking to convert capital expenditures into predictable operating expenses.
Global Truck Refrigeration Unit Market Segmentation
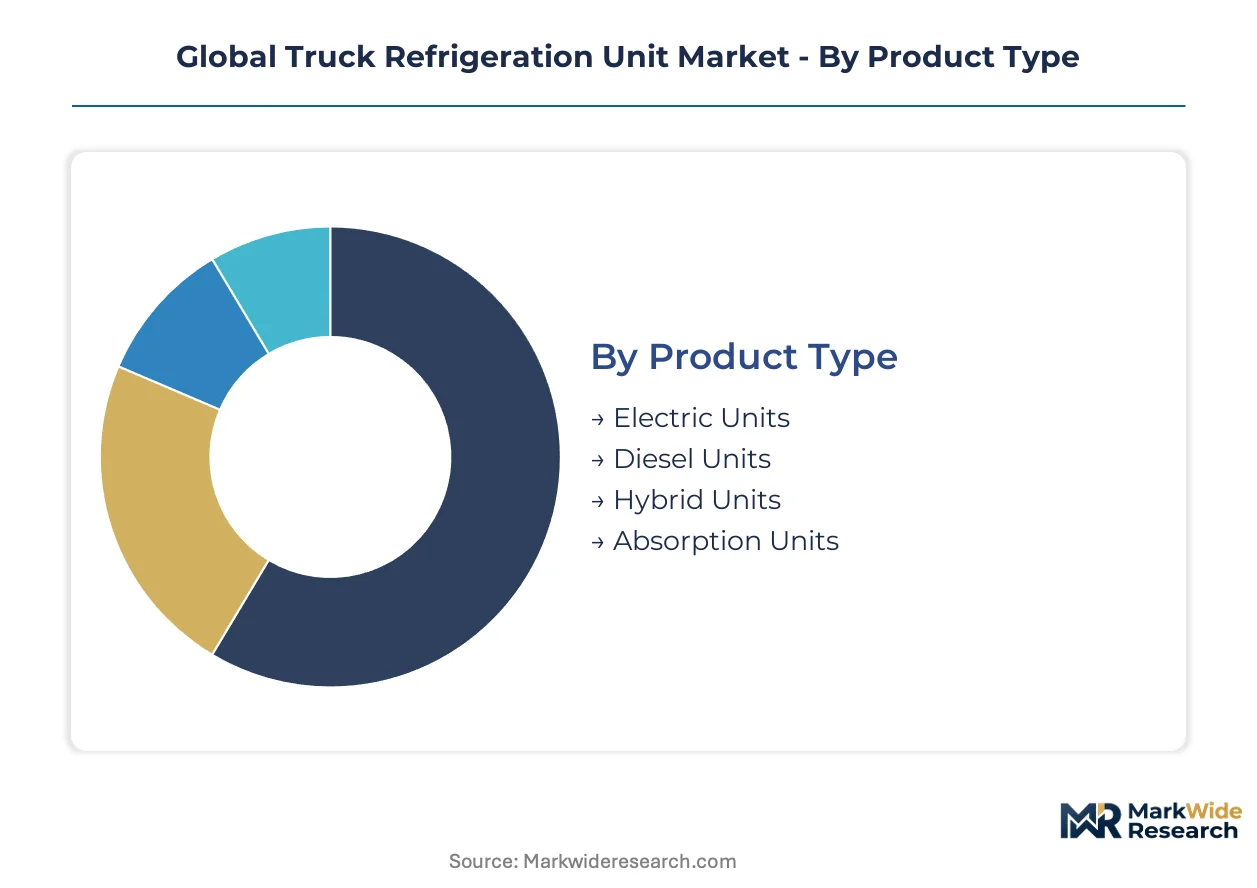
The segmentation of the global truck refrigeration unit market highlights the diverse operational requirements and technological preferences across various end-user applications. Understanding these distinctions is crucial for manufacturers to tailor solutions that address specific cold chain demands, from urban last-mile delivery to international pharmaceutical transport.
Product Type:
The product type segmentation reveals distinct preferences across different global regions, with some unit types dominating urban domestic routes and others serving international long-haul exports.
- Electric Units:These self-contained systems power the refrigeration compressor using dedicated battery packs or the truck's traction battery. Demand concentrates in European and North American urban centers, driven by zero-emission zone mandates and local delivery requirements.
- Diesel Units:These self-contained systems utilize an internal combustion engine to power the refrigeration compressor. Demand remains strong in emerging markets and for long-haul routes globally, supported by established infrastructure and lower initial capital expenditure.
- Hybrid Units:These units combine diesel power with electric standby or electric-assist capabilities, offering operational flexibility.
- Absorption Units:Absorption units use a heat source, often exhaust heat, to drive the refrigeration cycle, finding niche applications.
Diesel Units command the established base. The steepest expansion runs through Electric Units.
Application:
The application segments demonstrate varying margin profiles and operational complexities for refrigeration unit manufacturers.
- Perishable Food Transport:These units maintain precise temperatures for fresh produce, dairy, and meat products during transit. Demand is universally high across all geographies, driven by consumer expectations for fresh goods and robust retail supply chains.
- Pharmaceutical Logistics:Specialized units ensure stringent temperature control for biologics, vaccines, and other sensitive medicines, often requiring multi-zone capabilities. Demand is accelerating in India and Europe due to expanding drug distribution networks and strict regulatory compliance.
- Floral Delivery:Units for floral delivery maintain specific cool temperatures to preserve freshness and prevent wilting during transit.
- Frozen Seafood Carriage:These applications require ultra-low temperature capabilities to prevent spoilage of frozen fish and shellfish over long distances.
Volume is dominated by Perishable Food Transport, while Pharmaceutical Logistics drives premium segment growth.
End User:
End-user categories reflect distinct procurement patterns and service level expectations within the cold chain ecosystem.
- Logistics Providers:Large third-party logistics firms operate extensive fleets, prioritizing total cost of ownership, reliability, and advanced telematics integration. These buyers are concentrated in North America and Europe, seeking long-term service contracts.
- Food Retail Chains:Major grocery chains and supermarket groups manage their own distribution fleets, requiring units optimized for frequent stops and multi-temperature deliveries. Demand for these units is strong in urban centers globally, supporting last-mile delivery.
- Cold Storage Warehouses:These end-users integrate refrigeration units into their transfer and short-haul distribution operations for inventory movement.
- Courier Services:Courier services primarily utilize compact electric units for last-mile delivery of temperature-sensitive parcels in urban areas.
The largest fleet procurements originate from Logistics Providers, with Food Retail Chains showing consistent expansion.
Technology:
Technology segmentation highlights the impact of environmental regulations and the ongoing pursuit of greater energy efficiency.
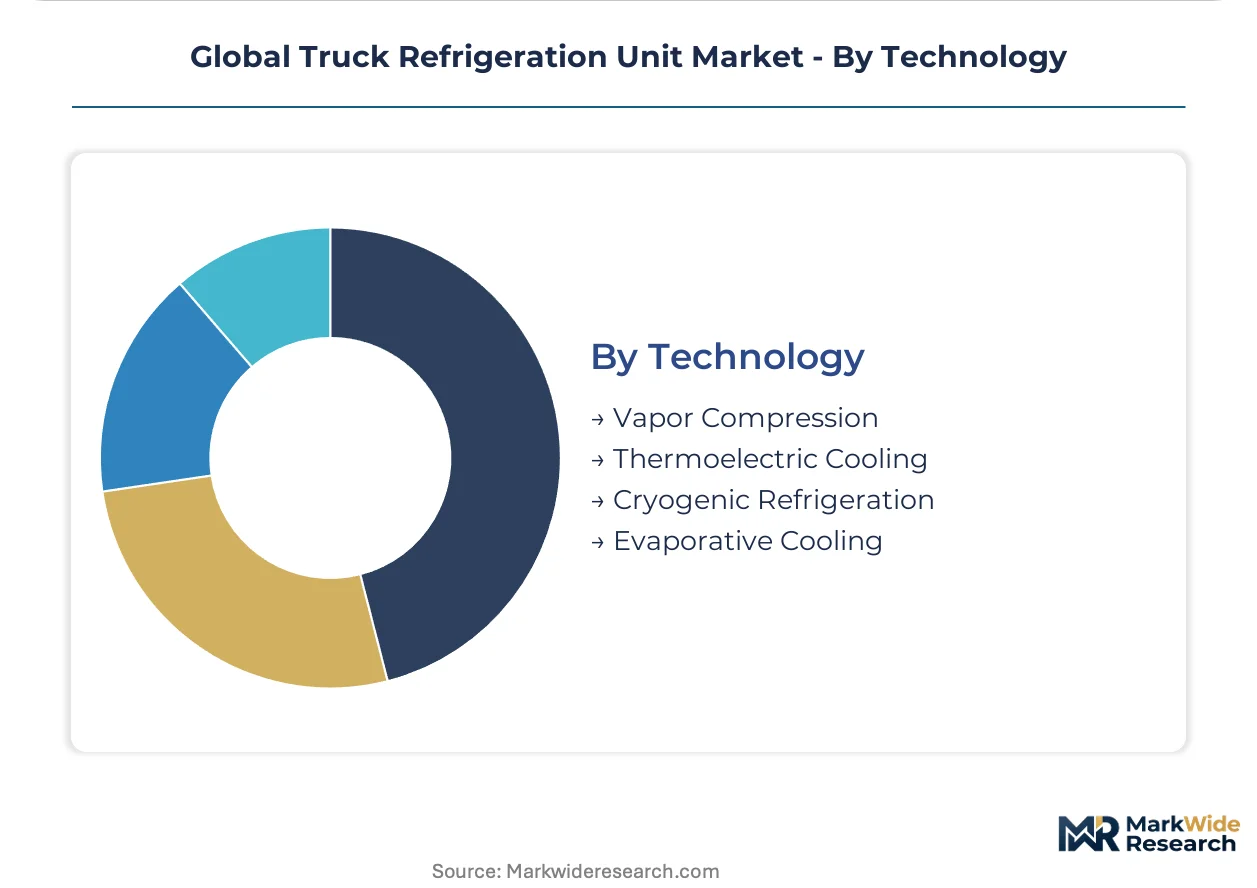
- Vapor Compression:This traditional technology uses a refrigerant to absorb and release heat through compression and expansion cycles. It remains the most widespread method globally, offering robust cooling capacity for diverse applications.
- Cryogenic Refrigeration:These systems use ultra-cold liquefied gases, like nitrogen, for rapid cooling and ultra-low temperature maintenance. Demand is emerging in pharmaceutical logistics for cell and gene therapies, particularly in advanced healthcare markets.
- Thermoelectric Cooling:Thermoelectric units use the Peltier effect for small-scale, precise temperature control in compact applications.
- Evaporative Cooling:Evaporative cooling systems reduce temperature through water evaporation, suitable for less stringent temperature requirements.
While Vapor Compression remains foundational, innovation is concentrated in Cryogenic Refrigeration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The supply-side for truck refrigeration units exhibits concentration among established manufacturers with global distribution networks. This structure influences technology adoption and service availability across diverse geographical markets, particularly in response to evolving environmental standards. Key regions are driving demand through specific regulatory pressures and significant infrastructure investments.
United States
Demand for advanced electric units in the United States stems from urban logistics and pharmaceutical transport needs. The US EPA's SNAP program mandates the transition to low-GWP refrigerants, significantly affecting fleet upgrade cycles. Major logistics hubs like Los Angeles and Chicago are seeing increased deployment of electric refrigeration technologies.
Germany
European demand for truck refrigeration units is driven by stringent environmental regulations and a sophisticated cold chain. The EU's F-Gas Regulation compels a systemic shift towards alternative refrigerants and electric systems for compliant operations. Munich and Hamburg, as key distribution centers, are actively investing in multi-temperature zone units and electric solutions.
India
India's truck refrigeration unit market is expanding due to substantial government and private investments in cold chain infrastructure. The PLI scheme supports domestic manufacturing and modernization of transport fleets for food and pharmaceutical logistics. Delhi-NCR and Mumbai, major economic corridors, are experiencing high procurement for modern refrigeration solutions.
China
Logistics providers in China are seeking efficient refrigeration units for a rapidly expanding e-commerce and fresh food delivery network. China's MEE energy efficiency standards and dual carbon goals are accelerating the adoption of electric and hybrid systems. The Yangtze River Delta region, a major manufacturing and distribution hub, is a focal point for new unit deployment.
Global Truck Refrigeration Unit Market Key Industry Players
Concentration sits with a few large, globally diversified manufacturers alongside specialized regional players catering to specific market needs. The competitive structure is tiered, featuring premium segment innovators focused on advanced features and volume-driven producers prioritizing cost-effectiveness. Dominant competitive moves include strategic partnerships for technology integration, particularly in telematics and electrification, and geographic expansion into rapidly developing cold chain markets.
Among the globally recognized manufacturers, Carrier Transicold and Thermo King occupy a position as market leaders, known for their extensive service networks and advanced system offerings for diverse applications. Carrier Transicold leverages its global support infrastructure to serve major logistics partners, while Thermo King differentiates with multi-temperature zone systems. Denso Corporation represents a strong presence, particularly in compact and efficient units designed for smaller urban delivery vehicles. These companies anchor the industry's evolution towards more sustainable and integrated solutions, responding to both regulatory pressures and customer demands for reliability.
| Leading Market Players |
|---|
| Webasto Group |
| Mitsubishi Heavy Industries Thermal Systems |
| Carrier Transicold |
| Subros Limited |
| Zanotti |
| Thermo King |
| Denso Corporation |
| Klinge Corporation |
| Daikin Industries |
| Others |
Cost & Logistics Intelligence
Two-week lead times for specialized components directly influence the supply chain's agility and the pricing power of major manufacturers. This tight coupling ensures that component availability impacts final unit costs.
Pricing Analysis
The EU's F-Gas Regulation dictates the pricing tier structure for truck refrigeration units, driving higher costs for compliant, low-GWP refrigerant systems. Pricing stratifies across premium, standard, and economy tiers, with advanced telematics integration and multi-temperature zone capabilities driving differentiation. Pricing pressure stems from the high capital cost of electric units, particularly for smaller fleet operators. Logistics providers, prioritizing total cost of ownership, are less price-sensitive than independent owner-operators.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume components, but strategic stockpiles are maintained for critical refrigerants and specialized electronic controls. The supply of core refrigeration compressors concentrates in Japan, Germany, and China. Raw material dependencies include specialized steel alloys, rare earth elements for electric motors, and advanced battery chemistries. Logistics chokepoints for cross-border component movement represent a structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global truck refrigeration unit market presents a significant service-attach opportunity, with subscription-based telematics and predictive maintenance services expanding faster than hardware unit sales. This shift allows for recurring revenue streams beyond the initial equipment purchase.
For Market Incumbents: Consolidate market share by leveraging extensive global service networks and deep integration with major logistics partners. Focus R&D on developing advanced multi-temperature zone systems for pharmaceutical logistics, addressing the threat from specialized niche players. Invest in technician training programs to mitigate skill gaps for complex electric and hybrid units. Strengthen channel control through long-term service contracts.
For New Entrants and Emerging Players: Differentiate on ultra-low temperature capabilities for cell and gene therapy transport, a high-value niche. Target last-mile electrification in urban centers, which is the most penetrable segment due to zero-emission mandates. A go-to-market angle involves offering compact, lightweight electric units bundled with charging infrastructure solutions for e-commerce grocery delivery.
For Investors and Strategic Acquirers: Long-term, this sits as a technology and service integration play because regulatory pressures and customer demands favor advanced, connected solutions. Acquisition targets include specialized software firms for AI-driven predictive maintenance or manufacturers of compact electric units. The signal to watch is the widespread rollout of high-capacity charging infrastructure for long-haul electric trucks.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven Predictive Maintenance | This initiative enhances unit uptime and reduces operational costs for large fleet operators. |
| Expand Global Service Network | A robust service network supports the complex repair needs of advanced electric and hybrid systems. |
| Invest in Ultra-Low Temperature R&D | This investment addresses the exacting requirements of high-value pharmaceutical logistics. |
| Form Charging Infrastructure Partnerships | These partnerships alleviate infrastructure gaps for electric unit adoption in long-haul applications. |
| Acquire Telematics Software Specialists | Integrating specialized software improves data communication and fleet management capabilities. |
Research Approach
A spread of perspectives from logistics executives, fleet managers, cold chain specialists, and regulatory compliance officers converged on the working assumptions for the market. The analysis combined primary interviews with industry stakeholders and secondary validation. Secondary data sources included US EPA SNAP program documents, EU F-Gas Regulation impact assessments, and Indian PLI scheme reports. Bottom-up and top-down triangulation provided robust data validation.
The segmentation dimensions modeled included product type, application, end user, technology, and regional adoption patterns. The analytical framework projected market growth across the analysis window, deriving CAGRs from historical trends and future regulatory impacts. Key industry-specific forecast inputs included cold chain infrastructure investment rates and low-GWP refrigerant technology development.
The analysis sits within stated boundaries; outcomes outside significant trade shifts or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions on regulatory enforcement. Revision becomes warranted when regulatory deadlines or battery improvements cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Japan Automotive Hydraulic Actuators Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Thailand Automotive Lubricants Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market