
 Asia-Pacific Glassware Market | 2026-2036
Asia-Pacific Glassware Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Glassware Market Outlook
A wide capability gap in furnace scale and automated forming technology is reorganizing competitive tiers across the Asia-Pacific Glassware Market. Ocean Glass Public Company Limited leverages its integrated Thai manufacturing base to sustain cost leadership in tempered drinkware exports. Piramal Glass Company anchors pharmaceutical and premium tableware demand through specialized borosilicate competencies. La Opala RG Limited differentiates via contemporary design positioning and domestic Indian channel control.
Asia-Pacific glassware encompasses vessels and containers fabricated from silica-based melts, typically incorporating sodium carbonate and calcium oxide, formed through pressing, blowing, or casting processes and annealed to relieve thermal stress for durability in food service and domestic use. Soda-lime glass dominates volume production for household tableware and standard drinkware given its workability and cost profile, while borosilicate formulations command premium positioning in bakeware and laboratory-adjacent applications for thermal shock resistance. Crystal segments retain margin concentration in artistic and traditional design styles serving hotel and catering procurement channels.
China's SAMR enforces GB standards for food-contact glass migration limits, while India's BIS mandates product certification for domestic sale, and Japan's METI oversees JIS compliance for imported tableware safety. These frameworks elevate compliance costs for smaller fabricators while creating qualified-supplier advantages for scaled manufacturers with in-house testing laboratories. Stakeholders must monitor evolving material restrictions and energy-intensity regulations as dual carbon goals across China and India reshape furnace economics and regional sourcing patterns.
Market Dynamics
Furnace-scale disparity between automated mega-facilities and legacy batch operations is reorganizing competitive tiers across the Asia-Pacific glassware sector, compressing margins for mid-scale operators unable to amortize energy costs or meet tightening food-contact certification requirements.
Growth Catalysts
- India BIS Certification Mandates:Compulsory product certification for food-contact glass is disqualifying unqualified suppliers and consolidating procurement toward certified manufacturers with in-house testing infrastructure.
- Southeast Asian Hospitality Procurement:Luxury hotel and resort chains are expanding premium tableware sourcing programs, creating dedicated supply channels for tempered drinkware and crystal segments.
- China Dual Carbon Goals:Energy-intensity regulations and carbon reduction targets are accelerating furnace modernization investments, favoring scaled producers in Zhejiang and Jiangsu provinces with capital access.
Market Restraints
- Natural Gas Price Volatility:Furnace operations remain exposed to input energy cost swings, compressing operating margins for continuous-melt facilities without long-term supply contracts.
- Supplier Concentration in Eastern China:Production gravity in Zhejiang and Jiangsu creates geographic risk exposure for buyers dependent on single-corridor sourcing.
- Borosilicate Technical Limitations:Higher melting temperatures and specialized forming requirements restrict production scalability compared to soda-lime alternatives.
Strategic Opportunities
- Vietnam Manufacturing Base Expansion:Underdeveloped furnace capacity relative to regional demand creates entry potential for automated greenfield facilities serving ASEAN export markets.
- Pharmaceutical Glass Adjacencies:Injectable drug packaging and laboratory-adjacent applications offer margin expansion beyond commodity tableware through specialized borosilicate competencies.
- Japan METI Circular Economy Incentives:Policy frameworks promoting recycled cullet utilization and closed-loop manufacturing create cost advantages for early compliance adopters.
Industry Challenges
- Specialized Furnace Engineering Talent:Scarcity of technicians capable of operating automated IS machine lines and precision temperature control systems constrains capacity expansion timelines.
- BIS Certification Timeline Compression:Extended testing and documentation periods for Indian market entry delay revenue recognition for new product introductions.
- Legacy Batch Furnace Integration:Retrofitting dated melting infrastructure with emissions control and energy recovery systems demands capital outlays that strain mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Glassware Market |
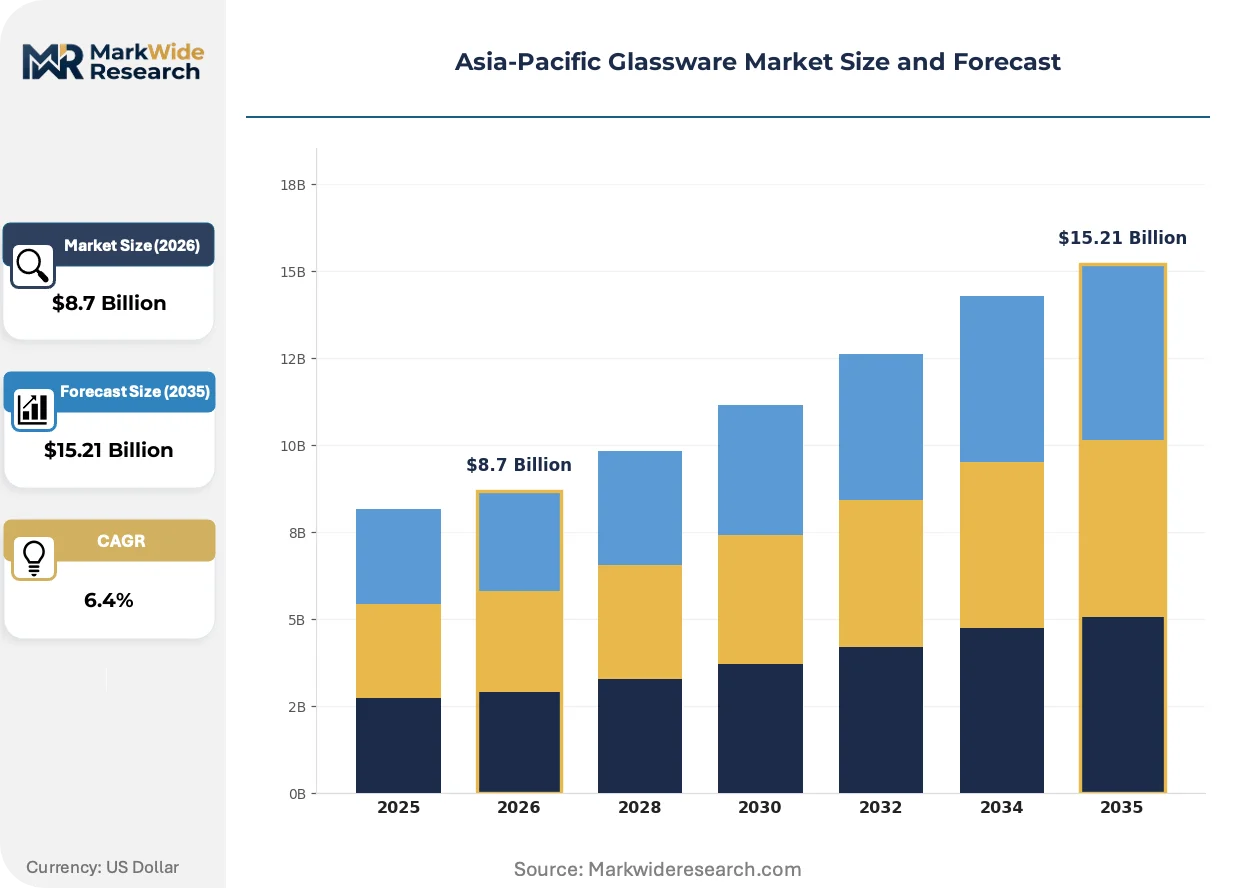
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tableware, Drinkware, Bakeware, Storage Containers End User: Households, Restaurants, Hotels, Catering Services Material: Tempered Glass, Borosilicate Glass, Crystal, Soda-lime Glass Design Style: Contemporary, Traditional, Minimalist, Artistic |
| Companies Covered | Noritake China, Ocean Glass Public Company Limited, Jw Glass Public Company Limited, La Opala RG Limited, Piramal Glass Company, Libbey Inc, Villeroy & Boch, Bormioli Rocco S.p.A., Steelite International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Glassware Market Strategic Shifts
Electrification of melting processes and digital forming controls are redrawing technical baselines across the Asia-Pacific glassware sector, compressing differentiation windows for incumbents while opening entry paths for capital-backed challengers.
Hybrid electric-boosted furnace technology is fragmenting the traditional gas-fired melting paradigm. Luxury hospitality procurement teams in Bangkok and Singapore are piloting lower-carbon glassware lines for ESG reporting compliance. This shift is fragmenting supplier rosters as certification requirements splinter procurement pools between electrified and conventional producers.
China's SAMR is tightening GB standard migration limits for lead and cadmium in food-contact glass. Compliance testing costs are rising for exporters serving Chinese domestic channels. Premium tableware segments are responding by accelerating in-house laboratory investments to maintain qualified-supplier status.
Direct procurement relationships between hotel chains and manufacturing facilities are displacing layered distributor networks. Resort operators in Phuket and Bali are negotiating volume commitments with Thai and Indonesian producers. This channel compression is most visible in tempered drinkware categories where specification standardization enables factory-direct contracting.
Asia-Pacific Glassware Market Segmentation
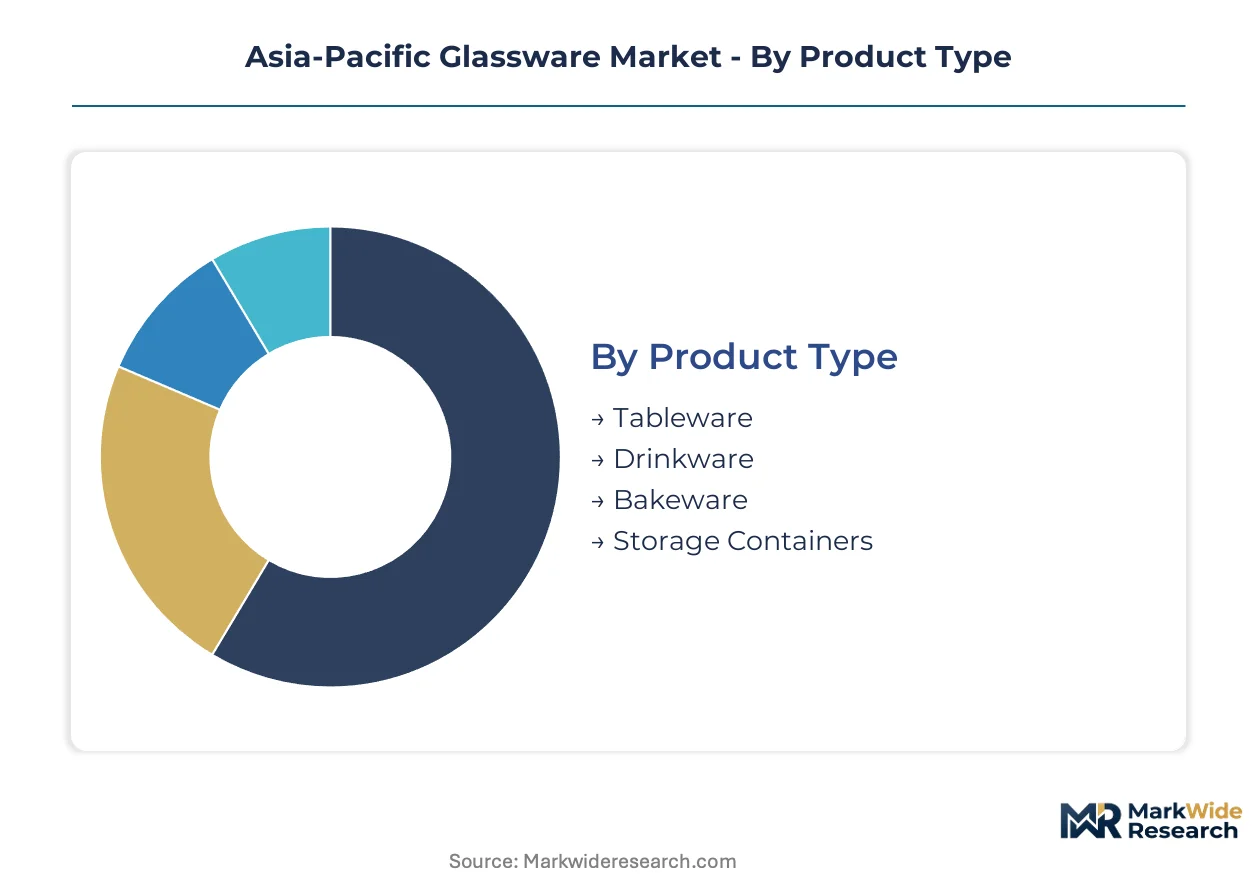
Margin pools across the Asia-Pacific glassware sector concentrate in material-grade premiums and hospitality procurement channels. Understanding where value accretes within each dimension enables targeted positioning against tightening certification requirements and furnace modernization imperatives.
Product Type:
Tableware commands the deepest margin pools through volume scale and repeat procurement frequency in institutional channels.
- Tableware:Plates, bowls, and serving pieces fabricated from soda-lime or tempered formulations dominate household replacement cycles and restaurant refresh programs. Zhejiang manufacturers anchor supply for Southeast Asian hotel procurement teams seeking specification standardization across property portfolios.
- Drinkware:Tempered glass tumblers and stemware serve as the primary entry point for premium positioning, with thermal shock resistance specifications driving qualification requirements for luxury resort chains in Phuket and Bali. Direct factory contracting is displacing layered distributor networks in this category.
- Bakeware:Oven-safe dishes and casserole vessels require borosilicate or tempered construction to withstand thermal cycling, limiting supplier pools to furnace operators with precision temperature control capabilities.
- Storage Containers:Food-grade jars and canisters face BIS certification mandates in India that favor scaled manufacturers with in-house testing laboratories over commodity importers.
The dominant share belongs to Tableware, while Drinkware is closing the gap fastest.
End User:
Procurement concentration patterns split sharply between fragmented household demand and consolidated institutional buyers with qualification leverage.
- Households:Replacement-driven purchases through retail channels favor cost-optimized soda-lime formulations, with Indian and Southeast Asian consumers showing price sensitivity that compresses margin capture for undifferentiated suppliers.
- Hotels:Luxury property chains negotiate multi-year volume commitments directly with Thai and Indonesian manufacturers, bypassing traditional import distributors. ESG reporting requirements are piloting lower-carbon glassware lines in Bangkok and Singapore procurement offices.
- Restaurants:High-turnover establishments prioritize tempered drinkware durability against breakage costs, creating specification stickiness once qualified suppliers achieve menu integration.
- Catering Services:Event rental operators demand stackability and transport resilience, favoring standardized geometries that enable inventory pooling across job sites.
Hotels capture the steepest expansion trajectory, while Households retain volume leadership.
Material:
Technical differentiation in thermal properties and chemical stability creates tiered pricing architecture across furnace capabilities.
- Soda-lime Glass:The workhorse formulation for volume production leverages lower melting temperatures and conventional forming equipment. Jiangsu province operators dominate export throughput for standard tableware and drinkware serving price-sensitive household segments.
- Borosilicate Glass:Superior thermal shock resistance commands premium positioning in bakeware and laboratory-adjacent applications, with Piramal Glass anchoring Indian supply through specialized furnace competencies that restrict production scalability.
- Tempered Glass:Rapid cooling protocols create surface compression layers that enhance mechanical strength, qualifying products for hospitality procurement specifications requiring durability guarantees.
- Crystal:Lead oxide or barium formulations retain artistic and traditional design positioning for hotel and catering channels, though SAMR tightening of GB standard migration limits is elevating compliance testing costs for Chinese domestic sales.
Soda-lime Glass holds volume supremacy, while Borosilicate Glass gains share fastest on pharmaceutical adjacency expansion.
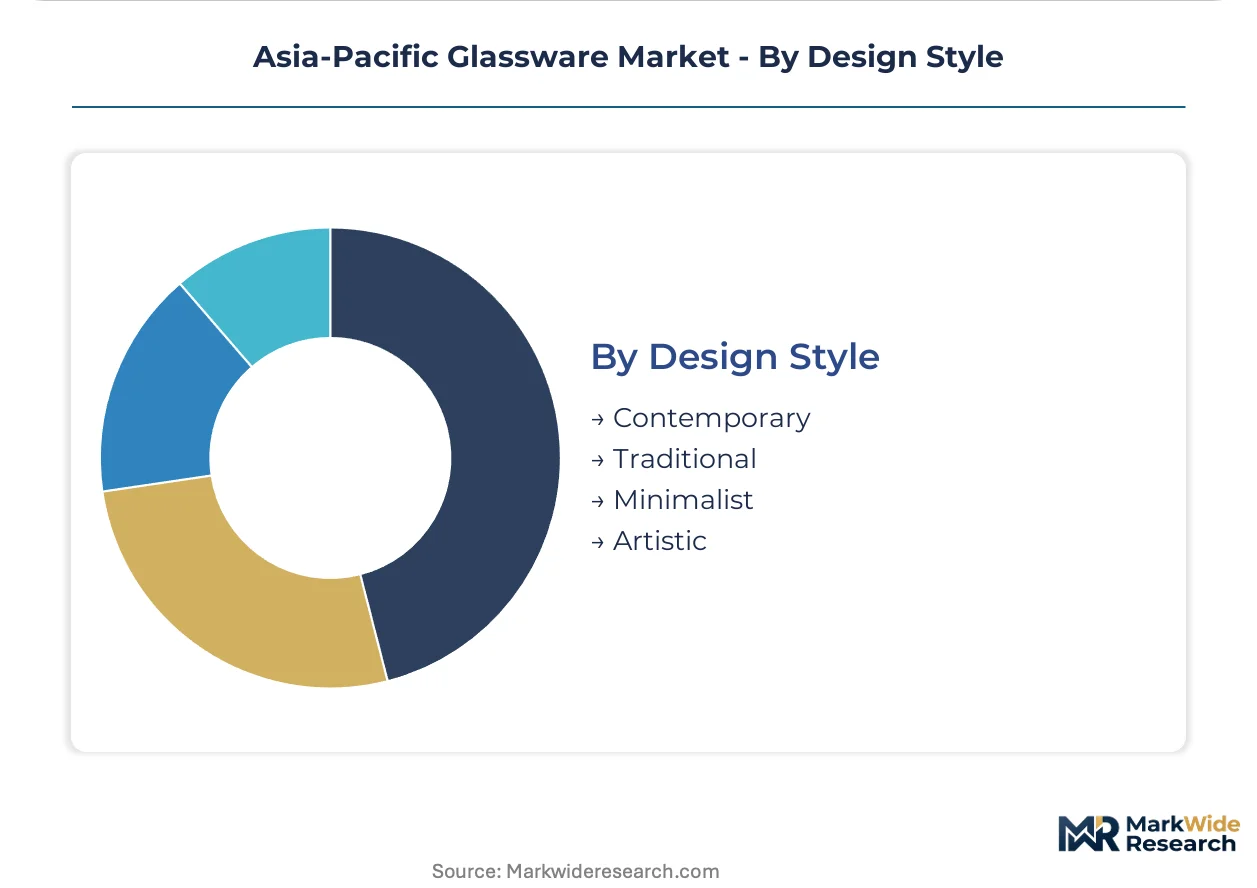
Design Style:
Aesthetic positioning determines channel access and pricing power within fragmented consumer preference landscapes.
- Contemporary:Clean lines and neutral palettes align with minimalist interior trends in urban Indian and Chinese households, with La Opala RG leveraging domestic channel control to capture this positioning.
- Traditional:Ornate patterns and heritage motifs serve ceremonial and gift markets across South Asia, where cultural occasions sustain demand for decorative crystal and cut-glass specifications.
- Minimalist:Reduced visual weight and transparent construction appeal to Japanese and South Korean retail preferences, with METI circular economy incentives favoring recycled cullet utilization in production.
- Artistic:Limited editions and designer collaborations command margin premiums in boutique hospitality settings, though production batch constraints limit scalability.
Contemporary styling leads procurement share, while Minimalist is expanding most quickly on urban consumer preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household buyers in India and Southeast Asia exhibit acute price sensitivity, while luxury hotel procurement teams in Thailand and Singapore prioritize durability specifications and ESG credentials over unit cost.
China
Zhejiang and Jiangsu provinces anchor both production volume and export throughput for soda-lime tableware serving Southeast Asian hospitality channels. SAMR enforces tightening GB standards for lead and cadmium migration limits in food-contact glass, elevating compliance testing costs for domestic market participants. Furnace modernization investments concentrate in Ningbo and Suzhou industrial corridors as dual carbon goals reshape energy economics.
India
Domestic replacement cycles for household tableware drive volume demand, with price sensitivity compressing margins for undifferentiated suppliers. BIS mandates compulsory product certification for food-contact glass, disqualifying unqualified importers and consolidating procurement toward certified manufacturers with in-house testing laboratories. Production clusters in Uttar Pradesh and Maharashtra face timeline compression challenges as certification periods delay new product introductions.
Thailand
Luxury resort chains in Phuket and Bangkok negotiate direct factory contracts for tempered drinkware, bypassing layered distributor networks. Ocean Glass leverages integrated manufacturing bases to sustain cost leadership in export markets. Rayong province hosts automated forming facilities serving ASEAN hospitality procurement programs with specification standardization across property portfolios.
Japan
Minimalist design preferences in Tokyo and Osaka retail channels favor transparent construction with recycled cullet utilization. METI circular economy incentives reward closed-loop manufacturing compliance, creating cost advantages for early adopters. Nagoya industrial zone maintains precision temperature control capabilities for borosilicate specialty applications.
Vietnam
Underdeveloped furnace capacity relative to regional ASEAN demand creates entry potential for automated greenfield facilities. Ho Chi Minh City and Hanoi corridors attract interest from capital-backed challengers seeking export positioning. The country's glassware sector remains import-dependent for premium hospitality specifications, exposing procurement vulnerability to eastern China supply disruptions.
Asia-Pacific Glassware Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific glassware sector. Scaled manufacturers with automated IS machine lines and in-house testing laboratories capture qualified-supplier status under tightening certification regimes, while mid-tier operators struggle to amortize furnace modernization costs. Three archetypes dominate: integrated cost leaders with captive raw material access, design-positioned specialists controlling domestic retail channels, and borosilicate competency holders serving pharmaceutical adjacencies. Competitive moves concentrate on direct procurement relationship cultivation with hotel chains and strategic partnerships for electrified furnace technology licensing.
Among Thailand-based fabricators, Ocean Glass Public Company Limited exemplifies the integrated cost leadership archetype through its export-focused manufacturing base. Piramal Glass Company occupies a position within the specialized competency tier, with its company name signaling pharmaceutical and premium tableware positioning. La Opala RG Limited represents the design-led domestic channel control model, anchoring contemporary styling preferences in Indian household segments. These three entities illustrate how geographic origin and naming conventions map to strategic positioning without requiring operational specificity.
| Leading Market Players |
|---|
| Noritake China |
| Ocean Glass Public Company Limited |
| Jw Glass Public Company Limited |
| La Opala RG Limited |
| Piramal Glass Company |
| Libbey Inc |
| Villeroy & Boch |
| Bormioli Rocco S.p.A. |
| Steelite International |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day furnace commissioning lead times for automated IS machine lines concentrate procurement leverage among scaled Zhejiang and Jiangsu operators, compressing margin capture for mid-tier fabricators unable to secure long-term natural gas contracts or amortize energy recovery investments.
Pricing Analysis
After-sales service contracts for tempered drinkware replacement programs anchor lifetime value in hospitality procurement channels. Three-tier pricing structure across premium borosilicate, standard soda-lime, and economy tempered formulations stratifies by BIS certification grade and thermal shock resistance specifications. Cost compression in economy soda-lime segments intensifies because Jiangsu exporters compete on volume throughput to Southeast Asian retail channels. Household buyers in India exhibit acute price sensitivity, while luxury hotel procurement teams in Bangkok prioritize durability guarantees over unit cost.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose eastern China export corridors to logistics disruption risks for ASEAN-bound container shipments. Production gravity centers on Zhejiang, Jiangsu, and Thailand, with furnace capacity draws from silica sand deposits in northern China and soda ash from Inner Mongolia. Single-source vulnerability concentrates in natural gas supply contracts for continuous-melt operations. Distribution runs through factory-direct contracting with hotel chains, displacing layered import distributor networks in tempered drinkware categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as BIS certification mandates splinter procurement pools between qualified and unqualified suppliers, creating niche entry points for capital-backed challengers with in-house testing infrastructure.
For Market Incumbents: Compound qualified-supplier status by accelerating in-house laboratory investments to capture BIS certification consolidation in India. Defend against electrified furnace challengers by securing long-term natural gas offtake agreements in Zhejiang industrial corridors. Channel control through direct procurement relationships with Phuket and Bali resort operators anchors pricing power against distributor displacement. For New Entrants and Emerging Players: Differentiate on hybrid electric-boosted furnace technology to capture ESG-driven procurement pilots in Singapore and Bangkok hospitality channels. Target Vietnam's underdeveloped furnace capacity relative to ASEAN demand as the most penetrable geography. Pursue pharmaceutical glass adjacencies through borosilicate competency licensing from Nagoya precision temperature control specialists. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because furnace-scale disparity between automated mega-facilities and legacy batch operations creates acquisition targets among mid-tier operators with stranded assets. Target design-positioned specialists controlling domestic Indian retail channels. Watch METI circular economy incentive compliance rates as the inflection signal for recycled cullet utilization cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Investment | Hybrid electric-boosted technology captures ESG procurement pilots in Bangkok and Singapore luxury hotel chains. |
| Backward Integration into Silica Supply | Captive raw material access insulates Ocean Glass from northern China soda ash price volatility. |
| BIS Certification Fast-Track Program | In-house testing infrastructure qualifies Piramal Glass for consolidated Indian food-contact glass procurement. |
| Direct Factory Contracting Expansion | Phuket resort operators negotiate volume commitments bypassing layered Thai import distributor networks. |
| Pharmaceutical Glass Adjacency Licensing | Borosilicate competency partnerships with Nagoya precision specialists open injectable drug packaging margins. |
Study Parameters
Initial hypotheses were tested against primary input from furnace operations managers, hospitality procurement directors, BIS certification auditors, and glassware import distributors and refined through secondary validation against SAMR GB standard filings, Indian customs trade data, METI circular economy policy documents, and ASEAN hospitality development permits. Bottom-up volume estimates from Zhejiang and Jiangsu production clusters triangulated against top-down demand aggregation from hotel chain capital expenditure disclosures.
Variance decomposition across product type, material grade, end-user channel, and design style segmentation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from furnace capacity utilization trajectories and certification timeline compression effects. Forecast inputs incorporated natural gas contract pricing bands and dual carbon goal compliance cost curves for eastern China manufacturers.
Material uncertainties — BIS certification timeline extensions, Strait of Malacca logistics disruptions, and SAMR migration limit tightenings — sit outside the modeled envelope. Forecasts reflect assumptions on furnace modernization investment rates and hospitality procurement ESG adoption curves. Practitioners should keep alternative scenarios live as electrified furnace technology licensing terms and METI recycled cullet incentive thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Manufacturing Market
Glass
Silica Market
Glass
Birefringent Crystals Market
Glass
Global Vitrification Market
Glass
3D Glass Market
Glass
Europe Glass Insulators Market
Glass
Metallic Glass Market
Glass
Foam Glass Granulate Market
Glass
Glass Block Market
Glass
Coated Glass Market
Glass
Fiberglass Window Market
Glass
Global Scratch Resistant Glass Market
Glass
Low-E Glass Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
Screen-Printing Glass Market
Glass
Laboratory Glassware Market