
 Cell and Gene Supply Chain Services Market | 2026-2036
Cell and Gene Supply Chain Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cell and Gene Supply Chain Services Market Outlook
The EU Green Deal is rebalancing cold chain investment toward lower-global-warming-potential refrigerants across European gene therapy logistics networks. Thermo Fisher Scientific leverages its cryogenic infrastructure footprint to sustain temperature integrity from manufacturing to bedside administration. Catalent Inc. anchors North American cell therapy distribution through its integrated packaging and logistics platform. World Courier competes on international courier density, operating validated cold chain lanes that connect clinical trial sites across multiple continents.
Cell and gene supply chain services encompass temperature-controlled logistics, cryogenic storage, specialized packaging, and regulatory-compliant distribution for living therapeutic products requiring maintenance at minus 150 degrees Celsius or controlled ambient conditions throughout transit. These services preserve cellular viability and genetic material integrity while enabling commercial-scale patient access to personalized medicines. Logistics services dominate current revenue as therapy developers outsource complex chain-of-custody requirements, while cold chain solutions within the technology dimension represent the fastest-growing segment due to expanding autologous therapy pipelines demanding patient-specific traceability. Quality control services command premium pricing where real-time temperature monitoring and serialization technology intersect with pharmacovigilance mandates.
FDA's cell and gene therapy guidance, EMA's ATMP regulation, and EU GDP guidelines collectively shape facility qualification standards, transport validation protocols, and audit requirements that determine market access for service providers. The EU AI Act introduces additional compliance layers for automated temperature monitoring systems used in predictive logistics analytics. Stakeholders must evaluate whether to build captive cold chain capabilities or deepen partnerships with specialized third-party logistics providers as therapy modalities diversify beyond viral vectors into non-viral delivery platforms.
Market Dynamics
The EU F-Gas Regulation is forcing wholesale replacement of hydrofluorocarbon refrigerants across ultra-low temperature freezer fleets, compressing capital cycles and accelerating vendor consolidation in cryogenic logistics infrastructure.
Growth Catalysts
- Autologous therapy pipelines:Patient-specific cell therapies require chain-of-custody tracking at minus 150 degrees Celsius, pulling specialized third-party logistics providers into manufacturing partnerships.
- EMA's ATMP framework:Centralized marketing authorization for advanced therapy medicinal products harmonizes cross-border distribution standards across EU member states.
- Rhine-Main cluster density:Contract manufacturers co-locating near Frankfurt Airport's pharmaceutical cargo hub create validated cold chain corridors reducing transit risk exposure.
Market Restraints
- Refrigerant supply constraints:Hydrofluorocarbon phase-down under EU F-Gas Regulation limits availability of replacement gases for existing ultra-low temperature equipment.
- Equipment vendor concentration:Cryogenic freezer manufacturing concentrates among three dominant suppliers, creating procurement bottlenecks for therapy developers scaling commercial production.
- Qualification timeline friction:FDA cell and gene therapy guidance requires 12-18 month transport validation protocols, delaying therapy launch timelines.
Strategic Opportunities
- Non-viral delivery platforms:Lipid nanoparticle and electroporation-based gene therapies require less stringent cold chain profiles than viral vectors, opening logistics service tiers.
- EU AI Act compliance services:Automated temperature monitoring systems used in predictive logistics analytics create demand for algorithmic audit and validation capabilities.
- Serialization integration:Pharmacovigilance mandates for patient-specific traceability converge with real-time temperature monitoring, enabling premium quality control service bundles.
Industry Challenges
- Cryogenic engineering talent scarcity:Qualified technicians for minus 150 degrees Celsius equipment maintenance and repair remain concentrated in pharmaceutical manufacturing hubs.
- Legacy warehouse retrofit costs:Existing distribution facilities require structural reinforcement and redundant power systems to support cryogenic storage zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell and Gene Supply Chain Services Market |
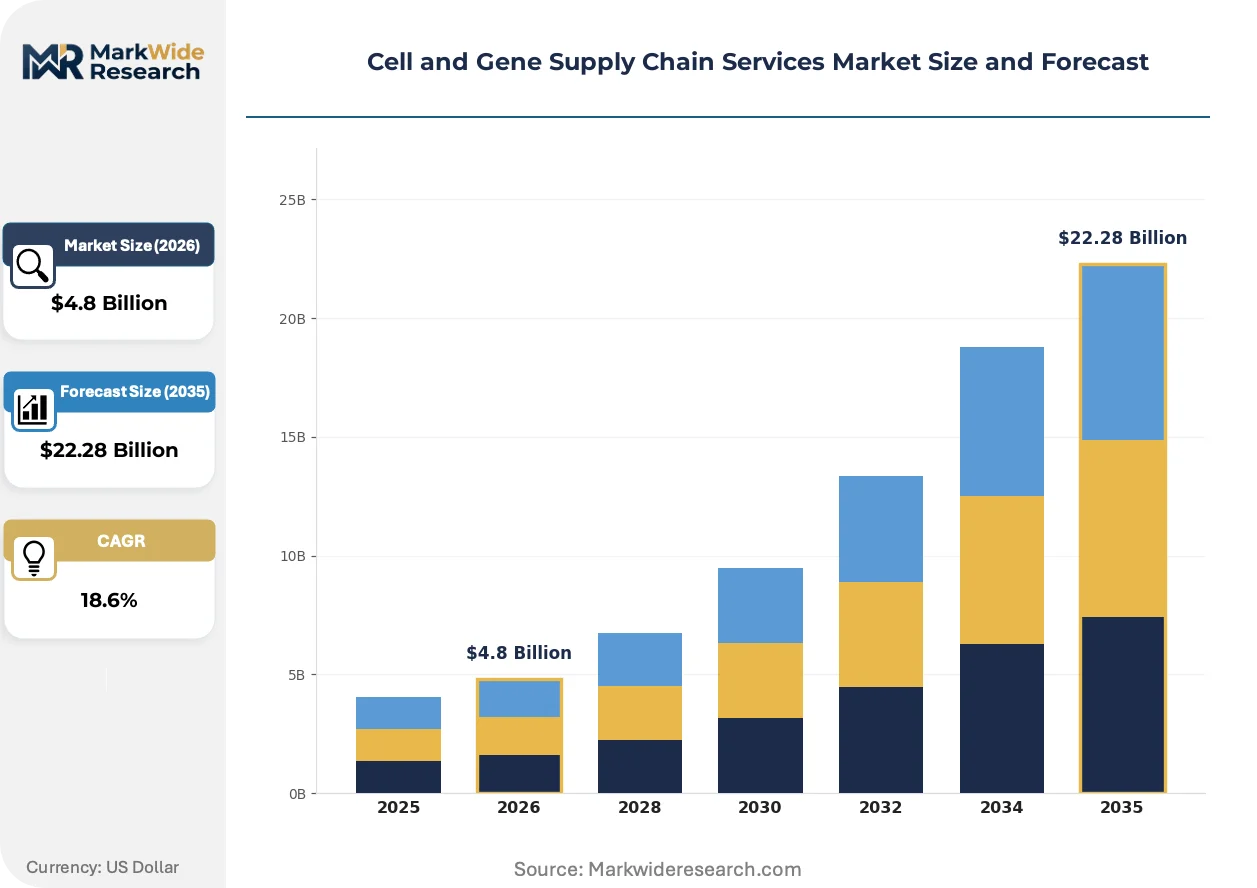
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Logistics, Packaging, Quality Control, Storage End User: Pharmaceutical Companies, Research Institutions, Biotech Firms, Contract Manufacturers Technology: Cold Chain Solutions, Temperature Monitoring, Shipping Platforms, Serialization Product Type: Cell Therapies, Gene Therapies, Tissue Products, Biologics |
| Companies Covered | AmerisourceBergen Corporation, Catalent Inc., Thermo Fisher Scientific, World Courier, Biocair Inc., Lonza Group, Arvato Supply Chain Solutions, BioLife Solutions Inc., Cryoport Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell and Gene Supply Chain Services Market Strategic Shifts
Digital integration across temperature monitoring, chain-of-custody documentation, and predictive analytics is compressing the gap between manufacturing release and patient administration.
Passive thermal packaging systems incorporating phase-change materials and vacuum-insulated panels are rewriting the economics of international clinical trial distribution. Biotech sponsors deploying these systems for autologous cell therapies reduce reliance on active refrigeration units during air transit. The technology is compressing the cost differential between regional manufacturing and centralized production models.
The EU AI Act imposes conformity assessment requirements on automated temperature monitoring systems processing predictive logistics data. Service providers must document algorithmic transparency and risk management protocols for AI-driven route optimization. Cold chain analytics vendors serving European gene therapy networks are restructuring product architectures to satisfy these audit requirements.
Biotech procurement teams are unbundling after-sales service contracts from equipment purchases, creating standalone validation and qualification service markets. Third-party logistics providers now compete directly with original equipment manufacturers for ongoing temperature mapping and re-qualification business. This shift is most visible in Germany's Rhine-Main biotech cluster, where contract manufacturers prioritize vendor flexibility over single-source equipment-service bundles.
Cell and Gene Supply Chain Services Market Segmentation
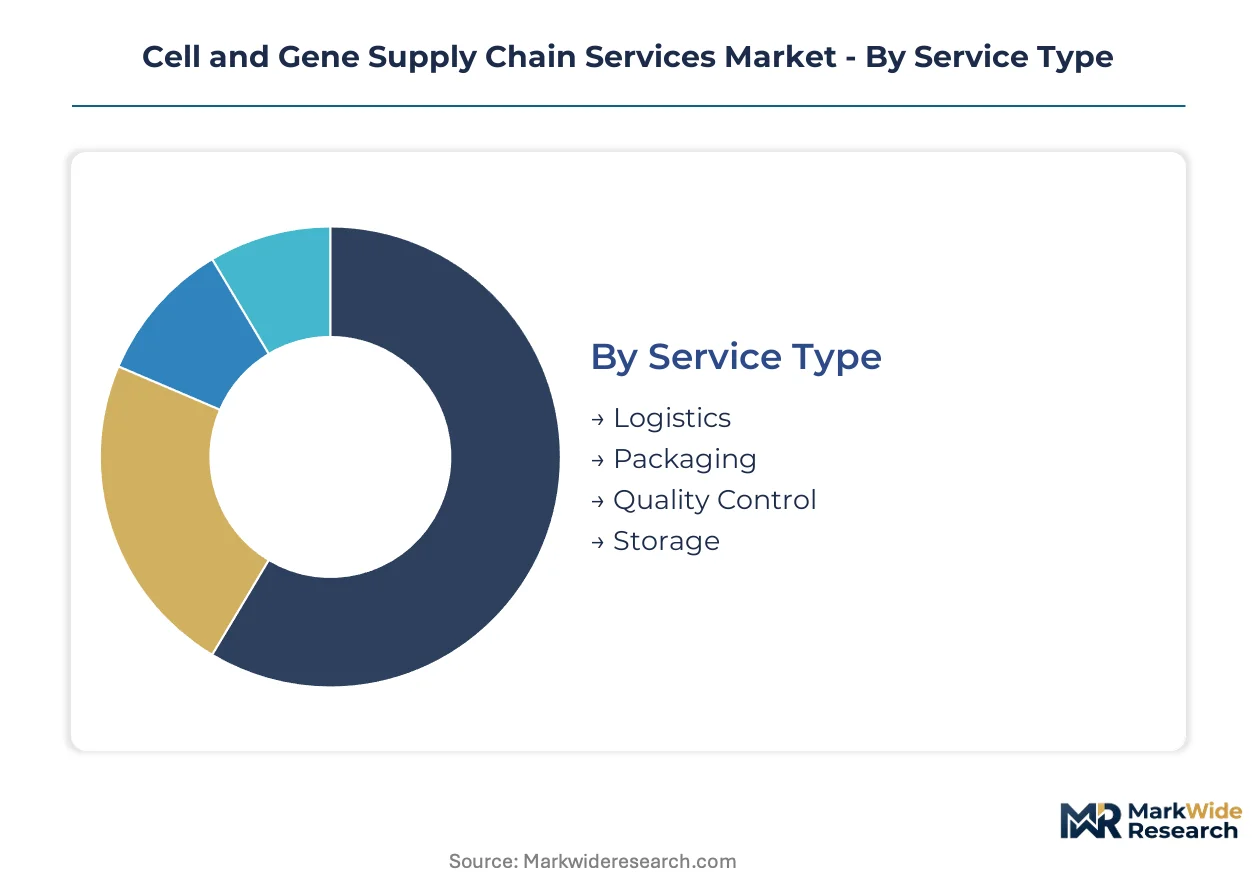
Cell and gene supply chain services demand granular segmentation because therapy modalities impose radically different temperature profiles, custody protocols, and regulatory pathways. Service providers configure infrastructure investments around specific segment requirements rather than offering uniform capabilities across all categories.
Service Type:
Capital intensity varies sharply across service categories, with cryogenic infrastructure requiring the heaviest upfront investment while digital services scale with lighter fixed asset bases.
- Logistics:Temperature-controlled transport networks with validated cold chain lanes connecting manufacturing sites to clinical administration points. Demand concentrates among autologous therapy developers in Germany's Rhine-Main cluster seeking chain-of-custody integrity at minus 150 degrees Celsius. EMA's ATMP framework harmonizes cross-border distribution standards, reducing qualification burden for multi-country trials.
- Storage:Cryogenic facilities maintaining cellular viability through liquid nitrogen or mechanical ultra-low temperature systems. The EU F-Gas Regulation accelerates equipment replacement cycles as hydrofluorocarbon refrigerants phase down, compressing vendor selection timelines for therapy developers scaling commercial production.
- Quality Control:Real-time temperature monitoring and serialization technology intersecting with pharmacovigilance mandates. FDA guidance requires 12-18 month transport validation protocols.
- Packaging:Passive thermal systems incorporating phase-change materials and vacuum-insulated panels for international clinical trial distribution.
Logistics absorbs the bulk of installed capacity; Storage is expanding most quickly.
End User:
Customer sophistication determines service tier selection, with commercial-stage sponsors demanding integrated platforms while research institutions prioritize flexibility over scale.
- Pharmaceutical Companies:Integrated supply chain platforms spanning manufacturing release through bedside administration. Large sponsors in North America and Europe consolidate vendor relationships to reduce audit complexity under FDA and EMA frameworks.
- Biotech Firms:Outsourced cold chain logistics for autologous cell therapy pipelines requiring patient-specific traceability. Venture-backed developers lack capital for captive infrastructure, pulling specialized third-party logistics providers into manufacturing partnerships.
- Contract Manufacturers:Co-located near Frankfurt Airport's pharmaceutical cargo hub, creating validated cold chain corridors that reduce transit risk exposure.
- Research Institutions:Flexible procurement arrangements prioritizing protocol adaptability over long-term contractual commitments.
Pharmaceutical companies anchor current revenue; Biotech firms are climbing the fastest as autologous pipelines mature.
Technology:
Technology segmentation reflects the digital transformation of physical supply chains, with hardware and software solutions commanding different margin profiles and replacement cycles.
- Cold Chain Solutions:Active refrigeration units, cryogenic freezers, and passive thermal packaging systems. The EU F-Gas Regulation forces retrofit of ultra-low temperature equipment, accelerating vendor consolidation.
- Temperature Monitoring:Sensor networks and data loggers providing continuous environmental tracking. The EU AI Act imposes conformity assessment requirements on automated systems processing predictive logistics data.
- Serialization:Patient-specific traceability systems converging with pharmacovigilance mandates for advanced therapy medicinal products.
- Shipping Platforms:Digital infrastructure coordinating multi-modal transport with regulatory documentation.
Cold Chain Solutions command the largest installed base; Temperature Monitoring is gaining share fastest through AI-enabled predictive analytics adoption.
Product Type:
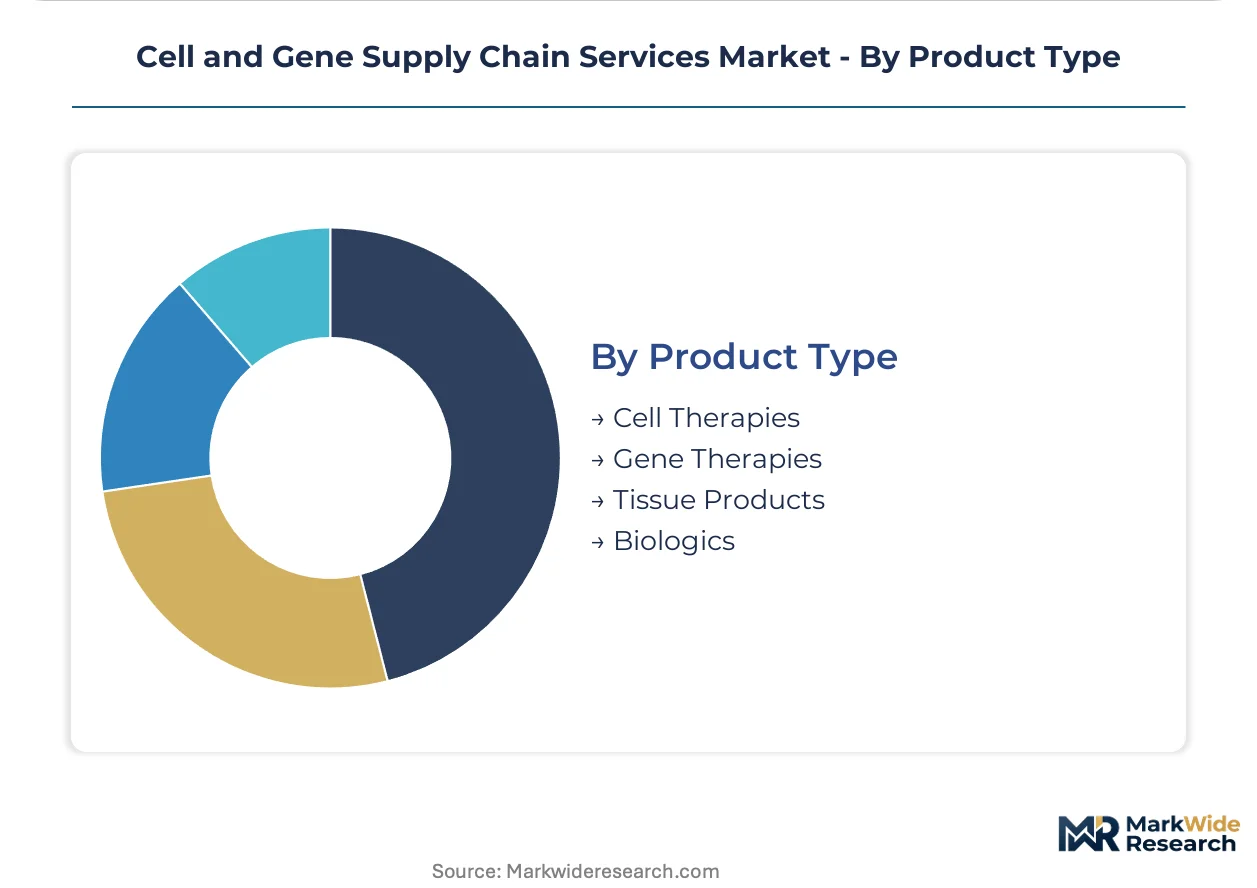
Product segmentation aligns supply chain configuration with biological stability requirements, where cellular therapies demand the most stringent environmental controls.
- Cell Therapies:Autologous and allogeneic products requiring maintenance at minus 150 degrees Celsius or controlled ambient conditions. Patient-specific traceability mandates under FDA cell and gene therapy guidance drive serialization integration.
- Gene Therapies:Viral vector and non-viral delivery platforms with varying cold chain profiles. Lipid nanoparticle formulations require less stringent temperature controls than adeno-associated viral vectors.
- Tissue Products:Processed human cellular and tissue-based materials with intermediate stability requirements.
- Biologics:Recombinant proteins and monoclonal antibodies with established cold chain protocols.
Cell Therapies absorb the bulk of cryogenic infrastructure investment; Gene Therapies are expanding most quickly as non-viral delivery platforms diversify pipeline composition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's Rhine-Main biotech cluster anchors European cell and gene supply chain activity, with contract manufacturers clustering near the airport's pharmaceutical cargo hub to minimize cryogenic transit risk.
United States
FDA's cell and gene therapy guidance shapes facility qualification standards across the Boston-Cambridge corridor and San Francisco Bay Area. The IRA's drug pricing provisions pressure therapy developers to optimize logistics costs. Greater Boston hosts the densest concentration of autologous therapy developers outsourcing cold chain custody.
Germany
EMA's ATMP framework harmonizes cross-border distribution standards for advanced therapy medicinal products. The EU F-Gas Regulation accelerates replacement of hydrofluorocarbon refrigerants in ultra-low temperature freezer fleets. Hesse's Rhine-Main region validates integrated cold chain corridors connecting manufacturing sites to Frankfurt Airport's cargo terminals.
Switzerland
Swissmedic's alignment with EMA procedures enables seamless EU market access for Basel-based therapy developers. The country's pharmaceutical trade agreements reduce customs friction for temperature-sensitive biologics. Basel-Land canton concentrates cryogenic storage infrastructure serving viral vector production facilities.
United Kingdom
MHRA's post-Brexit recognition agreements with EMA preserve cross-border distribution pathways for London-Oxford-Cambridge cell therapy developers. NHS England's specialized commissioning frameworks create demand for bedside administration logistics. The Golden Triangle anchors contract manufacturing capacity with integrated distribution capabilities.
Singapore
EDB's biomedical sciences initiative attracts cell therapy manufacturers to Tuas Biomedical Park. The country's free trade agreements with ASEAN markets enable regional distribution hub positioning. Biopolis hosts quality control laboratories specializing in real-time temperature monitoring for tropical climate transit validation.
Cell and Gene Supply Chain Services Market Competitive Environment
Premium-margin players sit above commodity-margin players across validation depth and cryogenic infrastructure ownership. The market structures around three tiers: integrated life science conglomerates with captive logistics arms, specialized third-party cold chain providers, and regional courier networks competing on lane density. Strategic archetypes include temperature integrity specialists, chain-of-custody platform operators, and regulatory compliance service bundlers. Consolidation concentrates among cryogenic equipment vendors while partnerships proliferate between therapy developers and logistics platforms.
Within the integrated platform tier, Thermo Fisher Scientific and Catalent Inc. exemplify archetypes combining manufacturing services with distribution capabilities. Cryoport Inc. occupies a position among specialized cryogenic logistics providers focused on minus 150 degrees Celsius custody integrity. World Courier represents international courier density strategies connecting multi-continental clinical trial sites through validated cold chain lanes.
| Leading Market Players |
|---|
| AmerisourceBergen Corporation |
| Catalent Inc. |
| Thermo Fisher Scientific |
| World Courier |
| Biocair Inc. |
| Lonza Group |
| Arvato Supply Chain Solutions |
| BioLife Solutions Inc. |
| Cryoport Inc. |
| Others |
Value Chain & Pricing Dynamics
Cryogenic engineering talent scarcity in Germany's Rhine-Main cluster widens labor-cost differentials between premium-tier validation services and economy-tier temperature monitoring, compressing mid-market margins as therapy developers unbundle equipment purchases from after-sales contracts.
Pricing Analysis
Outcome-based pricing anchored to patient-dose integrity uptime dominates contract structures for autologous cell therapy logistics, with premium tiers commanding certification-grade traceability under FDA cell and gene therapy guidance and economy tiers offering basic temperature logging. Price differentiation stems from serialization integration depth and geographic lane density, with biotech firms in venture-funded pipelines exhibiting highest price sensitivity and commercial-stage pharmaceutical sponsors least sensitive due to pharmacovigilance liability exposure. Cost compression in mid-tier storage services intensifies as EU F-Gas Regulation equipment retrofits absorb capital budgets.
Supply Chain Analysis
Workforce availability constraints for minus 150 degrees Celsius equipment technicians concentrate supply chain vulnerability in Germany, Switzerland, and the United States, where cryogenic infrastructure maintenance expertise clusters near pharmaceutical manufacturing hubs. Raw material dependencies span hydrofluorocarbon refrigerant alternatives, phase-change materials for passive packaging, and liquid nitrogen supply networks. Single-source vulnerability pervades cryogenic freezer manufacturing where three dominant equipment vendors control production. Distribution runs through validated cold chain lanes connecting Frankfurt Airport's pharmaceutical cargo hub to contract manufacturing sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
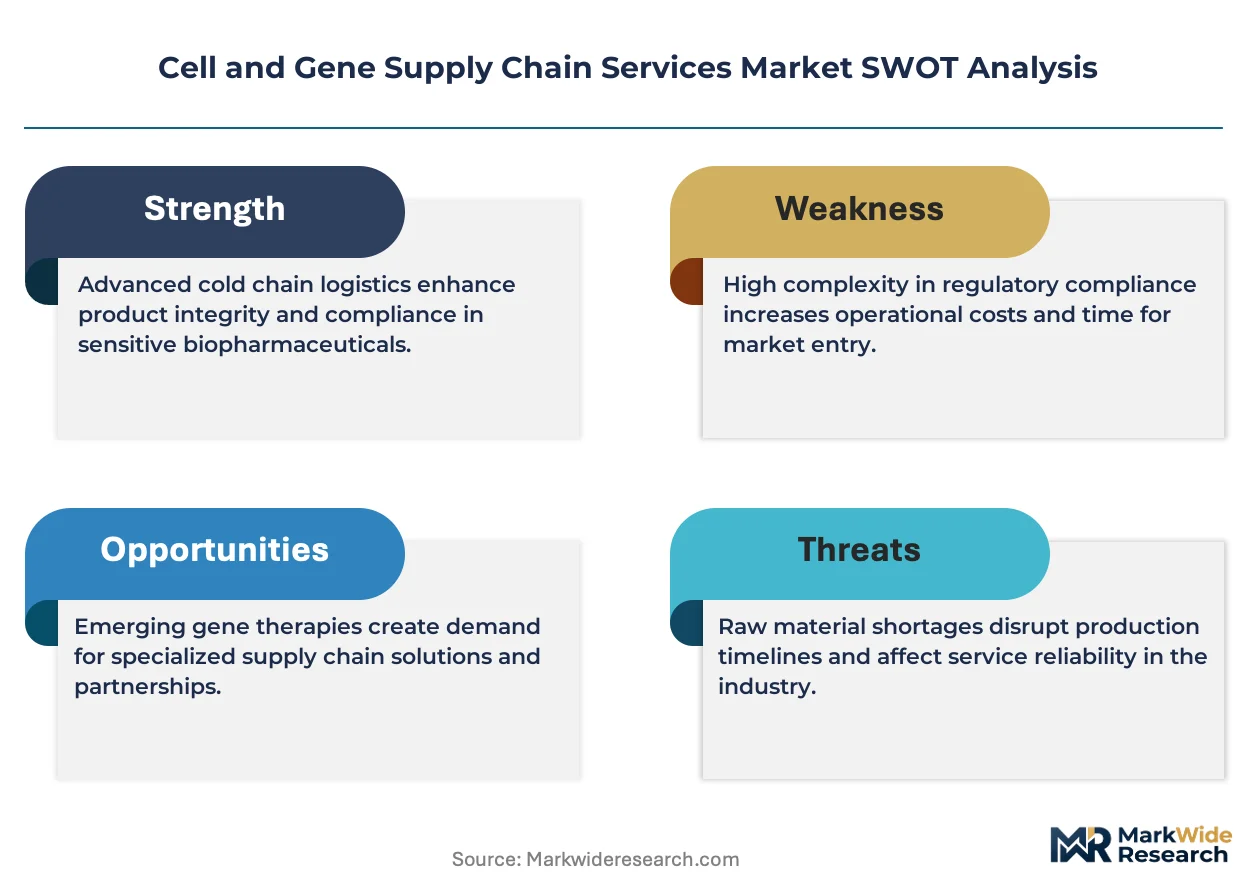
The EU AI Act's conformity assessment requirements for automated temperature monitoring systems erect a compliance moat that favors incumbent service providers with existing algorithmic audit capabilities over new entrants lacking validation infrastructure.
For Market Incumbents: Hedge refrigerant transition risk by accelerating partnerships with alternative-chemistry equipment vendors before EU F-Gas Regulation phase-down deadlines compress procurement timelines. Consolidate cryogenic engineering talent through targeted hiring in Basel and Boston-Cambridge corridors to defend against specialized third-party logistics providers poaching qualified technicians. For New Entrants and Emerging Players: Launch via non-viral delivery platform logistics services where lipid nanoparticle cold chain profiles require less stringent infrastructure than viral vectors, creating service tier differentiation. Target quality control and serialization integration bundles for mid-tier biotech firms unbundling after-sales contracts from original equipment manufacturer purchases. For Investors and Strategic Acquirers: Re-rating potential sits with specialized cryogenic logistics providers possessing validated minus 150 degrees Celsius infrastructure given autologous therapy pipeline maturation. Long-term viability favors asset-heavy platforms with captive cold chain ownership over asset-light software plays. Watch FDA transport validation protocol timeline extensions as inflection signals for qualification service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Fleet Retrofit | EU F-Gas Regulation compliance preserves market access for ultra-low temperature storage providers. |
| AI Validation Service Launch | EU AI Act conformity assessment creates premium audit and algorithmic transparency revenue streams. |
| Serialization Platform Integration | FDA patient-specific traceability mandates converge temperature monitoring with pharmacovigilance systems. |
| Passive Packaging Scale-Up | Phase-change material systems reduce active refrigeration dependency for international clinical trial distribution. |
| Rhine-Main Corridor Expansion | Frankfurt Airport pharmaceutical cargo proximity minimizes cryogenic transit risk for contract manufacturers. |
Study Parameters
Multi-period observation of cryogenic infrastructure deployment patterns and autologous therapy pipeline progression anchored the trend analysis, supplemented by interviews with cold chain logistics directors, regulatory affairs leads at advanced therapy medicinal product sponsors, quality control managers at contract manufacturers, and pharmaceutical procurement officers. Secondary validation drew from FDA cell and gene therapy guidance documents, EMA ATMP framework submissions, EU F-Gas Regulation implementation reports, and ClinicalTrials.gov protocol filings. Bottom-up service provider capacity estimates triangulated against top-down therapy developer spend projections.
Segment-weighting approaches modeled service type, end user sophistication, technology adoption stage, and product temperature profile across the projection horizon. Cold chain solution penetration rates, logistics outsourcing intensity, and quality control premium attach rates informed analytical frameworks. CAGRs derived from installed base expansion curves and therapy launch timeline densities without assuming linear adoption patterns.
Regulatory timeline acceleration, refrigerant supply disruption, and autologous therapy clinical failure rates are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect assumptions about EMA harmonization stability and FDA validation protocol consistency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Global Therapeutic Vaccines Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
Gene Delivery Technologies Market