
 Tunisia Container Glass Market | 2026-2036
Tunisia Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Tunisia Container Glass Market Insights
The EU Green Deal's extended producer responsibility mandates is consolidating export-bound container glass production around certified recyclability benchmarks. SOTUVER leverages its integrated furnace operations to sustain cost-competitive amber and flint glass output for European beverage clients. BE.TA. VERRE SARL anchors regional supply through specialized pharmaceutical-grade vial manufacturing. Tunisia Glass Group competes on proximity logistics, serving domestic olive oil and wine bottlers with shortened lead times.
Container glass comprises silica-sand-based, thermally formed hollowware typically manufactured through blow molding or press-and-blow processes, with wall thickness and chemical durability calibrated to contents ranging from carbonated beverages to reactive pharmaceuticals. The material's inertness and impermeability make it the preferred barrier packaging for oxidation-sensitive products across food, beverage, and pharmaceutical supply chains. Bottles dominate volume throughput in Tunisia's export-oriented beverage glass segment, while jars capture expanding demand from processed food producers and artisanal cosmetics formulators. Blow molding leads manufacturing-stage deployment for standardized bottle geometries, though press-and-blow methods gain traction in premium spirits and custom pharmaceutical presentations where dimensional precision commands margin premiums.
Tunisia's Ministry of Industry and Ministry of Environment enforce industrial emissions standards and packaging waste directives that shape furnace technology investments and post-consumer collection infrastructure. BIS-equivalent conformity assessments and CE marking requirements govern market access for glassware destined toward European Union member states. The country's national investment promotion agency channels incentives toward energy-efficient furnace rebuilds. Stakeholders must monitor regulatory alignment between Tunisian technical standards and evolving EU packaging sustainability protocols to preserve export competitiveness.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are compressing export windows for Tunisia's container glass producers, forcing furnace-level investments in certified recyclability infrastructure ahead of competitor nations.
Growth Catalysts
- Beverage export corridors:European bottlers source amber and flint glass from Tunis and Sfax manufacturing zones to supply wine and spirits brands requiring CE-marked packaging.
- REACH-aligned chemical durability standards:Pharmaceutical-grade vial production for EU markets drives specialized furnace configurations and quality certification uptake.
- Lightweighting technology diffusion:Thinner-wall bottle designs reduce silica sand and soda ash consumption per unit while maintaining pressure resistance for carbonated applications.
Market Restraints
- Natural gas price volatility:Furnace operations depend on imported Algerian pipeline gas, exposing margins to North African energy contract renegotiations.
- Silica sand supply concentration:High-purity deposits cluster in specific coastal governorates, creating single-source vulnerability for container glass batch formulations.
- Aluminum can substitution:Beverage brands in cost-sensitive segments pivot to metal packaging for single-serve formats, eroding glass volume in mass-market soft drinks.
Strategic Opportunities
- Pharmaceutical serialization mandates:EU MDR traceability requirements create demand for tamper-evident glass closures and etched batch coding compatible with automated inspection lines.
- Artisanal cosmetics channel expansion:Small-batch skincare formulators in domestic and Mediterranean markets seek premium jar presentations with custom color matching.
- Solar-powered furnace pilots:Hybrid thermal systems combining grid electricity with photovoltaic generation align with national investment promotion agency incentives for energy-intensive manufacturing.
Industry Challenges
- Specialized furnace engineering talent:Glass technology programs at Tunisian technical institutes produce insufficient graduates familiar with oxy-fuel combustion and electric boosting systems.
- Post-consumer collection infrastructure gaps:Reverse logistics for cullet recovery remain underdeveloped outside Greater Tunis, limiting closed-loop manufacturing scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunisia Container Glass Market |
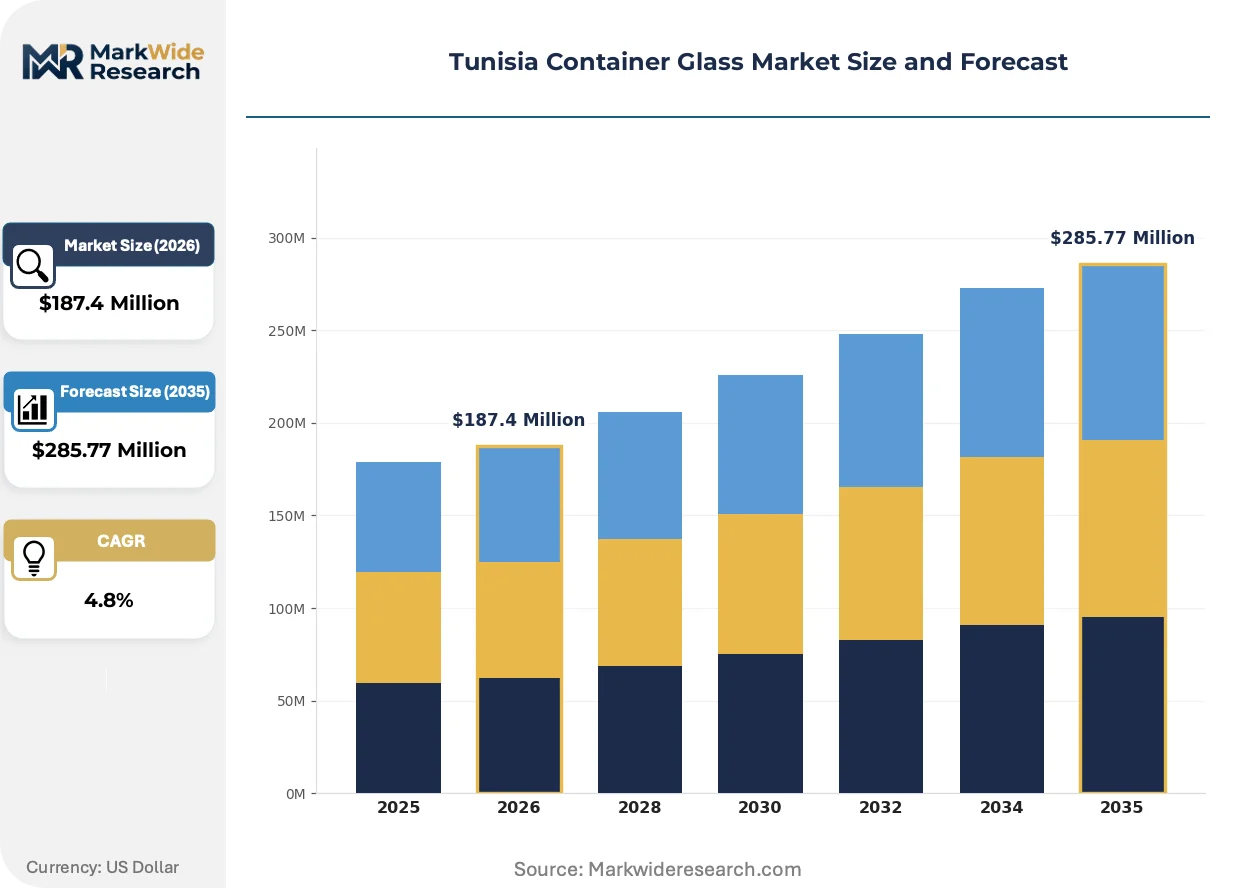
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Tumblers End User: Food Industry, Beverage Industry, Pharmaceutical, Cosmetics Manufacturing Stage: Blow Molding, Press and Blow, Molded, Annealing Distribution Channel: Direct Sales, Retail Stores, E-commerce, Wholesalers |
| Companies Covered | Pragati Glass Pvt. Ltd., BE.TA. VERRE SARL, SOTUVER, Tunisia Glass Group, BA Glass, Société Tunisienne de Verreries SA, STE TUNISIE LABEL, Vidrala SA, Feemio Group Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunisia Container Glass Market Trends and Innovations
Active furnace technology renovation and packaging sustainability protocol alignment are compressing the competitive set for Tunisia's export-bound container glass segment.
Electrical boosting systems integrated with oxy-fuel combustion are rewriting energy efficiency benchmarks for Tunisian furnace operations. SOTUVER and competing manufacturers deploy these hybrid configurations to reduce nitrogen oxide emissions while maintaining thermal uniformity for pharmaceutical-grade melts. The technology is rewriting cost structures for producers serving EU beverage clients facing Scope 3 reporting obligations.
EU Green Deal packaging waste directives now mandate minimum recycled content thresholds for glass containers entering single markets. Tunisian exporters must demonstrate cullet integration rates and end-of-life recyclability through third-party certification to preserve tariff advantages under the Euro-Mediterranean association agreement. Pharmaceutical vial manufacturers face the steepest compliance ramps due to purity requirements limiting post-consumer feedstock ratios.
Beverage brand technical buyers now specify lightweight bottle designs with performance guarantees spanning filling line compatibility and distribution stress testing. Tunisian producers respond with finite element modeling capabilities and rapid prototyping services that compress development cycles for custom spirits presentations. This specification intensity concentrates among olive oil and wine bottlers in the domestic market and French retail private label programs.
Tunisia Container Glass Market Segmentation
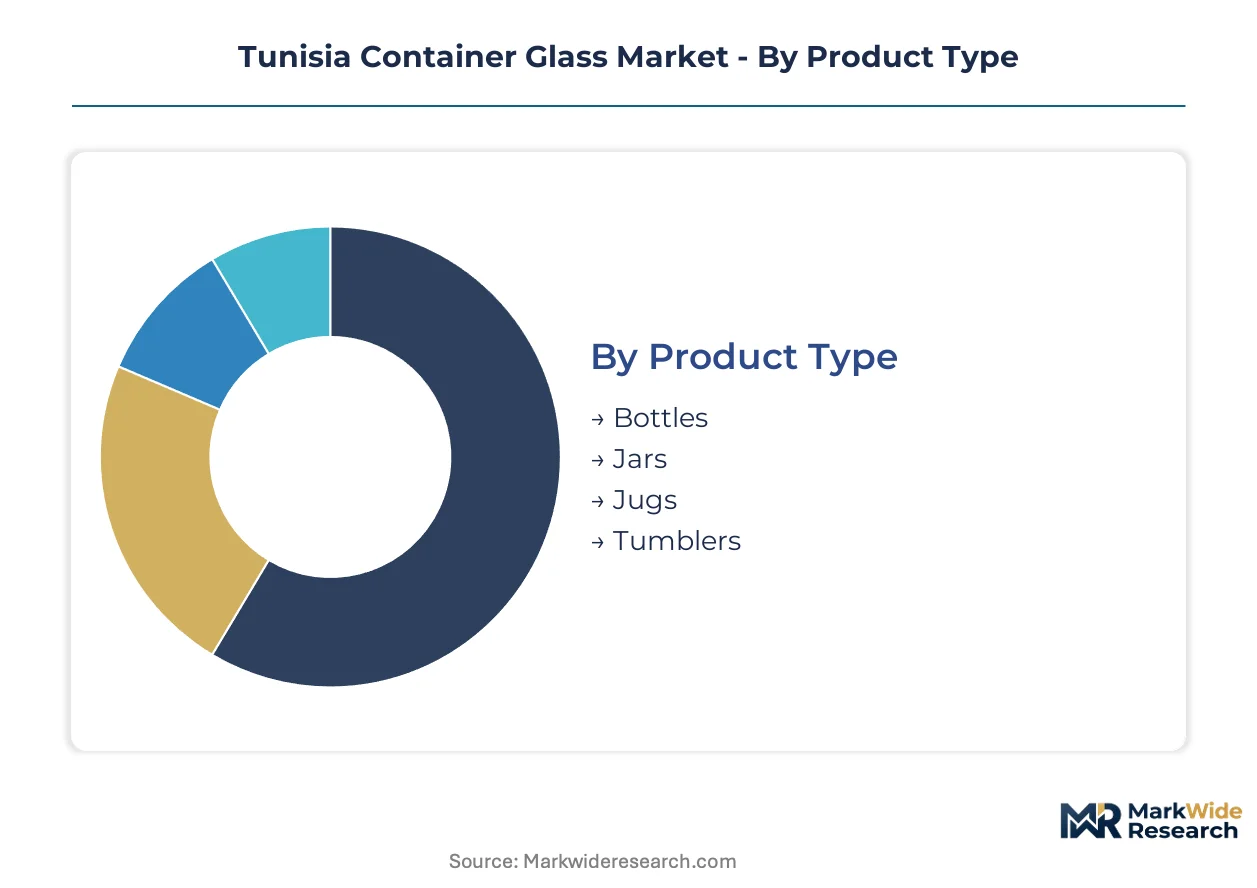
Container glass segmentation in Tunisia tracks divergent margin profiles across beverage export volumes and pharmaceutical precision requirements. Furnace configurations and quality certification tiers separate commodity bottle production from specialized vial manufacturing. Distribution channel selection directly shapes working capital intensity and customer concentration risk for Tunisian producers.
Product Type:
Bottles dominate tonnage throughput while jars command premium pricing through specialized cosmetic and pharmaceutical applications.
- Bottles:Silica-sand-based hollowware formed through blow molding or press-and-blow processes, calibrated for carbonated beverage pressure resistance and wine oxidation protection. Tunis and Sfax manufacturing corridors supply European bottlers with CE-marked amber and flint glass for wine and spirits brands under EU Green Deal recyclability mandates.
- Jars:Wide-mouth containers produced via press-and-blow methods for dimensional precision in pharmaceutical vial and premium cosmetic applications. BE.TA. VERRE SARL anchors regional supply through specialized pharmaceutical-grade manufacturing serving EU MDR traceability requirements.
- Jugs:Large-format containers for bulk food service and industrial chemical storage, typically manufactured through heavier-wall blow molding configurations.
- Tumblers:Straight-sided drinking vessels capturing limited demand from hospitality and retail channels, often produced as secondary furnace output during bottle campaign changeovers.
Today's leader: Bottles. Tomorrow's challenger: Jars.
End User:
Application-driven furnace scheduling prioritizes beverage campaign volumes while pharmaceutical batches require dedicated melt cycles.
- Beverage Industry:Wine, spirits, and olive oil bottlers drive container glass adoption across Tunisia's coastal manufacturing zones, with European export clients specifying lightweight designs and certified recyclability documentation.
- Pharmaceutical:Injectable vial and diagnostic container production demands REACH-aligned chemical durability standards and specialized annealing protocols for thermal shock resistance.
- Food Industry:Processed food producers and artisanal formulators source jar presentations for sauces, preserves, and condiments, with domestic demand concentrated in Greater Tunis retail corridors.
- Cosmetics:Small-batch skincare formulators in Mediterranean markets seek premium jar presentations with custom color matching and tamper-evident closure compatibility.
Beverage Industry commands current furnace capacity. Pharmaceutical represents the steepest margin expansion trajectory.
Manufacturing Stage:
Process selection determines energy intensity, dimensional tolerance, and minimum efficient scale for Tunisian furnace operations.
- Blow Molding:Compressed air-driven formation of standardized bottle geometries at high throughput rates, dominating Tunisian export beverage production with lower per-unit energy consumption.
- Press and Blow:Mechanical plunger pressing combined with air blow finishing for precise wall thickness distribution in pharmaceutical vials and premium spirits presentations.
- Molded:Direct mechanical forming for heavy-wall industrial containers and specialty closures, requiring simpler tooling but limiting geometric complexity.
- Annealing:Controlled cooling tunnels relieving thermal stress in formed glassware, mandatory for pharmaceutical-grade durability certification and high-value cosmetic applications.
Blow Molding anchors volume economics. Press and Blow captures value-added migration.
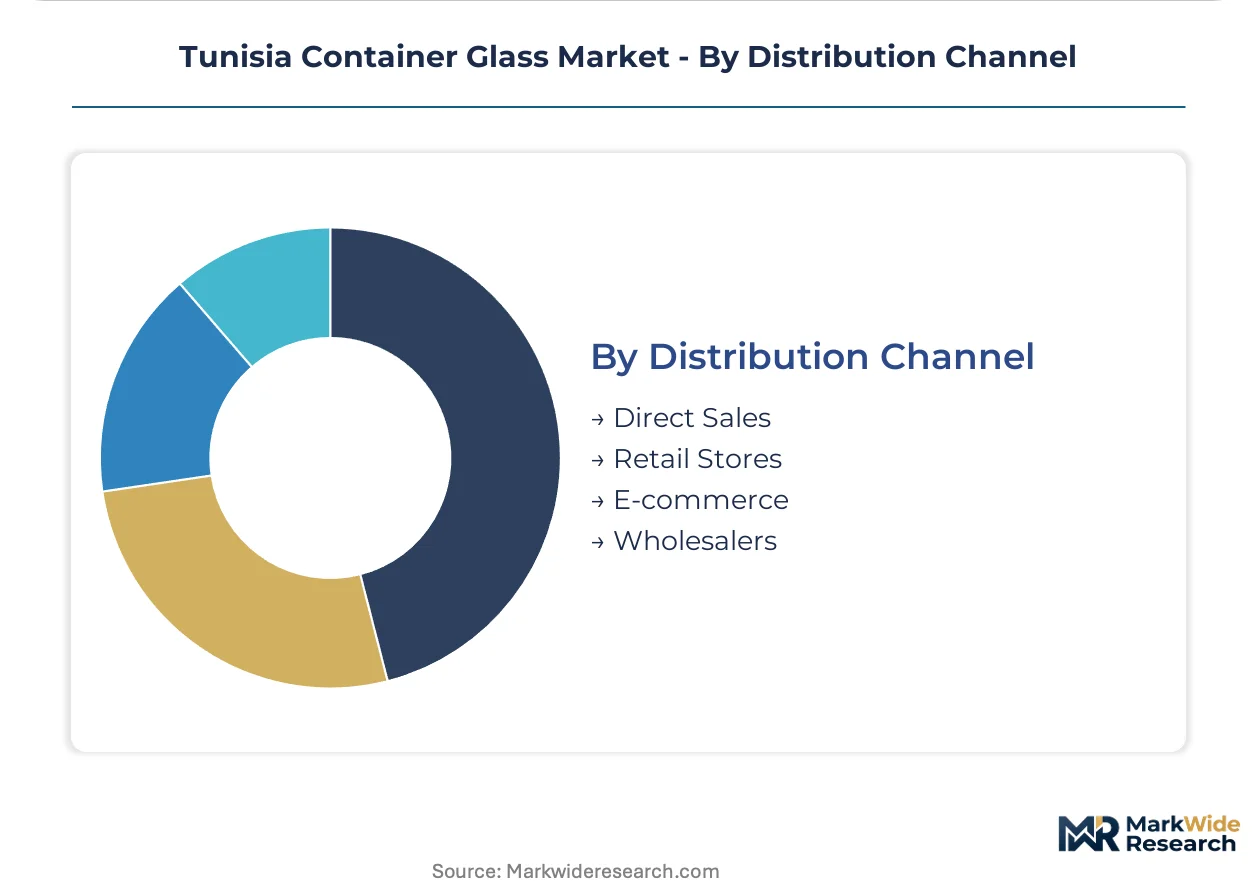
Distribution Channel:
Channel structure reflects customer scale, geographic concentration, and inventory carrying cost tolerance across Tunisia's glass-producing regions.
- Direct Sales:Large-volume contracts with European beverage bottlers and domestic olive oil producers, minimizing intermediary margins while requiring dedicated logistics coordination from Tunis and Sfax production corridors.
- Wholesalers:Regional distributors aggregating fragmented domestic demand from processed food and artisanal cosmetics formulators, extending payment terms and absorbing inventory risk.
- Retail Stores:Limited presence for specialty glassware and replacement containers, concentrated in urban Tunis commercial districts with high per-unit logistics costs.
- E-commerce:Emerging channel for small-batch cosmetic jar orders and custom color matching services, leveraging reduced minimum order quantities for Mediterranean artisanal formulators.
Direct Sales locks in export volume. E-commerce enables market access fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container glass manufacturing in Tunisia traces its industrial lineage to French colonial-era furnace installations in Tunis and Sfax, with post-independence state investment scaling capacity through the 1960s and 1970s to serve Mediterranean export corridors.
Greater Tunis
Olive oil bottlers and wine exporters in the capital region drive demand for amber and flint glass with CE marking compliance. The Ministry of Industry channels investment promotion agency incentives toward furnace rebuilds in this corridor. Tunis-based producers serve European beverage clients under EU Green Deal extended producer responsibility mandates.
Sfax Governorate
Coastal manufacturing zones here concentrate integrated furnace operations for high-volume export production. The national environmental compliance framework enforces emissions standards shaping oxy-fuel combustion adoption. Sfax facilities supply lightweight bottle designs to French retail private label programs.
Cap Bon Peninsula
Artisanal cosmetics formulators in this region generate specialized jar demand with custom color matching requirements. Domestic regulators enforce packaging waste directives that shape post-consumer collection infrastructure development. Nabeul and surrounding areas host small-batch skincare producers sourcing premium glass presentations.
Sahel Region
Processed food producers in Sousse and Monastir governorates source wide-mouth containers for sauces and preserves. BIS-equivalent conformity assessments govern quality certification for packaging destined toward Maghreb markets. This corridor exhibits expanding demand from domestic retail distribution channels.
Northwestern Mining Belt
High-purity silica sand deposits in Jendouba and Béja governorates supply batch formulations for container glass melts. Supply concentration creates single-source vulnerability for furnace operations dependent on specific mineral chemistry. Mining concessions operate under national industrial minerals licensing frameworks.
Tunisia Container Glass Market Competitive Landscape
Capital-heavy integrated furnace operators compete with specialized batch manufacturers and import-dependent distributors for share of Tunisia's container glass value chain. The market structure concentrates around three domestic producers with captive melting capacity, supplemented by regional trading houses sourcing finished ware from European and Asian suppliers. Strategic archetypes separate energy-intensive primary manufacturers, pharmaceutical-grade specialists, and logistics-focused proximity suppliers. Competitive moves center on furnace technology renovation and Euro-Mediterranean association agreement tariff positioning.
Among integrated Tunisian producers, SOTUVER and BE.TA. VERRE SARL exemplify divergent specialization vectors within the national market structure. SOTUVER occupies a position representing scale-driven export orientation toward European beverage clients, while BE.TA. VERRE SARL anchors the pharmaceutical-grade tier with specialized vial manufacturing capabilities. Tunisia Glass Group sits within the proximity logistics archetype, serving domestic olive oil and wine bottlers through shortened lead time configurations.
| Leading Market Players |
|---|
| Pragati Glass Pvt. Ltd. |
| BE.TA. VERRE SARL |
| SOTUVER |
| Tunisia Glass Group |
| BA Glass |
| Société Tunisienne de Verreries SA |
| STE TUNISIE LABEL |
| Vidrala SA |
| Feemio Group Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
EU beverage bottlers' lightweighting specifications for carbonated wine and spirits packaging force Tunisian furnace operators toward thinner-wall press-and-blow configurations, raising per-unit tooling costs while compressing margins on standardized amber bottle runs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade vial production from export beverage bottles and domestic commodity jars. Price differentiation hinges on CE marking compliance and furnace campaign minimums, with certified pharmaceutical melts commanding substantial premiums over uncertified beverage runs. Cost compression in standard-tier export bottles is intensifying because Algerian natural gas contract renegotiations feed directly into energy-intensive melting costs. Domestic olive oil bottlers exhibit highest price sensitivity, while European pharmaceutical clients prioritize batch traceability over unit economics.
Supply Chain Analysis
High-purity silica sand supply rests on Jendouba and Béja governorate mining concessions, with soda ash sourcing anchored in Egyptian and Turkish chemical production. Raw material dependencies include furnace refractories from German and Italian suppliers, oxy-fuel combustion equipment from French engineering firms, and pharmaceutical-grade mold coatings from Swiss specialty chemical producers. Single-source vulnerability concentrates in coastal silica deposits, where specific mineral chemistry limits alternative batch formulation. Distribution runs through direct sales contracts with European beverage bottlers and domestic olive oil producers, bypassing intermediary layers for volume export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tunisia's container glass market functions as a geographic-arbitrage play, leveraging Euro-Mediterranean association agreement tariff advantages against EU-based producers facing steeper natural gas and carbon compliance costs.
For Market Incumbents: Cement furnace-level oxy-fuel combustion retrofit leadership to defend against Algerian energy price volatility and incoming EU carbon border adjustments. Prioritize captive cullet recovery infrastructure in Greater Tunis to meet Green Deal recycled content thresholds before competitors secure certification. Lock in long-term supply contracts with Jendouba silica mining concessionaires to neutralize single-source raw material risk. For New Entrants and Emerging Players: E-commerce channels for small-batch cosmetic jar orders offer the most penetrable entry vector, serving Mediterranean artisanal formulators with custom color matching and reduced minimum order quantities. Target Cap Bon Peninsula skincare producers seeking premium glass presentations with tamper-evident closure compatibility. Pursue white-label pharmaceutical vial partnerships with BE.TA. VERRE SARL to access EU MDR traceability certification without captive furnace investment. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized pharmaceutical-grade batch manufacturers possessing REACH-aligned quality systems and existing EU MDR audit histories. Five-to-ten year viability favors furnace operators with demonstrated lightweighting prototyping capabilities and finite element modeling services for European spirits brands. Watch for EU packaging waste directive enforcement acceleration as the inflection trigger for cullet-integrated production scale.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Technology Renovation | Oxy-fuel combustion retrofits align SOTUVER operations with EU Green Deal nitrogen oxide emissions standards. |
| Backward Integration into Silica Mining | Captive Jendouba deposit control neutralizes single-source vulnerability for high-purity batch formulations. |
| Pharmaceutical Certification Investment | REACH-aligned quality systems unlock EU MDR traceability mandates for injectable vial export contracts. |
| Lightweighting Prototyping Services | Finite element modeling capabilities compress development cycles for French retail private label programs. |
| Cullet Recovery Infrastructure Buildout | Post-consumer collection networks in Greater Tunis satisfy EU minimum recycled content thresholds. |
Research Methodology
Bottom-up beverage and pharmaceutical end-use modeling reconciled against top-down furnace capacity and silica sand extraction tracking forms the analytical core of this study. Primary interviews with plant managers at Tunis and Sfax manufacturing facilities, procurement leads at European beverage bottlers, pharmaceutical regulatory affairs specialists, and distribution channel partners in Greater Tunis were cross-validated against secondary sources including Tunisian Ministry of Industry emissions filings, Euro-Mediterranean association agreement tariff schedules, ECHA REACH substance registrations, and EU Green Deal packaging waste directive implementations.
Historical production volume trendlines from Tunisian technical institutes and furnace campaign records inform the projection framework across the analysis window. Segmentation modeling incorporates product type, end-user industry, manufacturing stage process selection, and distribution channel structure. CAGRs derive from regression analysis against energy cost trajectories, EU regulatory compliance ramp schedules, and lightweighting technology diffusion curves. Forecast inputs include Algerian natural gas contract renegotiation patterns and pharmaceutical serialization mandate implementation timelines.
The model assumes a particular technology adoption path for oxy-fuel combustion and electric boosting systems; alternative pathways for solar-powered furnace pilots would alter the outlook for energy-intensive melting cost structures. Forecasts reflect assumptions regarding EU Green Deal enforcement consistency, REACH alignment maintenance, and Euro-Mediterranean tariff preference continuity. A small set of triggers—Algerian pipeline supply disruptions, EU carbon border adjustment acceleration, and pharmaceutical-grade cullet purity breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Glass Veil Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Dosing Bottles Market