
 Global Train Communication Gateways Systems Market | 2026-2036
Global Train Communication Gateways Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Train Communication Gateways Systems Market Outlook
Buyer concentration across European rail operators is rebalancing as national carriers consolidate procurement through joint ventures while Asian freight transporters fragment demand across private logistics consortia. Duagon AG leverages its IEC 61375 protocol expertise to anchor Central European retrofit programs. EKE-Electronics Ltd competes through Finnish R&D intensity in ruggedized gateway designs. Advantech Co., Ltd. extends its industrial computing dominance into rolling-stock edge platforms across East Asian corridors.
Train communication gateways systems comprise ruggedized network bridge hardware and protocol translation firmware that interconnects vehicle subsystems using IEC 61375-compliant MVB, WTB, and Ethernet train bus architectures, enabling real-time data exchange between traction control, passenger information, and diagnostic modules. Onboard Communication segments lead value capture due to rolling-stock lifecycle mandates, while Ethernet technology displaces legacy fieldbus in new-build contracts. Safety Systems applications sustain premium pricing through SIL certification requirements, though Remote Monitoring grows fastest as predictive maintenance contracts expand.
ETSI mandates GSM-R spectrum transition timelines across EU member states, while the EU AI Act imposes algorithmic transparency requirements on automated train operation gateways. The US FRA enforces Positive Train Control interoperability standards that dictate gateway protocol compatibility. Stakeholders must monitor regulatory divergence between IEC 61375-3-4 Ethernet extensions and regional cybersecurity frameworks as procurement specifications harden.
Market Dynamics
Ethernet train bus architectures are compressing gateway replacement cycles as IEC 61375-3-4 adoption accelerates across rolling-stock modernization programs. Deutsche Bahn's ICE fleet specifications and the EU F-Gas Regulation are forcing simultaneous protocol migration and refrigerant system overhauls, creating bundled procurement windows.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-global-warming-potential refrigerants in train HVAC systems trigger gateway replacements during climate-system retrofits across German and French passenger fleets.
- Predictive maintenance contracts:Freight operators in North American corridors are bundling remote diagnostic subscriptions with gateway hardware, expanding recurring revenue attach rates.
- IEC 61375-3-4 Ethernet extensions:Standardized interoperability specifications reduce integration risk for system integrators, accelerating new-build rolling-stock commissioning timelines.
Market Restraints
- Semiconductor supply concentration:Ruggedized FPGA and industrial Ethernet PHY sourcing remains concentrated among Taiwanese foundries, exposing lead-time volatility for gateway manufacturers.
- SIL certification timelines:Safety Integrity Level 4 validation for brake-control gateway interfaces extends product development cycles by 18-24 months, compressing margin recovery windows.
- Legacy MVB protocol entrenchment:Installed base of Multifunction Vehicle Bus systems in Central European commuter fleets creates substitution friction against Ethernet migration.
Strategic Opportunities
- Indian freight corridor digitization:Dedicated Freight Corridor Corporation procurement specifications for train-to-ground communication create first-mover positioning for Ethernet-MVB hybrid gateway suppliers.
- EU AI Act algorithmic transparency:Automated train operation gateway vendors can differentiate through pre-certified explainable AI modules for obstacle detection and speed optimization.
- Edge-AI and 5G convergence:Integration of onboard inference engines with private 5G rail networks enables millisecond-latency predictive maintenance for high-speed rolling stock.
Industry Challenges
- IEC 61375-3-4 implementation fragmentation:Divergent national interpretations of Ethernet train bus conformance testing create certification duplication costs across EU member states.
- Embedded cybersecurity skill scarcity:Shortage of engineers qualified in IEC 62443 industrial security standards delays secure gateway development for remote monitoring applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Train Communication Gateways Systems Market |
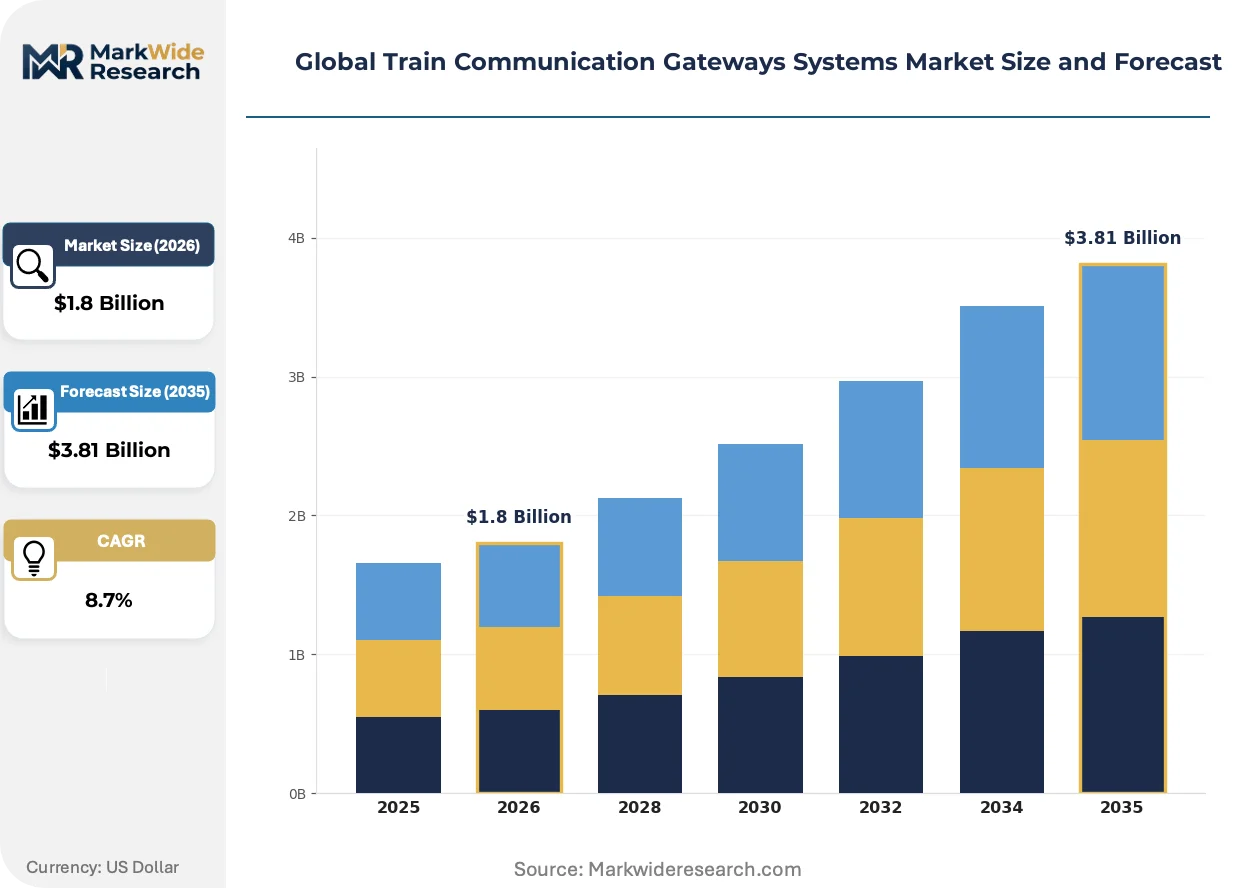
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onboard Communication, Ground Communication, Trackside Units, Network Interface Technology: GSM-R, LTE, Wi-Fi, Ethernet End User: Rail Operators, Government Agencies, Freight Transporters, Maintenance Providers Application: Passenger Services, Freight Management, Safety Systems, Remote Monitoring |
| Companies Covered | Duagon AG, EKE-Electronics Ltd, Quester Tangent, AMiT Transportation, SYS TEC electronic, SAIRA Electronics, Advantech Co., Ltd., Ingeteam, HaslerRail AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Train Communication Gateways Systems Market Strategic Shifts
Gateway hardware is evolving from passive protocol translators to active edge-computing nodes capable of local inference and fleet-wide orchestration. This shift redefines supplier value capture toward software-enabled recurring revenue.
Ethernet train bus technology is overtaking legacy MVB and WTB fieldbus architectures in new-build contracts. European high-speed operators including Deutsche Bahn and SNCF Voyageurs are specifying pure-Ethernet backbone networks for 2027+ fleet deliveries. This transition is compressing gateway supplier margins on legacy protocol support while expanding attach rates for cybersecurity and AI acceleration modules.
The EU AI Act imposes mandatory algorithmic transparency requirements on automated train operation systems processing passenger safety data. Gateway vendors must now document decision pathways for obstacle classification and emergency braking triggers. Safety Systems applications face the steepest compliance burden, with German TSI certification bodies expanding audit scope to cover AI model provenance.
Freight operators are unbundling gateway hardware from long-term service contracts, reversing prior bundled procurement patterns. North American Class I railroads now separate capital equipment acquisition from predictive maintenance subscriptions, pressuring OEMs to compete on standalone software value. This disintermediation is most pronounced in Union Pacific and BNSF corridor modernization programs, where third-party diagnostic platforms are displacing manufacturer-captive service agreements.
Global Train Communication Gateways Systems Market Segmentation
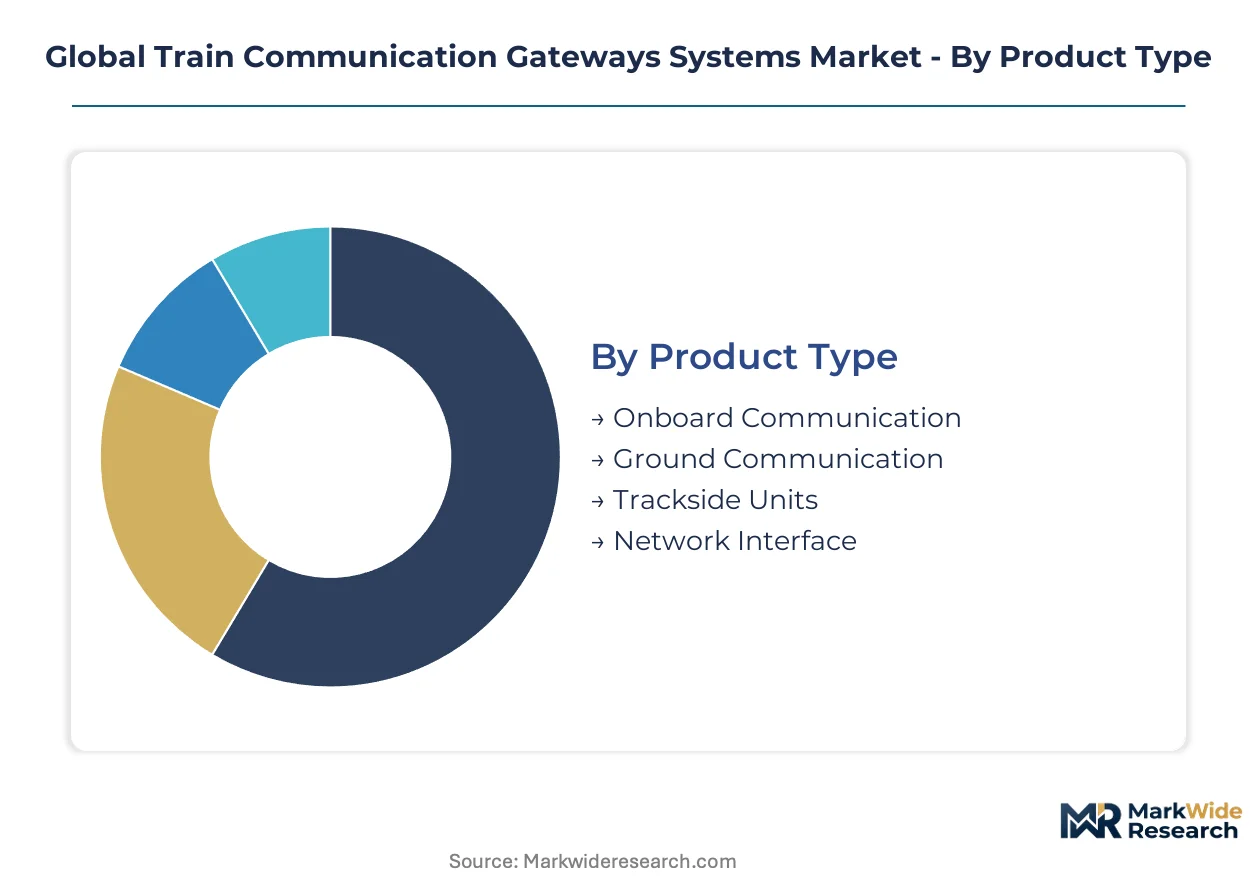
Gateway procurement patterns diverge sharply between rolling-stock lifecycle mandates and infrastructure upgrade cycles. Segmentation reveals how protocol migration, regulatory deadlines, and service contract unbundling reshape supplier priorities across hardware and software boundaries.
Product Type:
Ethernet train bus specifications are redefining hardware form factors and firmware architectures across all product categories.
- Onboard Communication:Ruggedized network bridge hardware with IEC 61375-3-4 protocol translation dominates new-build rolling-stock contracts. Deutsche Bahn ICE fleet modernization in Germany drives replacement demand as lifecycle mandates collide with Ethernet migration timelines.
- Ground Communication:Station-to-train data handoff systems enable fleet-wide orchestration and predictive maintenance platforms. North American freight corridors concentrate investment here as Union Pacific and BNSF unbundle hardware from service subscriptions.
- Trackside Units:Wayside protocol gateways bridge vehicle networks with signaling infrastructure.
- Network Interface:Modular connection modules for subsystem integration in retrofit programs.
Mature deployment sits with Onboard Communication. Newer deployment is concentrated in Ground Communication.
Technology:
Radio spectrum reallocation and fieldbus displacement are compressing technology transition windows.
- Ethernet:IEC 61375-3-4 standardized train bus architectures displace legacy MVB and WTB in European high-speed fleets. SNCF Voyageurs specifications for 2027+ deliveries anchor pure-Ethernet backbone adoption, expanding attach rates for cybersecurity modules.
- GSM-R:Legacy rail-specific mobile radio faces ETSI-mandated spectrum transition timelines across EU member states. Installed base entrenchment in Central European commuter networks creates substitution friction despite obsolescence pressure.
- LTE:Commercial cellular protocols enable train-to-ground broadband in freight corridors.
- Wi-Fi:Passenger-facing onboard connectivity systems with limited safety-critical application.
Technology margins compress fastest in GSM-R. Value capture is climbing the fastest in Ethernet.
End User:
Procurement consolidation among national carriers contrasts with fragmentation across private logistics networks.
- Rail Operators:Deutsche Bahn, SNCF, and joint venture structures in Europe bundle gateway replacement with climate-system retrofits triggered by EU F-Gas Regulation mandates. Consolidated purchasing power pressures standalone hardware pricing.
- Freight Transporters:North American Class I railroads and Asian private logistics consortia fragment demand across corridor-specific specifications. Predictive maintenance contract unbundling creates standalone software competition.
- Government Agencies:Regulatory procurement for interoperability certification and standards compliance.
- Maintenance Providers:Third-party diagnostic platforms displacing manufacturer-captive service agreements.
Contract volume concentrates with Rail Operators. Procurement flexibility is expanding most quickly among Freight Transporters.
Application:
Safety certification requirements and AI transparency mandates are stratifying application-tier pricing.
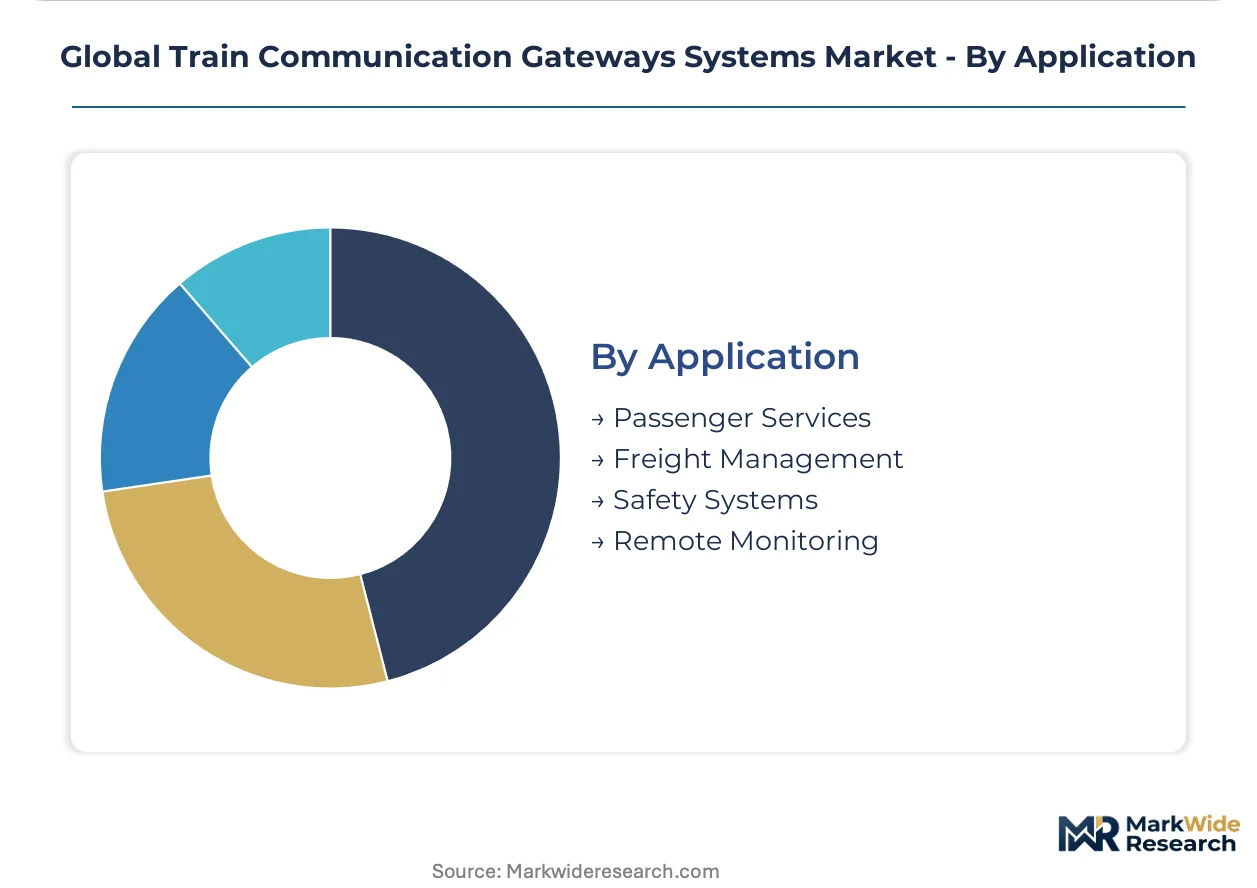
- Safety Systems:SIL 4-certified brake-control and obstacle-detection gateways command premium pricing through extended validation cycles. EU AI Act algorithmic transparency requirements expand German TSI certification audit scope to cover AI model provenance.
- Remote Monitoring:Predictive maintenance platforms with edge-AI inference engines enable millisecond-latency diagnostics. Private 5G rail network integration in high-speed rolling stock drives fastest expansion.
- Passenger Services:Information and entertainment system gateways with lower certification burden.
- Freight Management:Cargo tracking and fleet optimization across distributed logistics networks.
Certification complexity peaks in Safety Systems. Revenue expansion is steepest in Remote Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German rail procurement concentrates gateway demand through Deutsche Bahn's consolidated fleet modernization mandates. Fragmented freight corridors across North America and Asia-Pacific distribute volume across competing logistics consortia.
Germany
Deutsche Bahn's ICE fleet replacement cycles and F-Gas Regulation compliance deadlines compress procurement timelines for climate-system retrofits. KBA vehicle certification requirements extend to gateway protocol interoperability under revised TSI standards. Munich and Nuremberg manufacturing clusters host subsystem integrators bundling Ethernet migration with HVAC overhauls.
United States
Class I railroads including Union Pacific and BNSF unbundle gateway hardware from predictive maintenance subscriptions across western freight corridors. FRA Positive Train Control interoperability standards mandate protocol compatibility for automated braking systems. Chicago and Omaha logistics hubs concentrate third-party diagnostic platform deployment.
France
SNCF Voyageurs specifications for 2027+ high-speed deliveries anchor pure-Ethernet backbone adoption. ANSM and CNIL oversight extends to AI algorithmic transparency for obstacle detection gateways under EU AI Act implementation. Île-de-France commuter networks face substitution friction from legacy MVB entrenchment.
India
Dedicated Freight Corridor Corporation procurement specifications create first-mover positioning for hybrid Ethernet-MVB gateway suppliers across eastern and western dedicated corridors. Indian Railways electrification targets and BIS rolling-stock standards accelerate digitization timelines. Gujarat and Maharashtra industrial corridors concentrate manufacturing localization efforts.
Japan
Shinkansen fleet renewal programs and METI industrial standards drive gateway replacement in high-speed rolling stock. JIS certification requirements and cybersecurity frameworks for critical infrastructure apply to train-to-ground communication systems. Nagoya and Osaka manufacturing basins host subsystem suppliers integrating edge-AI inference modules.
Global Train Communication Gateways Systems Market Competitive Environment
German producers anchor one tier of protocol-specialist suppliers; Taiwanese industrial computing fabricators hold scale-driven positions in ruggedized hardware. Market structure tilts toward consolidation among national-carrier procurement channels while fragmenting across private freight networks. Three archetypes dominate: IEC 61375 protocol specialists, industrial edge-computing platforms, and safety-certified subsystem integrators. Dominant competitive moves include backward integration into FPGA sourcing and geographic expansion through joint venture structures.
Within the protocol-specialist tier, Duagon AG and EKE-Electronics Ltd occupy positions anchored in European rail certification ecosystems. Advantech Co., Ltd. exemplifies the industrial computing archetype extending ruggedized platform expertise into rolling-stock applications. These three entities represent distinct strategic vectors: Duagon AG through Central European retrofit program anchoring, EKE-Electronics Ltd through Nordic R&D intensity, and Advantech Co., Ltd. through East Asian corridor penetration.
| Leading Market Players |
|---|
| Duagon AG |
| EKE-Electronics Ltd |
| Quester Tangent |
| AMiT Transportation |
| SYS TEC electronic |
| SAIRA Electronics |
| Advantech Co., Ltd. |
| Ingeteam |
| HaslerRail AG |
| Others |
Value Chain & Pricing Dynamics
Industrial-grade FPGA and ruggedized Ethernet PHY component indices cascade through three pricing tiers, compressing margins on legacy MVB protocol support while expanding premium capture for IEC 61375-3-4 Ethernet gateway modules bundled with cybersecurity firmware.
Pricing Analysis
High-volume Onboard Communication hardware trades at compressed margins against low-volume Safety Systems gateways carrying SIL 4 certification premiums. Price differentiation hinges on certification grade and after-sales service bundling, with predictive maintenance subscriptions now unbundled from hardware in North American freight corridors. Cost compression in standard-tier Ethernet bridges is intensifying because Taiwanese foundry concentration exposes lead-time volatility. Freight transporters exhibit highest price sensitivity; European national rail operators tolerate premium pricing for regulatory compliance.
Supply Chain Analysis
Regional distribution centers in Germany, Taiwan, and Japan orchestrate hub-and-spoke fulfillment patterns for gateway hardware destined to rolling-stock OEMs and subsystem integrators. Manufacturing draws from Taiwanese FPGA foundries, German precision component suppliers, and Japanese industrial Ethernet module producers. Single-source vulnerability concentrates in ruggedized semiconductor sourcing from Taiwan. Distribution runs through captive logistics networks serving Deutsche Bahn, SNCF, and North American Class I railroad maintenance depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
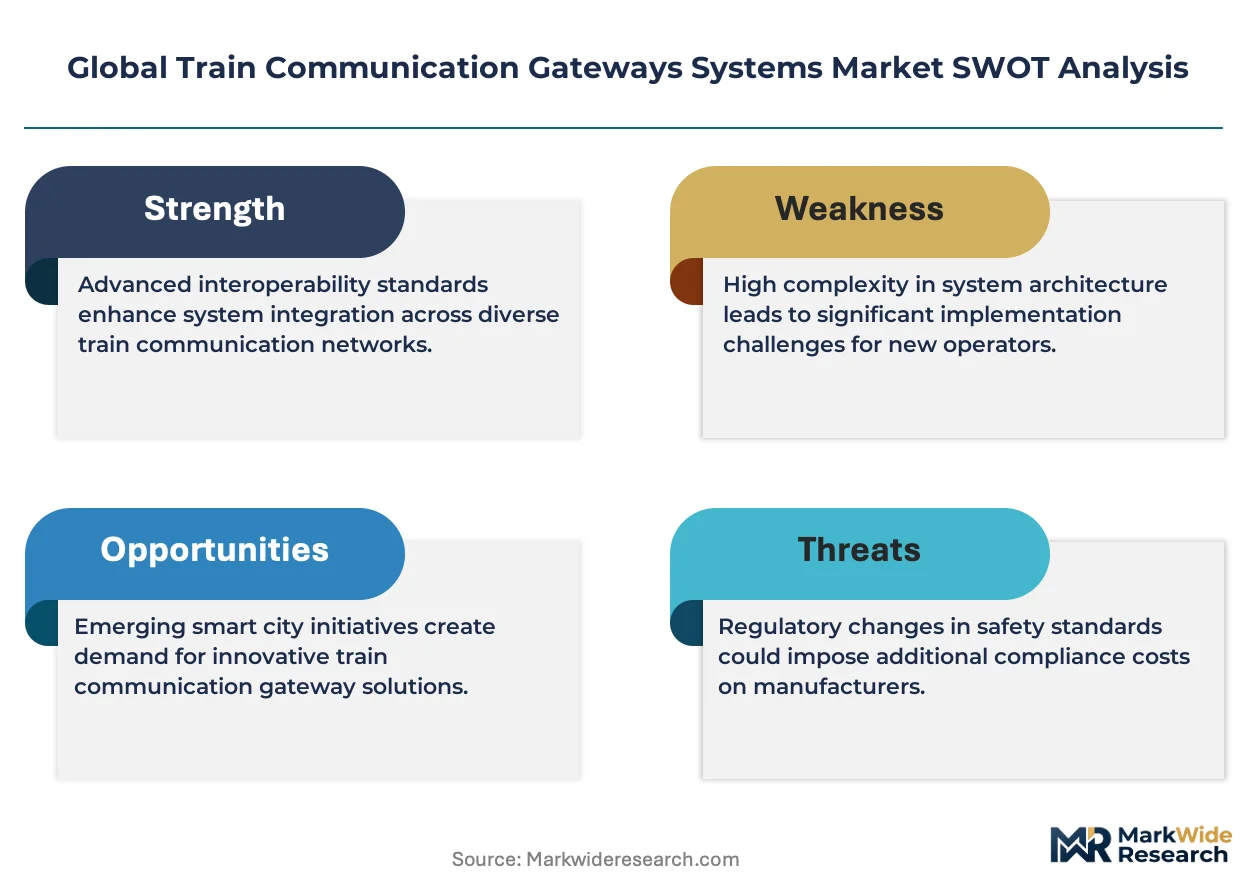
This market consolidates around protocol specialists with IEC 61375 certification ecosystems, as EU AI Act compliance costs force subscale competitors toward exit or acquisition.
For Market Incumbents:To counter Ethernet migration margin compression, anchor retrofit program relationships through backward integration into FPGA sourcing and expand TSI certification audit capabilities for AI-enabled Safety Systems gateways. Lock in Deutsche Bahn and SNCF Voyageurs through multi-fleet service contracts spanning climate-system retrofits.
For New Entrants and Emerging Players:The EU AI Act in Germany and France opens a window for explainable AI module specialists to penetrate automated train operation gateway segments with pre-certified algorithmic transparency. Target Indian Dedicated Freight Corridor Corporation procurement as the most penetrable geography, positioning through hybrid Ethernet-MVB designs. Lead with edge-AI inference engines bundled with private 5G rail network integration.
For Investors and Strategic Acquirers:Distressed-cycle entries favor IEC 61375 protocol specialists with captive Central European retrofit channels and stranded R&D assets in Nordic markets. Long-term viability centers on software-enabled recurring revenue attach rates rather than standalone hardware volume. Watch for SNCF 2027+ fleet specification finalization as inflection signal for pure-Ethernet backbone adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61375-3-4 Certification Investment | TSI audit scope expansion in Germany locks in Deutsche Bahn replacement cycles. |
| Edge-AI Module Development | EU AI Act algorithmic transparency mandates create premium pricing for pre-certified gateways. |
| Backward Integration into FPGA Sourcing | Taiwanese foundry concentration risk drives captive supply strategies for margin defense. |
| Predictive Maintenance Platform Launch | Union Pacific and BNSF unbundling patterns favor standalone software revenue models. |
| Joint Venture in Indian Freight Corridors | Dedicated Freight Corridor Corporation specifications reward localized manufacturing partnerships. |
Study Parameters
Regulatory filings from ETSI, KBA, and FRA, rolling-stock procurement databases, and IEC standard documentation formed the secondary backbone. Primary interviews with Deutsche Bahn procurement directors, SNCF systems integration engineers, North American Class I railroad maintenance heads, Taiwanese industrial computing OEMs, and Indian Dedicated Freight Corridor Corporation technical officers validated demand assumptions. Bottom-up fleet replacement modeling and top-down rail operator capex analysis provided triangulation.
Historical trendline analysis of gateway replacement cycles, Ethernet migration adoption curves, and predictive maintenance contract penetration informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology protocol, end-user archetype, and application tier with SIL certification grade. CAGRs derived from rolling-stock lifecycle mandates, regulatory deadline clustering, and service contract unbundling velocity. Forecast inputs incorporated EU F-Gas Regulation compliance timelines and ETSI GSM-R spectrum transition schedules.
The model assumes a particular technology adoption path; alternative pathways for Ethernet train bus displacement of MVB would alter the outlook. Forecasts reflect stated assumptions around IEC 61375-3-4 implementation uniformity, semiconductor supply normalization, and AI Act audit scope interpretation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Fishplate Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Rail Pads Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Autonomous Train Technology Market