
 Railway Traction Inverter Market | 2026-2036
Railway Traction Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Traction Inverter Market Analytics
The EU Green Deal is expanding electrification mandates across European rail networks, compelling operators to replace diesel-hauled services with electric traction. Siemens AG leverages its integrated drive systems to dominate European retrofit programs. ABB Ltd anchors its position through high-power modular platforms engineered for interoperability across national grids. Mitsubishi Electric Corporation specializes in SiC traction inverters that reduce energy losses on Japan's Shinkansen routes.
A railway traction inverter converts DC or single-phase AC line power into variable-frequency three-phase AC for driving traction motors, typically handling power levels from hundreds of kilowatts to multiple megawatts with switching frequencies between 500 Hz and 2 kHz depending on semiconductor technology. SiC inverters are displacing conventional IGBT platforms in premium segments where efficiency gains justify higher semiconductor costs. Among end users, high-speed rail commands the largest installed base while light rail transit represents the fastest upgrade cycle as cities electrify urban corridors. Voltage source inverter technology leads volume shipments due to its mature control algorithms and broad supplier ecosystem.
The EU's F-Gas Regulation and Ecodesign directives constrain coolant choices and energy efficiency thresholds for traction power equipment. China's GB standards and MIIT railway equipment certifications shape product specifications for the world's largest rolling stock procurement market. The US Federal Railroad Administration and EPA locomotive emission rules are tightening compliance windows for freight operators considering diesel-to-electric conversions. Stakeholders must weigh semiconductor supply security against technology migration timelines when committing to next-generation traction platforms.
Market Dynamics
The transition from silicon IGBT to silicon carbide traction inverters is restructuring competitive economics across rail electrification programs, compressing energy losses while elevating semiconductor supply security to strategic priority status for procurement teams.
Growth Catalysts
- EU Green Deal transport mandates:Binding electrification targets for cross-border rail corridors are accelerating diesel-to-electric fleet conversions across member states.
- Urban light rail expansion:Municipal transit authorities in China, Germany, and France are procuring battery-electric multiple units requiring compact, high-efficiency traction inverters.
- SiC semiconductor maturation:Yield improvements at wafer fabrication facilities are narrowing the cost gap against conventional silicon platforms for high-power applications.
Market Restraints
- Concentrated SiC substrate supply:Wolfspeed, Coherent, and ROHM control the majority of 150mm SiC wafer capacity, creating single-source vulnerability for inverter manufacturers.
- Extended qualification timelines:Railway-specific EN 50155 and IEC 61215 certification cycles stretch 18-24 months, freezing design iterations for rolling stock programs.
- Copper and rare earth price volatility:Traction motor windings and permanent magnet materials face commodity swings that compress inverter-motor system margins.
Strategic Opportunities
- Freight corridor electrification in India:Dedicated freight corridors and the Ministry of Railways' net-zero targets are opening procurement windows for 25kV AC traction systems.
- Interoperability standardization:The EU's Shift2Rail and subsequent Europe's Rail Joint Undertaking are harmonizing traction control interfaces across national networks.
- Digital twin integration:Predictive maintenance platforms fused with inverter health monitoring are creating recurring revenue streams for system integrators.
Industry Challenges
- Power electronics engineering scarcity:Specialized expertise in high-voltage packaging and thermal management for rail environments commands premium compensation and extends hiring cycles.
- Legacy fleet retrofit complexity:Mechanical clearances and cooling system architectures from 1980s-1990s rolling stock constrain drop-in inverter replacements without structural modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Traction Inverter Market |
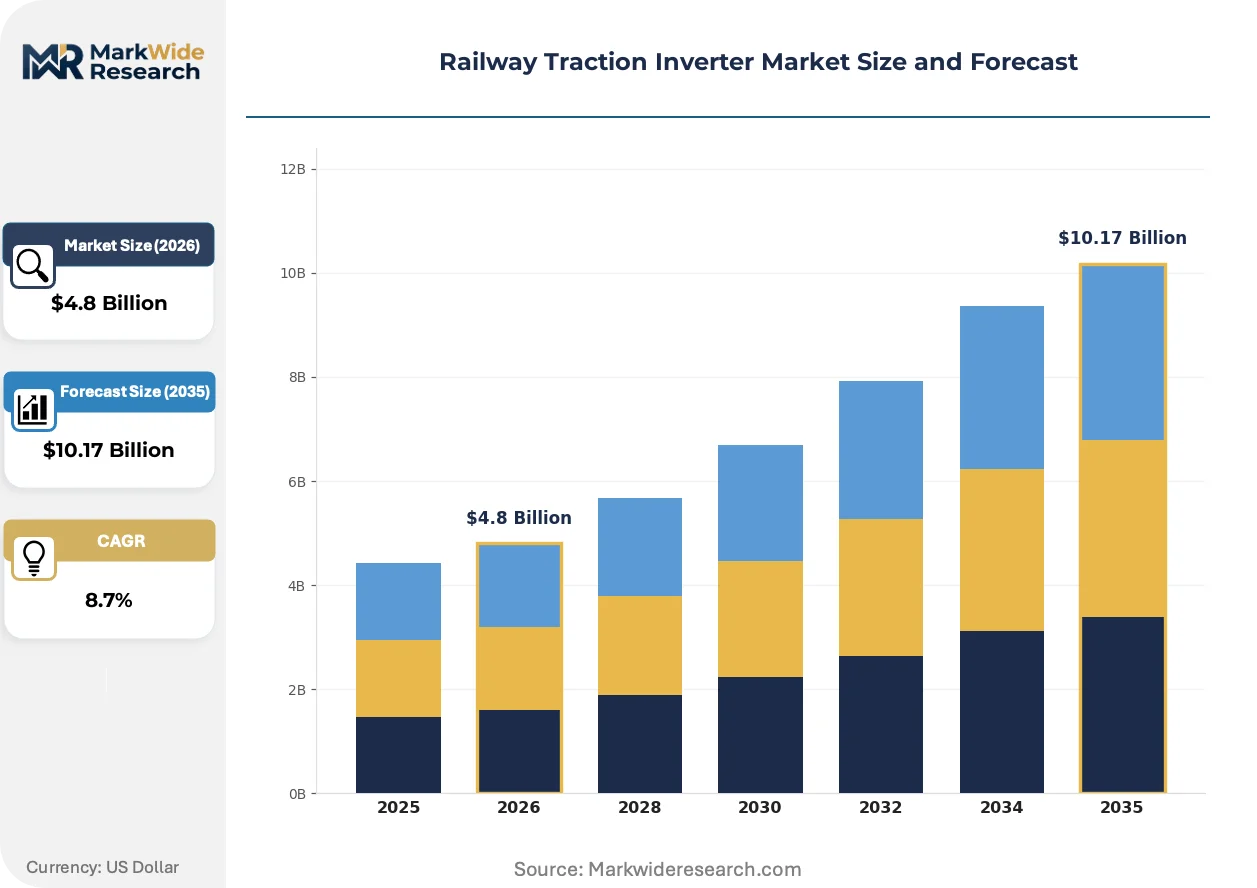
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Inverter, Integrated Inverter, SiC Inverter, IGBT Inverter End User: Public Transport, Freight Transport, High-Speed Rail, Light Rail Transit Installation: Stationary, Mobile, Fixed, Permanent Technology: Voltage Source Inverter, Current Source Inverter, PWM Inverter, Resonant Converter |
| Companies Covered | Siemens AG, ABB Ltd, Mitsubishi Electric Corporation, Alstom SA, Hitachi Ltd, CRRC, Toshiba Corporation, Schneider Electric, Voith GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Traction Inverter Market Evolving Landscape
Silicon carbide traction technology is rewriting efficiency benchmarks while regulatory pressure on coolant chemistries and thermal management compounds design complexity. Digitalization of maintenance protocols is simultaneously reshaping supplier-customer relationships.
Silicon carbide MOSFETs replace silicon IGBTs in traction inverter power modules, cutting switching losses by half compared to conventional platforms. High-speed rail operators in Japan and China are deploying SiC-based systems on new Shinkansen and Fuxing trainsets. This semiconductor transition is decentralizing thermal management architecture, enabling air-cooled designs that eliminate heavy water-glycol loops and reduce overall system mass.
The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in traction inverter cooling systems, compelling manufacturers to adopt CO2 or propane-based alternatives. Inverter suppliers must redesign heat exchangers and pressure vessels to accommodate lower-GWP coolants under tighter safety envelopes. European retrofit programs and new rolling stock procurements face the steepest compliance cost adjustments as 2024-2030 reduction targets tighten.
Performance-based maintenance contracts are displacing traditional time-based service agreements for traction power equipment. Rolling stock operators in France and Germany now specify availability guarantees and energy consumption thresholds rather than component replacement schedules. This contractual evolution concentrates risk with inverter manufacturers while rewarding predictive analytics capabilities and remote diagnostic infrastructure investments.
Railway Traction Inverter Market Segmentation
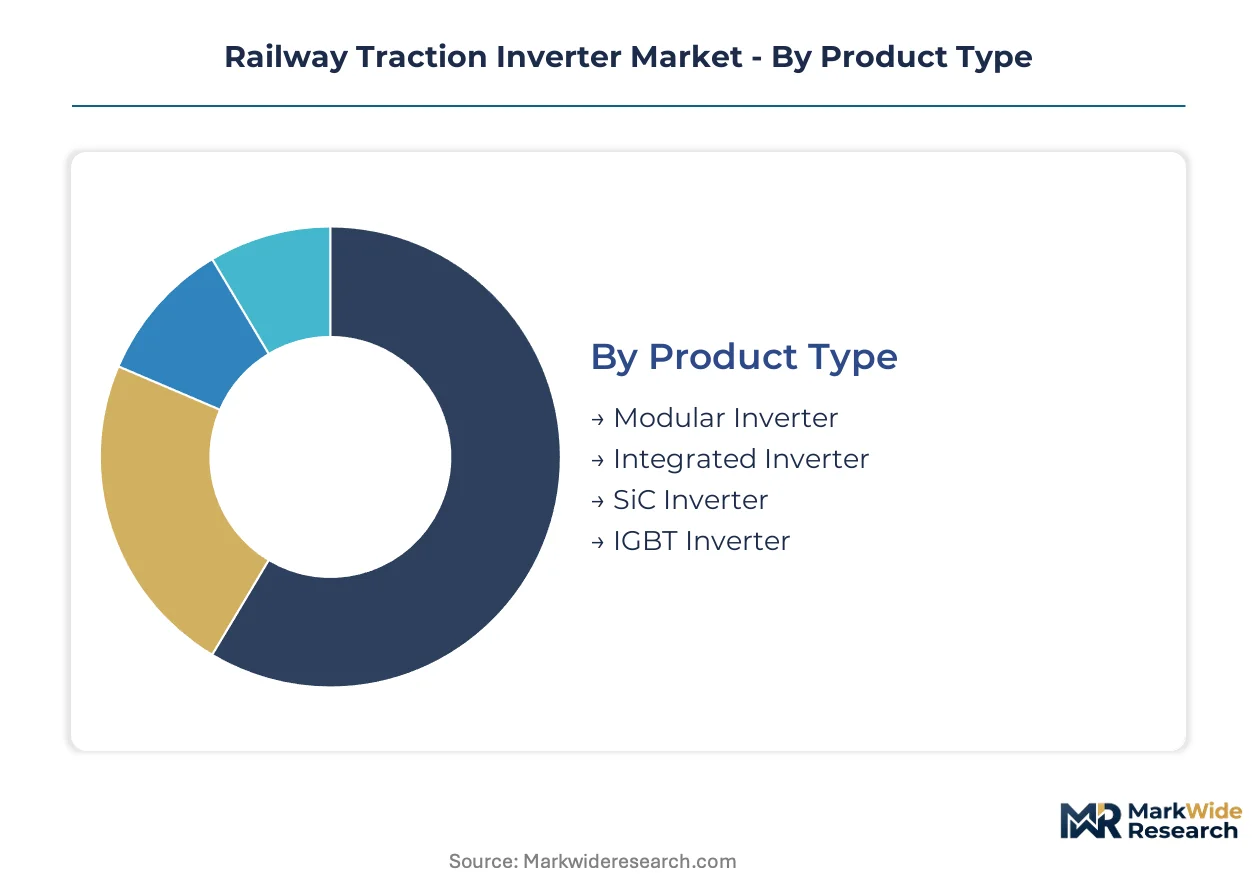
Railway traction inverters serve divergent operational regimes—from fixed substations feeding catenary networks to onboard systems enduring vibration and thermal cycling. Segment boundaries reflect these environmental distinctions alongside semiconductor technology choices that determine efficiency ceilings and procurement economics.
Product Type:
Customization intensity varies sharply across this category, with modular platforms offering configurability for mixed fleets while integrated systems sacrifice flexibility for space and weight optimization.
- Modular Inverter:Standardized power blocks assemble into scalable configurations supporting 500kW to 3MW outputs. European retrofit programs favor this architecture for phased diesel-to-electric conversions across heterogeneous rolling stock.
- SiC Inverter:Silicon carbide MOSFETs slash switching losses versus silicon IGBTs, enabling air-cooled designs that eliminate water-glycol loops. Japan's Shinkansen operators and China's CRRC deploy these systems where energy efficiency justifies semiconductor cost premiums.
- Integrated Inverter:Compact motor-drive units merge power electronics with traction motors in sealed enclosures. Urban metro operators specify these for space-constrained underfloor mounting.
- IGBT Inverter:Mature silicon insulated-gate bipolar transistor technology dominates installed base maintenance and cost-sensitive procurement tenders.
Most installed capacity flows through IGBT Inverter systems. Expansion is steepest in SiC Inverter platforms.
End User:
Volume concentration clusters around passenger services, though freight electrification timelines are compressing as diesel emission regulations tighten.
- High-Speed Rail:Traction systems handle 5-10MW per trainset with regenerative braking energy recovery exceeding 15% of consumption. China's expanding Fuxing fleet and Japan's N700S Shinkansen procurement anchor demand.
- Light Rail Transit:Battery-electric multiple units require compact, high-power-density inverters for catenary-free operation. Municipal authorities in France and Germany specify these for urban corridor electrification.
- Public Transport:Commuter and regional rail services prioritize reliability and interoperability across national networks.
- Freight Transport:Heavy-haul locomotives demand ruggedized inverters with extended thermal envelopes for sustained high-torque operation.
High-Speed Rail absorbs the largest procurement volumes. Light Rail Transit is climbing the fastest as cities accelerate decarbonization timelines.
Installation:
Margin profiles diverge between stationary infrastructure with decade-long depreciation and mobile systems subject to shock, vibration, and accelerated wear.
- Mobile:Onboard traction inverters endure EN 61373 Category 1 vibration standards and temperature swings from -40°C to +70°C. Rolling stock OEMs integrate these into bogie-mounted or roof-mounted packages.
- Stationary:Wayside inverters feed third-rail or overhead catenary systems with maintenance access and climate-controlled enclosures. Metro operators in India deploy these for depot charging of battery-electric multiple units.
- Fixed:Permanent trackside installations with dedicated foundations and grid interconnection infrastructure.
- Permanent:Embedded infrastructure with 30-40 year asset lifecycles and minimal reconfiguration flexibility.
Mobile installations carry the steepest qualification burdens. Stationary systems are gaining share fastest in emerging electrification corridors.
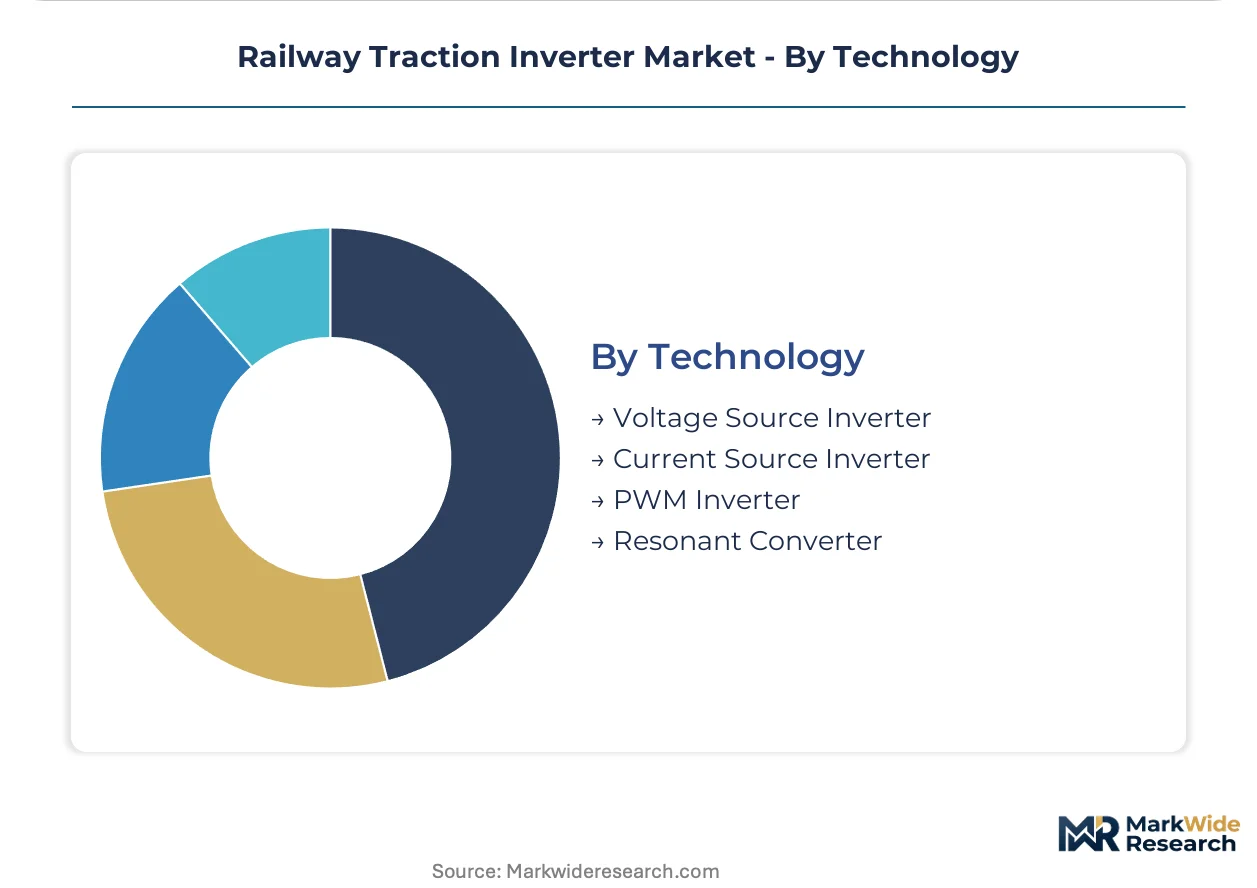
Technology:
Control algorithm maturity and supplier ecosystem breadth create adoption friction that favors established topologies over emerging architectures.
- Voltage Source Inverter:DC-link capacitors feed three-phase bridge topologies with mature space-vector modulation. This architecture commands dominant volume through proven reliability and broad component availability.
- PWM Inverter:Carrier-based pulse-width modulation enables precise torque control for induction and permanent-magnet synchronous motors. European traction suppliers standardize on this approach for interoperability across national grid frequencies.
- Current Source Inverter:Inductor-based DC links with thyristor or symmetrical gate-commutated thyristor switching persist in legacy high-power applications.
- Resonant Converter:Soft-switching topologies reduce electromagnetic interference for sensitive signaling environments, though magnetic component costs constrain adoption.
Voltage Source Inverter platforms carry the dominant installed base. PWM Inverter configurations are expanding most quickly in digitally-controlled traction systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Railway electrification traces its industrial lineage to Germany's pioneering 16.7 Hz systems and Japan's post-war Shinkansen development, with contemporary manufacturing and procurement now distributed across specialized national clusters.
Germany
Deutsche Bahn's fleet modernization and cross-border corridor electrification sustain demand for high-power traction systems. The EU Green Deal's binding transport decarbonization targets mandate diesel phase-out timelines through 2035. Siemens AG anchors industrial activity in Bavaria and Berlin-Brandenburg, supplying integrated drive systems for European retrofit programs.
China
CRRC and state rail operators drive procurement volume for expanding high-speed rail corridors spanning 45,000 route-kilometers. MIIT railway equipment certifications and GB standards shape product specifications for domestic and export markets. Qingdao and Changchun manufacturing clusters concentrate rolling stock production with captive inverter supply chains.
Japan
East Japan Railway and Central Japan Railway operate the world's densest high-speed network with continuous rolling stock renewal cycles. METI technology roadmaps prioritize SiC semiconductor adoption for energy efficiency gains. Nagoya and Kobe industrial zones host precision manufacturing of traction power electronics for Shinkansen and export markets.
India
Dedicated freight corridors and Ministry of Railways net-zero targets open procurement windows for 25kV AC traction systems. CEA grid codes and RDSO specifications govern equipment qualification for domestic manufacturing. Gujarat and Maharashtra industrial corridors attract component localization investments under PLI scheme incentives.
France
SNCF Réseau's catenary modernization and battery-electric multiple unit trials reshape traction system requirements. ANSM rail safety oversight and EU Ecodesign directives constrain coolant choices and efficiency thresholds. Île-de-France and Auvergne-Rhône-Alpes clusters concentrate Alstom's manufacturing and systems integration capabilities.
Railway Traction Inverter Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and certification depth, with SiC-based platforms commanding pricing separation from conventional IGBT systems. The vendor base organizes into three strategic archetypes: diversified industrial conglomerates with captive rail divisions, specialized traction power electronics houses, and state-affiliated rolling stock manufacturers with vertical integration into drive systems. Dominant competitive moves include strategic partnerships for semiconductor supply security and geographic expansion through local content requirements in emerging electrification corridors.
Among diversified European industrial groups, Siemens AG and ABB Ltd occupy positions exemplifying integrated platform strategies, while Mitsubishi Electric Corporation represents the specialized precision electronics archetype with deep heritage in high-speed rail applications. These three anchors demonstrate how competitive positioning stratifies across technology generation, geographic footprint, and customer relationship depth in electrification procurement cycles.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Mitsubishi Electric Corporation |
| Alstom SA |
| Hitachi Ltd |
| CRRC |
| Toshiba Corporation |
| Schneider Electric |
| Voith GmbH & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EN 50155-compliant premium systems and commodity IGBT platforms manifests in both procurement economics and semiconductor sourcing configurations, with SiC-based traction inverters commanding semiconductor cost premiums that compress margins for suppliers locked into silicon supply chains.
Pricing Analysis
Three-tier pricing structure across premium SiC, standard IGBT modular, and economy integrated systems dominates procurement negotiations, with price differentiation anchored in semiconductor technology grade and EN 50155 certification depth. Cost compression in economy-tier integrated inverters is intensifying because Chinese rolling stock OEMs are internalizing drive system production. Freight operators exhibit the highest price sensitivity due to thin operating margins, while high-speed rail authorities prioritize energy efficiency over upfront capital expenditure.
Supply Chain Analysis
Freight costs for 150mm SiC wafers from Wolfspeed's New York fabrication complex and Coherent's Swedish facilities elevate landed costs for European and Asian inverter manufacturers. Semiconductor feedstock draws from the United States, Japan, and Germany, with copper busbar and rare earth magnet dependencies feeding from China and Australia. Single-source vulnerability concentrates around Wolfspeed's substrate capacity. Distribution runs through rolling stock OEM captive supply chains and authorized systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's binding diesel phase-out mandates through 2035 compound electrification procurement timelines, creating regulatory-driven demand acceleration that rewards early certification investments and penalizes lagging suppliers.
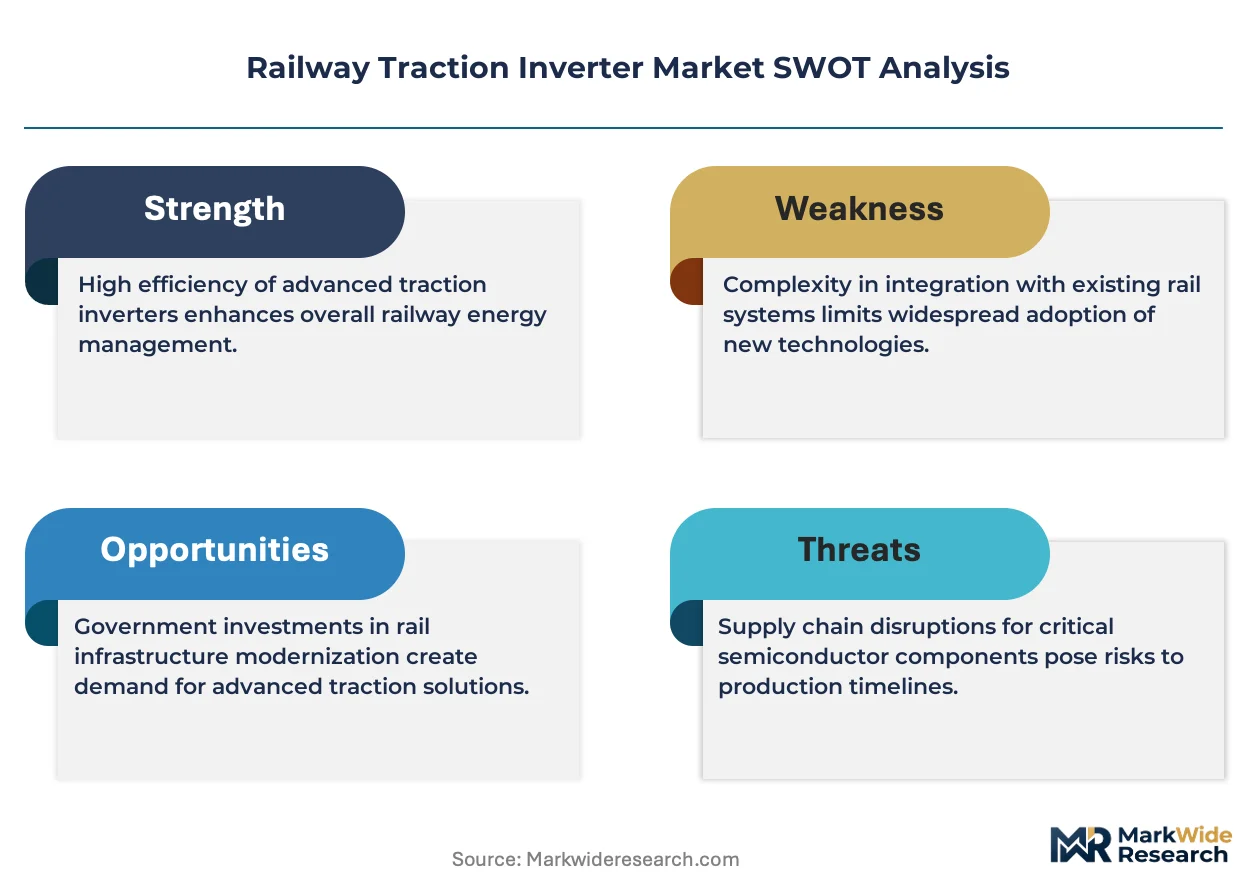
For Market Incumbents: Hedge SiC supply security through multi-year offtake agreements with Wolfspeed, Coherent, and ROHM before wafer allocation tightens further. Reinforce position in European retrofit programs by accelerating EN 50155 certification for air-cooled SiC platforms that eliminate water-glycol maintenance burdens. Channel control through performance-based maintenance contracts concentrates customer switching costs.
For New Entrants and Emerging Players: The premium-to-economy price gap in India's dedicated freight corridor electrification opens procurement windows for cost-optimized 25kV AC traction systems that undercut European incumbents. Target battery-electric multiple unit inverters for French and German municipal transit authorities seeking catenary-free urban solutions. Go-to-market through PLI scheme partnerships with Gujarat and Maharashtra manufacturing clusters accelerates domestic qualification.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized traction power electronics houses possessing SiC packaging expertise and active railway certification pipelines. Long-term viability over the next decade hinges on semiconductor technology transition completion and aftermarket service contract penetration. Watch for inflection when Indian freight corridor procurement volumes cross threshold levels that justify dedicated local assembly investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year SiC Wafer Offtake Agreement | Secures substrate allocation from Wolfspeed and Coherent against supply rationing. |
| Air-Cooled Platform Certification | Eliminates water-glycol maintenance for EU F-Gas Regulation compliance. |
| Performance-Based Maintenance Contract | Shifts revenue from component sales to availability guarantees with SNCF and Deutsche Bahn. |
| Indian Manufacturing Localization | Captures PLI scheme incentives for dedicated freight corridor traction system assembly. |
| Predictive Maintenance Platform Integration | Fuses inverter health monitoring with digital twin infrastructure for recurring revenue. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rolling stock procurement directors, traction power electronics engineering leads, semiconductor supply chain managers, and railway operator maintenance heads with secondary validation against SEC filings, MIIT railway equipment certification databases, EU Shift2Rail program documentation, and customs trade data for power semiconductor imports. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates.
Historical reference periods anchored the forecast window to installed base replacement cycles and announced rolling stock procurement programs across the projection horizon. Segmentation modeling incorporated product type, end user category, installation environment, and semiconductor technology generation dimensions. CAGRs derived from regression analysis of electrification investment correlations with regulatory milestone timelines, incorporating CRRC production forecasts and Japanese Shinkansen renewal schedules as traction system demand inputs.
Caveats apply where SiC substrate yield improvements, EU F-Gas Regulation enforcement intensity, or Indian freight corridor commissioning delays could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Railway Connectors Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Digital Railway Market
Railway Transportation
Rail Pads Market