
 Rail Gangways Market | 2026-2036
Rail Gangways Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Gangways Market Analysis
China's manufacturing capacity build-out is reshaping competitive dynamics in rail gangway supply. HÜBNER GmbH & Co. KG leverages its European engineering heritage to dominate premium intercity contracts. Dellner Couplers anchors Nordic and Baltic markets through specialized coupler-integrated gangway systems. Hutchinson Group extends its polymer expertise into lightweight composite gangways for high-speed applications.
Rail gangways are articulated passageway assemblies connecting railway vehicles, typically fabricated from extruded aluminum profiles, elastomeric bellows, and reinforced flooring rated for passenger loads exceeding specific density thresholds. Their primary function ensures safe inter-car movement while maintaining environmental sealing and crash energy management. Bi-directional configurations lead in metro and commuter deployments where turnaround efficiency matters, while composite materials represent the fastest-expanding material class as operators pursue mass reduction targets. Rigid gangways still occupy the majority of high-speed rail contracts due to aerodynamic stability requirements and lower maintenance cycles.
Europe's EBA and EN standards, alongside China's NRA technical specifications and the US FRA safety mandates, collectively elevate barrier strength, fire resistance, and accessibility compliance across procurement specifications. These frameworks effectively restrict market access for uncertified suppliers and accelerate replacement cycles in aging fleets. Stakeholders must monitor evolving crashworthiness benchmarks and material qualification protocols to align R&D roadmaps with forthcoming certification requirements.
Market Dynamics
Crashworthiness mandates from European and Chinese regulators are compressing design cycles and forcing material upgrades across the rail gangway supply base. EN 15227 and NRA technical specifications now require energy-absorbing structures that exceed legacy aluminum extrusion capabilities.
Growth Catalysts
- Urban Metro Expansion:Asia-Pacific operators are procuring high-capacity fleets to address congestion corridors. Bi-directional gangway configurations dominate these contracts for turnaround efficiency.
- EN 15227 Mandates:European crashworthiness standards require reinforced gangway structures with elastomeric energy absorbers. Fleet operators face accelerated replacement cycles for non-compliant rolling stock.
- Composite Material Adoption:Lightweight polymer gangways are penetrating high-speed rail tenders. Mass reduction targets from operators are displacing traditional aluminum bellows in premium segments.
Market Restraints
- Aluminum Price Volatility:Extruded profile feedstock costs fluctuate with energy-intensive smelting economics. Gangway fabricators face margin compression during input spikes.
- Certification Concentration:European Notified Bodies and China's NRA dominate type-approval pathways. Uncertified suppliers face structural exclusion from tender participation.
- Rigid Gangway Lock-in:Aerodynamic stability requirements on high-speed corridors limit flexible bellows adoption. Composite alternatives struggle to match the maintenance cycles of rigid assemblies.
Strategic Opportunities
- Indian Subcontinent Penetration:Metro construction in Delhi, Mumbai, and Bangalore creates demand for standardized gangway platforms. Domestic manufacturing incentives lower import dependency.
- Digital Twin Integration:Predictive maintenance algorithms converge with sensor-embedded gangways. Real-time structural monitoring enables condition-based replacement scheduling.
- Accessibility Mandates:US FRA and European PRM-TSI requirements favor low-floor gangway designs. Tenders increasingly specify wheelchair-compatible passage widths and tactile guidance systems.
Industry Challenges
- Welding Certification Scarcity:EN 15085-qualified aluminum welders are concentrated in Central European labor pools. Fabricators face recruitment bottlenecks for qualified assembly technicians.
- Multi-Standard Compliance:Simultaneous EN, FRA, and NRA qualification extends product development timelines. Test facility availability constrains parallel certification programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Gangways Market |
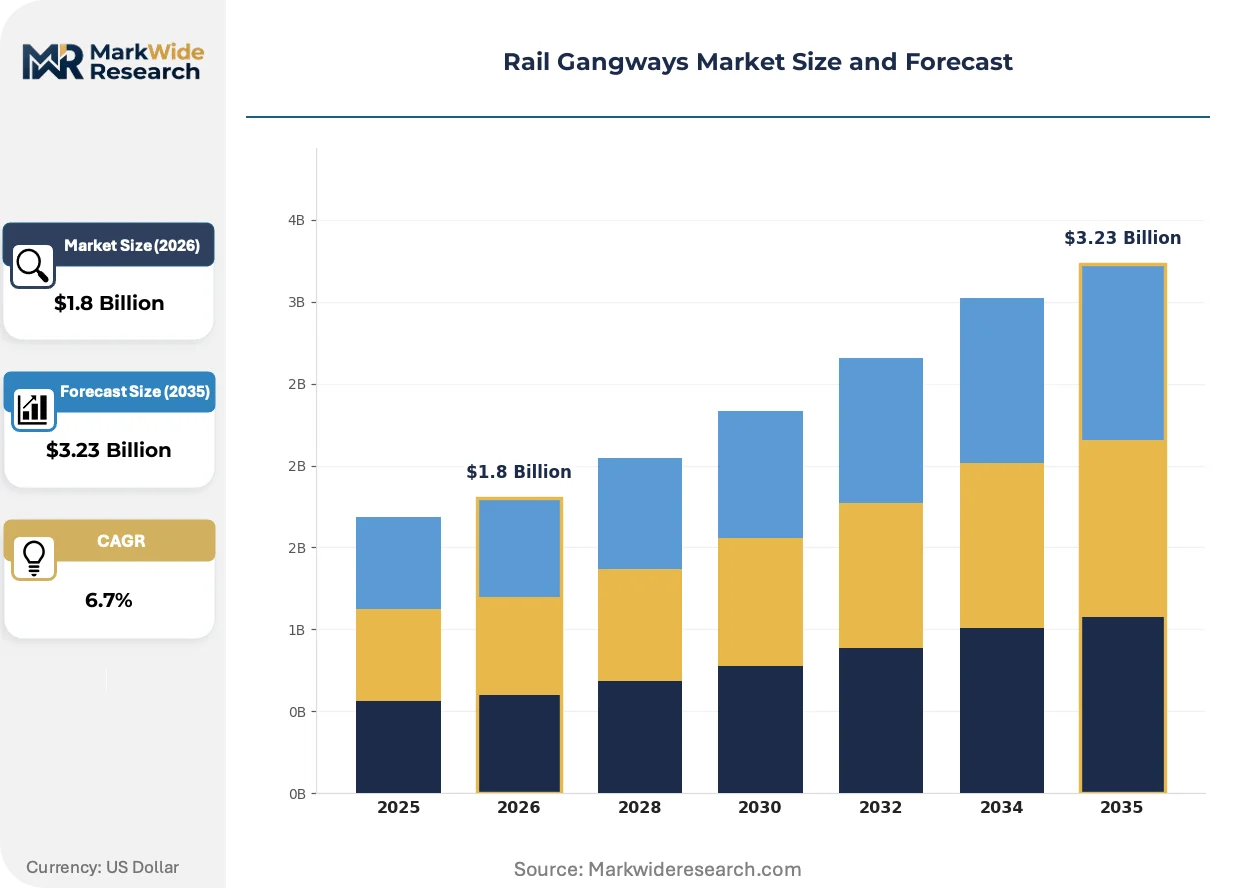
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bi-directional, Single-directional, Flexible, Rigid Material: Aluminum, Steel, Composite, Plastic Application: Passenger Coaches, Freight Trains, Maintenance Vehicles, Rail Yard Operations Connection Type: Manual, Hydraulic, Pneumatic, Electric |
| Companies Covered | Jai Dadi Group, Zhejiang Yonggui Electric Equipment Co., Ltd., HÜBNER GmbH & Co. KG, Schliess- und Sicherungssysteme, Hutchinson Group, Dellner Couplers, KTK Group, Airflow Equipment, Narita Mfg. Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Gangways Market Emerging Trajectories
Material science advances and predictive maintenance architectures are redefining gangway lifecycle economics. Suppliers now compete on total cost of ownership rather than unit price.
Sensor-integrated gangway systems are virtualizing traditional inspection protocols. Embedded strain gauges and accelerometers transmit structural health data to operator maintenance platforms. Deutsche Bahn and SNCF pilot programs demonstrate 40% reduction in unplanned downtime. This virtualization is compressing the market for scheduled visual inspection services.
REACH restrictions on halogenated flame retardants are forcing polymer reformulation across European supply chains. ECHA substance evaluations have delisted several legacy elastomer compounds used in bellows construction. Gangway manufacturers in Germany and France are accelerating bio-based polyurethane development. High-speed operators face material requalification costs before 2027 tender deadlines.
Lifecycle service contracts now dominate procurement evaluation criteria for Nordic and Baltic fleet operators. Dellner Couplers and HÜBNER have unbundled gangway supply from 15-year maintenance agreements. Danish State Railways and VR Group Finland prioritize availability guarantees over capital expenditure minimization. This contracting evolution is visible across Northern European intercity corridors where reliability metrics determine contract renewal.
Rail Gangways Market Segmentation
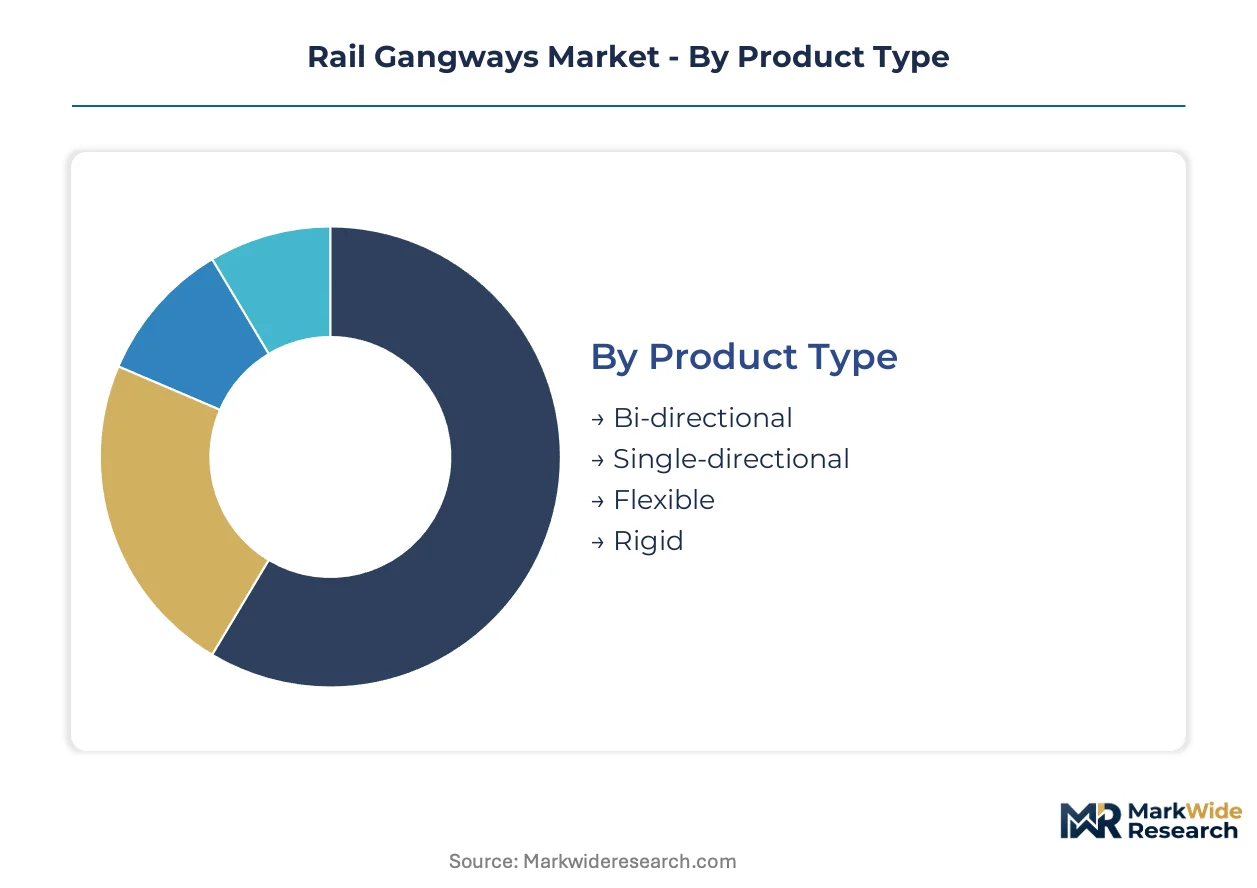
Rail gangway procurement patterns diverge sharply across operational contexts. Fleet operators select configurations based on corridor speed ratings, turnaround frequency, and regulatory compliance tiers rather than unit cost alone.
Product Type:
Operational velocity and turnaround efficiency dictate product selection across commuter, intercity, and high-speed deployments.
- Bi-directional:Articulated assemblies permit passenger flow in both directions without vehicle reorientation. Metro operators in Delhi and Mumbai specify these for terminal-independent operations where dwell time reduction drives fleet productivity.
- Single-directional:Unidirectional passage designs dominate legacy intercity fleets with fixed terminus configurations. Deutsche Bahn's regional networks retain these for cost-optimized replacement cycles on non-reversing corridors.
- Flexible:Elastomeric bellows accommodate angular displacement between coupled vehicles. Freight operators in North American classification yards deploy these for irregular coupling angles during hump yard operations.
- Rigid:Fixed-frame assemblies provide aerodynamic stability at elevated speeds. China's NRA technical specifications mandate these for corridors exceeding specific velocity thresholds where bellows deformation risks seal integrity.
Bi-directional configurations hold installed capacity across urban metro fleets. Rigid assemblies are rotating up the share rankings as high-speed network expansion accelerates.
Material:
Mass reduction targets and crashworthiness mandates are reordering material procurement priorities across European and Asian supply chains.
- Aluminum:Extruded 6000-series profiles deliver strength-to-weight ratios proven across decades of passenger service. EN 15085 welding certification requirements constrain fabricator pools in Germany and Austria, extending lead times for complex extrusion assemblies.
- Steel:Carbon and stainless grades persist in freight applications where impact resistance supersedes mass considerations. Russian Railways and Indian Railways specify these for heavy-haul corridors with minimal speed differentiation requirements.
- Composite:Glass-fiber and carbon-fiber reinforced polymers achieve specific mass reductions exceeding aluminum alternatives. SNCF's TGV fleet renewal tenders specify these for energy consumption targets tied to decarbonization commitments.
- Plastic:Thermoplastic formulations serve interior finishing and secondary structural elements. REACH compliance costs are accelerating substitution timelines for halogenated compounds in bellows construction.
Aluminum maintains dominant share in active fleet materials. Composite alternatives are climbing the fastest as high-speed operators renegotiate lifecycle cost models.
Application:
End-use environments determine structural load ratings, fire resistance tiers, and accessibility compliance levels.
- Passenger Coaches:Gangways for human occupancy require PRM-TSI accessibility compliance, fire resistance to EN 45545, and slip-resistant flooring rated for dense standing loads. European intercity tenders specify these as integrated subsystems with 30-year design lifecycles.
- Freight Trains:Crew passage units between locomotives and cabooses prioritize impact resistance over passenger comfort specifications. Australian and Brazilian mining railroads specify these for remote corridor operations with limited maintenance access.
- Maintenance Vehicles:Self-propelled inspection and track repair fleets require compact gangway footprints. Network Rail and JR East deploy these for ultrasonic rail testing trains with frequent coupling changes.
- Rail Yard Operations:Shunting locomotives and switcher crews use simplified passage units for short-distance crew transfer. Classification yards in Chicago and Hamburg specify these for non-revenue movements with minimal environmental sealing requirements.
Passenger coach applications hold installed capacity across revenue fleets. Maintenance vehicle configurations are rotating up the share rankings as infrastructure inspection automation expands.
Connection Type:
Actuation mechanisms align with fleet automation levels and coupling frequency requirements.
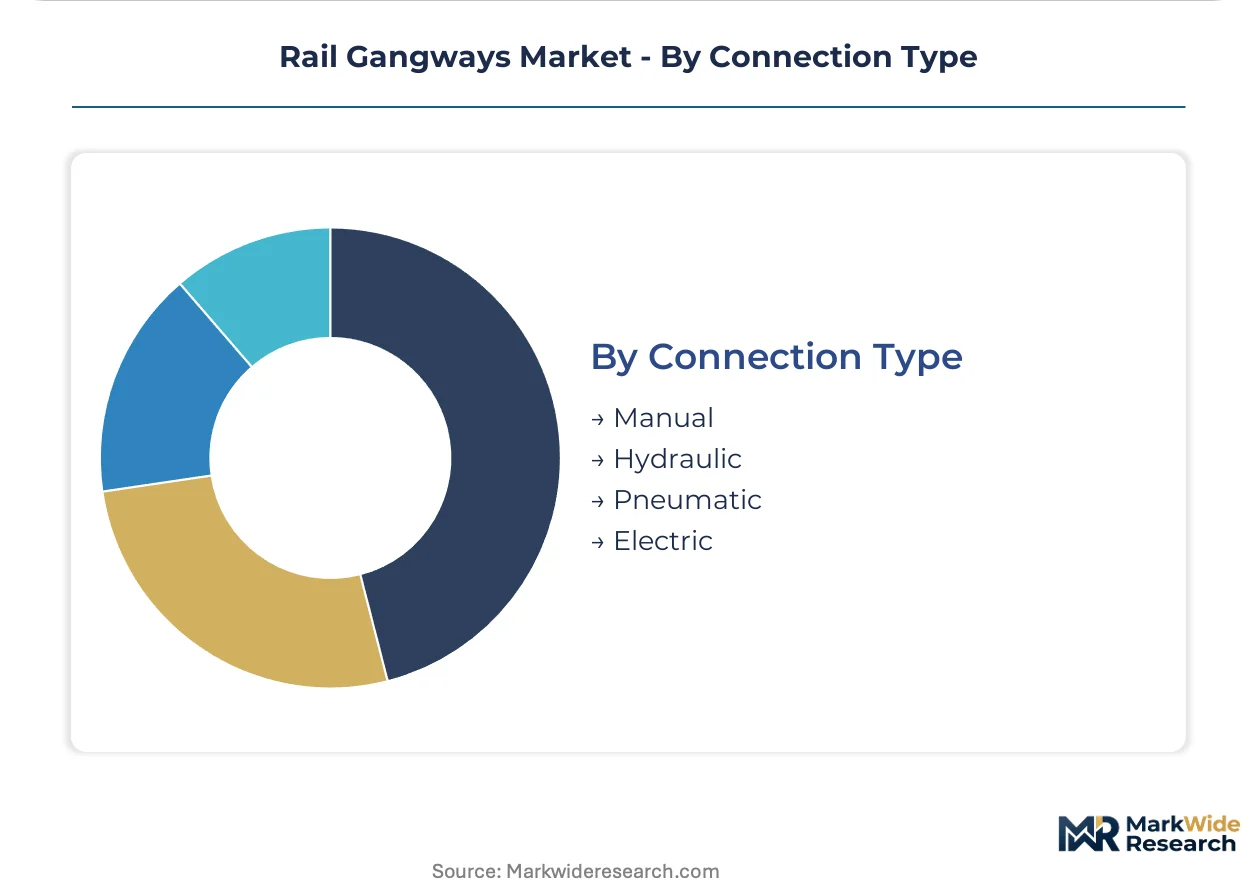
- Manual:Hand-operated locking systems persist in heritage railways and developing market fleets with limited electrification. Steam locomotive excursion operators in the UK and Germany specify these for mechanical simplicity and field repairability.
- Hydraulic:Fluid-power actuation delivers high clamping forces for heavy-haul freight seals. BHP and Rio Tinto specify these for Pilbara iron ore trains with automated ore car coupling at port terminals.
- Pneumatic:Compressed air systems integrate with existing trainline supplies on European and Japanese fleets. Shibata and Dellner dominate tenders where gangway deployment sequences couple with automatic coupler engagement.
- Electric:Servo-motor actuation enables programmable deployment sequences and diagnostic feedback. Alstom and Siemens specify these for driverless metro platforms where remote monitoring replaces manual inspection protocols.
Pneumatic systems hold installed capacity across established fleets. Electric actuation is rotating up the share rankings as autonomous train operations expand regulatory approval.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NRA technical specifications anchor procurement frameworks in China, the dominant geography where state-backed rail modernization programs concentrate fleet investment. European operators navigate EN 15227 crashworthiness mandates that compress design cycles. Indian metro authorities leverage domestic manufacturing incentives to reduce import dependency.
China
State Railway Group procurement drives gangway demand across high-speed corridors and urban metro networks. NRA technical specifications mandate rigid assemblies for velocity thresholds exceeding operational benchmarks. CRRC Qingdao Sifang and Changchun Railway Vehicles anchor manufacturing clusters in Shandong and Jilin provinces.
Germany
Deutsche Bahn fleet renewal programs sustain demand for premium intercity gangway configurations. EBA enforcement of EN 15227 standards accelerates replacement cycles for legacy rolling stock. Engineering fabricators concentrate in North Rhine-Westphalia and Bavaria, leveraging EN 15085 welding certification infrastructure.
India
Metro construction in Delhi, Mumbai, and Bangalore generates standardized gangway procurement volumes. PLI scheme incentives for domestic manufacturing reduce tender participation barriers for local fabricators. Integral Coach Factory in Chennai and Rail Coach Factory in Kapurthala anchor production capacity.
France
SNCF TGV fleet decarbonization targets prioritize composite gangway materials for mass reduction. PRM-TSI accessibility mandates favor low-floor designs with wheelchair-compatible passage widths. Alstom manufacturing presence in Île-de-France and Auvergne-Rhône-Alpes sustains supplier ecosystems.
Japan
JR East and JR West procurement emphasizes sensor-integrated gangway systems for predictive maintenance architectures. JIS standards govern material qualification protocols for high-speed applications. Industrial concentration in Kanto and Kansai regions supports integrated coupler-gangway supply chains.
Rail Gangways Market Vendor Landscape
European engineering specialists and Asian scale fabricators split the market along premium-standard segmentation lines. Consolidation concentrates among tier-one suppliers with multi-standard certification capabilities. Three archetypes dominate: heritage European engineering houses, integrated coupler-gangway specialists, and Asian volume manufacturers. Competitive moves center on strategic partnerships for technology licensing and backward integration into polymer compounding.
Among German-based engineering houses, HÜBNER GmbH & Co. KG occupies a position exemplifying heritage European premium-tier positioning. Dellner Couplers represents the integrated specialist archetype, anchoring Nordic and Baltic market presence through coupler-gangway system bundling. Zhejiang Yonggui Electric Equipment Co., Ltd. sits within the Asian volume-manufacturing tier, reflecting scale-driven competitive positioning.
| Leading Market Players |
|---|
| Jai Dadi Group |
| Zhejiang Yonggui Electric Equipment Co., Ltd. |
| HÜBNER GmbH & Co. KG |
| Schliess- und Sicherungssysteme |
| Hutchinson Group |
| Dellner Couplers |
| KTK Group |
| Airflow Equipment |
| Narita Mfg. Co. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Kunming high-speed corridor's freight cost dynamics illustrate how aluminum feedstock volatility and EN 15227 certification premiums interact to stratify gangway procurement tiers. Chinese state rail tenders leverage domestic extrusion capacity to compress standard-tier pricing, while European operators absorb 15-20% premiums for crashworthy composite assemblies.
Pricing Analysis
Geographic price spreads between Chinese domestic tenders and European premium contracts exceed three-to-one ratios for equivalent capacity ratings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales bundling intensity. Pricing pressure stems from aluminum smelting energy cost spikes and REACH-compliant polymer reformulation expenses. Freight operators in heavy-haul corridors exhibit highest price sensitivity, while high-speed rail authorities prioritize lifecycle cost over unit procurement.
Supply Chain Analysis
Contract manufacturing concentration rests with CRRC Qingdao Sifang and Changchun Railway Vehicles in China, HÜBNER GmbH in Germany, and Dellner Couplers in Sweden. Geographic supply concentration centers on China, Germany, and Japan for extruded aluminum profiles, polymer compounding, and sensor integration modules. Raw material dependencies draw from 6000-series aluminum billet, halogen-free polyurethane elastomers, and carbon-fiber prepregs. Single-source vulnerability concentrates in EN 15085-certified welding labor pools. Distribution runs through OEM direct procurement for high-speed fleets and tier-one system integrators for metro deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rail gangways market constitutes a high-growth disruption as EN 15227 crashworthiness mandates and composite material advances simultaneously reshape procurement specifications and supplier qualification barriers.
For Market Incumbents: Insulate premium positioning through captive polymer compounding capabilities and exclusive EN 15085 welding certification pipelines. Deepen backward integration into elastomer formulation to offset REACH-driven raw material cost spikes. Defend against Asian volume manufacturers by anchoring lifecycle service contracts with availability guarantees.
For New Entrants and Emerging Players: Establish a beachhead in Indian metro procurement through PLI scheme-compliant domestic manufacturing partnerships. Target maintenance vehicle configurations where sensor-integrated gangway penetration remains below passenger coach saturation. Pursue digital twin integration capabilities as a differentiated go-to-market wedge.
For Investors and Strategic Acquirers: Sensor-embedded gangway specialists with predictive maintenance software stacks represent the priority acquisition archetype for portfolio exposure to rail infrastructure digitalization. Long-term viability hinges on multi-standard certification capabilities spanning EN, FRA, and NRA frameworks. Watch for inflection in Indian tender participation thresholds and Chinese state rail localization mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | Parallel EN 15227, FRA, and NRA qualification unlocks tender participation across Chinese high-speed and European intercity corridors. |
| Composite Material Manufacturing Scale-Up | Glass-fiber and carbon-fiber production capacity addresses SNCF TGV decarbonization targets and mass reduction specifications. |
| Predictive Maintenance Platform Development | Sensor-embedded gangway systems with real-time structural monitoring align with Deutsche Bahn and JR East availability mandates. |
| Domestic Manufacturing Joint Venture | Indian PLI scheme partnerships with Integral Coach Factory and Rail Coach Factory reduce import dependency in Delhi and Mumbai metro expansions. |
| REACH-Compliant Polymer Reformulation | Bio-based polyurethane development replaces delisted halogenated flame retardants before European tender deadlines. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors, gangway engineering leads, rolling stock OEM platform managers, and aftermarket service heads. Secondary validation drew from NRA technical specification filings, EBA type-approval databases, SEC 10-K disclosures by listed rail equipment suppliers, and customs trade data for aluminum extrusion and polymer imports. Bottom-up unit shipment estimates triangulated against top-down fleet investment projections across the analysis window.
Calibration against historical replacement cycles and announced procurement pipelines anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material class, application environment, connection mechanism, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating fleet age profiles, mandate compliance deadlines, and infrastructure investment commitments. Industry-specific inputs encompassed EN 15227 test facility capacity constraints and aluminum LME price volatility bands.
Sensitivities concentrate around NRA specification revisions, REACH substance delisting timelines, and Indian domestic content threshold adjustments. Forecasts reflect documented assumptions regarding fleet renewal acceleration and composite material qualification progress. Quarterly review of tender award patterns, certification body backlogs, and smelter energy cost indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Rail Pads Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Train Transformer Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Railroad Tank Car Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Rail Testing Vehicle Market