
 Autonomous Train Technology Market | 2026-2036
Autonomous Train Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Train Technology Market Analysis
Multi-source procurement of sensor suites and control systems is recalibrating vendor relationships across the rail automation sector. Siemens AG leverages its European installed base to sustain long-term service contracts. Alstom SA anchors its position through in-house production of digital signaling platforms. CRRC Corporation Limited competes on manufacturing scale across Asia-Pacific corridors.
Autonomous train technology encompasses sensor fusion architectures, automatic train operation algorithms, and communication-based train control systems that enable driverless movement with specified headways below ninety seconds. These systems serve commercial rail networks by eliminating human error in braking curves, platform alignment, and collision avoidance. Computer vision segments command premium pricing due to real-time obstacle detection requirements in mixed-traffic environments. Light rail deployments represent the fastest-growing product category as municipalities prioritize urban decongestion. Rail operators as an end-user group concentrate procurement volume through fleet-wide standardization programs.
EU's ERTMS/ETCS framework and the F-Gas Regulation shape component certification timelines across European deployments. The US Federal Railroad Administration enforces positive train control compliance that mandates interoperable automatic train protection. Japan's MLIT maintains stringent GoA4 safety integrity levels that filter market access. Stakeholders must monitor divergence between regional signaling standards when architecting platform roadmaps for cross-border corridors.
Market Dynamics
Positive train control mandates across North America and Europe are forcing wholesale replacement of legacy signaling infrastructure, compressing procurement cycles and recalibrating vendor qualification thresholds for safety-critical subsystems.
Growth Catalysts
- ERTMS/ETCS Deployment Deadlines:European rail operators face binding interoperability mandates that require full ETCS Level 2 or 3 implementation on cross-border corridors, generating sustained retrofit demand through 2035.
- Urban Decongestion Policies:Municipal transit authorities in China, Japan, and Germany prioritize GoA4 metro lines to maximize passenger throughput per track kilometer during peak hours.
- LiDAR Cost Curves:Automotive-scale manufacturing of solid-state LiDAR sensors is reducing per-unit costs for obstacle detection suites in mixed-traffic rail environments.
Market Restraints
- Rare Earth Magnet Concentration:Permanent magnet motors for traction systems depend on Chinese-processed neodymium, creating supply vulnerability for European and Japanese rolling stock manufacturers.
- Silicon Photonics Bottlenecks:Fiber-optic gyroscope production for train positioning systems concentrates among a handful of specialized foundries, limiting sensor fusion scaling.
- F-Gas Certification Friction:The EU's phasedown of hydrofluorocarbons in cooling systems for onboard electronics extends thermal management redesign timelines by 18-24 months.
Strategic Opportunities
- India's Dedicated Freight Corridors:The country's 1,500-kilometer Eastern and Western freight corridors lack legacy signaling, enabling greenfield autonomous deployment without interoperability constraints.
- 5G-Rail Convergence:Integration of 3GPP Release 16 URLLC standards with train-to-ground communication architectures permits sub-50-millisecond latency for emergency braking.
- Performance-Based Maintenance Contracts:German and Swiss operators now contract availability guarantees rather than component replacement schedules, shifting vendor revenue toward uptime metrics.
Industry Challenges
- SIL-4 Software Certification:Demonstrating safety integrity level compliance for automatic train operation algorithms requires 10,000+ hours of fault injection testing per release cycle.
- Legacy Interlocking Integration:Relay-based signaling systems from the 1970s-1980s lack digital interfaces, forcing costly gateway development for hybrid corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Train Technology Market |
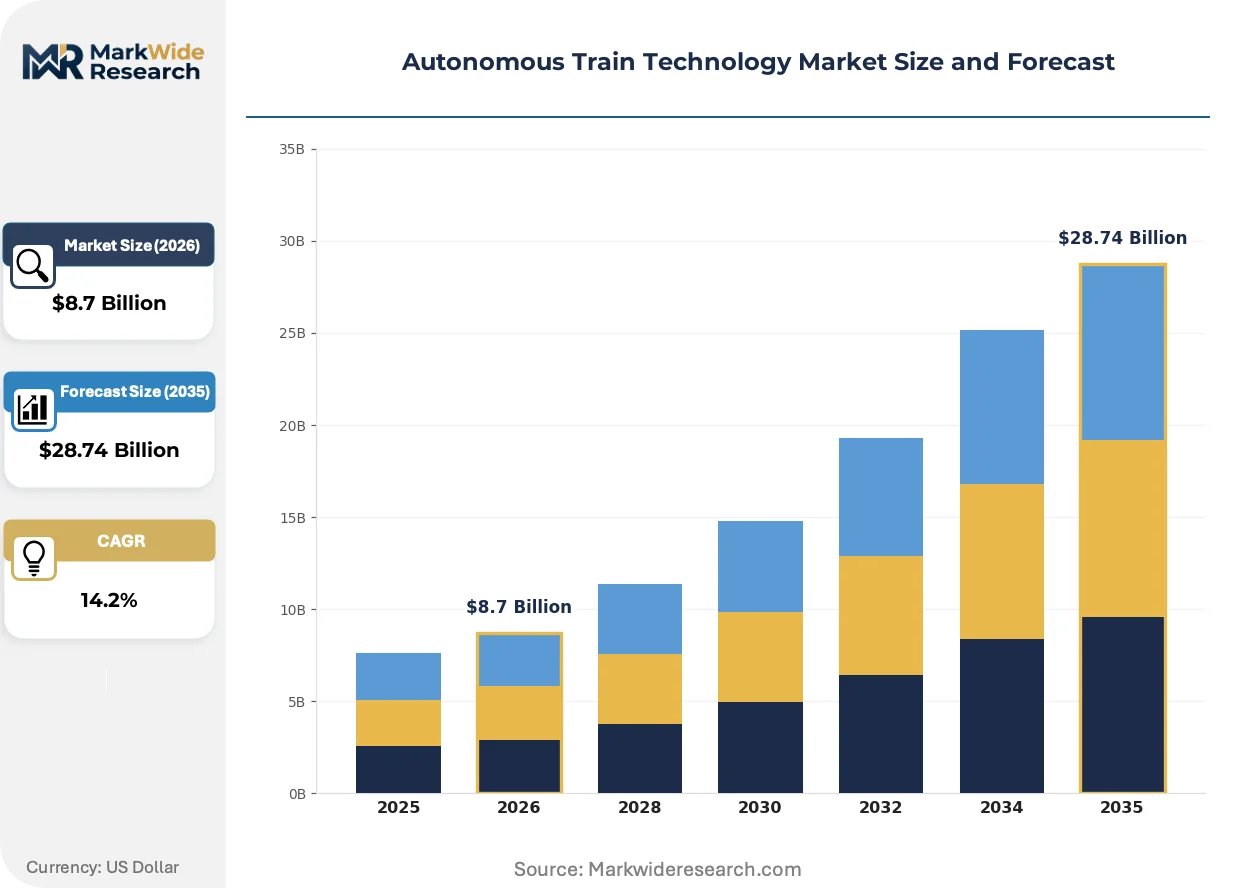
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AID, LIDAR, GPS, Computer Vision Product Type: Freight Trains, Passenger Trains, Light Rail, Monorail End User: Rail Operators, Government Agencies, Private Companies, Logistics Providers Deployment Model: On-premise, Cloud-based, Hybrid, Modular |
| Companies Covered | Alstom SA, Siemens AG, Hitachi Ltd, CRRC Corporation Limited, Thales Group, Bombardier, Kawasaki Heavy Industries, Mitsubishi Heavy Industries, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Train Technology Market Emerging Trajectories
Distributed computing architectures are displacing centralized train control rooms, embedding decision-making directly within rolling stock and wayside units. This shift compresses response latency and reduces single-point vulnerability.
Edge AI inference engines are decentralizing obstacle detection from trackside servers to onboard sensor fusion units. Japanese Shinkansen operators deploy these systems for real-time debris recognition at 300 km/h. The architecture eliminates fiber dependency for safety-critical functions, hardening operations against communication outages.
The EU's F-Gas Regulation is accelerating refrigerant transition in onboard electronics cooling. Rolling stock manufacturers must redesign thermal management for climate-controlled sensor enclosures. German and French operators now specify CO2-based cooling in new procurements, filtering vendor eligibility.
Lifecycle service unbundling is fragmenting long-term vendor relationships. Swiss and Austrian federal railways now separately contract predictive maintenance analytics from rolling stock supply. Tier-2 software specialists capture recurring revenue previously held by integrated OEMs, compressing margins for hardware-centric suppliers.
Autonomous Train Technology Market Segmentation
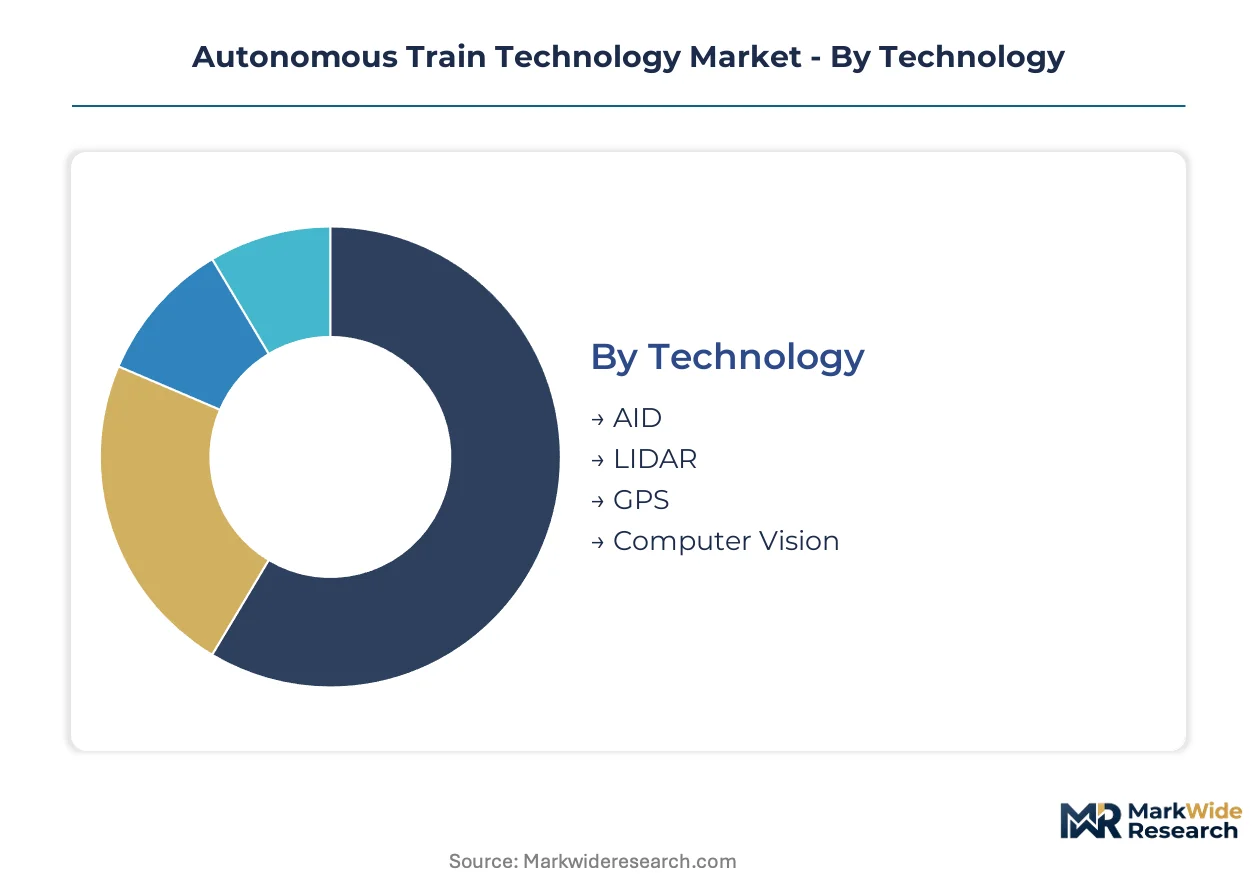
Technology choices in autonomous rail systems cascade through procurement specifications, certification pathways, and long-term maintenance economics. Vendors architect platform roadmaps around specific sensor fusion combinations and deployment architectures that match operator risk profiles and infrastructure maturity.
Technology:
Rail operators prioritize sensor redundancy levels based on corridor traffic density and maximum operating speeds.
- Computer Vision:Real-time image processing algorithms detect track obstructions, platform edge intrusions, and signal aspect recognition through convolutional neural networks. Japanese Shinkansen corridors and German high-speed lines specify multi-camera arrays for mixed-traffic environments where pedestrian or vehicle incursion risks concentrate.
- LIDAR:Solid-state laser scanning generates three-dimensional point clouds for precise obstacle localization and tunnel clearance verification. Municipal transit authorities in China specify LIDAR fusion for underground metro segments where GPS denial requires alternative positioning.
- AID:Automatic train operation algorithms execute braking curves, platform alignment, and headway management through SIL-4 certified control loops. European ETCS Level 3 deployments embed AID cores within onboard units for moving-block operation.
- GPS:Satellite positioning provides absolute location reference for wayside-free train control in open-track environments. Indian Dedicated Freight Corridors leverage GPS augmentation for kilometer-long freight consist tracking across rural alignments.
Computer Vision leads on scale; LIDAR leads on momentum.
Product Type:
Vehicle architecture dictates control system complexity, sensor payload requirements, and certification scope.
- Light Rail:Tram and streetcar systems operate in mixed-traffic conditions requiring continuous pedestrian and cyclist detection. French and Spanish municipal networks expand GoA4 deployments to reduce labor costs on high-frequency urban circulators.
- Freight Trains:Heavy-haul consists demand distributed power control and distributed braking coordination across kilometer-long formations. Australian iron ore corridors and Russian freight lines pilot autonomous operation for remote resource extraction routes.
- Passenger Trains:Intercity and regional services balance speed optimization with passenger safety integrity requirements. Italian and British operators retrofit existing fleets with ETCS Level 2 for cross-border interoperability.
- Monorail:Straddle-beam and suspended systems eliminate grade conflicts but require precise guideway alignment monitoring. Chongqing and São Paulo networks represent concentrated procurement for urban elevated transit.
Freight Trains dominate retrofit volume; Light Rail exhibits the steepest expansion trajectory.
End User:
Procurement authority and risk tolerance vary sharply across institutional ownership structures.
- Rail Operators:Deutsche Bahn, SNCF, and JR East drive fleet-wide standardization programs that consolidate multi-year technology roadmaps.
- Government Agencies:Federal transport ministries in India and Brazil fund greenfield corridor development with embedded autonomy specifications.
- Private Companies:Mining conglomerates in Western Australia and Chile operate captive rail networks with customized safety protocols outside public regulatory frameworks.
- Logistics Providers:DHL and Maersk explore autonomous shunting and terminal operations for intermodal freight efficiency.
Rail Operators command procurement volume; Private Companies show the fastest adoption velocity.
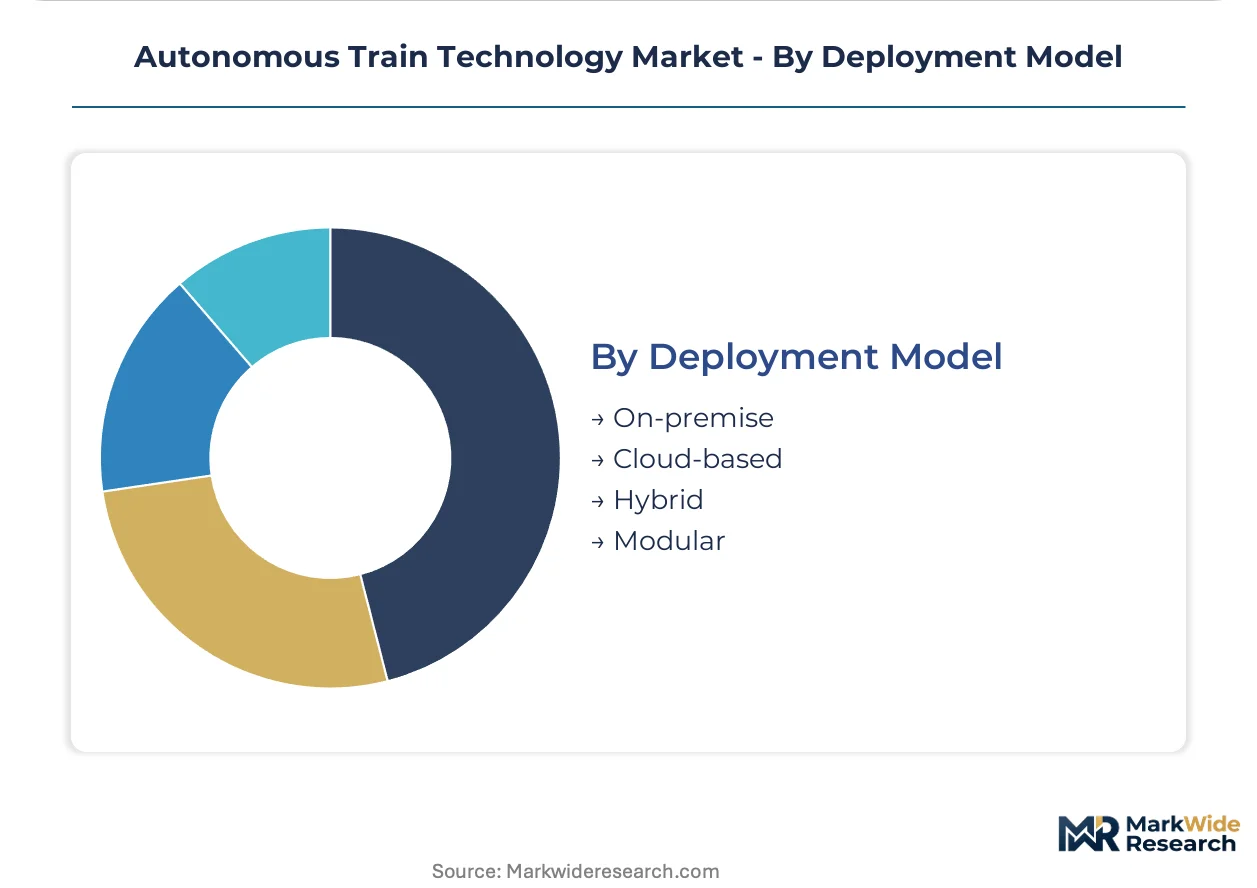
Deployment Model:
Data sovereignty requirements and connectivity infrastructure determine architectural choices for train-to-ground communication.
- Hybrid:Split processing between onboard edge units and wayside cloud resources balances latency-critical safety functions with predictive analytics. Swiss Federal Railways specify hybrid architectures for Alpine tunnels with intermittent cellular coverage.
- On-premise:Fully localized control systems satisfy national security requirements for critical infrastructure. Russian and Chinese operators mandate on-premise deployment for strategic rail corridors.
- Cloud-based:Centralized fleet management and predictive maintenance analytics concentrate in data centers with redundant connectivity. Nordic operators pilot cloud-based dispatch for regional networks with reliable 5G coverage.
- Modular:Componentized subsystems permit phased capability upgrades without fleet-wide replacement. Southeast Asian operators favor modular procurement to manage capital deployment across extended timelines.
Hybrid architectures capture the largest installed base; Modular approaches gain share fastest among emerging market operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting autonomous train system procurement toward jurisdictions with streamlined certification pathways. Germany and Japan absorb premium pricing for SIL-4 compliance, while China and India exploit greenfield deployment flexibility to compress implementation timelines.
China
CRRC Corporation's manufacturing scale dominates domestic metro procurement across Beijing, Shanghai, and Shenzhen corridors. The Ministry of Transport's smart rail initiative mandates GoA4 capability on all new urban lines by 2030. Chongqing's straddle-beam monorail network serves as a testbed for autonomous guideway alignment systems.
Germany
Deutsche Bahn's fleet-wide ETCS retrofit program generates sustained demand for interoperable signaling platforms. The F-Gas Regulation forces thermal management redesigns for onboard electronics cooling. Siemens anchors its position through long-term service contracts across Bavaria and North Rhine-Westphalia rail corridors.
Japan
JR East's standardization programs concentrate procurement volume for Shinkansen and urban metro lines. MLIT maintains stringent GoA4 safety integrity levels that filter market access for foreign vendors. The Tokyo-Osaka corridor deploys edge AI inference engines for real-time debris recognition at operating speeds.
United States
Freight railroads face Federal Railroad Administration mandates for positive train control compliance across Class I networks. The absence of legacy signaling on Indian Dedicated Freight Corridors enables greenfield autonomous deployment without interoperability constraints. California's high-speed rail project specifies hybrid control architectures for mountain tunnel segments.
India
The Dedicated Freight Corridor Corporation procures autonomous systems for 1,500 kilometers of greenfield track without legacy interlocking constraints. Indian Railways' electrification push aligns with autonomous deployment on Eastern and Western freight routes. The Delhi-Meerut RRTS corridor pilots moving-block signaling for regional rapid transit.
Autonomous Train Technology Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular subsystem specialization. The vendor base stratifies between integrated rolling stock manufacturers and component specialists. Three archetypes dominate: European signaling incumbents with service contract lock-in, Asian conglomerates with captive manufacturing scale, and Tier-2 software vendors unbundling predictive maintenance analytics. Competitive moves center on geographic expansion through local joint ventures and technology licensing agreements for regional certification compliance.
Among European-anchored integrators, Alstom SA and Siemens AG exemplify the service-contract archetype, embedding long-term availability guarantees into fleet procurement. CRRC Corporation Limited occupies a scale-driven position across Asia-Pacific corridors. These three entities represent distinct strategic postures: European incumbents defend through aftermarket revenue, while the Chinese manufacturer competes on capital cost and deployment velocity.
| Leading Market Players |
|---|
| Alstom SA |
| Siemens AG |
| Hitachi Ltd |
| CRRC Corporation Limited |
| Thales Group |
| Bombardier |
| Kawasaki Heavy Industries |
| Mitsubishi Heavy Industries |
| ABB |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed rolling stock manufacturers in China and family-owned sensor specialists in Japan anchor supply behavior through captive production networks, while European system integrators defend pricing discipline via long-term availability contracts that bundle hardware with SIL-4 certification services.
Pricing Analysis
Distributor margins for component-level sensor suites compress pricing by 12-18 points before system integration. Project-based contracting dominates turnkey deployments, with price differentiation resting on certification grade and after-sales service bundling. Cost compression in computer vision modules intensifies as automotive-scale LiDAR production spills into rail applications. Municipal transit authorities in Southeast Asia exhibit highest price sensitivity; German and Swiss federal railways prioritize uptime guarantees over capital cost.
Supply Chain Analysis
Permanent magnet motor supply rests on Chinese-processed neodymium, Japanese silicon photonics foundries, and German precision machining for safety-critical enclosures. Solid-state LiDAR sensors, fiber-optic gyroscopes, and ETCS-compatible control units constitute core component dependencies. Single-source vulnerability concentrates in rare earth magnet processing and specialty optical fiber production. Distribution runs through direct OEM relationships for rolling stock manufacturers, with Tier-2 software vendors increasingly unbundling predictive analytics through separate contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous train technology market functions as a stable compounder, with regulatory mandates for positive train control and ERTMS/ETCS interoperability generating predictable retrofit demand across extended procurement cycles.
For Market Incumbents: Cement service contract lock-in through performance-based availability guarantees rather than component replacement schedules. Deepen backward integration into sensor fusion hardware to capture margins fleeing modular software specialists. Alstom and Siemens already anchor European corridors through this posture; extend similar frameworks into India's greenfield freight corridors before local manufacturing scales. For New Entrants and Emerging Players: Regional system integrators in Southeast Asia represent the most penetrable channel partner type for modular subsystem vendors. Target India's Dedicated Freight Corridor Corporation with decoupled predictive maintenance analytics, unbundled from rolling stock supply. Position around 5G-Rail convergence expertise as incumbent OEMs lag in 3GPP Release 16 integration. For Investors and Strategic Acquirers: Valuations sit cheapest among Tier-2 software specialists with SIL-4 certification capabilities and recurring revenue from unbundled maintenance contracts. The five-to-ten year viability window favors acquisition of edge AI inference engine developers with proven Shinkansen deployment references. Watch for F-Gas Regulation compliance delays as inflection indicator for thermal management redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Maintenance Contracting | Shifts vendor revenue toward uptime metrics at Deutsche Bahn and Swiss Federal Railways. |
| 5G-Rail Communication Integration | Enables sub-50-millisecond emergency braking latency through 3GPP Release 16 URLLC standards. |
| SIL-4 Software Certification Investment | Filters market access for automatic train operation algorithms in Japanese MLIT-regulated corridors. |
| Backward Integration into Sensor Hardware | Captures margins from solid-state LiDAR cost curves spilling from automotive-scale manufacturing. |
| Greenfield Corridor Deployment | India's Eastern and Western freight corridors enable autonomous systems without legacy interlocking constraints. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rolling stock procurement directors, ETCS certification engineers, rail operator maintenance heads, and government transport ministry planners with secondary validation against UNIFE market statistics, ERA technical specifications, UIC interoperability frameworks, and national rail regulator filings. Bottom-up segment sizing and top-down macro anchoring were cross-checked for consistency.
Historical reference periods anchored the projection horizon to documented deployment timelines for GoA4 metro lines and ETCS retrofit programs. The analytical framework modeled technology type, product category, end-user ownership structure, and deployment architecture as core segmentation dimensions. CAGRs were derived from installation base growth curves and replacement cycle analysis, with rail electrification rates and urban transit ridership recovery patterns serving as industry-specific demand inputs.
Revisions become necessary when regulatory deadline extensions, rare earth export restrictions, or 5G spectrum allocation delays materialize across major deployment jurisdictions. Forecasts reflect documented assumptions about interoperability mandate adherence and certification timeline norms. A small set of named triggers—F-Gas Regulation phasedown pace, Indian freight corridor commissioning schedules, and Japanese Shinkansen edge AI deployment rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Train Transformer Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Rail Pads Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Railway Connectors Market