
 Global Thyroid Disorder Market | 2026-2036
Global Thyroid Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thyroid Disorder Market Foresight
The premium biologic thyroid segment is repositioning away from commodity levothyroxine generics through differentiated pharmacokinetic profiles and companion diagnostic bundling. AbbVie Inc. leverages its immunology infrastructure to cross-sell thyroid autoimmunity testing with hormone therapy protocols. Pfizer Inc. sustains manufacturing scale across multiple active pharmaceutical ingredient sources for synthetic thyroid hormones. Merck KGaA anchors European distribution through specialized endocrinology channels that require cold-chain integrity certification.
Thyroid disorder encompasses pathological dysfunction of the thyroid gland involving dysregulated synthesis, secretion, or peripheral conversion of triiodothyronine and thyroxine hormones, typically measured through serum TSH, free T4, and anti-TPO antibody assays. The condition serves clinical purposes ranging from metabolic rate correction in hypothyroidism to suppression of thyrotoxicosis and management of differentiated thyroid carcinomas. Thyroid hormone replacement dominates current prescription volumes due to lifelong therapy requirements for Hashimoto's and post-ablative patients, while radioactive iodine captures concentrated margin pools in refractory hyperthyroidism and adjuvant cancer protocols. The hypothyroidism therapy area maintains the largest patient base, though thyroid cancer segments command premium pricing through targeted kinase inhibitor adjuvants and specialized surgical oncology referrals.
FDA, EMA, and WHO prequalification standards shape thyroid drug approval pathways, with bioequivalence requirements for levothyroxine generics creating sustained barriers to interchangeability claims. The EU MDR and FDA 21 CFR Part 11 documentation mandates are elevating quality management costs for hormone replacement manufacturers while accelerating consolidation among suppliers lacking validated electronic batch records. Stakeholders must monitor evolving pharmacovigilance requirements for long-acting thyroid formulations and prepare for potential reimbursement recalibration as value-based contracting expands in endocrinology.
Market Dynamics
The thyroid disorder market is restructuring around diagnostic-treatment bundling as specialty clinics deploy high-throughput autoantibody screening to capture patients earlier in disease progression. This shift compresses the traditional referral pathway and concentrates volume in integrated endocrinology networks.
Growth Catalysts
- EU MDR documentation mandates:The Medical Device Regulation is accelerating consolidation among hormone replacement manufacturers lacking validated electronic batch records, pushing volume toward certified suppliers.
- Japan's deepening screening protocols:METI-backed metabolic disease prevention programs are expanding TSH testing penetration in corporate health screenings and municipal clinics.
- Companion diagnostic bundling:Anti-TPO antibody assays paired with levothyroxine initiation protocols are capturing Hashimoto's patients at diagnosis, locking in long-term therapy relationships.
Market Restraints
- API supply concentration:Synthetic thyroid hormone active pharmaceutical ingredients concentrate in Chinese and Indian manufacturing clusters, exposing formulators to single-source disruption risk.
- Levothyroxine bioequivalence barriers:FDA's narrow therapeutic index requirements block interchangeability claims for generic entrants, entrenching incumbent pricing power.
- Radioactive iodine facility scarcity:Germany and Japan face constrained production capacity for I-131 capsules, limiting adjuvant cancer therapy access outside major metropolitan centers.
Strategic Opportunities
- Brazil's underpenetrated autoimmune thyroiditis management:ANVISA's streamlined registration pathway for hormone therapies opens access to a patient population previously reliant on importation.
- Long-acting thyroid formulation development:Depot injection technologies converging with polymer-based sustained-release platforms could reduce dosing frequency from daily to monthly intervals.
- Direct-to-patient pharmacy channels:Cold-chain certified mail-order distribution is bypassing traditional hospital pharmacy gatekeepers in Germany and the United States.
Industry Challenges
- Endocrinology workforce scarcity:Fellowship-trained specialists concentrate in urban academic centers, leaving rural and suburban markets dependent on primary care physicians with limited hormone titration expertise.
- Cold-chain integrity certification costs:EU GDP compliance for biologic thyroid extracts requires validated temperature monitoring infrastructure that mid-size distributors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thyroid Disorder Market |
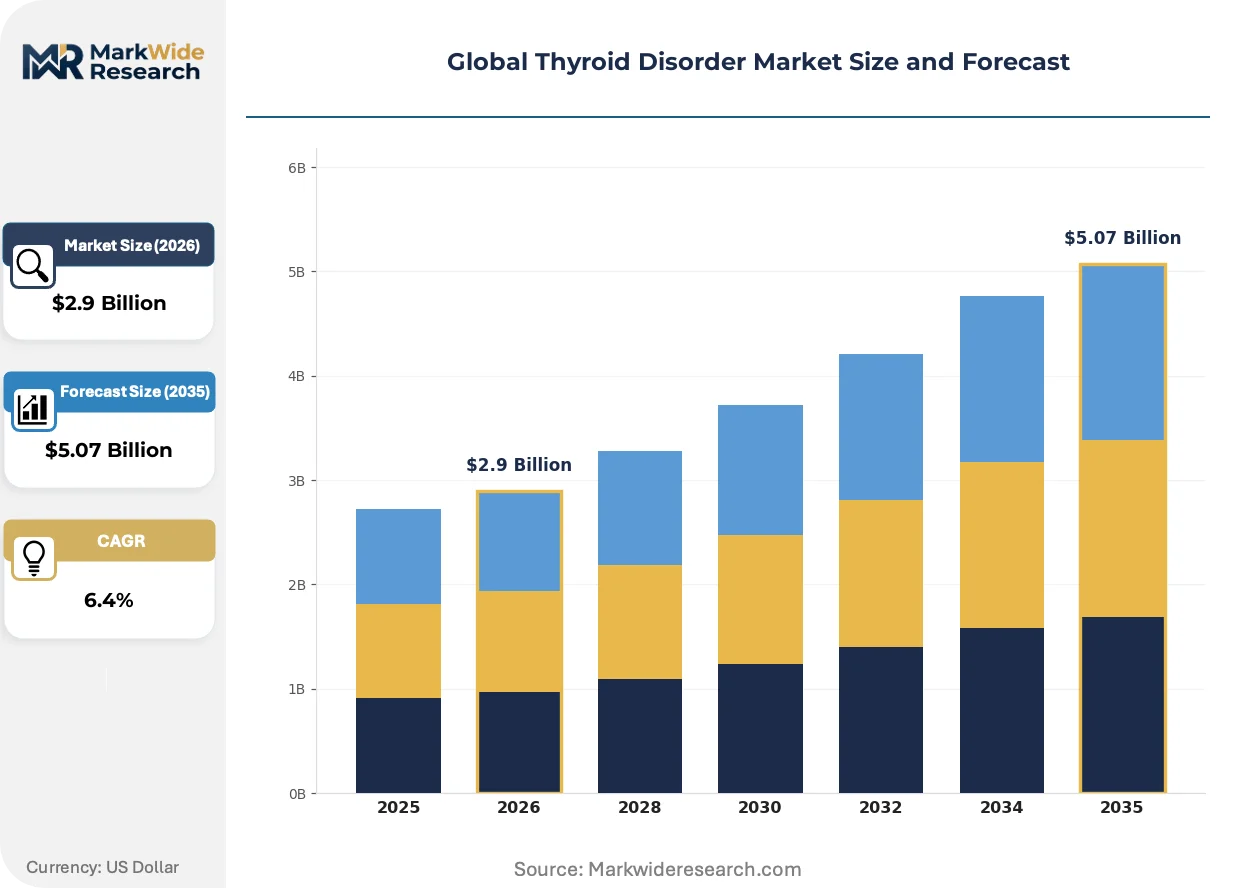
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.07 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thyroid Hormone Replacement, Antithyroid Drugs, Radioactive Iodine, Beta Blockers, Surgery Therapy Area: Hypothyroidism, Hyperthyroidism, Thyroid Nodules, Thyroid Cancer, Goiter End User: Hospitals, Diagnostic Laboratories, Specialty Clinics, Research Institutes, Wellness Centers Delivery Mode: Oral, Injectable, Radioiodine Therapy, Surgical Intervention, Transdermal |
| Companies Covered | Pfizer Inc., AbbVie Inc., Merck KGaA, GSK Plc, Novartis AG, Allergan Plc., Sanofi, Amgen Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thyroid Disorder Market Shifts & Advancements
Digital biomarker integration is reshaping how thyroid function is monitored outside clinical settings, with continuous metabolic sensors and patient-reported outcome platforms compressing the feedback loop between dose adjustment and physiological response.
Continuous glucose monitoring derivatives adapted for metabolic hormone tracking are electrifying the hypothyroidism management segment. Endocrinology practices in Germany and Japan are piloting these wearable platforms to capture circadian T3/T4 fluctuations. The technology is compressing reliance on quarterly venous draws and enabling real-time dose optimization.
EMA's forthcoming pharmacovigilance guidance for long-acting thyroid formulations is tightening post-market surveillance requirements. Manufacturers must now submit patient registry data as a condition of marketing authorization renewal. The synthetic hormone segment faces the steepest compliance burden, with batch-level traceability mandates extending back to API synthesis records.
Patient-driven switching between branded and generic levothyroxine is accelerating as online pharmacy aggregators dissolve traditional prescriber-pharmacist control. Direct price comparison tools in the United States and Germany are fragmenting loyalty to established formulations. Hashimoto's patient advocacy networks are increasingly demanding specified manufacturers rather than accepting pharmacy-level substitution.
Global Thyroid Disorder Market Segmentation
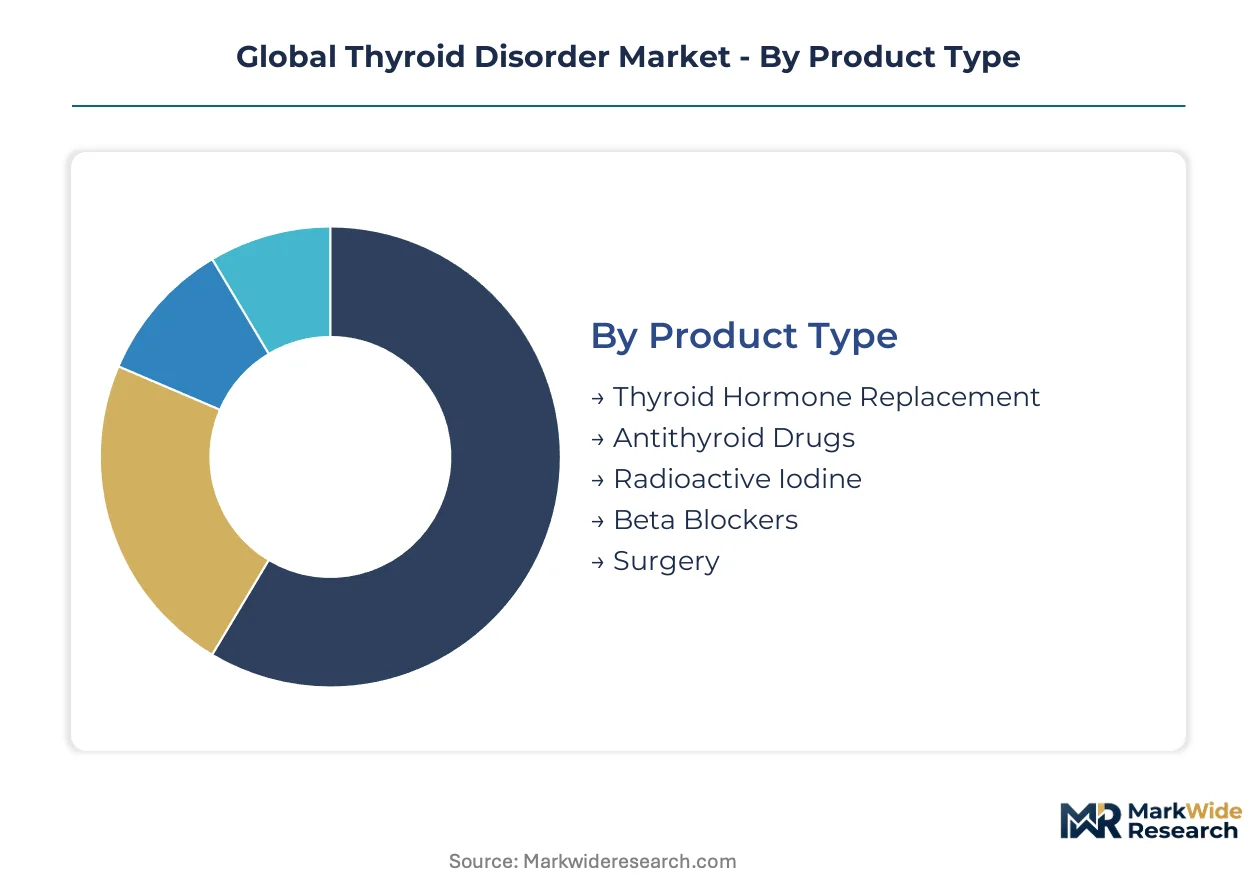
Thyroid disorder treatment modalities fragment across lifelong chronic management, acute intervention, and curative protocols. Each segment commands distinct regulatory pathways, reimbursement codes, and distribution infrastructure that shape competitive entry barriers.
Product Type:
Customization spans from mass-produced synthetic hormones to patient-matched radioactive dosing, with standardization concentrated in oral generics.
- Thyroid Hormone Replacement:Synthetic levothyroxine and liothyronine formulations dominate prescription volumes through once-daily oral dosing. Demand concentrates in the United States and Germany where Hashimoto's thyroiditis screening protocols identify patients earlier, locking in decades-long therapy relationships.
- Antithyroid Drugs:Methimazole and propylthiouracil tablets suppress thyroid hormone synthesis in Graves' disease through thionamide-mediated TPO inhibition. Japan's METI-backed metabolic prevention programs are expanding first-line pharmaceutical management of hyperthyroidism outside surgical referral pathways.
- Radioactive Iodine:I-131 capsules deliver targeted beta radiation for refractory hyperthyroidism and post-surgical thyroid cancer ablation.
- Beta Blockers:Propranolol and atenolol manage adrenergic symptoms during thyrotoxicosis or preoperative preparation.
- Surgery:Thyroidectomy addresses compressive goiter, suspected malignancy, and patient preference for definitive hyperthyroidism cure.
Most installed capacity flows through Thyroid Hormone Replacement. Expansion is steepest in Radioactive Iodine.
Therapy Area:
Volume distribution tracks disease prevalence curves, with margin concentration in oncology adjuvants requiring specialized surgical and nuclear medicine infrastructure.
- Hypothyroidism:Autoimmune thyroiditis and post-ablative hormone deficiency require lifelong T4 supplementation with dose titration against TSH targets. Germany's statutory health insurance funds reimbursement for quarterly monitoring visits sustains patient adherence programs.
- Thyroid Cancer:Differentiated carcinomas command premium pricing through kinase inhibitor adjuvants, recombinant TSH stimulation protocols, and centralized radioactive iodine therapy. The United States concentrates specialized surgical oncology referrals at NCI-designated centers with integrated nuclear medicine departments.
- Hyperthyroidism:Graves' disease and toxic nodular goiter drive antithyroid drug and ablative procedure demand.
- Thyroid Nodules:Ultrasound-guided fine-needle aspiration triages benign from malignant pathology.
- Goiter:Iodine deficiency and multinodular enlargement indicate surgical or expectant management.
Hypothyroidism anchors absolute patient volume. Thyroid Cancer claims the steepest per-patient revenue trajectory.
End User:
Site-of-care migration shifts routine monitoring toward outpatient settings while complex interventions concentrate at academic medical centers.
- Specialty Clinics:Integrated endocrinology networks deploy high-throughput autoantibody screening to capture Hashimoto's patients at diagnosis, compressing traditional primary-care-to-referral pathways. Japan's corporate health screening programs embed TSH testing within annual metabolic panels.
- Hospitals:Inpatient thyroidectomy, radioactive iodine isolation units, and emergency management of thyroid storm require 24-hour endocrinology coverage and nuclear medicine licensing.
- Diagnostic Laboratories:Reference labs process TSH, free T4, anti-TPO, and thyroglobulin antibody panels with automated chemiluminescence platforms.
- Research Institutes:Academic centers conduct Phase I-III trials for long-acting thyroid formulations and novel immunomodulators.
- Wellness Centers:Direct-to-consumer hormone optimization programs operate at the fringe of evidence-based practice.
Specialty Clinics absorb the majority of new patient intake. Hospitals retain the most complex procedural volume.
Delivery Mode:
Patient convenience preferences and pharmacokinetic requirements determine route selection, with oral dominance challenged by adherence gaps in chronic disease.
- Oral:Levothyroxine tablets constitute the default chronic hypothyroidism management route with established bioequivalence frameworks. FDA's narrow therapeutic index requirements sustain brand loyalty despite generic availability.
- Injectable:Intravenous levothyroxine serves myxedema coma and perioperative patients unable to absorb oral formulations.
- Radioiodine Therapy:Oral I-131 capsule administration requires radiation safety protocols and post-therapy isolation capacity.
- Surgical Intervention:Open and minimally invasive thyroidectomy approaches vary by nodule size and surgeon training.
- Transdermal:Experimental patches and gels seek to bypass gastrointestinal absorption variability.
Oral delivery commands the largest installed base. Injectable formulations are gaining share fastest in acute care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained endocrinologists concentrate in urban academic centers across the United States, Germany, and Japan, leaving rural markets dependent on primary care physicians with limited hormone titration expertise. This workforce distribution shapes where diagnostic-treatment bundling and specialty clinic networks achieve deepest penetration.
United States
NCI-designated cancer centers drive differentiated thyroid carcinoma management through integrated surgical oncology and nuclear medicine departments. FDA's narrow therapeutic index requirements for levothyroxine generics sustain brand loyalty despite generic availability. Boston and New York Metro anchor the highest concentration of radioactive iodine therapy facilities.
Germany
Statutory health insurance funds reimbursement for quarterly TSH monitoring visits sustains patient adherence programs for Hashimoto's thyroiditis. EU MDR documentation mandates accelerate consolidation among hormone replacement manufacturers lacking validated electronic batch records. Bavaria and North Rhine-Westphalia host the densest networks of cold-chain certified distributors.
Japan
METI-backed metabolic disease prevention programs expand TSH testing penetration in corporate health screenings and municipal clinics. PMDA pharmacovigilance guidance tightens post-market surveillance for long-acting thyroid formulations. Tokyo and Osaka metropolitan areas concentrate the nation's limited radioactive iodine production capacity.
Brazil
ANVISA's streamlined registration pathway for hormone therapies opens access to autoimmune thyroiditis patients previously reliant on importation. Underpenetration in specialty endocrinology networks outside São Paulo and Rio de Janeiro creates whitespace for direct-to-patient pharmacy channels. Minas Gerais and Paraná are emerging as distribution hubs for cold-chain biologic thyroid extracts.
India
CDSCO bioequivalence requirements for levothyroxine generics create sustained barriers to interchangeability claims, entrenching incumbent pricing power. Domestic API manufacturing clusters in Hyderabad and Ahmedabad supply synthetic thyroid hormone active pharmaceutical ingredients to global formulators. Maharashtra and Gujarat concentrate contract research organizations conducting Phase I-III trials for novel immunomodulators.
Global Thyroid Disorder Market Competitive Landscape
Top-tier vendors anchor synthetic hormone manufacturing scale, while mid-size distributors struggle to fund EU GDP compliance for biologic thyroid extracts. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with immunology infrastructure, specialized endocrinology channel operators, and regional generic formulators. Two dominant competitive moves are reshaping positioning: diagnostic-treatment bundling through companion diagnostic partnerships, and backward integration into API synthesis to mitigate single-source disruption risk.
Within the multinational tier, Pfizer Inc. and AbbVie Inc. exemplify divergent strategic archetypes. Pfizer Inc. represents manufacturing-scale players sustaining multiple active pharmaceutical ingredient sources for synthetic thyroid hormones. AbbVie Inc. occupies a position leveraging immunology infrastructure to cross-sell thyroid autoimmunity testing with hormone therapy protocols. Merck KGaA anchors European distribution specialization, sitting within the channel-certification tier that requires cold-chain integrity credentials for specialized endocrinology networks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Merck KGaA |
| GSK Plc |
| Novartis AG |
| Allergan Plc. |
| Sanofi |
| Amgen Inc. |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Depot injection technologies and polymer-based sustained-release platforms are compressing manufacturing cost curves while concentrating production capacity among formulators with validated cold-chain infrastructure. This dual shift simultaneously reduces per-unit production economics and raises barriers for mid-size distributors lacking GDP-certified temperature monitoring systems.
Pricing Analysis
The bundled-vs-unbundled service split separates diagnostic-treatment packages from standalone hormone prescriptions. Three-tier pricing structure across premium biologics, certified synthetic formulations, and commodity generics reflects cold-chain certification and companion diagnostic inclusion. Cost compression in the generic levothyroxine tier is intensifying because of bioequivalence testing requirements and API sourcing competition. Primary care networks exhibit highest price sensitivity, while academic medical centers prioritize formulation stability over unit cost.
Supply Chain Analysis
EU GDP and FDA 21 CFR Part 11 certification gating is eliminating uncertified distributors and consolidating volume toward validated electronic batch record holders. Synthetic thyroid hormone APIs concentrate in Indian and Chinese manufacturing clusters, with European formulators dependent on these sources for levothyroxine sodium. Supply chain risk centers on single-source API vulnerability given limited alternative synthesis capacity. Distribution runs through cold-chain certified specialty pharmacy channels in Germany and direct-to-patient mail-order platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in thyroid therapeutics rests on the shift from daily oral dosing toward long-acting formulations commanding premium reimbursement, compounded by diagnostic bundling that captures lifetime patient value at diagnosis.
For Market Incumbents: Anticipate regulatory consolidation by securing EU MDR documentation and validated electronic batch records ahead of enforcement deadlines. Backward integration into API synthesis mitigates single-source disruption risk from Indian and Chinese supply clusters. Cold-chain integrity certification investments defend position against emerging biologic thyroid extract competitors.
For New Entrants and Emerging Players: Specialty clinic networks in Brazil's Minas Gerais and Paraná states represent the most penetrable channel, given ANVISA's streamlined registration pathway and underdeveloped endocrinology infrastructure outside São Paulo. Direct-to-patient pharmacy partnerships bypass traditional hospital gatekeepers and capture Hashimoto's patients at diagnosis through bundled TSH testing and levothyroxine initiation protocols.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size distributors lacking GDP compliance but holding established endocrinology channel relationships. Long-term viability hinges on regulatory certification completion and companion diagnostic platform integration. The signal to monitor is EMA pharmacovigilance guidance implementation for long-acting formulations, which will reshape marketing authorization renewal requirements and patient registry data obligations.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Bundling | Anti-TPO antibody assay partnerships with levothyroxine protocols lock in decades-long therapy relationships at Hashimoto's diagnosis. |
| Long-Acting Formulation Development | Depot injection platforms reduce dosing frequency from daily to monthly, enabling premium pricing and improved adherence metrics. |
| API Backward Integration | In-house synthesis of synthetic thyroid hormones mitigates single-source concentration risk in Chinese and Indian manufacturing clusters. |
| Cold-Chain Certification Investment | EU GDP compliance for biologic thyroid extracts opens access to specialized endocrinology networks requiring validated temperature monitoring. |
| Direct-to-Patient Channel Expansion | Mail-order pharmacy platforms bypass hospital pharmacy gatekeepers in Germany and the United States, capturing recurring prescription volume. |
Research Methodology
Direct dialogue with endocrinology practice administrators, formulary directors at statutory health insurance funds, regulatory affairs specialists at hormone replacement manufacturers, and GPO contracts managers grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EMA marketing authorization databases, ClinicalTrials.gov protocol registries, and hospital procurement databases. Bottom-up patient volume estimates and top-down pharmaceutical spending trajectories were triangulated against manufacturer shipment data and reimbursement code utilization.
Bottom-up modeling segmented the market by product type, therapy area, end user, and delivery mode, with cross-validation against regional regulatory cluster adoption patterns. CAGRs were derived from trend extrapolation of quarterly prescription volumes and pricing trajectories across the projection horizon. Forecast inputs incorporated EU MDR implementation timelines, METI screening program expansion rates, and ANVISA registration pathway efficiency.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacovigilance guidance evolution and radioactive iodine production capacity constraints. A model refresh is warranted upon material change in EMA long-acting formulation surveillance requirements or API supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Generalized Myasthenia Gravis (GMG) Management Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market