
 Primary Immunodeficiency Market | 2026-2036
Primary Immunodeficiency Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Immunodeficiency Market Outlook
The EU Green Deal is expanding sustainability requirements for plasma-derived medicinal products, compelling manufacturers to decarbonize fractionation facilities and secure certified plasma supply chains. CSL Behring leverages its vertically integrated plasma collection network across multiple continents to sustain volume leadership in immunoglobulin therapies. Takeda Pharmaceutical anchors its position through specialized rare disease commercial infrastructure and deep hematology channel relationships. Grifols competes by operating one of the industry's largest plasma fractionation footprints, with manufacturing scale that supports both intravenous and subcutaneous product lines.
Primary immunodeficiency comprises a heterogeneous group of inherited disorders characterized by defective innate or adaptive immune function, typically diagnosed through quantitative immunoglobulin assays, lymphocyte subset analysis, and genetic sequencing to identify mutations in genes encoding immune signaling proteins, complement factors, or cellular effector mechanisms. These conditions require lifelong therapeutic intervention to prevent recurrent infections, autoimmune complications, and malignancy risk. Immunoglobulin replacement therapy dominates the product type landscape as the established standard of care with mature reimbursement pathways, while gene therapy represents the fastest-expanding segment as clinical programs for X-linked agammaglobulinemia and severe combined immunodeficiency advance toward commercialization. The end user structure tilts toward hospitals for initial diagnosis and acute infusion management, though homecare channels capture expanding volume as subcutaneous delivery modes reduce facility dependency.
FDA orphan drug designations and EMA rare disease incentives shape clinical trial investment and market exclusivity timelines for novel primary immunodeficiency therapies, while WHO International Nonproprietary Name biological qualifiers and ISO plasma collection standards govern product traceability and viral safety documentation. The EU AI Act introduces compliance obligations for diagnostic algorithms used in newborn screening programs that identify severe combined immunodeficiency through T-cell receptor excision circle quantification. Stakeholders must monitor gene therapy durability data and payer willingness to fund one-time curative interventions against chronic immunoglobulin replacement economics.
Market Dynamics
Plasma supply concentration across the United States, Germany, and Czech Republic is forcing manufacturers to secure captive collection networks or face fractionation capacity idling. This supply-side bottleneck is reshaping competitive positioning more than product differentiation.
Growth Catalysts
- EMA rare disease incentives:Orphan drug designation accelerates clinical trial investment for gene therapies targeting X-linked agammaglobulinemia, compressing regulatory timelines.
- Homecare nursing infrastructure:Subcutaneous immunoglobulin delivery modes reduce hospital dependency and expand addressable patient populations in rural catchment areas.
- EU Green Deal procurement mandates:Public tenders now require certified sustainable plasma supply chains, favoring vertically integrated collectors with carbon-audited fractionation facilities.
Market Restraints
- Plasma collection concentration:Over 70% of source plasma originates from US paid-donor centers, creating geopolitical and viral screening concentration risk.
- Gene therapy durability uncertainty:Long-term efficacy data for lentiviral and CRISPR-based approaches remains immature, constraining payer willingness to fund curative interventions.
- REACH chemical compliance:Solvent and reagent used in protein fractionation face tightening ECHA registration requirements, elevating production complexity.
Strategic Opportunities
- India plasma infrastructure:Underpenetrated voluntary donor networks and emerging CDSCO regulatory pathways offer first-mover advantages for fractionation joint ventures.
- WHO International Nonproprietary Name biological qualifiers:Standardized traceability documentation opens procurement access across Gulf Cooperation Council national formularies.
- AI-enabled newborn screening:T-cell receptor excision circle quantification algorithms integrated into national health programs expand early diagnosis capture rates.
Industry Challenges
- Genetic counselor workforce scarcity:Complex immunodeficiency diagnoses require specialized interpretation of sequencing variants, creating diagnostic bottlenecks.
- Cold chain integrity for biologics:Immunoglobulin stability requirements demand validated 2-8°C distribution infrastructure across last-mile homecare networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Immunodeficiency Market |
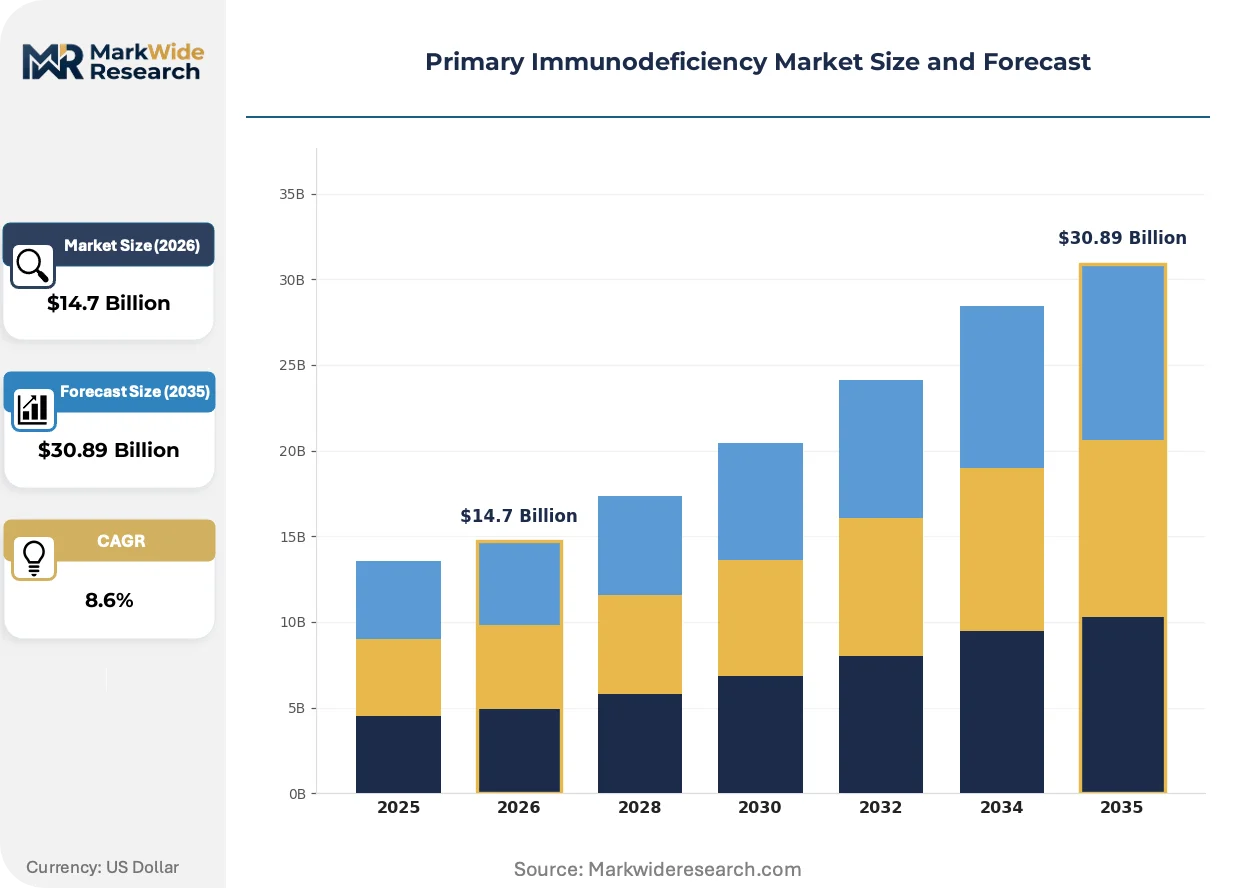
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Antibody Deficiency, Cell-Mediated Deficiency, Combined Deficiency, Autoinflammatory Disorders End User: Hospitals, Clinics, Homecare, Diagnostic Laboratories Product Type: Immunoglobulin Therapy, Gene Therapy, Cell Therapy, Enzyme Replacement Therapy Delivery Mode: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | CSL Behring, Takeda Pharmaceutical, Grifols, Octapharma, Baxter International, ADMA Biologics, Kedrion Biopharma, Bio Products Laboratory, Biotest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Immunodeficiency Market Strategic Shifts
Gene therapy platforms are compressing the chronic replacement paradigm, while diagnostic algorithms and sustainable manufacturing standards are rewriting procurement criteria and facility investment decisions.
Recombinant immunoglobulin production from cell culture systems is rewriting the plasma dependency model for select indications. Biotech developers in Switzerland and the Netherlands are advancing CHO-based platforms toward Phase III, targeting niches where plasma supply constraints bite hardest. This technology is rewriting margin structures by decoupling volume growth from donor pool expansion.
The EU AI Act imposes conformity assessment obligations on diagnostic algorithms used in newborn screening programs for severe combined immunodeficiency. Manufacturers must now document algorithmic transparency and bias mitigation for T-cell receptor excision circle quantification tools. French and German screening laboratories are recalibrating procurement specifications to prioritize CE-marked AI diagnostic modules.
Patient advocacy groups are consolidating purchasing influence through specialty pharmacy benefit managers, unbundling traditional hospital infusion contracts. United States commercial payers are steering volume toward homecare channels with documented adherence monitoring capabilities. This behavioral shift concentrates most visibly in Medicare Advantage plans with dedicated rare disease management programs.
Primary Immunodeficiency Market Segmentation
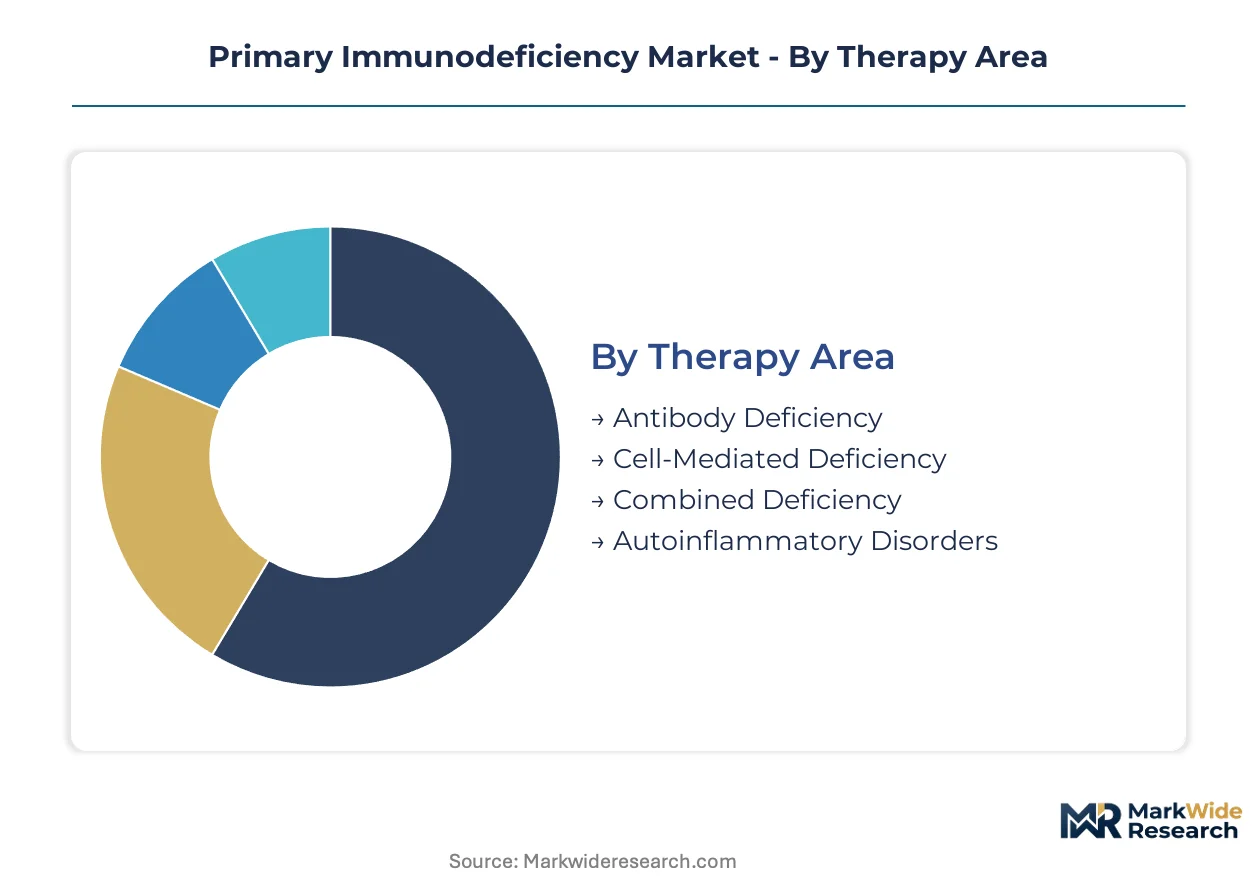
Primary immunodeficiency treatment selection hinges on disease mechanism, patient stability, and reimbursement pathway maturity. Segment boundaries blur as gene therapy candidates target antibody deficiencies and homecare infrastructure expands across delivery modes.
Therapy Area:
EMA orphan drug designation and FDA breakthrough therapy status cluster differently across these indications, shaping clinical trial investment and payer negotiation leverage.
- Antibody Deficiency:X-linked agammaglobulinemia and common variable immunodeficiency comprise the addressable population for immunoglobulin replacement. CSL Behring and Takeda concentrate promotional resources here due to established reimbursement and mature diagnostic codes.
- Cell-Mediated Deficiency:Defects in T-cell development or function require distinct therapeutic approaches including hematopoietic stem cell transplantation. Demand concentrates in tertiary referral centers with transplant accreditation.
- Combined Deficiency:Severe combined immunodeficiency represents the urgent intervention segment with newborn screening expansion driving incident case capture. SCID requires immediate hematopoietic stem cell transplantation or experimental gene therapy protocols.
- Autoinflammatory Disorders:Periodic fever syndromes and interferonopathies respond to targeted cytokine inhibition rather than immunoglobulin replacement.
Antibody Deficiency sits at the top of the volume ranking, with Combined Deficiency climbing the fastest.
End User:
Site-of-care economics and nursing workforce availability determine competitive access across these channels.
- Hospitals:Acute infusion management, diagnostic workup, and transplant coordination anchor institutional volume. Centers with dedicated immunology units capture complex case referrals from regional networks.
- Clinics:Outpatient infusion suites bridge hospital capability and homecare convenience for patients requiring monitoring during immunoglobulin loading.
- Homecare:Subcutaneous immunoglobulin delivery reduces facility dependency and expands rural access where specialty pharmacy nursing networks exist. Medicare Advantage rare disease management programs steer volume here.
- Diagnostic Laboratories:T-cell receptor excision circle quantification and next-generation sequencing panels flow through reference laboratories with CAP/CLIA accreditation.
Hospital channels retain the highest per-patient revenue intensity, though Homecare gains share fastest as subcutaneous products mature.
Product Type:
Manufacturing complexity and plasma supply dependency create divergent margin structures across these modalities.
- Immunoglobulin Therapy:Plasma-derived and recombinant formulations dominate current utilization with fractionation capacity constraints determining competitive availability. Grifols and CSL Behring sustain volume leadership through captive plasma collection networks.
- Gene Therapy:Lentiviral and CRISPR-based approaches for X-linked agammaglobulinemia and SCID are advancing through registrational trials. Durability data will determine payer willingness to fund curative interventions against chronic replacement economics.
- Cell Therapy:Allogeneic and autologous hematopoietic stem cell transplantation remains standard for severe combined immunodeficiency.
- Enzyme Replacement Therapy:Adenosine deaminase deficiency represents the addressable niche where pegademase bovine provides functional immune reconstitution.
Immunoglobulin Therapy commands the revenue base, with Gene Therapy positioned for the steepest expansion trajectory contingent on durability confirmation.
Delivery Mode:
Patient training burden and cold chain requirements differentiate competitive positioning across administration routes.
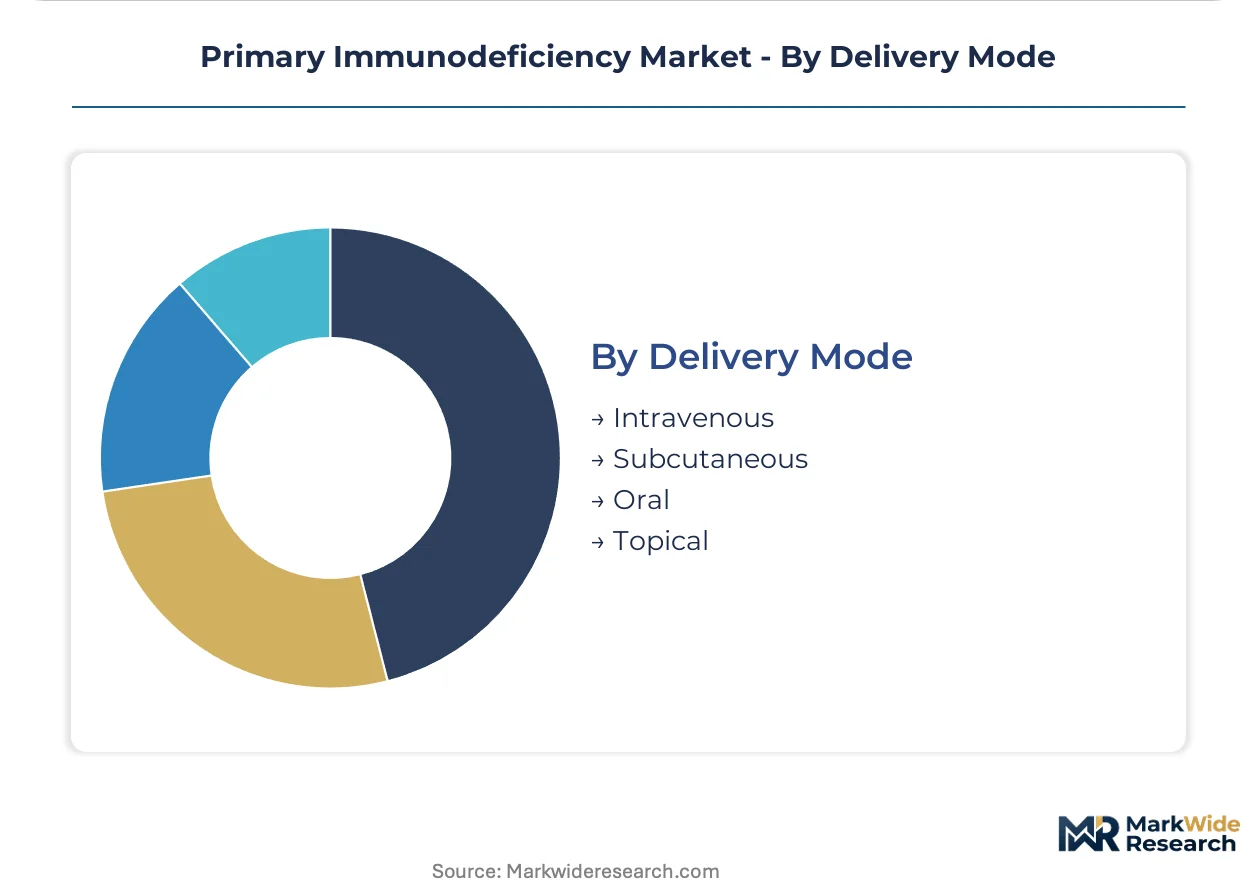
- Intravenous:Monthly high-dose infusions require facility-based administration or home nursing visits with infusion pump capability. Hospital contracts and specialty pharmacy networks determine access.
- Subcutaneous:Weekly or biweekly self-administration via portable pumps reduces facility dependency and enables rural patient management. Grifols and CSL Behring compete on infusion volume and needle set design.
- Oral:No approved immunoglobulin formulations exist; supportive therapies including prophylactic antibiotics occupy this channel.
- Topical:Limited to adjunctive infection management in select antibody deficiencies with mucocutaneous complications.
Intravenous delivery retains the installed base, while Subcutaneous modalities expand most quickly as patient training programs and pump technology improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The plasma fractionation industry traces its modern origins to Cohn's ethanol precipitation methods developed at Harvard Medical School during the 1940s, with subsequent scaling concentrated in the United States and Germany. Today's geographic distribution reflects this dual heritage, with manufacturing clusters anchored by historical fractionation expertise and captive plasma collection infrastructure.
United States
Specialty pharmacy networks and Medicare Advantage rare disease management programs drive subcutaneous immunoglobulin penetration. FDA orphan drug designations accelerate gene therapy development timelines for X-linked agammaglobulinemia. The Research Triangle Park cluster in North Carolina hosts diagnostic laboratories scaling T-cell receptor excision circle quantification for newborn screening expansion.
Germany
EMA rare disease incentives and national reimbursement stability sustain immunoglobulin demand across antibody deficiency indications. REACH chemical compliance requirements elevate production complexity for solvent-based protein fractionation. The Frankfurt-Rhine-Main biotech corridor concentrates plasma collection center operations and fractionation facility investment.
France
ANSM oversight of plasma-derived medicinal products maintains stringent viral safety documentation standards. The EU AI Act imposes conformity assessment obligations on newborn screening algorithms for severe combined immunodeficiency detection. Paris-based reference laboratories recalibrate procurement specifications toward CE-marked AI diagnostic modules.
United Kingdom
NHS England's specialized commissioning framework directs immunoglobulin utilization toward evidence-based indications. The Medicines and Healthcare products Regulatory Agency governs traceability documentation for plasma supply chains. London's tertiary immunology centers coordinate national diagnostic networks and transplant referral pathways.
India
Underpenetrated voluntary donor networks and emerging CDSCO regulatory pathways attract fractionation joint venture interest. The country's national pharmaceutical regulator is harmonizing plasma collection standards with WHO International Nonproprietary Name biological qualifier requirements. Maharashtra's emerging biopharma corridor hosts contract manufacturing discussions for recombinant immunoglobulin platforms.
Primary Immunodeficiency Market Competitive Environment
Premium-margin players sit above commodity-margin players across plasma supply security and fractionation scale dimensions. The market structure concentrates around vertically integrated collectors with captive donor networks and independent fractionators dependent on contracted plasma supply. Three archetypes dominate: plasma collection network owners, specialized rare disease commercializers, and recombinant platform developers. Competitive moves center on securing captive plasma supply through collection network expansion and decarbonizing fractionation facilities to meet EU Green Deal procurement mandates.
Among plasma-derived therapy specialists, CSL Behring, Takeda Pharmaceutical, and Grifols occupy positions reflecting distinct strategic emphases. CSL Behring exemplifies the vertically integrated archetype through its multi-continent plasma collection infrastructure. Takeda Pharmaceutical represents the rare disease commercialization specialist model with established hematology channel relationships. Grifols anchors the scale-driven fractionation tier with manufacturing footprint supporting multiple delivery modalities.
| Leading Market Players |
|---|
| CSL Behring |
| Takeda Pharmaceutical |
| Grifols |
| Octapharma |
| Baxter International |
| ADMA Biologics |
| Kedrion Biopharma |
| Bio Products Laboratory |
| Biotest |
| Others |
Value Chain & Pricing Dynamics
Plasma collection labor costs in United States paid-donor centers cascade through fractionation economics to differentiate immunoglobulin pricing tiers across hospital, specialty pharmacy, and homecare channels. This input-cost transmission shapes margin structures more acutely than formulation innovation, concentrating pricing power with vertically integrated collectors who control donor pool access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified sustainable plasma from conventional supply and from recombinant alternatives entering Phase III. Price differentiation rests on EU Green Deal carbon audit certification and captive plasma collection network scale. Cost compression in standard-tier immunoglobulin intensifies as REACH chemical compliance elevates solvent-based fractionation expenses. Hospital buyers exhibit highest price sensitivity due to formulary budget constraints, while specialty pharmacy channels absorb premium pricing for documented adherence monitoring capabilities.
Supply Chain Analysis
Domestic-content mandates in EU public procurement are redirecting sourcing toward certified European plasma collection networks and away from pure US dependency. Geographic supply concentration centers on the United States, Germany, and Czech Republic for source plasma, with fractionation capacity clustering in these same markets. Raw material dependencies span plasma donor pools, ethanol precipitation solvents, and viral inactivation reagents. Single-source vulnerability concentrates in US paid-donor center networks, where over 70% of global source plasma originates. Distribution runs through hospital-based infusion programs, specialty pharmacy channels, and emerging homecare nursing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The primary immunodeficiency market compounds steadily as gene therapy durability data matures and chronic replacement economics sustain long-term revenue visibility. Plasma supply security and fractionation decarbonization represent the durable value drivers across the analysis window.
For Market Incumbents: Lock in captive plasma collection network expansion across multiple continents to defend against recombinant platform displacement. Secure EU Green Deal carbon audit certification for fractionation facilities to maintain public procurement eligibility. Prioritize backward integration into diagnostic laboratory partnerships controlling newborn screening algorithm procurement. For New Entrants and Emerging Players: Rural Medicare Advantage subscribers represent an underserved buyer archetype with limited homecare nursing infrastructure penetration. Target subcutaneous immunoglobulin delivery training programs as the most penetrable service layer, leveraging portable pump technology to bypass hospital contract barriers. Pursue joint venture structures with established specialty pharmacy networks rather than building de novo distribution. For Investors and Strategic Acquirers: Consolidation pressure builds where plasma collection network scale determines fractionation capacity utilization and margin sustainability. Frame long-term viability around 5-10 year gene therapy durability readouts against chronic replacement paradigms. Target acquisition profiles emphasizing CDSCO-registered plasma infrastructure in underpenetrated voluntary donor markets. Monitor T-cell receptor excision circle quantification algorithm procurement specifications as the signal indicating newborn screening program expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | CSL Behring's multi-continent donor center scaling secures volume leadership against supply constraints. |
| EU Green Deal Certification Program | Grifols' carbon-audited fractionation facilities meet public procurement mandates in Germany and France. |
| Gene Therapy Clinical Advancement | Lentiviral platform durability data for X-linked agammaglobulinemia will reshape payer economics. |
| Homecare Nursing Partnership | Medicare Advantage rare disease management programs steer immunoglobulin volume toward subcutaneous delivery. |
| AI Diagnostic Module Development | CE-marked T-cell receptor excision circle algorithms capture newborn screening procurement in Paris laboratories. |
Study Parameters
Direct dialogue with plasma collection center operators, fractionation facility managers, specialty pharmacy benefit directors, and immunology clinic procurement leads grounded qualitative insights in operational reality. Secondary validation drew from FDA orphan drug filings, EMA rare disease incentive documentation, ClinicalTrials.gov gene therapy protocols, and CMS Medicare Advantage plan formularies. Bottom-up patient population modeling and top-down plasma supply-demand balancing triangulated volume estimates across therapy areas and delivery modes.
Segment-level projections emerged from cross-referencing immunoglobulin replacement patient counts, gene therapy clinical pipeline advancement, and newborn screening expansion trajectories over the projection horizon. CAGRs derived from regression analysis against historical plasma collection growth rates and reimbursement pathway maturity indices. Modeled inputs included EMA orphan drug designation timelines, REACH chemical compliance cost curves, and EU AI Act diagnostic algorithm procurement specifications.
Underlying measurement precision varies by segment; antibody deficiency immunoglobulin therapy carries tighter precision than emerging gene therapy commercialization forecasts. Projections embed assumptions regarding payer willingness to fund curative interventions against chronic replacement economics, and gene therapy durability data maturation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Pigmentosa Treatment Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Perennial Allergic Rhinitis Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Monoclonal Antibody Therapy Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market