
 Serotonin Syndrome Market | 2026-2036
Serotonin Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Serotonin Syndrome Market Analytics
EMA's tightened pharmacovigilance guidelines for serotonergic agents is repositioning the competitive threshold for market participants. Pfizer Inc. leverages its established neurology infrastructure to sustain manufacturing scale across multiple continents. Eli Lilly and Company anchors its position through specialized R&D intensity in psychiatric pharmacology. AstraZeneca differentiates via controlled distribution networks for high-risk therapeutic categories.
Serotonin syndrome constitutes a potentially life-threatening drug-induced condition characterized by excessive serotonergic activity in the central and peripheral nervous systems, typically manifesting through mental status changes, autonomic hyperactivity, and neuromuscular abnormalities following therapeutic or supratherapeutic exposure to serotonergic medications. The condition demands immediate clinical recognition because delayed intervention escalates mortality risk, driving institutional investment in diagnostic protocols and reversal-agent formularies. Among therapy areas, depression and chronic pain generate the largest patient pools exposed to combination serotonergic regimens, while the opioids segment within product types carries disproportionate syndrome incidence due to frequent polypharmacy with antidepressants. Oral delivery mode dominates prescription volume, though intravenous administration commands premium positioning in acute emergency settings where rapid intervention proves critical.
FDA pharmacovigilance mandates and EMA's Periodic Safety Update Report requirements shape manufacturer obligations for risk communication and post-market surveillance across serotonergic drug portfolios. The WHO's International Classification of Diseases coding standards influence hospital reimbursement and epidemiological tracking precision for adverse drug events. Stakeholders must monitor evolving regulatory divergence between jurisdictions to anticipate compliance cost trajectories and formulary access conditions.
Market Dynamics
FDA pharmacovigilance mandates are intensifying manufacturer compliance burdens as serotonergic drug portfolios expand across psychiatric and pain management categories. Hospital formularies now prioritize adverse-event monitoring infrastructure over pure therapeutic efficacy in procurement decisions.
Growth Catalysts
- Enhanced FDA Adverse Event Reporting:Mandatory electronic submission requirements for serotonergic agents are driving institutional investment in pharmacovigilance software and specialized clinical pharmacy staffing.
- Polypharmacy in Chronic Pain:Rising concurrent prescriptions of antidepressants and opioid analgesics are expanding the at-risk patient population requiring syndrome recognition protocols.
- Emergency Department Triage Protocols:Standardized diagnostic algorithms for serotonin syndrome are shortening time-to-treatment and improving clinical outcomes in acute care settings.
Market Restraints
- Specialized Diagnostic Cost Burden:Serum serotonin metabolite testing and neuromuscular monitoring equipment impose capital constraints on smaller hospital systems.
- Reimbursement Fragmentation:Inconsistent ICD-10-CM coding recognition across US commercial payers creates claims denial risk for syndrome-related interventions.
- Off-Label Substitution Pressure:Non-serotonergic alternatives for depression and pain management are gaining formulary preference in risk-averse institutions.
Strategic Opportunities
- Telemedicine Triage Integration:Remote patient monitoring platforms are embedding algorithmic screening tools for early syndrome detection in polypharmacy patients.
- EMA Pharmacovigilance Harmonization:Periodic Safety Update Report standardization across European markets is creating compliance service demand for multinational manufacturers.
- Point-of-Care Testing Development:Rapid diagnostic assays for hyperthermia and clonus assessment are opening ambulatory and pre-hospital market entry.
Industry Challenges
- Clinical Pharmacology Talent Scarcity:Shortage of board-certified toxicologists and clinical pharmacists limits expansion of hospital-based syndrome management programs.
- Legacy EHR Integration Friction:Adverse-event alert systems require costly customization to interface with heterogeneous electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serotonin Syndrome Market |
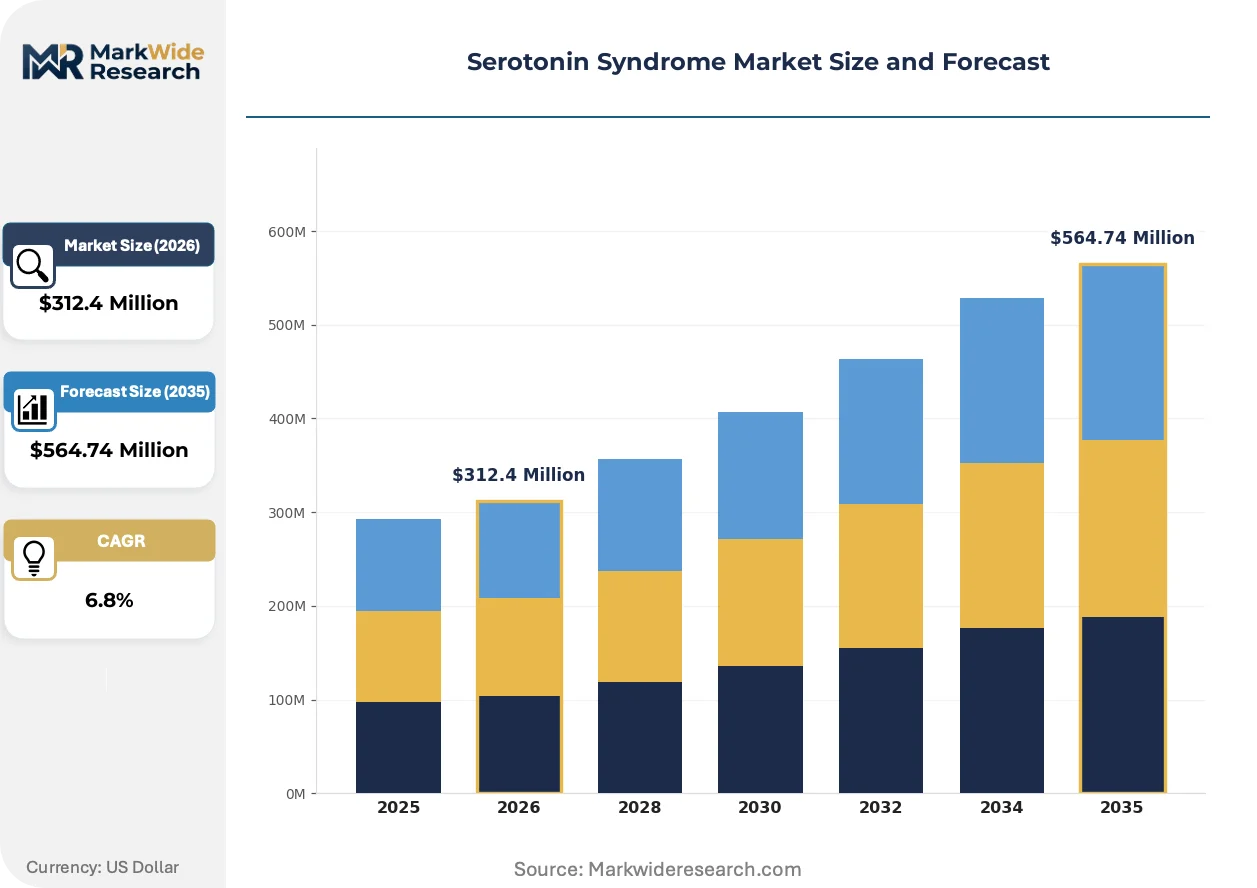
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSRIs, SNRIs, TCAs, Opioids Therapy Area: Depression, Anxiety Disorders, Chronic Pain, Bipolar Disorder Delivery Mode: Oral, Intravenous, Transdermal, Inhalation End User: Hospitals, Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | Johnson & Johnson, AstraZeneca, Eli Lilly and Company, Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline plc, Bristol-Myers Squibb, Novartis AG, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serotonin Syndrome Market Evolving Landscape
Digital biomarker platforms are compressing diagnostic latency for drug-induced toxidromes. Real-time physiological monitoring is displacing retrospective chart review as the standard of care in high-risk prescribing environments.
Multiparameter wearable sensors are unifying continuous temperature, heart rate variability, and tremor detection into single-platform patient surveillance. Academic medical centers in the United States are piloting these systems for outpatient antidepressant initiation protocols. This convergence is unifying previously siloed vital sign streams into integrated risk scoring that triggers preemptive clinical intervention.
EMA's strengthened Periodic Safety Update Report requirements are mandating standardized signal detection methodologies across serotonergic drug classes. Manufacturers must now submit cumulative adverse event analyses at fixed intervals regardless of individual product risk profiles. Small and mid-sized pharmaceutical firms without dedicated pharmacovigilance infrastructure are outsourcing compliance to specialized contract research organizations.
Hospital procurement committees are elevating drug-drug interaction screening capability above unit cost in formulary evaluations. Third-party clinical decision support modules are displacing native electronic health record alerts in competitive vendor assessments. This preference shift is most pronounced in US health systems managing substantial Medicaid populations with complex polypharmacy profiles.
Serotonin Syndrome Market Segmentation
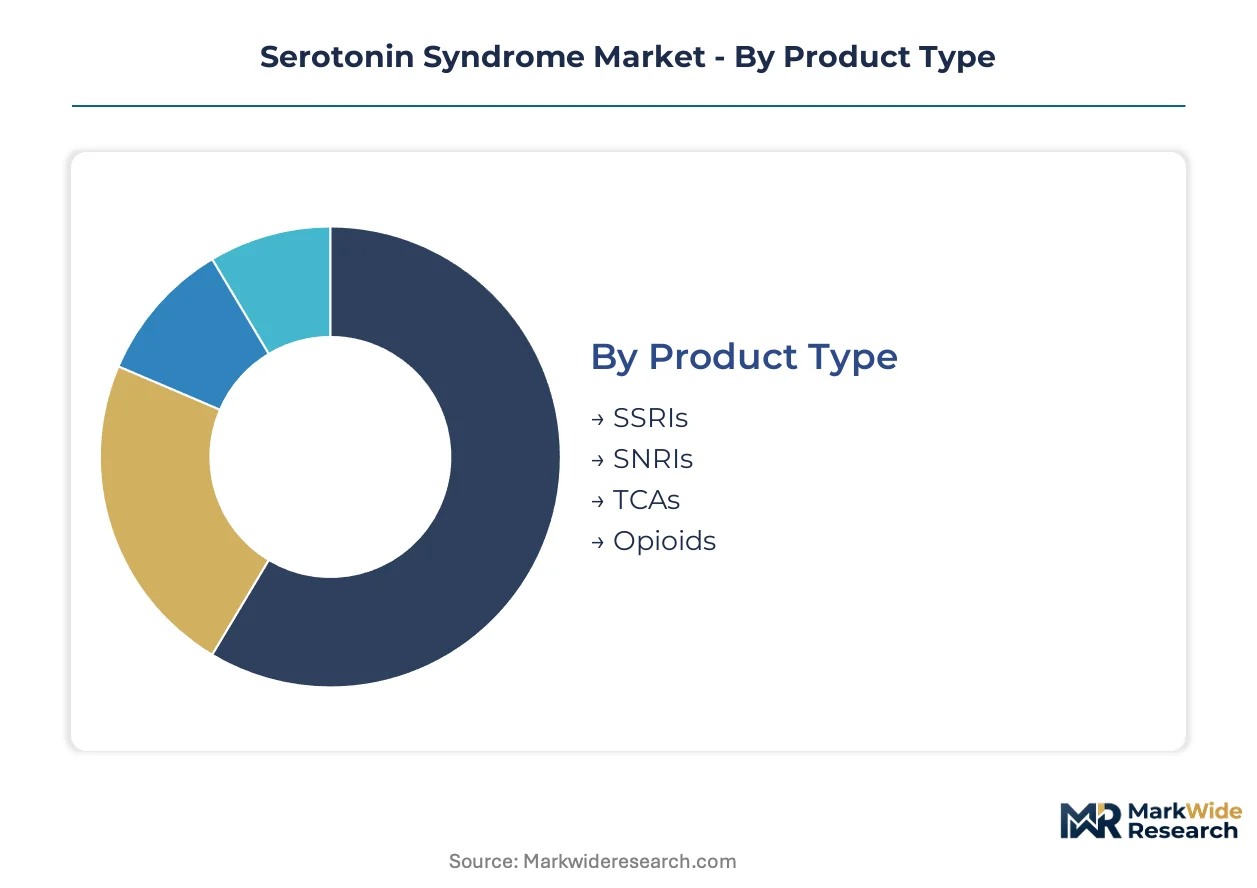
Serotonin syndrome risk profiles vary sharply across drug classes and care settings, demanding granular segmentation for targeted pharmacovigilance investment. Hospital formulary committees and emergency departments require distinct protocols for each product type and delivery mode to manage adverse event recognition and reversal agent stocking.
Product Type:
Standardization dominates high-volume antidepressant classes, while specialized monitoring protocols concentrate around agents with narrow therapeutic indices or frequent polypharmacy exposure.
- SSRIs:Selective serotonin reuptake inhibitors constitute the most prescribed antidepressant class, with fluoxetine and sertraline driving substantial exposure volume in outpatient depression management. Risk concentrates in elderly patients receiving concurrent antiplatelet therapy or CYP2D6 inhibitors, where metabolic competition elevates serum levels and syndrome incidence.
- Opioids:Tramadol, fentanyl, and meperidine carry disproportionate serotonin syndrome liability through dual SNRI activity or metabolite accumulation. Demand for adverse event monitoring concentrates in perioperative and chronic pain settings where these agents combine routinely with SSRIs.
- SNRIs:Serotonin-norepinephrine reuptake inhibitors including duloxetine and venlafaxine present dose-dependent syndrome risk amplified by renal impairment.
- TCAs:Tricyclic antidepressants such as amitriptyline and clomipramine generate syndrome through potent serotonin reuptake blockade alongside anticholinergic toxicity.
Most installed capacity flows through SSRIs. Expansion is steepest in Opioids.
Therapy Area:
Volume scales with chronic disease prevalence, while syndrome recognition complexity tracks with psychiatric comorbidity density and medication regimen intricacy.
- Depression:Major depressive disorder generates the largest patient population exposed to serotonergic monotherapy and combination regimens, with treatment-resistant cases requiring augmentation strategies that elevate syndrome risk. Demand for monitoring infrastructure concentrates in United States integrated delivery networks managing substantial Medicaid populations with complex polypharmacy.
- Chronic Pain:Fibromyalgia, neuropathic pain, and osteoarthritis drive prolonged exposure to SNRIs, TCAs, and serotonergic opioids in overlapping therapeutic windows. Risk recognition protocols are expanding fastest in ambulatory surgical centers and pain management clinics where anesthesia handoffs create information discontinuity.
- Anxiety Disorders:Generalized anxiety and panic disorder maintenance therapy involves long-acting SSRIs with lower per-dose syndrome incidence but cumulative exposure concerns.
- Bipolar Disorder:Mood stabilization with serotonergic augmentation introduces syndrome risk during manic phase medication adjustments and lithium interactions.
Depression captures the largest installed base. Chronic Pain is gaining share fastest.
Delivery Mode:
Route selection determines pharmacokinetic emergency windows and reversal agent accessibility, with acute care settings commanding premium positioning for rapid-intervention modalities.
- Oral:Tablet and capsule formulations dominate prescription volume across all serotonergic classes, enabling outpatient initiation and maintenance with established bioavailability profiles. Demand concentrates in retail pharmacy and mail-order channels where drug interaction screening software serves as the primary risk mitigation layer.
- Intravenous:Parenteral administration commands critical care formulary positioning for perioperative analgesia, emergency sedation, and rapid antidepressant loading protocols. United States academic medical centers are expanding neuromuscular monitoring and temperature surveillance capabilities specifically for IV serotonergic exposure in emergency departments.
- Transdermal:Patch delivery systems for selegiline and fentanyl introduce absorption variability and depot effects complicating syndrome timeline prediction.
- Inhalation:Nasal and inhaled serotonergic formulations remain limited but growing in migraine and acute pain applications with rapid onset profiles.
Oral administration handles most volume. Intravenous is expanding most quickly.
End User:
Care setting determines monitoring infrastructure sophistication, with institutional scale driving adverse event detection capability and reversal agent formulary depth.
- Hospitals:Inpatient facilities maintain the most comprehensive syndrome management protocols, integrating pharmacy surveillance, clinical decision support alerts, and toxicology consultation services. United States health systems with level I trauma designation are investing in dedicated clinical pharmacology staffing and rapid cyproheptadine access.
- Clinics:Outpatient specialty and primary care settings manage the largest denominator of at-risk patients with limited real-time monitoring capability. Demand for telemedicine triage integration and patient-facing risk education tools is concentrating in United States federally qualified health centers serving high-polypharmacy populations.
- Home Care:Skilled nursing and home health services manage post-acute serotonergic therapy with variable nursing oversight and delayed recognition risk.
- Rehabilitation Centers:Substance use and physical rehabilitation facilities encounter syndrome risk during opioid tapering and psychiatric medication reintroduction.
Hospitals deploy the deepest monitoring infrastructure. Clinics are scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical pharmacology specialists cluster in the United States, Germany, Japan, and the United Kingdom, anchoring pharmacovigilance infrastructure for serotonergic drug monitoring. Hospital systems in these markets maintain the deepest adverse-event detection capabilities and reversal-agent formularies.
United States
Academic medical centers in Boston and Baltimore pilot wearable-based outpatient monitoring for antidepressant initiation protocols. FDA pharmacovigilance mandates for serotonergic agents intensify manufacturer compliance burdens and drive institutional investment in specialized clinical pharmacy staffing. Level I trauma centers in Texas and California expand dedicated toxicology consultation services.
Germany
EMA Periodic Safety Update Report requirements shape manufacturer obligations for risk communication across serotonergic portfolios. The country's national pharmaceutical regulator enforces standardized signal detection methodologies that small and mid-sized firms outsource to contract research organizations. Industrial concentration in Baden-Württemberg and Bavaria hosts pharmacovigilance service clusters.
Japan
PMDA post-market surveillance protocols for psychiatric medications mandate adverse-event reporting infrastructure that domestic manufacturers must maintain. Tokyo and Osaka academic hospitals integrate clinical decision support modules for drug-drug interaction screening in polypharmacy patients. METI guidelines influence hospital procurement prioritization of monitoring capability over unit cost.
United Kingdom
NHS integrated care systems in London and Manchester deploy algorithmic triage tools for early syndrome detection in high-polypharmacy populations. MHRA pharmacovigilance requirements align with EMA standards while maintaining distinct national reporting pathways. Scotland's health boards pilot telemedicine integration for remote patient monitoring.
Canada
Health Canada pharmacovigilance frameworks for serotonergic drugs require manufacturer risk management plans that parallel FDA and EMA structures. Ontario and Quebec health systems invest in neuromuscular monitoring equipment for emergency department syndrome recognition. Toronto academic centers anchor clinical toxicology training programs.
Serotonin Syndrome Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established neurology and psychiatric therapeutic franchises. Hospital formulary access depends on integrated pharmacovigilance service offerings rather than standalone product efficacy. Three archetypes dominate: global diversified majors with dedicated safety infrastructure, mid-cap specialists in CNS therapeutics, and contract research organizations capturing outsourced compliance demand. Competitive moves concentrate on pharmacovigilance capability acquisitions and clinical decision support partnerships with health systems.
Within the diversified-major tier, Pfizer Inc. and Eli Lilly and Company exemplify scale-driven positioning through specialized R&D intensity in psychiatric pharmacology and multi-continent manufacturing networks. AstraZeneca occupies a position differentiated via controlled distribution networks for high-risk therapeutic categories. These three anchors represent distinct strategic postures: one emphasizing manufacturing scale, one prioritizing therapeutic-area depth, and one focusing on distribution control for safety-critical portfolios.
| Leading Market Players |
|---|
| Johnson & Johnson |
| AstraZeneca |
| Eli Lilly and Company |
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Bristol-Myers Squibb |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Hospital formulary committees in the United States are elevating adverse-event monitoring capability above unit cost in procurement evaluations, forcing manufacturers to bundle pharmacovigilance services with core drug supply and compressing margins on standalone product sales.
Pricing Analysis
Bundled pharmacovigilance service contracts now dominate hospital procurement, with unbundled product-only pricing relegated to retail and mail-order channels. Pricing stratifies across premium, standard, and economy tiers based on FDA adverse event reporting infrastructure and clinical decision support integration. Cost compression in the economy tier is intensifying because smaller hospital systems lack capital for specialized diagnostic equipment. Federally qualified health centers serving high-polypharmacy Medicaid populations exhibit the highest price sensitivity, while level I trauma centers in Texas and California demonstrate lowest sensitivity due to dedicated toxicology budgets.
Supply Chain Analysis
FDA and EMA certification requirements gate supplier access, with only manufacturers maintaining dedicated pharmacovigilance infrastructure qualifying for tier-one hospital contracts. Active pharmaceutical ingredient supply concentrates in India, China, and the United States, with formulation and packaging anchored in Germany and Japan. Cyproheptadine reversal agent stock and neuromuscular monitoring equipment draw from specialized medical device suppliers in Massachusetts and Bavaria. Single-source vulnerability in clinical pharmacology talent pools threatens supply chain resilience. Distribution runs through controlled distribution networks for high-risk serotonergic categories, with direct-to-hospital contracting displacing wholesale intermediaries in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA Periodic Safety Update Report standardization creates compliance cost differentials favoring European contract research organization clusters over fragmented US consulting markets.
For Market Incumbents: Acquire specialized clinical pharmacology staffing assets to defend formulary positioning against mid-cap CNS specialists. Backward integration into adverse-event monitoring software development counters third-party clinical decision support displacement. Capacity addition in Baden-Württemberg captures EMA harmonization service demand from multinational manufacturers lacking dedicated infrastructure. For New Entrants and Emerging Players: Federally qualified health centers represent an underserved buyer archetype requiring telemedicine-integrated triage tools at price points below academic medical center configurations. Ambulatory surgical centers in pain management corridors offer the most penetrable segment due to anesthesia handoff information discontinuity. A go-to-market angle anchored on algorithmic drug-drug interaction screening for polypharmacy patients bypasses entrenched EHR-native alert competition. For Investors and Strategic Acquirers: Asymmetric upside sits with contract research organizations possessing EMA-compliant signal detection methodologies and FDA submission track records. Long-term viability over the next decade rests on pharmacovigilance capability scarcity as serotonergic portfolios expand. Acquisition targets should demonstrate embedded hospital system relationships and clinical decision support partnerships. The signal to watch is FDA pharmacovigilance mandate expansion beyond current serotonergic classes.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacovigilance Capability Acquisition | EMA Periodic Safety Update Report mandates in Germany force compliance service consolidation. |
| Clinical Decision Support Partnership | FDA-mandated adverse event infrastructure in US health systems displaces native EHR alerts. |
| Telemedicine Triage Integration | Remote monitoring platforms in United Kingdom NHS systems embed algorithmic syndrome detection. |
| Point-of-Care Testing Development | Rapid diagnostic assays for hyperthermia assessment open pre-hospital market entry in Japan. |
| Specialized Clinical Pharmacy Staffing | Board-certified toxicologist scarcity in Texas and California trauma centers limits program expansion. |
Research Methodology
Multiple input streams — regulatory filing analysis, hospital procurement database review, and pharmacovigilance service contract documentation — were reconciled through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA pharmacovigilance filings, EMA Periodic Safety Update Report submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement data. Bottom-up prescription volume modeling and top-down therapeutic category expenditure analysis were triangulated against manufacturer revenue disclosures.
Historical growth patterns were cross-referenced against panel input from clinical pharmacology specialists and health system pharmacy directors across the analysis window. Segmentation dimensions modeled include product type, therapy area, delivery mode, and end-user care setting, with regional regulatory cluster effects incorporated. CAGRs were derived from prescription volume trajectories, adverse event reporting infrastructure investment flows, and formulary access conditions. Forecast inputs incorporated FDA mandate expansion scenarios and EMA harmonization timelines.
Underlying measurement precision varies by segment; hospital end-user and intravenous delivery mode carry tighter precision than home care and transdermal categories due to procurement data availability. Forecasts reflect assumptions regarding pharmacovigilance staffing expansion rates and serotonergic drug portfolio growth. Deviation in FDA adverse event reporting mandate scope or EMA Periodic Safety Update Report interval adjustments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Endometriosis Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Global Chronic Lower Back Pain (CLBP) Market
Specialty Medicine
Peptide Receptor Radionuclide Therapy (PRRT) Market
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Neurometabolic Disorder Market