
 Osteomyelitis Market | 2026-2036
Osteomyelitis Market Size, Share, and Industry Trends Forecast 2026-2036
Osteomyelitis Market Intelligence
A shift from multi-source procurement of antibiotics to single-source contracts for advanced local delivery systems is hardening supply chain relationships. Stryker Corporation specializes in surgical implants and related orthopedic solutions. Johnson & Johnson Services, Inc. leverages its broad pharmaceutical and device portfolio across multiple therapy areas. Medtronic competes with its integrated pain management devices and surgical technologies.
Osteomyelitis is an infection of the bone, most commonly caused by Staphylococcus aureus bacteria. Treatment aims to eradicate the pathogen, often requiring long-term antibiotic administration or surgical debridement to prevent bone necrosis. Within therapy areas, chronic infection cases represent a high-margin segment due to complex management needs. Antibiotics, delivered intravenously or orally, continue to constitute the largest product category by volume, while surgical implants are critical for post-traumatic cases.
Regulatory oversight from the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) governs the approval of new antibiotic therapies. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) sets stringent standards for surgical implants used in bone reconstruction. These agencies' guidelines on clinical trial design and manufacturing quality directly influence market access. Stakeholders must now prioritize developing novel non-antibiotic treatments to address the growing challenge of multidrug-resistant pathogens.
Market Dynamics
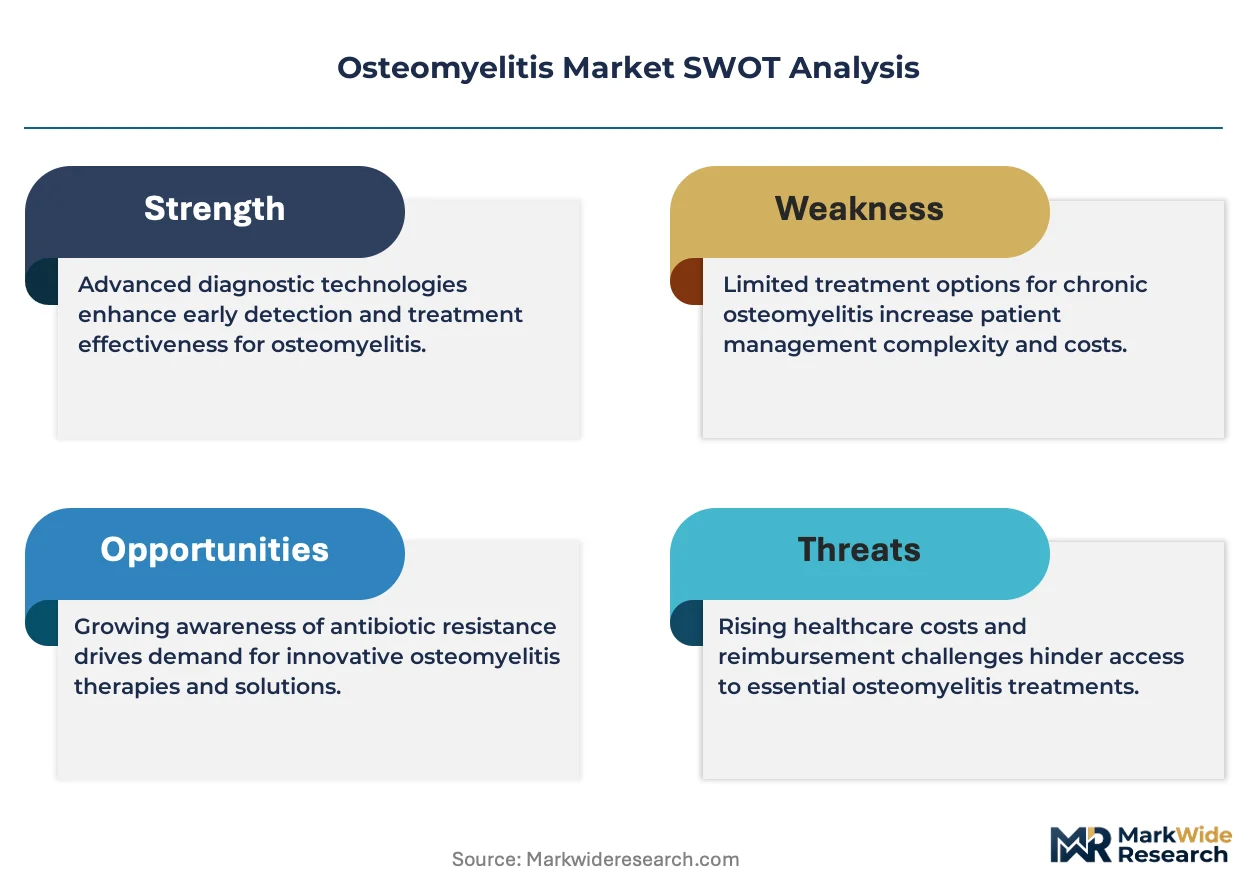
The increasing prevalence of multidrug-resistant pathogens is the central force shaping the osteomyelitis market. This biological reality compels a shift from systemic antibiotics toward targeted, localized delivery systems and novel non-antibiotic therapies to improve patient outcomes and address treatment failures.
Growth Catalysts
- Regulatory Incentives:The FDA's Fast Track designation accelerates review for novel anti-infectives, spurring investment in therapies targeting multidrug-resistant osteomyelitis.
- Advanced Local Delivery Systems:Biodegradable, antibiotic-eluting implants provide sustained drug release, reducing systemic toxicity and eliminating the need for implant removal surgeries.
- Surgical Procedure Volume:High rates of orthopedic surgeries in the United States and Germany increase the incidence of post-surgical bone infections, driving treatment demand.
Market Restraints
- High Treatment Costs:The expense of long-term IV antibiotic therapy and surgical debridement limits patient access in healthcare systems with limited reimbursement.
- Diagnostic Delays:Difficulty in obtaining definitive microbiological diagnoses from bone biopsies delays targeted therapy, risking progression to chronic, difficult-to-treat infections.
- Stringent Device Approval:The EU's MDR and Japan's PMDA impose rigorous data requirements for surgical implants, creating high entry barriers for manufacturers.
Strategic Opportunities
- Bacteriophage Therapy:Phage-based treatments offer a non-antibiotic alternative for multidrug-resistant infections, addressing a critical gap in chronic osteomyelitis management.
- Diabetic Foot Care Expansion:Specialized wound care services in Brazil and India can prevent progression to osteomyelitis, creating a new preventative care market.
- Stewardship-Enabling Products:Rapid diagnostics and narrow-spectrum agents align with hospital antibiotic stewardship programs promoted by the WHO, creating clear market demand.
Industry Challenges
- Clinical Trial Complexity:Designing and executing clinical trials for chronic osteomyelitis is difficult due to long follow-up periods and heterogeneous patient populations, delaying new therapy approvals.
- Supply Chain Hardening:The shift from multi-source antibiotics to single-source contracts for proprietary local delivery systems increases supply chain fragility and vendor lock-in risk for providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteomyelitis Market |
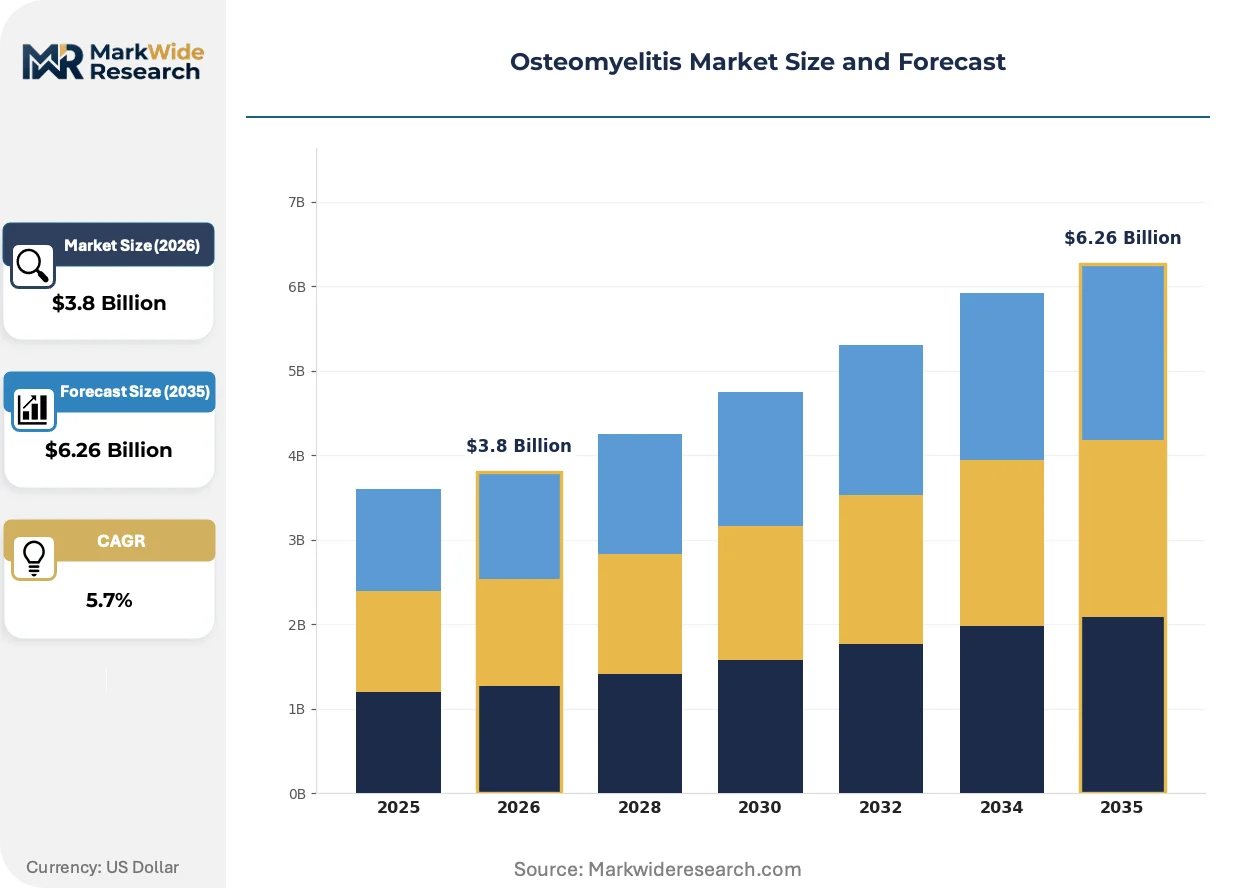
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Surgical Implants, Diagnostic Kits, Wound Dressings, Pain Management Devices Therapy Area: Chronic Infection, Acute Infection, Post-Traumatic, Post-Surgical, Hematogenous End User: Orthopedic Clinics, Diagnostic Laboratories, Specialized Care Centers, Research Institutes Delivery Method: Oral, Intravenous, Local Delivery Systems, Injectable, Topical Application |
| Companies Covered | Johnson & Johnson Services, Inc., Teva Pharmaceutical Industries Ltd., Pfizer Inc., Medtronic, Stryker Corporation, Merck & Co., Inc., AstraZeneca PLC, Smith & Nephew plc, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteomyelitis Market Strategic Shifts & Innovations
Innovation in the osteomyelitis market is defined by the race to outpace antimicrobial resistance. This drives development toward precision medicine, where treatment is tailored to specific pathogens and delivered directly to the site of infection.
Smart implants embedded with sensors represent a key technological evolution, designed to monitor infection status in real-time. Orthopedic centers in the United States and Germany are early adopters in clinical trials, seeking to improve post-operative surveillance. This technology is decentralizing patient monitoring from hospital-based imaging to continuous, remote data streams, enabling earlier intervention.
The European Union's Medical Device Regulation (MDR) now classifies many drug-device combination products, like antibiotic-coated implants, under more stringent rules. This policy harmonizes oversight but also increases the burden of clinical evidence required for market approval across member states. Manufacturers are now investing more heavily in post-market clinical follow-up studies to maintain CE marking for their osteomyelitis treatment devices.
A shift toward value-based healthcare models is changing how hospitals procure osteomyelitis treatments. Providers are moving away from purchasing individual components like antibiotics and implants separately, favoring bundled solutions from a single supplier that guarantee clinical outcomes. This trend is most pronounced in integrated delivery networks within the United States, which leverage their scale to negotiate such contracts.
Osteomyelitis Market Segmentation
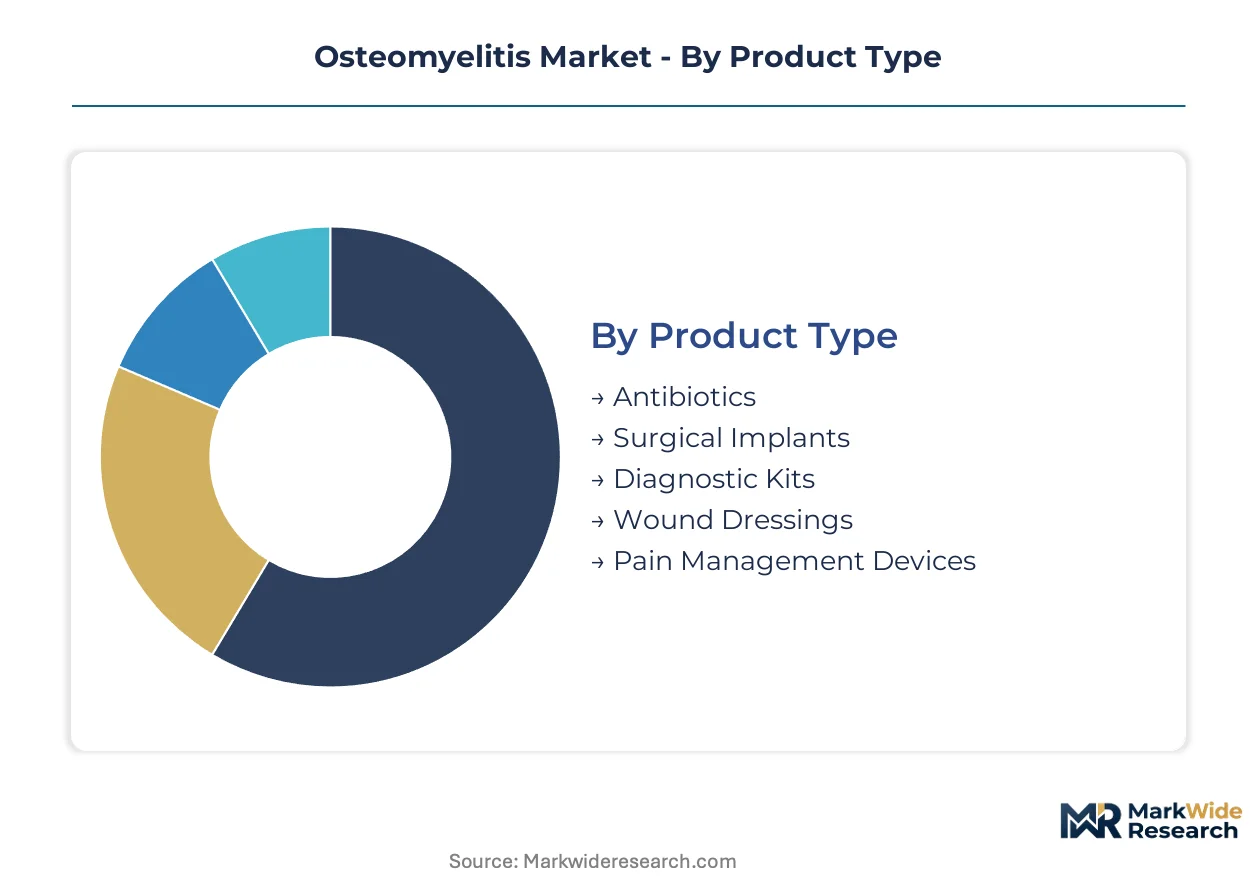
The osteomyelitis market is structured by diverse product offerings and treatment approaches. Understanding these distinct segments provides clarity on demand patterns and technological advancements. This detailed segmentation highlights areas of current investment and future growth trajectories within bone infection management.
Product Type:
The osteomyelitis treatment landscape is defined by the specific technologies and materials utilized in patient care.
- Antibiotics:These pharmaceutical agents target bacterial pathogens, delivered systemically or locally to eradicate bone infections. Demand concentrates in all healthcare settings, driven by the persistent need to combat Staphylococcus aureus and other causative bacteria.
- Surgical Implants:These devices, ranging from internal fixation hardware to antibiotic-eluting beads, support bone stability and deliver localized therapy. Demand is strong in the United States, propelled by high orthopedic surgery volumes and post-traumatic cases.
- Diagnostic Kits:These kits facilitate identification of pathogens and infection markers, enabling targeted therapy decisions.
- Wound Dressings:Specialized dressings manage open wounds associated with osteomyelitis, promoting healing and preventing secondary infections.
- Pain Management Devices:These devices, including neurostimulators, alleviate chronic pain often accompanying long-term bone infections.
Mature deployment sits with Antibiotics. Newer deployment is concentrated in Surgical Implants.
Therapy Area:
Osteomyelitis is categorized by the clinical presentation and duration of the bone infection.
- Chronic Infection:This segment encompasses long-standing bone infections, often requiring complex, multidisciplinary management due to bone necrosis and biofilm formation. Demand is high for advanced treatment modalities, particularly non-antibiotic options addressing multidrug-resistant pathogens.
- Post-Surgical:Infections occurring after orthopedic procedures fall into this category, representing a significant challenge for healthcare systems. High rates of orthopedic surgeries in the United States and Germany directly increase the incidence and demand for treatment in this area.
- Acute Infection:Characterized by rapid onset, these infections require prompt diagnosis and aggressive antibiotic treatment to prevent chronicity.
- Post-Traumatic:Infections developing after bone trauma or open fractures necessitate integrated surgical and antimicrobial approaches.
- Hematogenous:This refers to bone infections spread via the bloodstream from a distant primary infection site.
The Chronic Infection segment is expanding most quickly due to complex management needs.
End User:
The delivery of osteomyelitis care spans various specialized healthcare providers and research entities.
- Orthopedic Clinics:Serving as primary points of contact for bone-related issues, these clinics manage initial diagnoses and follow-up care for osteomyelitis patients. High volumes of orthopedic procedures create a consistent demand channel for related treatment and diagnostic products.
- Diagnostic Laboratories:These laboratories perform microbiological analysis of bone biopsies, crucial for identifying specific pathogens and guiding treatment selection.
- Specialized Care Centers:These facilities offer comprehensive, multidisciplinary treatment for complex bone infections, including surgical debridement and long-term antibiotic administration. Rising treatment rates in these centers contribute significantly to market growth for advanced therapies.
- Research Institutes:Focused on developing novel therapies and understanding disease mechanisms, these institutes drive innovation in osteomyelitis treatment.
Specialized Care Centers exhibit the steepest expansion trajectory in patient volume.
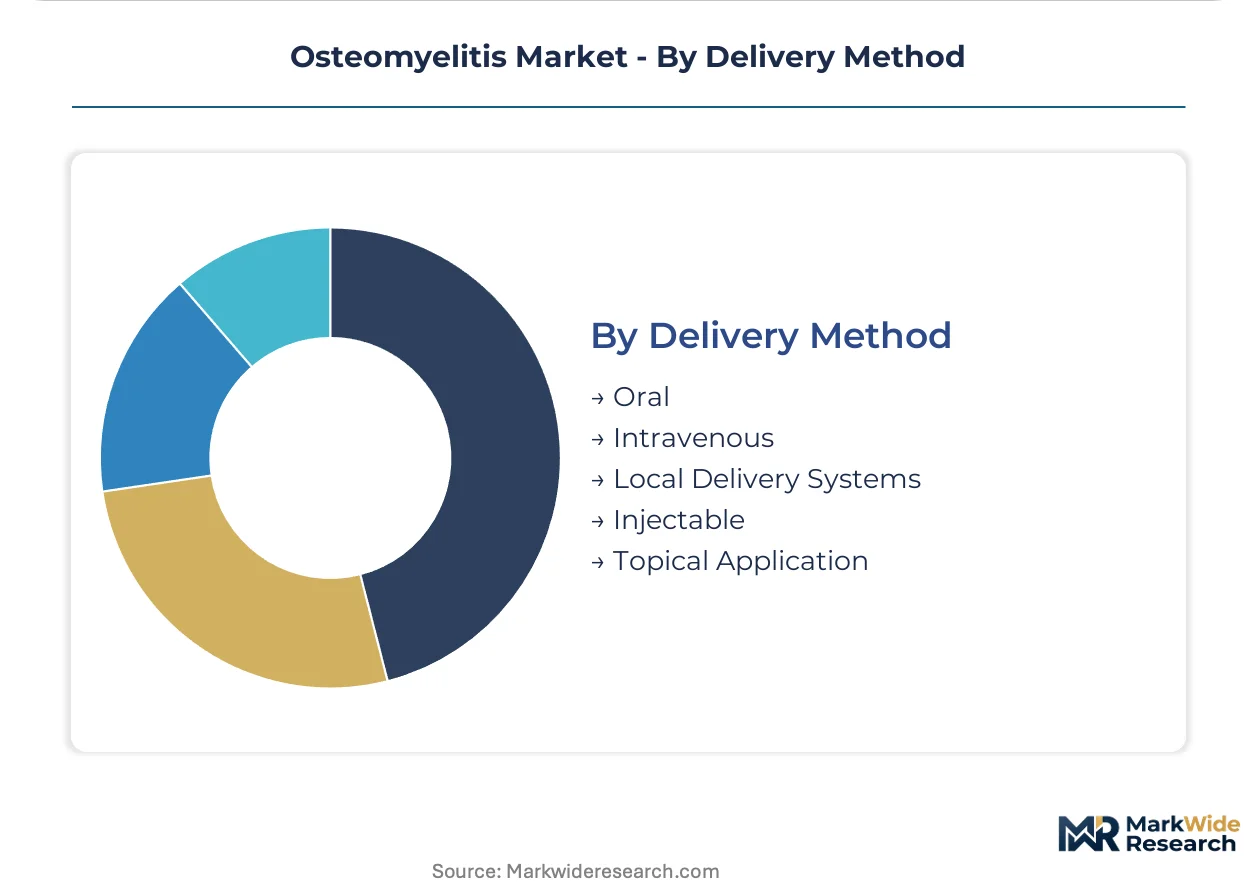
Delivery Method:
Treatment efficacy is significantly influenced by the route and mechanism through which therapeutic agents reach the infection site.
- Oral:Oral antibiotics are often used for less severe cases or as step-down therapy after initial intravenous treatment.
- Intravenous:Systemic administration of antibiotics via IV is a common approach for severe osteomyelitis, often requiring long-term hospital or home-based care. The high cost of long-term IV antibiotic therapy remains a significant market restraint.
- Local Delivery Systems:These advanced methods, including antibiotic-eluting implants, provide sustained drug release directly at the infection site, minimizing systemic toxicity. A shift from multi-source procurement to single-source contracts for these systems is hardening supply chain relationships.
- Injectable:This method includes direct injection of antibiotics or other agents into the infected bone or surrounding tissues.
- Topical Application:Topical treatments, such as antibiotic-containing creams or gels, are applied externally to superficial bone infections or wounds.
Local Delivery Systems are gaining share fastest as targeted non-systemic approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for osteomyelitis treatments concentrates in regions with advanced healthcare infrastructure and high orthopedic procedure volumes. These areas require sophisticated solutions for bone infections, particularly chronic and post-surgical cases. Regulatory frameworks also influence market access.
United States
The United States drives significant demand due to high orthopedic procedure volumes and prevalence of post-surgical infections. The FDA's Fast Track designation accelerates review for novel anti-infectives, spurring investment. Boston's biotech hub concentrates research and development for advanced localized delivery systems.
Germany
Germany represents a key European market, driven by substantial orthopedic surgery volumes and early adoption of smart implants for monitoring. The European Medicines Agency (EMA) provides regulatory oversight for new antibiotic therapies. Bavaria's strong medical technology sector actively develops and tests advanced surgical implants.
Japan
Japan exhibits demand for high-quality surgical implants used in bone reconstruction, especially for post-traumatic cases. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) sets stringent standards for device approval and market access. The Kansai region's medical device cluster develops and manufactures precision surgical instruments.
India
India presents a growing market for preventative care through the expansion of specialized diabetic foot care services. The Central Drugs Standard Control Organization (CDSCO) oversees approval of new antibiotic therapies and medical devices. Hyderabad's burgeoning pharmaceutical industry explores new avenues for anti-infective research.
Brazil
Brazil's demand is influenced by specialized wound care services and an increasing volume of orthopedic procedures. ANVISA, the national health surveillance agency, regulates medical products. São Paulo's extensive healthcare infrastructure supports the expansion of specialized care centers for osteomyelitis management.
Osteomyelitis Market Key Industry Players
Portfolio diversification dominates the current landscape, as companies seek to offer comprehensive solutions for complex bone infections. The market features a tiered structure, with large pharmaceutical companies and diversified medical technology firms alongside specialized device manufacturers. Strategic partnerships are crucial for integrating advanced local delivery systems with novel non-antibiotic treatments. Technology licensing also plays a role in addressing multidrug-resistant pathogens, particularly for chronic cases. This competitive dynamic is reshaping procurement patterns.
Among large diversified medical technology firms, Johnson & Johnson Services, Inc. exemplifies a broad pharmaceutical and device portfolio across multiple therapy areas, leveraging its extensive reach. Stryker Corporation represents a specialist in surgical implants and related orthopedic solutions, anchoring the device segment with its focus on post-traumatic cases. Medtronic, Inc. occupies a position with its integrated pain management devices and surgical technologies, addressing complex patient needs arising from chronic bone infections. These companies demonstrate diverse approaches to osteomyelitis treatment, from systemic solutions to localized interventions.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Medtronic |
| Stryker Corporation |
| Merck & Co., Inc. |
| AstraZeneca PLC |
| Smith & Nephew plc |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
The bifurcation between commodity antibiotics and specialized local delivery systems drives distinct pricing and supply chain configurations. Systemic antibiotics face volume-driven pricing, while advanced implants command higher margins due to regulatory hurdles and specialized manufacturing.
Pricing Analysis
Volume-driven pricing dominates the antibiotic segment, contrasting with value-based pricing for advanced surgical implants. Price differentiation stems from FDA and EMA certifications for novel therapies and the level of after-sales support for complex devices. Pricing softness affects generic antibiotics due to multi-source procurement and intense competition. Chronic infection cases, requiring complex management, are least price-sensitive, while acute infection treatments are more sensitive to cost.
Supply Chain Analysis
Workforce availability in specialized manufacturing geographies like the United States and Germany impacts local delivery system production. The supply chain sources critical inputs such as specialized polymers for implants and active pharmaceutical ingredients from India and China. Single-source vulnerability for proprietary local delivery systems presents a key structural risk. Distribution runs through specialized care centers and integrated delivery networks for bundled solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained narrative, with specialized manufacturing capacity for advanced local delivery systems serving as a critical bottleneck propping pricing.
For Market Incumbents:Extend existing product portfolios to include novel non-antibiotic treatments for multidrug-resistant pathogens. This defends against emerging biotech firms offering bacteriophage therapy, a significant threat. Reinforce market position through strategic investments in CE marking for drug-device combinations, ensuring broader European market access. Control over specialized manufacturing capabilities for advanced implants is a crucial lever.
For New Entrants and Emerging Players:A price-point gap exists between premium advanced implants and more accessible, rapidly deployable diagnostic kits. Target the post-surgical infection segment in regions with high orthopedic surgery volumes, like Germany, with rapid diagnostics. Offer a value proposition based on quicker diagnosis and targeted therapy. Leverage partnerships with orthopedic clinics to gain initial market penetration.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized medical device firms given the accelerating demand for localized delivery systems. Long-term viability favors companies developing non-antibiotic solutions addressing antimicrobial resistance over the projection horizon. Seek acquisition targets with strong intellectual property in bacteriophage therapy or smart implant technology. Watch for early clinical trial successes in novel non-antibiotic treatments as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates approval for novel anti-infectives targeting multidrug-resistant pathogens. |
| Product Development | Develops next-generation smart implants with real-time infection monitoring capabilities. |
| Manufacturing Scale-Up | Ensures consistent supply of specialized antibiotic-eluting beads for hospitals. |
| Strategic Partnership | Integrates advanced local delivery systems with complementary diagnostic platforms. |
| Regulatory Approval Pathway | Navigates stringent FDA and EMA requirements for drug-device combination products. |
Research Approach
Multi-period observation of treatment adoption rates and regulatory approval trends anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with orthopedic surgeons, hospital procurement managers, regulatory affairs specialists, and R&D directors. Secondary validation incorporated data from FDA filings, EMA submissions, and medical device registries. Bottom-up market sizing was triangulated with top-down validation of overall market revenues.
Segment-weighting approaches refined the market forecast, considering product type, therapy area, end-user, and delivery method dimensions. The analytical framework projected market growth across the analysis window, with compound annual growth rates derived from historical performance and anticipated regulatory shifts. Forecast inputs included orthopedic procedure volumes in the United States and Germany, and the prevalence of multidrug-resistant infections.
Underlying measurement precision varies by segment; surgical implants and local delivery systems carry tighter precision than others due to clear regulatory pathways. Forecasts reflect assumptions regarding antibiotic resistance evolution and healthcare policy changes. Material deviation in novel non-antibiotic therapy approvals warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Quadriplegia Treatment Market
Specialty Medicine
Community Acquired Bacterial Pneumonia (CABP) Treatment Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Pleurodynia Treatment Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
Hemochromatosis Treatment Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Rumination Syndrome Market