
 Acute Lymphoblastic Leukemia Therapeutics Market | 2026-2036
Acute Lymphoblastic Leukemia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Lymphoblastic Leukemia Therapeutics Market Outlook
CAR-T cell engineering is reshaping therapeutic development across the acute lymphoblastic leukemia landscape. Novartis AG leverages its Kymriah manufacturing infrastructure to sustain leadership in autologous cell therapy production. Bristol-Myers Squibb Company anchors its position through deep R&D investment in bispecific T-cell engagers. Pfizer Inc. competes via broad clinical trial networks spanning pediatric and adult oncology centers.
Acute lymphoblastic leukemia therapeutics encompass pharmaceutical and biologic interventions designed to eliminate malignant lymphoid progenitor cells, with treatment protocols typically combining induction chemotherapy at 40-50 mg/m² daunorubicin equivalent doses with consolidation phases incorporating asparaginase derivatives or monoclonal antibodies. The primary purpose is achieving minimal residual disease negativity to prevent relapse and enable long-term remission in both pediatric and adult patient populations. Immunotherapy, particularly CAR-T cell products, commands the fastest expansion as manufacturing scale improves and reimbursement frameworks mature, while chemotherapy retains volume leadership due to established protocols in first-line settings. Targeted therapy occupies concentrated margin pools through kinase inhibitors and antibody-drug conjugates serving relapsed populations with unmet need.
FDA breakthrough therapy designation and EMA PRIME eligibility criteria are compressing development timelines for novel biologics while raising evidence standards for confirmatory trials. The EU AI Act and GDPR frameworks are beginning to influence real-world evidence collection and algorithm-driven patient stratification tools used in treatment selection. Stakeholders must monitor how evolving pharmacovigilance requirements for gene-modified cell therapies will reshape post-market commitment burdens and manufacturing inspection frequencies across multiple jurisdictions.
Market Dynamics
CAR-T manufacturing scale-up is compressing production timelines from 21 days toward 10-14 days, forcing chemotherapy incumbents to defend first-line positioning through combination protocols with monoclonal antibodies.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses Phase 2-to-launch timelines for novel biologics, enabling earlier patient access to cell therapies in relapsed pediatric populations.
- Autologous cell therapy infrastructure:Dedicated manufacturing facilities in the United States, Germany, and Japan are expanding vein-to-vein capacity, reducing logistical barriers to treatment delivery.
- Minimal residual disease testing:Next-generation sequencing platforms are refining patient stratification, directing high-risk candidates toward intensive immunotherapy earlier in treatment sequences.
Market Restraints
- Vein-to-vein logistics complexity:Cryogenic cold chain requirements for autologous cell products limit treatment access to specialized academic medical centers with apheresis and infusion capabilities.
- Reimbursement fragmentation:Hospital outpatient prospective payment systems in the United States create misalignment between CAR-T acquisition costs and reimbursement rates, constraining site-of-care expansion.
- Asparaginase supply concentration:Production of E. coli-derived enzyme concentrates among three global suppliers exposes protocols to batch contamination risks and geographic supply interruptions.
Strategic Opportunities
- Allogeneic CAR-T platforms:Off-the-shelf cell products eliminate apheresis-dependent manufacturing delays, opening treatment access to community oncology settings without specialized infrastructure.
- EMA PRIME eligibility:Priority medicines status offers enhanced regulatory support for pediatric oncology developers, accelerating access to the European market for novel mechanisms.
- Real-world evidence networks:Post-market registries mandated by FDA for gene-modified therapies are generating long-term safety datasets that support label expansion into earlier treatment lines.
Industry Challenges
- Vector manufacturing capacity:Lentiviral and retroviral vector production bottlenecks constrain CAR-T output expansion, with viral GMP suites requiring 18-24 month construction timelines.
- Pharmacovigilance workforce scarcity:Gene therapy-specific safety monitoring demands expertise in cytokine release syndrome grading and neurotoxicity management that outpaces clinical training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Lymphoblastic Leukemia Therapeutics Market |
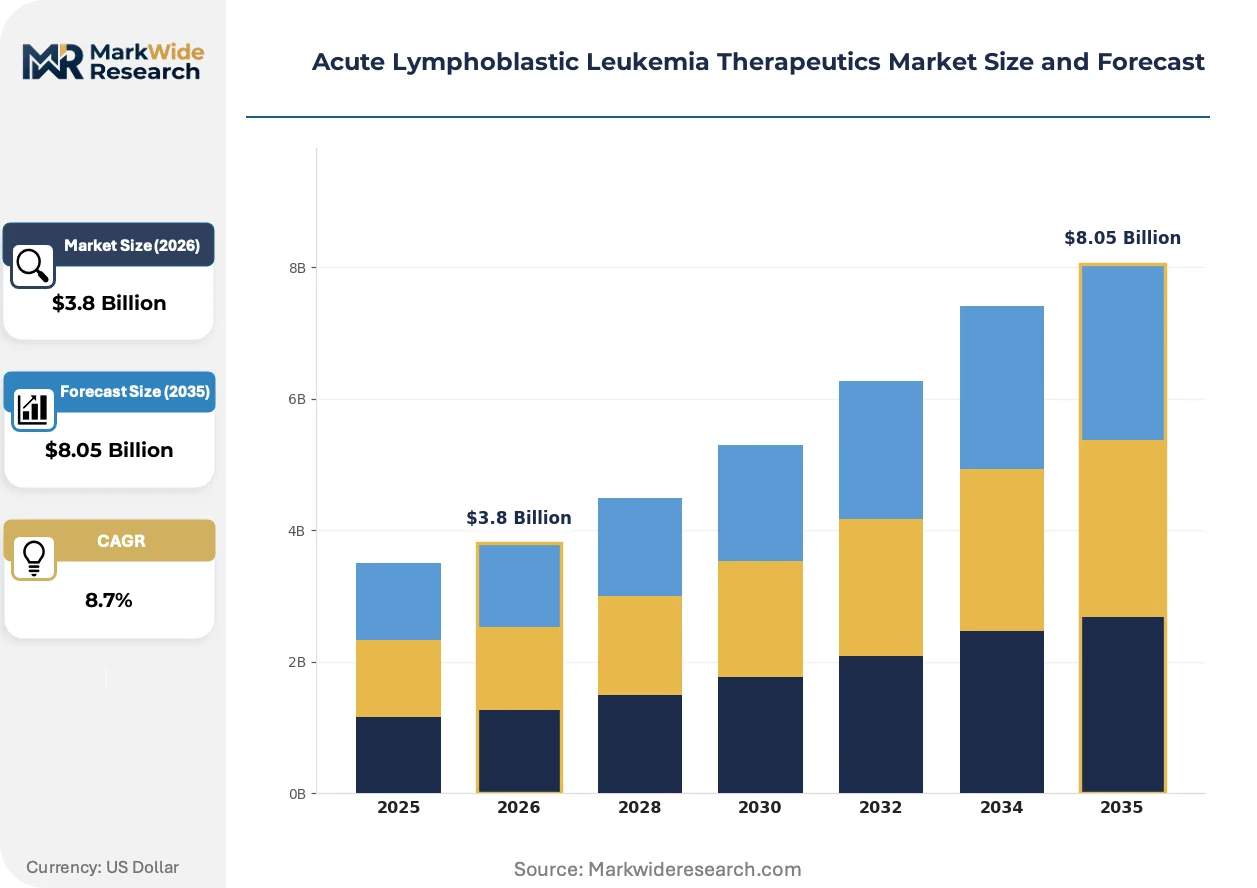
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Stem Cell Transplant Therapy Area: Pediatric, Adult, Relapsed, First-Line Administration Route: Oral, Intravenous, Subcutaneous, Intrathecal End User: Hospitals, Specialty Clinics, Outpatient Facilities, Research Labs |
| Companies Covered | Novartis AG, Pfizer Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Amgen Inc., Gilead Sciences, Jazz Pharmaceuticals, Takeda Pharmaceutical Co., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Lymphoblastic Leukemia Therapeutics Market Strategic Shifts
Digital infrastructure is penetrating clinical trial operations and manufacturing quality systems, compressing documentation cycles and enabling predictive batch release. Three developments are restructuring competitive positioning.
Artificial intelligence platforms are digitizing patient eligibility screening and manufacturing lot release decisions. Novartis AG and Bristol-Myers Squibb Company deploy machine learning algorithms to predict T-cell expansion rates from donor apheresis samples, reducing culture failure rates and compressing quality control timelines from days toward hours.
EMA's PRIME scheme and FDA's breakthrough therapy designation are converging on harmonized evidentiary standards for accelerated approval. Developers must now design single-arm trials with overall response rate endpoints that satisfy both agencies, raising protocol complexity but reducing duplicative clinical development costs for transatlantic submissions.
Academic medical centers are consolidating procurement authority for cell therapy services through centralized pharmacy and therapeutics committees. Sites in the United States now negotiate bundled pricing for CAR-T products with companion diagnostic testing and cytokine release syndrome management protocols, displacing product-centric purchasing patterns.
Acute Lymphoblastic Leukemia Therapeutics Market Segmentation
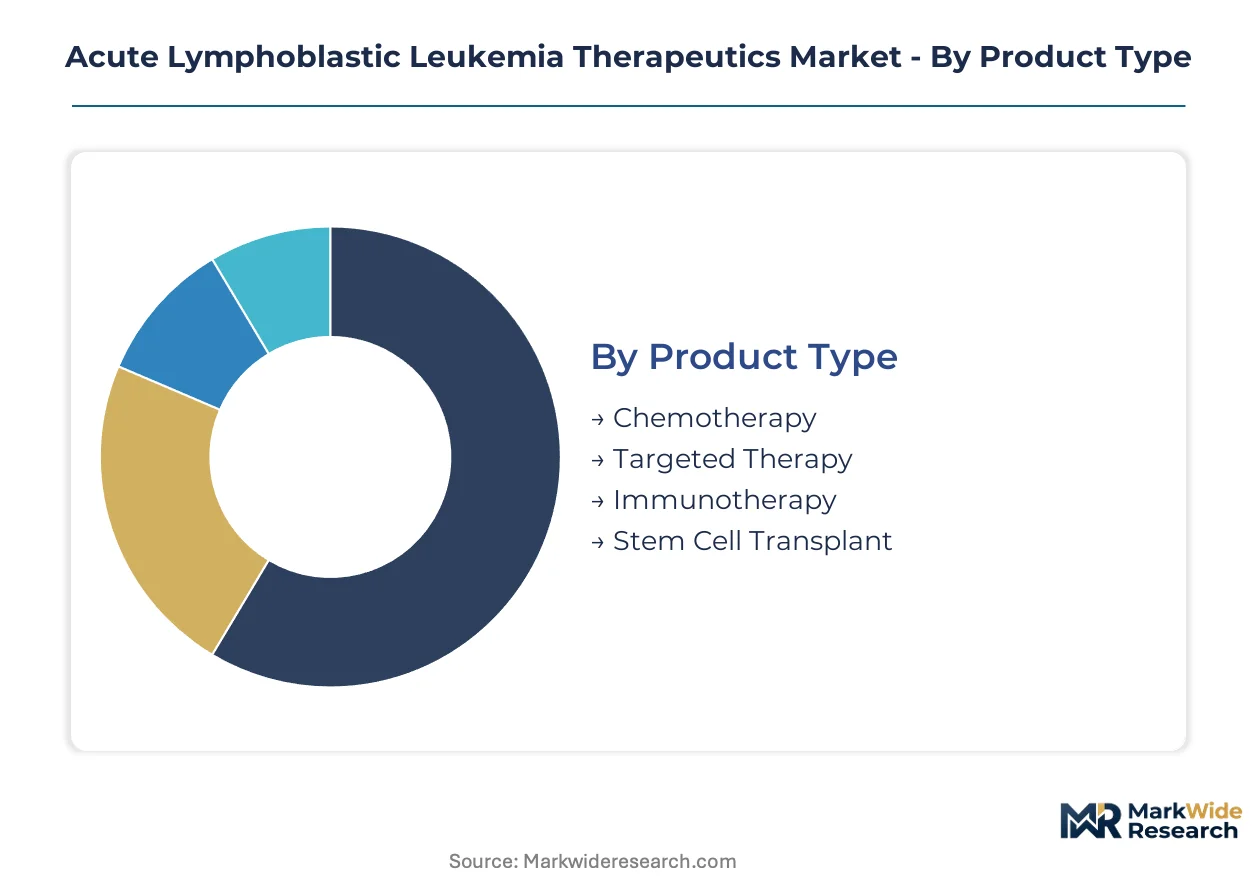
Treatment modality selection in acute lymphoblastic leukemia hinges on patient age, disease stage, and molecular risk stratification. Segmentation reveals how chemotherapy defends volume leadership while immunotherapy captures margin expansion through CAR-T and bispecific platforms.
Product Type:
Use-case spectrum spans curative-intent induction protocols through salvage therapy for multiply relapsed disease.
- Chemotherapy:Anthracycline-vincristine-asparaginase combinations remain the backbone of first-line pediatric and adult protocols, with daunorubicin-equivalent dosing at 40-50 mg/m². Demand concentrates in United States academic medical centers and German pediatric oncology networks where established infrastructure supports intensive inpatient administration.
- Immunotherapy:CD19-directed CAR-T cell products and bispecific T-cell engagers eliminate malignant progenitors through engineered immune recognition. Manufacturing scale improvements in Novartis AG's Kymriah network and Bristol-Myers Squibb Company's Breyanzi facilities are compressing vein-to-vein timelines toward 10-14 days.
- Targeted Therapy:Kinase inhibitors and antibody-drug conjugates address Philadelphia chromosome-positive and relapsed subpopulations with mechanism-specific toxicity profiles.
- Stem Cell Transplant:Allogeneic transplantation serves high-risk or second-remission patients with matched donor availability, requiring specialized graft-versus-host disease management capabilities.
The dominant share belongs to Chemotherapy, while Immunotherapy is closing the gap fastest.
Therapy Area:
Patient age and treatment history dictate regimen intensity and access to cellular interventions.
- Pediatric:Children aged 1-18 years receive risk-stratified multi-agent protocols with 90%+ event-free survival in standard-risk B-cell disease. Treatment concentrates in dedicated pediatric oncology centers across the United States, Germany, and Japan with established CAR-T apheresis partnerships.
- Adult:Patients over 18 years face inferior outcomes due to higher incidence of adverse genetics and reduced chemotherapy tolerance, driving faster adoption of immunotherapy salvage options.
- Relapsed:Second or greater recurrence mandates mechanism-of-action switches, with CD22-directed therapies and allogeneic CAR-T trials expanding options beyond CD19 exhaustion.
- First-Line:Initial diagnosis protocols combine chemotherapy with minimal residual disease monitoring to identify candidates for therapy intensification or de-escalation.
Pediatric protocols command the highest complete remission rates, though Adult represents the steepest expansion trajectory as CAR-T indications broaden beyond salvage settings.
Administration Route:
Delivery modality selection balances bioavailability requirements with central nervous system penetration and patient compliance.
- Intravenous:Anthracyclines, vincristine, and monoclonal antibodies require vascular access for systemic distribution, dominating inpatient infusion center capacity.
- Oral:Maintenance-phase 6-mercaptopurine and methotrexate enable outpatient therapy continuation, with adherence monitoring critical for relapse prevention.
- Intrathecal:Direct cerebrospinal fluid delivery of methotrexate, cytarabine, and hydrocortisone prevents central nervous system sanctuary relapse.
- Subcutaneous:Asparaginase derivatives and some supportive care agents allow reduced hospital dependency versus intravenous equivalents.
Intravenous delivery retains the dominant procedural volume, though Oral formulations are gaining share fastest through maintenance-phase optimization.
End User:
Site-of-care capabilities determine access to cellular therapies versus conventional chemotherapy.
- Hospitals:Academic medical centers with apheresis units, cryogenic storage, and neurotoxicity monitoring infrastructure control CAR-T patient access. United States centers in Boston, Houston, and Seattle anchor regional referral networks.
- Specialty Clinics:Pediatric oncology and adult leukemia-focused practices manage chemotherapy protocols and patient stratification, referring cellular therapy candidates to authorized treatment centers.
- Outpatient Facilities:Community infusion centers handle maintenance therapy and supportive care, though reimbursement fragmentation constrains CAR-T expansion to this setting.
- Research Labs:Translational facilities conduct minimal residual disease testing and correlative biomarker studies supporting trial enrollment.
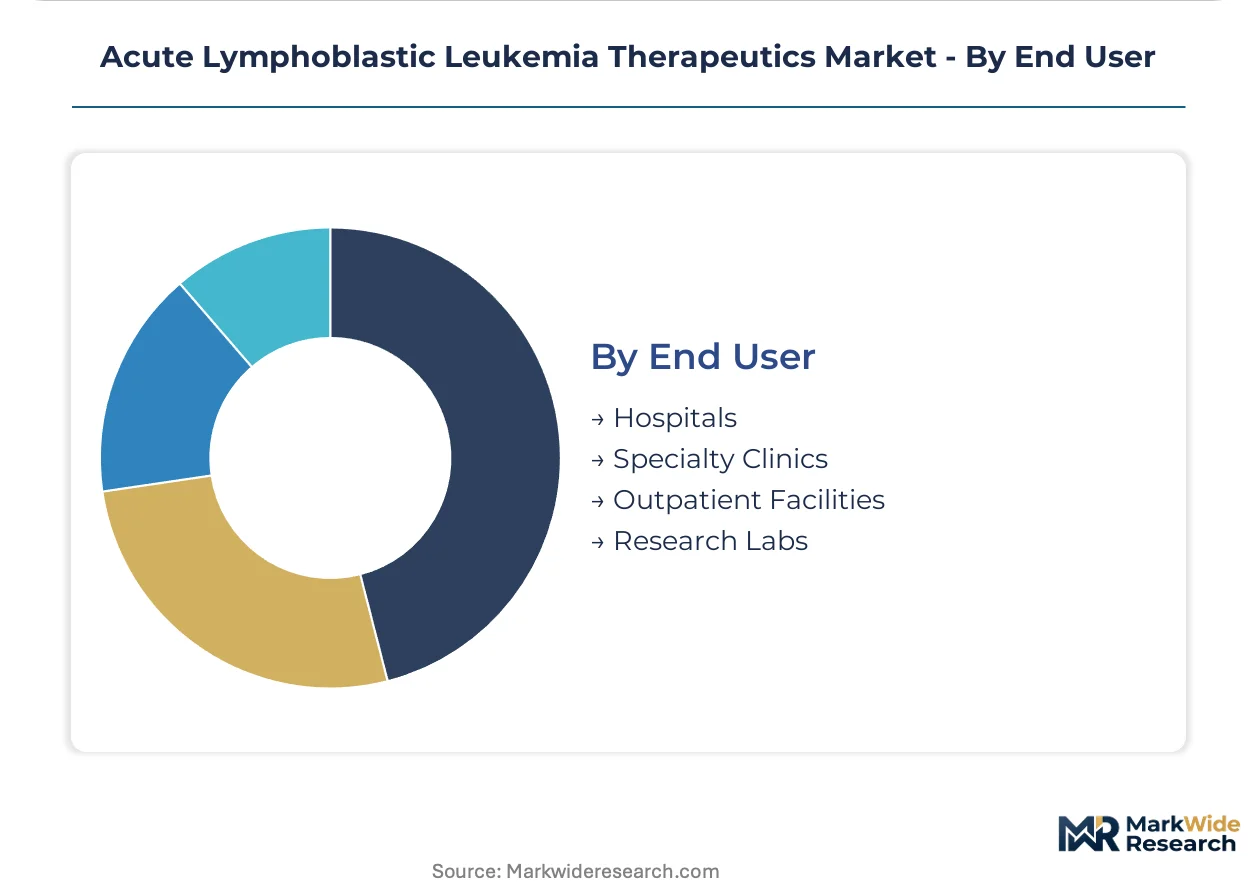
Hospitals capture the dominant share of immunotherapy value, while Specialty Clinics are expanding their role fastest through centralized referral partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biopharmaceutical exporters ship CAR-T cell products and kinase inhibitors to treatment centers in Germany and Japan, establishing a transatlantic corridor for advanced immunotherapy distribution. This trade flow concentrates value capture in specialized academic medical centers while manufacturing capacity clusters near apheresis collection networks.
United States
FDA breakthrough therapy designation accelerates pediatric oncology approvals, compressing development timelines for novel biologics. Hospital outpatient prospective payment systems create reimbursement friction for CAR-T acquisition costs. Boston, Houston, and Seattle anchor regional referral networks with dedicated apheresis and cryogenic storage infrastructure.
Germany
EMA PRIME eligibility offers enhanced regulatory support for priority medicines in pediatric oncology. The country's statutory health insurance funds negotiate outcome-based reimbursement for cell therapies. Heidelberg and Berlin concentrate CAR-T manufacturing partnerships between university hospitals and contract development organizations.
Japan
PMDA sakigake designation parallels FDA accelerated pathways for regenerative medicine products. METI funding supports domestic vector manufacturing capacity expansion. Tokyo and Osaka academic medical centers control national patient access through centralized pharmacy and therapeutics committees.
United Kingdom
NICE technology appraisals determine NHS funding for high-cost immunotherapies through incremental cost-effectiveness thresholds. The Cancer Drugs Fund provides managed access agreements for promising therapies pending confirmatory trial data. London and Manchester pediatric oncology networks refer cellular therapy candidates to authorized treatment centers.
Switzerland
Swissmedic maintains alignment with EMA centralized procedures while operating independent pricing negotiations. The country's health technology assessment body evaluates CAR-T cost-effectiveness against stem cell transplant benchmarks. Basel and Zurich pharmaceutical clusters host vector manufacturing and quality control operations serving European markets.
Acute Lymphoblastic Leukemia Therapeutics Market Competitive Environment
On the supply side, the industry is consolidating around integrated biopharmaceutical conglomerates with captive cell therapy manufacturing infrastructure. Large-cap developers dominate through vertical control over lentiviral vector production and apheresis network partnerships. Three strategic archetypes define positioning: autologous CAR-T specialists, bispecific antibody developers, and chemotherapy incumbents defending first-line protocols. Dominant competitive moves include manufacturing facility expansion and real-world evidence registry establishment to support label expansion.
Among Swiss-based pharmaceutical conglomerates, Novartis AG exemplifies the autologous cell therapy archetype through its Kymriah manufacturing network. Pfizer Inc. and Bristol-Myers Squibb Company occupy positions spanning bispecific platforms and broader oncology portfolios. These three entities represent the scale-driven tier where clinical trial density and site-of-care partnerships determine competitive differentiation.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Amgen Inc. |
| Gilead Sciences |
| Jazz Pharmaceuticals |
| Takeda Pharmaceutical Co. |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on E. coli-derived asparaginase production concentrates among three global suppliers determines both chemotherapy cost tier spreads and supply chain redundancy investments across acute lymphoblastic leukemia protocols.
Pricing Analysis
Next-generation CAR-T products command premium positioning against established chemotherapy backbones and emerging bispecific platforms. Three-tier pricing structure across premium cell therapies, standard monoclonal antibodies, and economy generic chemotherapy reflects manufacturing complexity and regulatory burden differentials. Cost compression in first-line chemotherapy intensifies because of asparaginase supply concentration and biosimilar entry. Pediatric oncology centers exhibit highest price sensitivity due to bundled reimbursement constraints, while adult salvage therapy settings show lowest sensitivity given limited alternatives.
Supply Chain Analysis
Export-control regimes limiting lentiviral vector technology flows constrain CAR-T manufacturing capacity expansion across jurisdictions. Supply concentrates in the United States, Germany, and Japan where apheresis networks and cryogenic infrastructure anchor production. Raw material dependencies span viral vectors, synthetic cytokines, and cryopreservation media. Single-source vulnerability in vector manufacturing suites creates bottlenecks requiring 18-24 month construction timelines. Distribution runs through authorized treatment centers with specialized neurotoxicity monitoring capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough therapy designation and EMA PRIME eligibility are compressing development timelines for novel biologics, creating a high-growth disruption window as cell therapies displace salvage chemotherapy protocols.
For Market Incumbents: Harden first-line positioning through combination protocols integrating monoclonal antibodies with chemotherapy backbones to delay CAR-T displacement. Secure backward integration into lentiviral vector production to reduce manufacturing bottlenecks threatening output expansion. Lock in apheresis network partnerships with academic medical centers to defend site-of-care control against allogeneic platform entrants.
For New Entrants and Emerging Players: Build out allogeneic CAR-T platforms targeting community oncology settings lacking autologous manufacturing infrastructure. Adult relapsed populations in European markets present the most penetrable segment given EMA PRIME regulatory support and outcome-based reimbursement frameworks. Pursue hospital system partnerships bundling companion diagnostics with therapy access.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors platforms with manufacturing scale and regulatory validation over early discovery assets. Five-to-ten year viability hinges on vein-to-vein timeline compression and real-world evidence generation supporting label expansion. Watch FDA confirmatory trial requirements for accelerated approvals as the critical inflection signal distinguishing sustainable revenue from regulatory reversal risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Compresses vein-to-vein timelines from 21 days toward 10-14 days for CAR-T products. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation accelerates pediatric oncology biologic launches. |
| Pipeline Diversification | CD22-directed therapies address CD19 exhaustion in multiply relapsed populations. |
| Licensing Agreement | EMA PRIME eligibility offers enhanced support for European market entry. |
| Reimbursement Strategy | Outcome-based contracts with German statutory health funds align pricing with clinical results. |
Study Parameters
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Primary insights from biopharmaceutical manufacturers and academic medical center procurement committees were cross-validated against secondary sources including CMS Medicare data and GPO contracts. Bottom-up patient-volume estimates and top-down revenue triangulation were reconciled across modeling approaches.
Assumptions held FDA and EMA regulatory pathways within current accelerated approval frameworks while varying pricing and reimbursement scenarios across jurisdictions. Segmentation dimensions modeled encompass treatment modality, patient age cohort, disease stage, administration route, and regional regulatory cluster. CAGRs were derived from patient population projections and therapy penetration curves. Forecast inputs incorporated manufacturing capacity expansion timelines and real-world evidence registry maturation.
The forecast holds incumbent behavior within observed patterns; aggressive manufacturing investments by allogeneic platform developers would shift competitive outcomes. Material shifts in FDA confirmatory trial requirements or EMA pharmacovigilance mandates for gene-modified therapies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pigmented Villonodular Synovitis Treatment Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Amino Acid Metabolism Disorders Treatment Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Global Allergy Vaccine Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Generalized Myasthenia Gravis (GMG) Management Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Vertigo Market