
 Heavy Alkyl Benzenes Market | 2026-2036
Heavy Alkyl Benzenes Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Alkyl Benzenes Market Foresight
Long-term supply agreements for sulfonation-ready feedstock is expanding how producers monetize heavy alkyl benzenes beyond spot chemical sales. Sasol leverages its Fischer-Tropsch integration to sustain cost-advantaged branched alkyl benzene output from South Africa. Chevron Phillips Chemical anchors North American supply through Gulf Coast paraffin-to-alkylate conversion. Fushun Petrochemical dominates captive demand in China's northeastern petrochemical belt.
Heavy alkyl benzenes comprise higher-molecular-weight alkylbenzene isomers, typically C13-C17 side chains, produced via alkylation of benzene with olefins or chloroparaffins; these materials function primarily as precursors to sulfonated surfactants and lubricant additive packages. Branched alkyl benzene retains cost leadership in industrial surfactant applications where biodegradability standards remain less stringent, while linear alkyl benzene faces substitution pressure from bio-based alternatives in European household detergents. Chemical intermediates for lubricant additive synthesis command margin premiums relative to commodity surfactant grades.
EPA fuel and lubricant additive regulations in the US, REACH chemical registration requirements in Europe, and China's MEE environmental compliance standards collectively elevate barium and sulfur content thresholds for lubricant-grade heavy alkyl benzenes. India's BIS detergent raw material specifications and the EU F-Gas Regulation's indirect pressure on fluorinated surfactant alternatives channel formulation demand toward sulfonated alkyl benzene chemistry. Stakeholders must monitor regulatory divergence between OECD jurisdictions and emerging economies to calibrate product slate and certification investments.
Market Dynamics
Long-term supply contracts for sulfonation-ready feedstock are replacing spot chemical sales as the dominant commercial arrangement, locking detergent and lubricant additive producers into multi-year offtake agreements with integrated petrochemical suppliers.
Growth Catalysts
- REACH purity mandates:European lubricant-grade specifications are tightening sulfur and barium thresholds, forcing reformulation toward higher-specification heavy alkyl benzene streams that command technical premiums.
- India's Gujarat chemical corridor:Integrated detergent plants are scaling captive sulfonation capacity, pulling additional heavy alkyl benzene volumes into western India's petrochemical belt.
- Chloroparaffin alkylation:This production route yields branched alkyl benzene isomers at lower cost than linear alternatives, sustaining cost leadership in industrial cleaning formulations where biodegradability standards remain permissive.
Market Restraints
- Feedstock concentration:Gulf Coast paraffin-to-alkylate conversion anchors North American supply, creating geographic vulnerability to hurricane disruption and refinery maintenance cycles.
- Linear alkyl benzene substitution:Bio-based surfactant alternatives are capturing share in European household detergents, compressing addressable volume for branched heavy alkyl benzene grades.
- EPA additive registration:Lubricant-grade material faces extended approval timelines for new fuel additive packages, delaying commercialization of reformulated streams.
Strategic Opportunities
- China's Shandong province:Provincial petrochemical clusters lack integrated sulfonation capacity, creating white space for toll-manufacturing partnerships with regional detergent producers.
- F-Gas Regulation displacement:EU restrictions on fluorinated surfactants are channeling formulation demand toward sulfonated alkyl benzene chemistry in industrial foam and emulsion applications.
- Digital procurement platforms:Specialty chemical distributors are launching online spot-market interfaces, reducing transaction friction for mid-volume detergent compounders.
Industry Challenges
- Sulfonation process engineering:Captive sulfonation requires specialized reactor design and emission control systems that extend project commissioning timelines beyond 18 months.
- REACH registration dossiers:The technical data requirements for higher-molecular-weight isomer mixtures are generating compliance costs that disproportionately burden smaller European traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Alkyl Benzenes Market |
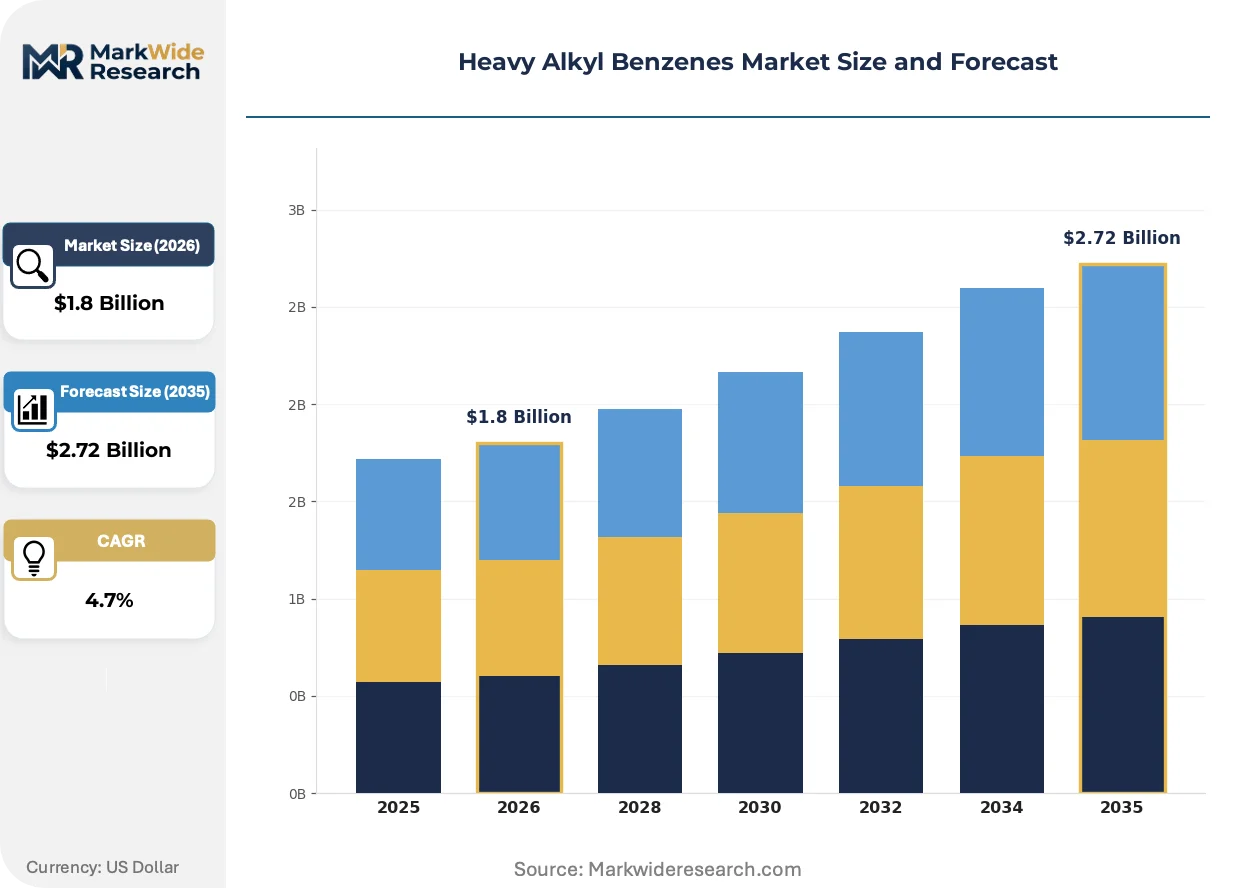
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Alkyl Benzene, Branched Alkyl Benzene, Heavy Alkyl Benzene, Light Alkyl Benzene Application: Surfactants, Detergents, Lubricants, Chemical Intermediates End User: Household, Industrial, Automotive, Agricultural Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | Huntsman Performance Products, ISU Chemical, Sasol, Chevron Phillips Chemical, ExxonMobil, CEPSA Quimica, Fushun Petrochemical, SEEF Limited, Reliance Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Alkyl Benzenes Market Shifts & Advancements
Process intensification and regulatory chemistry are converging to reshape how heavy alkyl benzenes are produced, certified, and commercialized across detergent and lubricant value chains.
Continuous sulfonation reactor technology is integrating real-time spectroscopic monitoring to optimize sulfur trioxide dosing and minimize byproduct formation. Detergent compounders in India's chemical corridor are adopting these systems to reduce acid sludge generation and improve linear alkyl benzene yield. The technology is integrating quality control directly into production flow, compressing the traditional batch-testing cycle and enabling just-in-time feedstock release.
REACH candidate list expansion is elevating trace impurity disclosure requirements for lubricant-grade heavy alkyl benzenes sold into European Union member states. ECHA's systematic review of C13-C17 alkylbenzene isomer toxicity is forcing producers to requalify existing registrations with enhanced analytical data packages. Lubricant additive houses are responding by dual-sourcing certified streams and investing in in-house chromatographic verification capacity.
Formulation houses are consolidating supplier relationships around integrated petrochemical producers capable of delivering sulfonation-ready material with bundled certification documentation. Long-term offtake agreements are displacing quarterly spot purchasing for surfactant manufacturers above 10,000-tonne annual consumption thresholds. This pattern is most visible in China's Shandong and Jiangsu provinces, where provincial environmental inspections have raised the compliance cost of maintaining multiple qualified suppliers.
Heavy Alkyl Benzenes Market Segmentation
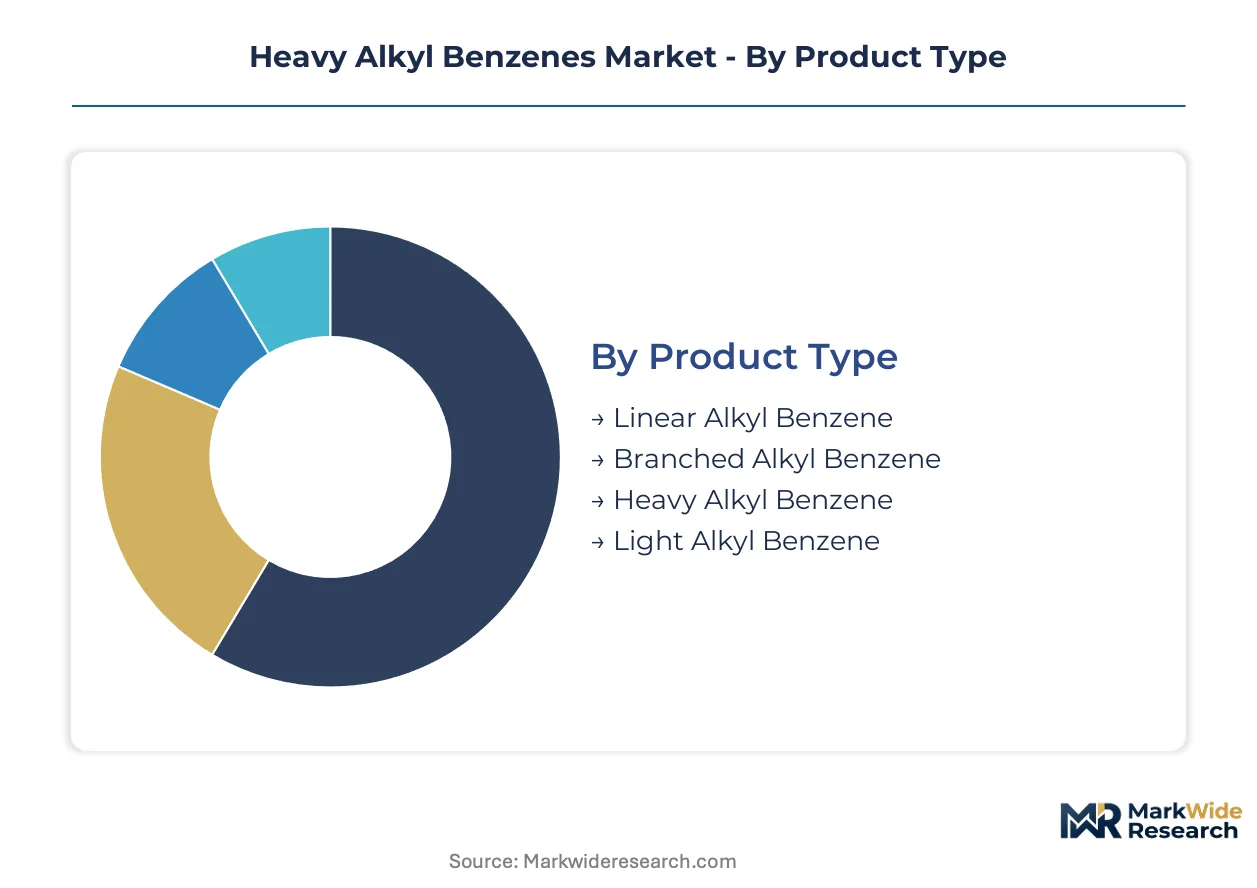
Heavy alkyl benzenes serve dual commercial pathways: direct sulfonation for surfactant production and captive consumption within integrated detergent and lubricant additive manufacturing. Segment boundaries reflect where producers monetize spot chemical sales versus long-term offtake contracts with formulation houses.
Product Type:
Integration depth separates commodity-grade materials consumed in standalone sulfonation plants from specification-critical streams embedded in lubricant additive synthesis.
- Linear Alkyl Benzene:Straight-chain C10-C14 alkylbenzene isomers produced via UOP Pacol-Olex or alkylation with linear olefins. European household detergent formulators in Germany and France are substituting bio-based surfactants for linear alkyl benzene sulfonates under REACH biodegradability pressure.
- Branched Alkyl Benzene:Highly branched C13-C17 isomers from chloroparaffin or propylene tetramer alkylation. India's Gujarat chemical corridor sustains dominant demand from industrial cleaning compounders where BIS specifications remain less stringent than EU counterparts.
- Heavy Alkyl Benzene:Higher-molecular-weight C13-C17 fractions commanding lubricant additive premiums. Captive consumption dominates in China's Shandong province where integrated producers bypass merchant markets.
- Light Alkyl Benzene:Lower-boiling C10-C12 fractions primarily directed to specialty solvent applications. Niche volumes serve pharmaceutical extraction processes in Switzerland and laboratory chemical supply chains.
Branched alkyl benzene leads volumes today; heavy alkyl benzene is gaining share fastest through lubricant additive specification premiums.
Application:
Cost tier stratification separates commodity surfactant formulations from margin-protected lubricant additive packages requiring certification documentation.
- Surfactants:Sulfonated alkyl benzene derivatives for emulsification and wetting. REACH candidate list expansion is elevating trace impurity disclosure burdens for European surfactant manufacturers sourcing C13-C17 isomer mixtures.
- Detergents:Heavy alkyl benzene sulfonates in powder and liquid cleaning formulations. India's western chemical belt is scaling captive sulfonation capacity to serve domestic detergent compounders.
- Lubricants:Additive precursor streams for motor oil and industrial lubricant packages. EPA fuel additive registration timelines extend commercialization cycles for reformulated heavy alkyl benzene grades in the US market.
- Chemical Intermediates:Feedstock for further derivatization into specialty chemicals. Swiss and German fine chemical houses command specification premiums for chromatographically verified isomer distributions.
Surfactant applications anchor current consumption; lubricant-grade intermediates are climbing the fastest on technical specification premiums.
End User:
Customer type determines procurement pattern: household formulators favor quarterly spot purchasing while industrial and automotive end users lock multi-year supply agreements.
- Household:Consumer detergent and cleaning product manufacturers. European formulators face substitution pressure from bio-based alternatives under EU Green Deal sustainability mandates.
- Industrial:Metalworking fluids, degreasers, and process chemicals. China's Shandong and Jiangsu provincial clusters are consolidating supplier relationships around integrated petrochemical producers.
- Automotive:Motor oil additive packages and fuel system treatments. US lubricant additive houses dual-source certified streams to mitigate EPA registration approval delays.
- Agricultural:Pesticide emulsifiers and crop protection formulations. India's agrochemical sector pulls sulfonation-ready feedstock through Gujarat's chemical corridor infrastructure.
Industrial end users dominate offtake volumes today; automotive applications are expanding most quickly on lubricant specification tightening.
Distribution Channel:
Supply concentration shapes channel selection: direct relationships prevail for high-volume detergent compounders while fragmented mid-tier buyers rely on distributor networks.
- Direct Sales:Long-term offtake agreements between integrated petrochemical producers and large-scale sulfonation operators. China's environmental inspections have raised compliance costs of maintaining multiple qualified suppliers.
- Online Sales:Digital procurement platforms reducing transaction friction for mid-volume compounders. Specialty chemical distributors are launching spot-market interfaces for specification-grade material.
- Distributors:Regional chemical distributors bundling certification documentation for smaller formulation houses. REACH registration dossier burdens disproportionately burden European traders without in-house compliance capacity.
- Wholesalers:Bulk material handlers serving spot-market purchasers with less stringent purity requirements. India's domestic detergent sector accesses branched alkyl benzene through Gujarat-based wholesale channels.
Direct sales channels command the largest volume share today; online procurement platforms are gaining traction fastest among mid-tier compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's detergent sulfonation capacity is expanding faster than China's lubricant additive integration, creating divergent demand profiles across Asia. European REACH compliance costs are compressing merchant market volumes while US Gulf Coast production maintains cost leadership through paraffin integration.
China
Shandong province's petrochemical clusters consume heavy alkyl benzenes for captive lubricant additive synthesis, bypassing merchant markets entirely. MEE environmental inspections have raised compliance costs for maintaining multiple qualified suppliers, consolidating procurement around integrated producers. Fushun Petrochemical anchors northeastern supply through captive demand in the Liaoning petrochemical belt.
India
Gujarat's chemical corridor is scaling sulfonation-ready feedstock consumption for domestic detergent compounders serving household and industrial cleaning markets. BIS detergent raw material specifications remain less stringent than EU counterparts, sustaining cost-advantaged branched alkyl benzene demand. Reliance Industries leverages Jamnagar refinery integration to supply western India's integrated detergent plants.
United States
Gulf Coast paraffin-to-alkylate conversion anchors North American heavy alkyl benzene supply through integrated refinery-petrochemical complexes. EPA fuel additive registration timelines extend commercialization cycles for reformulated lubricant-grade streams. Chevron Phillips Chemical sustains cost leadership through Beaumont and Pasadena production assets.
Germany
Ruhr industrial region lubricant additive houses dual-source certified heavy alkyl benzene streams to mitigate ECHA registration uncertainty. REACH candidate list expansion elevates trace impurity disclosure requirements for C13-C17 isomer mixtures sold into EU member states. BASF and Lanxess anchor demand through Ludwigshafen and Leverkusen additive formulation centers.
South Africa
Sasol's Secunda Fischer-Tropsch complex sustains cost-advantaged branched alkyl benzene output through synthetic paraffin integration unavailable elsewhere. African industrial cleaning compounders pull sulfonation-ready feedstock through Durban and Johannesburg distribution nodes. Regional demand concentrates in mining chemicals and metalworking fluid applications where biodegradability standards remain permissive.
Heavy Alkyl Benzenes Market Competitive Landscape
Top-tier vendors anchor integrated petrochemical supply, while regional sulfonation specialists occupy mid-tier toll-manufacturing positions. The competitive map stratifies across three archetypes: Fischer-Tropsch-integrated African producers, Gulf Coast refinery-integrated North American suppliers, and Asian state-affiliated petrochemical conglomerates with captive demand networks. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, displacing quarterly spot purchasing for volume detergent compounders.
Within the integrated production tier, Sasol exemplifies Fischer-Tropsch-based cost structure differentiation, while Chevron Phillips Chemical occupies the North American refinery-integrated position. Reliance Industries represents the Asian state-affiliated archetype with captive demand anchoring through western India's chemical corridor. These three entities collectively illustrate how feedstock integration depth determines competitive positioning across merchant and captive market segments.
| Leading Market Players |
|---|
| Huntsman Performance Products |
| ISU Chemical |
| Sasol |
| Chevron Phillips Chemical |
| ExxonMobil |
| CEPSA Quimica |
| Fushun Petrochemical |
| SEEF Limited |
| Reliance Industries Limited |
| Others |
Supply & Pricing Matrix
Specialized sulfonation engineers concentrated in India's Gujarat chemical corridor and China's Shandong province command wage premiums that compress margin spreads between economy-grade branched alkyl benzene and specification-critical lubricant streams. Labor-cost differentials between these regional clusters and European additive houses widen pricing-tier spreads as REACH compliance investments accumulate.
Pricing Analysis
Capacity additions in China's Shandong province are reshaping price floors for sulfonation-ready feedstock as provincial petrochemical clusters expand captive consumption. Contract-based long-term offtake agreements dominate, with price differentiation resting on certification grade and volume scale. Cost compression in industrial surfactant grades intensifies as India's detergent compounders scale captive sulfonation capacity. Household detergent formulators exhibit highest price sensitivity; automotive lubricant additive houses demonstrate lowest sensitivity due to specification lock-in.
Supply Chain Analysis
India's domestic-content mandates for detergent raw materials under BIS specifications are reshaping sourcing patterns for western India's chemical corridor. Supply draws from South Africa's Fischer-Tropsch complexes, the US Gulf Coast paraffin-to-alkylate conversion corridor, and China's northeastern petrochemical belt. Feedstock dependencies center on linear olefins, chloroparaffins, and synthetic paraffin streams. Single-source vulnerability concentrates around Gulf Coast hurricane exposure. Distribution runs through integrated petrochemical producers with bundled certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where lubricant-grade heavy alkyl benzene specifications are tightening faster than surfactant-grade commoditization. The demand-shift toward EPA-registered and REACH-certified additive streams rewards producers with in-house chromatographic verification capacity.
For Market Incumbents: Lock in multi-year offtake agreements with Shandong and Gujarat detergent compounders before provincial environmental inspections consolidate procurement further. Deepen backward integration into synthetic paraffin supply or Fischer-Tropsch feedstock to defend margin position against Sasol's cost structure. Prioritize certification investment for REACH candidate list compliance to capture technical premiums from European lubricant additive houses facing ECHA registration uncertainty. For New Entrants and Emerging Players: EU F-Gas Regulation opens a window for sulfonated alkyl benzene chemistry in industrial foam applications previously served by fluorinated surfactants. Target toll-manufacturing partnerships in China's Shandong province where integrated sulfonation capacity remains underdeveloped. India's agricultural emulsifier segment presents the most penetrable white space, with go-to-market execution through Gujarat-based wholesale channels serving domestic agrochemical formulators. For Investors and Strategic Acquirers: Integrated petrochemical conglomerates with captive demand networks are the most active acquirer in this space, seeking sulfonation-ready feedstock positions. Five-to-ten-year viability favors producers with Fischer-Tropsch integration or Gulf Coast paraffin access. Acquisition target archetype: regional sulfonation specialists with toll-manufacturing relationships in underpenetrated Chinese provinces. Watch for EPA fuel additive registration timeline compression as inflection signal for US lubricant-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Paraffin | Sasol's Fischer-Tropsch cost structure becomes replicable for margin defense. |
| Long-term Supply Agreement | Reliance Industries locks Gujarat detergent compounders into captive offtake structures. |
| Green Manufacturing Transition | REACH biodegradability pressure forces reformulation toward linear alkyl benzene streams. |
| Capacity Expansion | Chevron Phillips Chemical sustains Gulf Coast cost leadership through Beaumont asset utilization. |
| Joint Venture | Shandong provincial clusters attract toll-manufacturing partnerships for sulfonation-ready feedstock. |
Research Methodology
Multiple input streams — technical discussions with sulfonation plant managers, procurement leads at lubricant additive houses, distribution channel partners in India's chemical corridor, and regulatory affairs specialists navigating REACH dossiers — were reconciled against customs and trade data, Cefic industry reports, and SEC filings from integrated petrochemical producers. Secondary validation drew from EPA additive registration databases and ECHA substance evaluation records. Bottom-up volume modeling across detergent and lubricant end-uses was cross-checked against top-down petrochemical capacity assessments.
Historical capacity utilization patterns were cross-referenced against panel input from procurement directors at formulation houses to anchor growth trajectory assumptions across the analysis window. Segmentation modeling incorporated grade tier, end-use industry, regional production hub, and sulfonation integration depth. CAGRs were derived through regression analysis of feedstock demand against downstream capacity expansion announcements, with specific weighting applied to MEE environmental inspection timelines and BIS specification evolution.
Revisions become necessary when REACH candidate list expansion accelerates beyond current ECHA review schedules or when Gulf Coast hurricane disruption exceeds historical frequency patterns. Forecasts reflect documented assumptions regarding chloroparaffin alkylation cost structures and linear olefin substitution elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Barium Sulphate Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Foundry Coke Market
Bulk Chemicals
Carbon Black Market
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
Sodium Hypophosphite Market
Bulk Chemicals
Isopentane Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
North America and Europe Palm Derivatives Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
Sodium Gluconate Market