
 Mexico Caustic Soda Market | 2026-2036
Mexico Caustic Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Caustic Soda Market Foresight
Gulf Coast chlor-alkali producers is rebalancing supply flows toward Mexican industrial corridors as US export capacity redirects southward. Dow leverages its integrated petrochemical network to sustain feedstock advantages across the border region. Olin Corporation anchors membrane-cell technology leadership that differentiates its cost position in caustic soda manufacturing. Westlake Chemical Corporation competes through geographic proximity to Texas-Mexico logistics corridors.
Caustic soda, or sodium hydroxide, is an inorganic base produced primarily through the chlor-alkali electrolysis of sodium chloride brine, yielding a co-product of chlorine gas and hydrogen; the substance typically assays at 50% concentration in liquid form and serves as a fundamental reagent in pH adjustment, chemical synthesis, and industrial cleaning operations. Liquid caustic soda dominates volume flows due to its handling efficiency in pipeline-fed chemical parks, while flake and pearl grades command premium positioning in specialty detergent and aluminum processing applications where precise dosing and storage stability matter. Water treatment represents a structurally expanding end-use channel as Mexican municipalities upgrade municipal and industrial effluent systems under tighter discharge mandates.
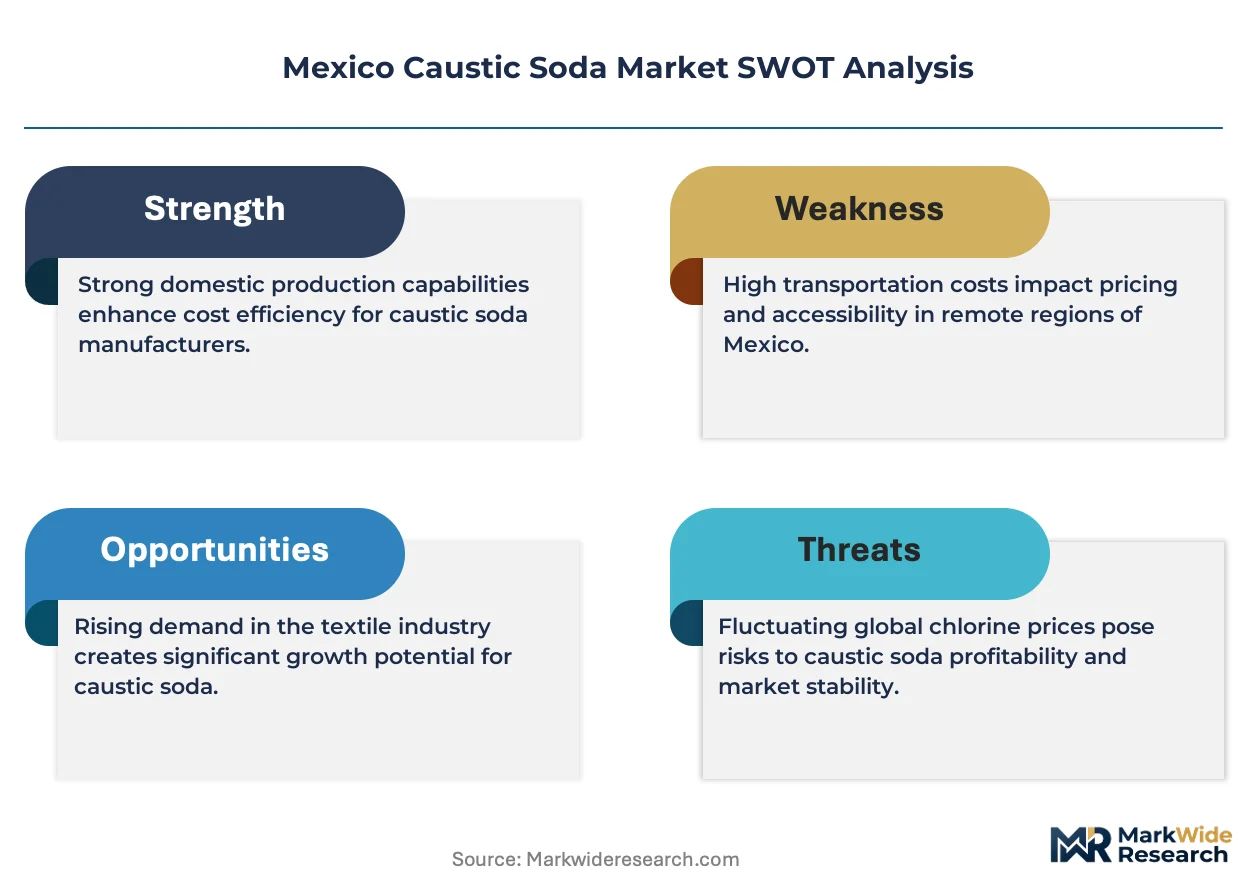
SEMARNAT enforces NOM-001-SEMARNAT wastewater discharge limits that compel industrial users to standardize caustic soda purity and documentation, while PROFECO oversees commercial labeling and measurement accuracy for chemical distribution. COFEPRIS regulates food-grade caustic soda applications in processing facilities, creating a bifurcated compliance landscape between technical and food-contact grades. Stakeholders must monitor how Mexico's energy transition policies reshape electricity pricing for electrolytic production and whether coastal desalination projects open new demand vectors for membrane-grade material.
Market Dynamics
Chlor-alkali membrane technology is displacing mercury-cell production across Mexican petrochemical corridors, forcing asset retooling and reshaping electricity consumption patterns for electrolytic operations. SEMARNAT enforcement of NOM-001-SEMARNAT wastewater standards is tightening purity documentation requirements, compressing margins for non-compliant distributors.
Growth Catalysts
- Paper and pulp capacity expansion:Wood pulp processors in Veracruz and Tabasco are scaling caustic soda intake for kraft pulping and bleaching sequences, creating sustained offtake commitments.
- NOM-001-SEMARNAT discharge mandates:Industrial wastewater treatment upgrades are standardizing caustic soda procurement for pH neutralization and heavy metal precipitation.
- Coastal desalination pipeline:Membrane-grade caustic soda demand is emerging from pre-treatment chemical dosing in proposed Pacific and Gulf desalination facilities.
Market Restraints
- Electricity cost volatility:Electrolytic production depends on CFE industrial tariffs, which fluctuate with natural gas import pricing and transmission congestion.
- US Gulf supply concentration:Chlor-alkali capacity concentrates in Texas and Louisiana, exposing Mexican buyers to pipeline disruption and hurricane-season supply interruptions.
- Chlorine co-product absorption:Caustic soda output ties to chlorine generation, and PVC or disinfectant demand lags create caustic inventory gluts that depress pricing.
Strategic Opportunities
- Baja California water stress:Municipal and industrial desalination projects in Tijuana and Ensenada are opening membrane-grade caustic soda demand vectors for pre-treatment scaling control.
- Food-grade certification expansion:COFEPRIS-regulated tortilla and beverage processors are formalizing caustic soda specifications for equipment cleaning and pH adjustment.
- Pipeline-fed chemical parks:Coatzacoalcos-Minatitlán petrochemical clusters are integrating caustic soda into shared utility networks, reducing drum handling and logistics costs.
Industry Challenges
- Membrane-cell technician scarcity:Electrolyzer maintenance and cell replacement require specialized skills concentrated in US and European chlor-alkali operations, not readily available in Mexican labor markets.
- Dual-grade inventory complexity:Technical-grade and food-grade caustic soda require segregated storage, documentation chains, and tank cleaning protocols that inflate working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Caustic Soda Market |
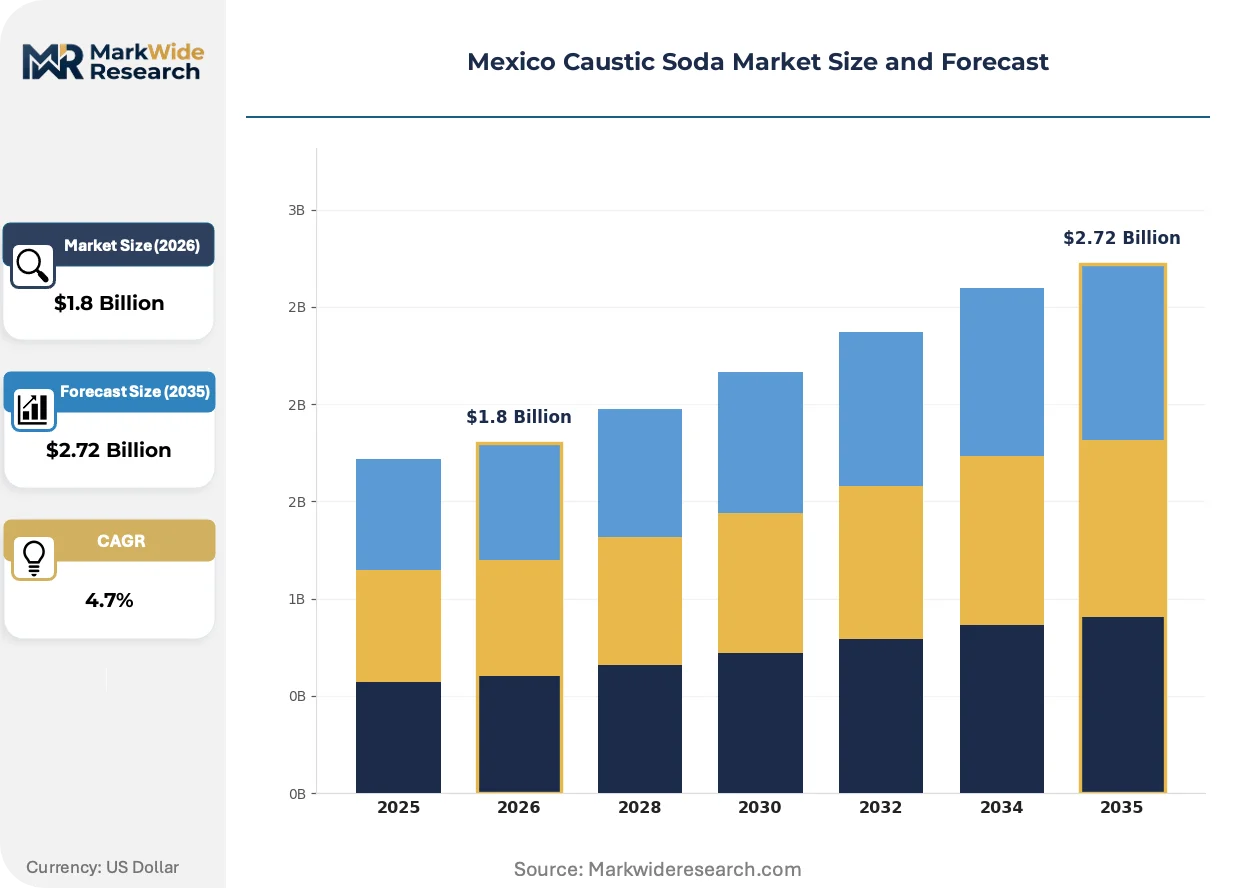
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flake, Liquid, Pearls, Solid End User: Paper & Pulp, Textiles, Soap & Detergents, Water Treatment Application: Chemical Manufacturing, Food Processing, Oil Refining, Mining Distribution Channel: Direct Sales, Wholesale, Online Retail, Distributors |
| Companies Covered | Dow, Olin Corporation, Covestro AG, FMC Corporation, Occidental Petroleum Corporation, SABIC, Nouryon, Westlake Chemical Corporation, QUÍMICA TREZA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Caustic Soda Market Shifts & Advancements
Membrane electrolysis is consolidating production economics while digital monitoring systems are reshaping how buyers verify purity and chain-of-custody documentation. These shifts are compressing the role of traditional chemical distributors.
Membrane-cell technology is decentralizing caustic soda production economics by enabling smaller-scale, energy-efficient electrolysis units with lower brine purification overhead. Paper mills and municipal water treatment facilities are piloting modular membrane systems for on-site generation, reducing bulk liquid transport dependency. This distributed model is compressing traditional distributor margins in corridor-proximate industrial zones.
SEMARNAT is tightening NOM-001-SEMARNAT enforcement protocols, requiring continuous discharge monitoring and standardized caustic soda purity certificates for effluent neutralization. Industrial users must now document lot-specific assay data and supplier chain-of-custody records. Food processing and textile dyeing facilities in Puebla and Jalisco are consolidating suppliers to reduce compliance audit burden.
Buyers are unbundling caustic soda procurement from bundled chemical service contracts, separating commodity supply from application engineering and dosing system maintenance. Large pulp mills and refineries are direct-contracting with chlor-alkali producers while outsourcing technical service to specialized equipment vendors. This bifurcation is most visible in Veracruz petrochemical corridors where pipeline access enables volume-direct relationships.
Mexico Caustic Soda Market Segmentation
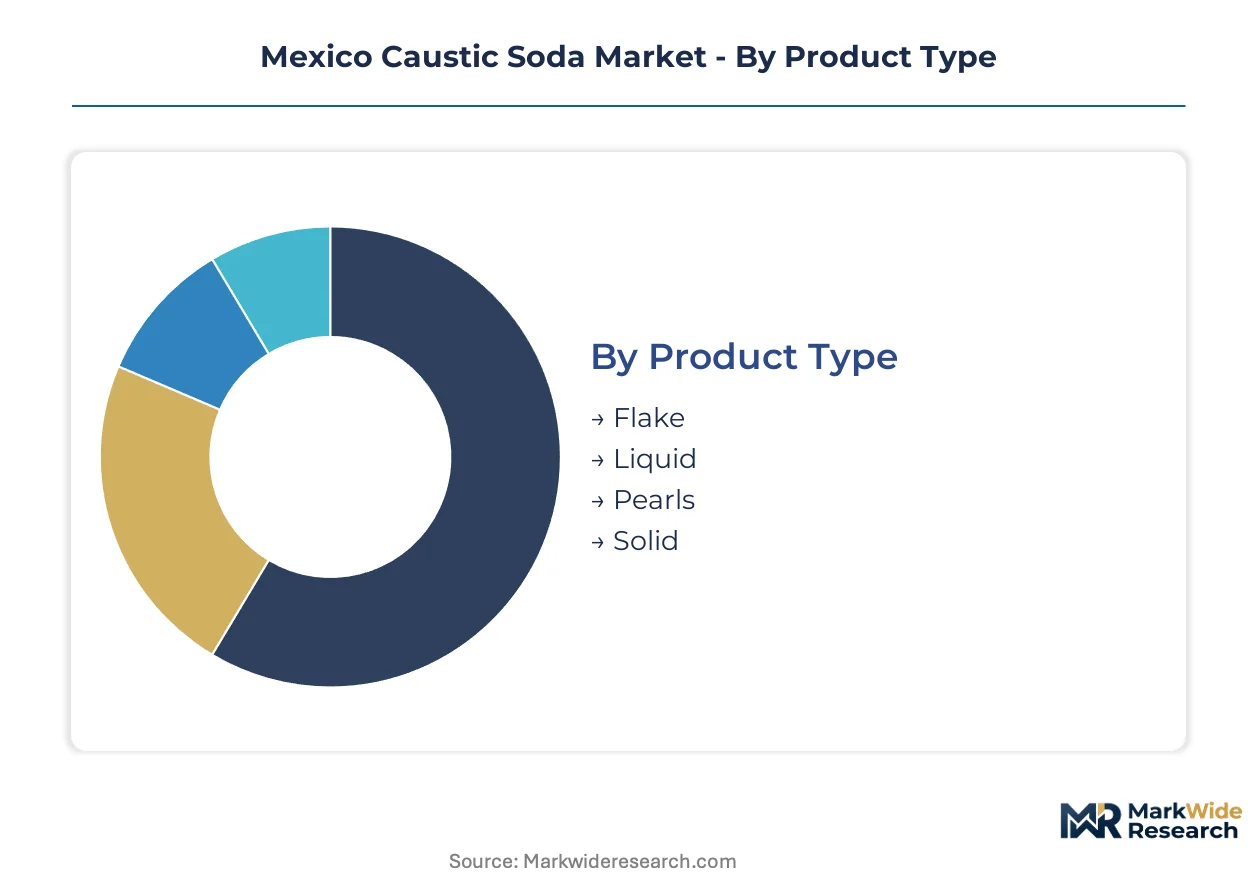
Caustic soda procurement patterns in Mexico diverge sharply across physical forms, end-use chemistry, and logistics infrastructure. Each segmentation axis carries distinct margin structures and compliance burdens that reshape supplier relationships and regional competitive positioning.
Product Type:
Membrane-cell electrolysis yields caustic soda in multiple physical states, each optimized for distinct handling economics and purity thresholds.
- Liquid:Pipeline-fed chemical parks in Coatzacoalcos-Minatitlán consume 50% concentration liquid via dedicated tankage, eliminating drum handling costs. Veracruz petrochemical clusters anchor the heaviest offtake as shared utility networks displace packaged chemical logistics.
- Flake:Solidified through evaporation and flaking drums, this grade delivers precise dosing control for aluminum smelting and specialty detergent manufacturing. Tabasco and Jalisco industrial zones concentrate demand where storage stability and metered feed systems justify premium positioning.
- Pearls:Spherical granules produced through controlled prilling offer superior flow characteristics for automated handling equipment. Puebla textile dyeing facilities favor pearl grades for pH adjustment in batch processing.
- Solid:Cast or extruded blocks serve remote mining operations and small-scale water treatment plants lacking liquid bulk infrastructure. Baja California desalination pre-treatment sites represent emerging solid-grade demand.
Mature deployment sits with Liquid. Newer deployment is concentrated in Pearls as automated dosing systems penetrate mid-sized processing facilities.
End User:
Cost tier stratification separates commodity-scale consumers from specialty-grade buyers with divergent purity documentation requirements.
- Paper & Pulp:Kraft pulping and bleaching sequences consume caustic soda at massive scale, with Veracruz wood processors driving sustained offtake. NOM-001-SEMARNAT discharge mandates compel integrated wastewater neutralization systems that lock in volume commitments.
- Water Treatment:Municipal and industrial effluent systems represent the steepest expansion trajectory as SEMARNAT tightens enforcement. Tijuana and Ensenada desalination projects are opening membrane-grade demand vectors for pre-treatment scaling control.
- Soap & Detergents:Saponification and pH adjustment in cleaning product manufacturing relies on technical-grade liquid supply. Guadalajara chemical formulators concentrate procurement through regional distributors.
- Textiles:Mercerization and dyeing processes in Puebla and Jalisco demand consistent purity for fabric treatment. COFEPRIS-regulated facilities are consolidating suppliers to reduce compliance audit burden.
Procurement consolidation is most advanced in Paper & Pulp. Fragmented buying persists in Textiles as smaller dye houses resist supplier reduction mandates.
Application:
Volume scale separates process-chemical consumption from food-contact and specialty refining applications with divergent certification overhead.
- Chemical Manufacturing:Chlor-alkali derivatives, sodium salts, and organic synthesis consume caustic soda as fundamental feedstock. Coatzacoalcos petrochemical corridors integrate this demand into continuous process flows.
- Oil Refining:Acid neutralization and mercaptan extraction in PEMEX facilities and private refineries drives technical-grade procurement. Salina Cruz and Cadereyta refineries anchor Gulf Coast demand concentration.
- Food Processing:COFEPRIS-regulated tortilla and beverage processors require food-grade certification for equipment cleaning and pH adjustment. Segregated storage and documentation chains inflate working capital requirements.
- Mining:Gold and silver extraction via cyanide leaching uses caustic soda for pH control in precious metal recovery. Zacatecas and Sonora operations represent dispersed, logistics-intensive demand.
Pipeline-fed integration dominates Chemical Manufacturing. Drum-supplied dispersion characterizes Mining procurement economics.
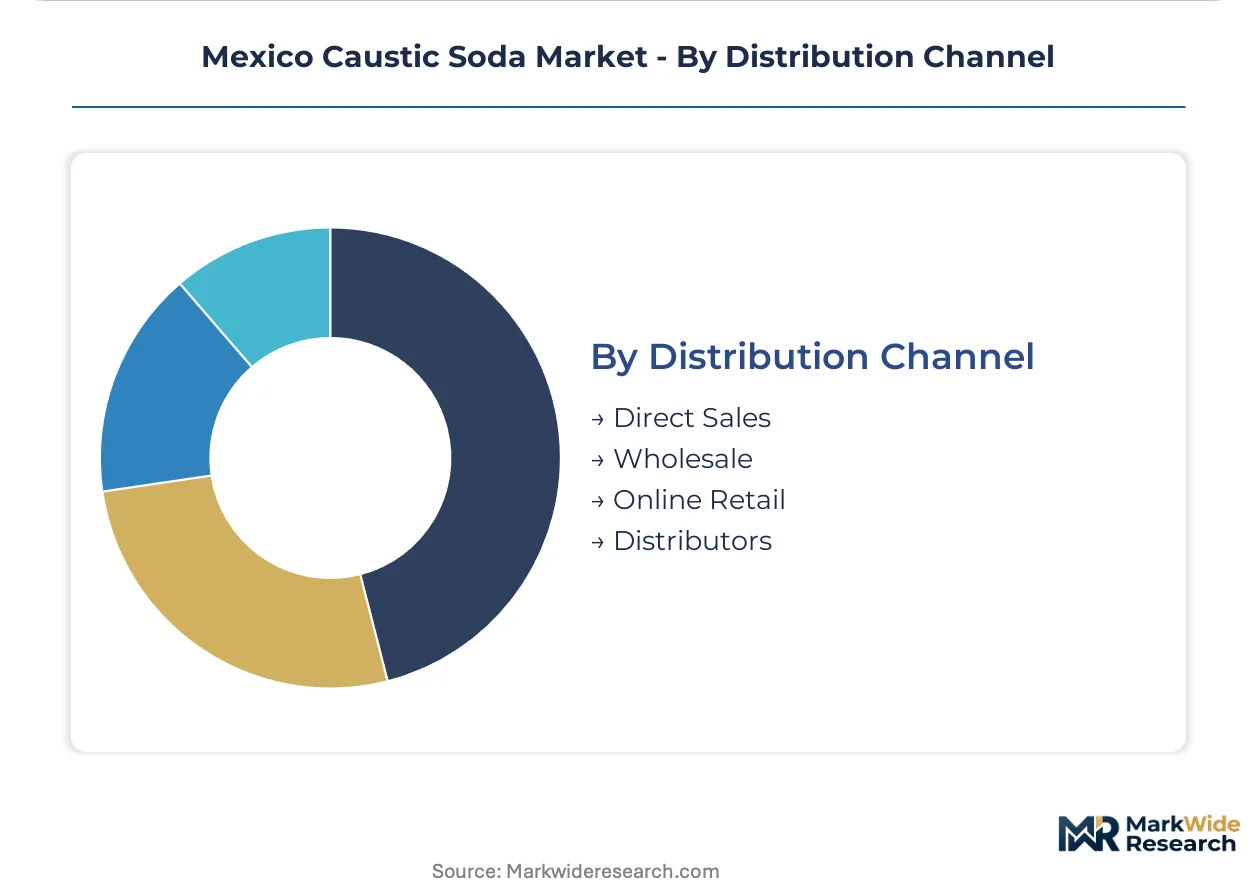
Distribution Channel:
Customer scale and geographic proximity determine whether direct producer relationships or intermediary networks capture value.
- Direct Sales:Chlor-alkali producers contract volume-direct with Veracruz pulp mills and refineries possessing pipeline access or dedicated tankage. This bifurcation compresses traditional distributor margins in corridor-proximate zones.
- Distributors:Regional chemical handlers manage inventory, documentation, and last-mile logistics for mid-sized consumers lacking bulk infrastructure. Puebla and Jalisco industrial zones rely heavily on distributor networks.
- Wholesale:Bulk breakers and cash-and-carry operations serve small water treatment plants and artisanal soap makers. Price transparency pressures margins in this tier.
- Online Retail:E-commerce platforms capture laboratory-scale and maintenance-repair-operations demand, particularly for flake and pearl grades in research and small food processing facilities.
Margin compression is most severe in Wholesale. Digital channel penetration is climbing fastest in Online Retail as procurement unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Salt dome formations along the Gulf Coast feed chlor-alkali electrolysis across Mexican industrial corridors. Veracruz petrochemical clusters leverage this feedstock proximity to anchor membrane-cell production capacity.
Veracruz
Coatzacoalcos-Minatitlán chemical parks consume pipeline-fed liquid caustic soda at massive scale for shared utility networks. SEMARNAT enforces NOM-001-SEMARNAT discharge documentation that compels integrated wastewater neutralization systems. Pulp mills in the region are locking in volume commitments for kraft bleaching sequences.
Tabasco
Wood processors are scaling caustic soda intake for kraft pulping operations alongside emerging water treatment infrastructure. The state's industrial zones face tightening effluent standards under federal environmental mandates. Paraíso and Cárdenas industrial corridors concentrate demand for flake-grade material in aluminum processing applications.
Jalisco
Guadalajara chemical formulators drive technical-grade liquid procurement for soap and detergent manufacturing. COFEPRIS-regulated food processing facilities require segregated storage protocols for equipment cleaning applications. Regional distributors manage last-mile logistics for mid-sized consumers lacking bulk tankage infrastructure.
Baja California
Tijuana and Ensenada desalination projects are opening membrane-grade caustic soda demand vectors for pre-treatment scaling control. Municipal water stress is accelerating infrastructure investment under state water authority programs. Coastal facilities represent emerging solid-grade consumption for remote operations lacking pipeline access.
Puebla
Textile dyeing facilities favor pearl-grade caustic soda for pH adjustment in batch mercerization processes. COFEPRIS compliance audits are driving supplier consolidation among smaller dye houses. The state's industrial zones rely heavily on distributor networks for drum-supplied material.
Mexico Caustic Soda Market Competitive Landscape
Global majors compete with regional champions across feedstock integration and membrane-cell technology deployment. The vendor base stratifies between integrated petrochemical conglomerates with captive chlorine absorption and specialized chlor-alkali operators focused on merchant caustic supply. Three archetypes dominate: Gulf Coast exporters leveraging pipeline proximity, European chemical multinationals with technology licensing positions, and Mexican regional distributors managing compliance-heavy last-mile logistics. Capacity expansion and direct sales bifurcation represent the dominant competitive moves reshaping channel economics.
Among US-based integrated producers, Dow and Olin Corporation exemplify the Gulf Coast export archetype, anchoring supply flows toward Mexican industrial corridors through pipeline-fed logistics networks. Westlake Chemical Corporation occupies a position within the geographic proximity tier, competing through Texas-Mexico corridor access. These three entities represent distinct strategic postures: feedstock-integrated petrochemical networks, membrane-cell technology leadership, and border-proximate distribution optimization.
| Leading Market Players |
|---|
| Dow |
| Olin Corporation |
| Covestro AG |
| FMC Corporation |
| Occidental Petroleum Corporation |
| SABIC |
| Nouryon |
| Westlake Chemical Corporation |
| QUÍMICA TREZA |
| Others |
Supply & Pricing Matrix
NOM-001-SEMARNAT wastewater discharge compliance gates qualified caustic soda supply and premium-tier pricing access, as industrial buyers must document lot-specific assay data and supplier chain-of-custody records to avoid enforcement penalties. Technical-grade liquid flows through pipeline-fed corridors at contract-based rates, while food-grade and membrane-grade materials command substantial premiums due to segregated storage protocols and COFEPRIS certification overhead.
Pricing Analysis
Service-bundling unbundling is reshaping how buyers contract caustic soda, with large Veracruz pulp mills and refineries separating commodity procurement from application engineering and dosing system maintenance. Three-tier pricing structure across membrane-grade, technical-grade, and solid-block grades reflects purity certification and handling infrastructure requirements. Cost compression in technical-grade liquid is intensifying because direct producer relationships are bypassing traditional distributor margins in corridor-proximate zones. Small water treatment plants and artisanal soap makers exhibit the highest price sensitivity, while pipeline-integrated petrochemical clusters lock in long-term offtake commitments with limited elasticity.
Supply Chain Analysis
Rail and tanker freight costs from Texas and Louisiana chlor-alkali corridors dominate landed pricing for Mexican buyers, with hurricane-season disruption risk concentrated in third-quarter delivery windows. Supply concentrates in the US Gulf Coast, with secondary flows from European membrane-cell producers and emerging Mexican domestic capacity. Raw material dependencies center on salt dome access, electricity from CFE industrial tariffs, and brine purification chemicals. Single-source vulnerability runs through the Texas-Mexico pipeline network. Distribution runs through direct producer contracts for corridor-proximate volume buyers and regional distributor networks for drum-supplied mid-tier consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolytic production capacity constraints in Mexican chlor-alkali operations prop pricing power, as membrane-cell technician scarcity and electricity cost volatility limit domestic supply expansion.
For Market Incumbents: To counter distributor margin compression from direct sales bifurcation, anchor volume commitments through integrated wastewater neutralization system contracts with Veracruz pulp mills and invest in membrane-cell technician training programs to reduce maintenance outsourcing dependency. For New Entrants and Emerging Players: NOM-001-SEMARNAT enforcement in Mexico opens a window for membrane-grade caustic soda specialization targeting Baja California desalination pre-treatment projects, with food-grade certification services representing the most penetrable adjacent segment. Pursue joint venture structures with established distributors to bypass tankage infrastructure barriers. For Investors and Strategic Acquirers: CFE industrial tariff restructuring announcements are the leading indicator that electrolytic production economics will shift across the analysis window. Target regional Mexican distributors with established COFEPRIS documentation capabilities and pipeline access rights in Coatzacoalcos-Minatitlán corridors as consolidation candidates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salt Dome Access | Captive brine supply from Gulf Coast formations reduces feedstock cost volatility for electrolytic operations. |
| Membrane-Grade Certification Investment | COFEPRIS and SEMARNAT dual compliance opens desalination and food processing premium segments. |
| Pipeline Infrastructure Partnership | Shared utility networks in Coatzacoalcos-Minatitlán corridors displace drum logistics for volume buyers. |
| Long-Term Supply Agreement with Pulp Mills | Kraft bleaching volume commitments lock in offtake against US Gulf import competition. |
| Joint Venture for Technician Training | Membrane-cell maintenance skills scarcity constrains domestic capacity expansion without workforce development. |
Research Methodology
Independent corroboration across chlor-alkali plant managers, procurement leads at Veracruz pulp mills, distribution channel partners, and SEMARNAT regulatory officers underwrites the qualitative findings in this study. Primary interviews with technical R&D directors at membrane-cell operators combined with secondary validation from customs/trade data, ACC and Cefic industry reports, and SEC 10-K filings from US Gulf producers established demand and supply parameters. Bottom-up segmentation modeling and top-down macroeconomic triangulation reconciled volume estimates across the analysis window.
Rate-of-change decomposition across grade tier, end-use industry, packaging format, and regional production hub segmentation dimensions shaped the analytical framework. CAGRs were derived from electrolyzer capacity expansion timelines, electricity tariff trajectory assumptions, and pulp mill capacity commissioning schedules. Chlorine co-product absorption rates and membrane-grade purity certification adoption curves served as industry-specific forecast inputs throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for mercury-cell phase-out acceleration or membrane-cell modularization would alter the outlook for domestic production economics and import dependency. Forecasts reflect assumptions about CFE tariff stability, NOM-001-SEMARNAT enforcement intensity, and hurricane-season supply disruption frequency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Carbon Black Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Phosphates Market
Bulk Chemicals
Magnesium Phosphate Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Global Butyl Acrylate Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market