
 Nitric Acid Market | 2026-2036
Nitric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Nitric Acid Market Analysis
Ammonia is decoupling from traditional feedstock economics in nitric acid production as renewable hydrogen pathways gain process traction. CF Industries Holdings, Inc. leverages its North American natural gas position to sustain cost leadership in merchant acid supply. Yara anchors European production networks through integrated ammonia-nitrate complexes. BASF SE differentiates via specialty-grade acid streams serving pharmaceutical and electronic chemical segments.
Nitric acid is a highly corrosive mineral acid with the chemical formula HNO₃, typically produced via the Ostwald process involving ammonia oxidation over platinum-rhodium catalysts at temperatures near 900°C, yielding concentrations of 50-70% for industrial use. Its primary purpose centers on ammonium nitrate fertilizer synthesis, adipic acid production for nylon manufacturing, and explosives formulation. Concentrated acid grades command premium positioning in chemical synthesis and rocket propellant applications where purity thresholds exclude dilute alternatives. The agriculture end-use industry absorbs the dominant volume share through fertilizer applications, while pharmaceutical and explosives segments retain higher margin profiles despite smaller throughput.
EPA regulations under the Clean Air Act mandate stringent NOx emissions controls at US production facilities, compelling capital deployment into catalytic reduction systems and process optimization. EU REACH frameworks classify nitric acid handling thresholds, shaping product stewardship obligations and cross-border trade documentation requirements. OSHA process safety management standards govern worker exposure limits and facility siting protocols domestically. Stakeholders must monitor hydrogen feedstock cost curves and carbon border adjustment mechanisms to assess long-term site competitiveness.
Market Dynamics
EPA NOx emissions mandates under the Clean Air Act are forcing capital redeployment into catalytic reduction systems and process optimization across US production facilities, compressing operating margins while raising barriers to facility expansion.
Growth Catalysts
- Ammonium nitrate fertilizer synthesis:Agricultural economies in Brazil, India, and China are expanding domestic manufacturing capacity to reduce import dependency.
- EU REACH product stewardship obligations:Cross-border trade documentation requirements are consolidating compliant suppliers and favoring integrated producers with established regulatory infrastructure.
- Platinum-rhodium catalyst efficiency gains:Process yield improvements at 900°C oxidation temperatures are lowering ammonia feedstock intensity per ton of acid output.
Market Restraints
- Natural gas feedstock volatility:Ammonia production costs swing with Henry Hub pricing, exposing merchant acid suppliers to margin compression without long-term supply contracts.
- Platinum group metal supply concentration:South African and Russian mining dominance creates catalyst cost and availability vulnerability for Ostwald process operators.
- Adipic acid process substitution:Bio-based nylon precursors and recycled polymer feedstocks are eroding demand for conventional nitric acid-derived intermediates.
Strategic Opportunities
- Renewable hydrogen ammonia pathways:Green hydrogen integration into nitric acid production is opening carbon-neutral product certification premiums in EU markets.
- Electronic-grade acid specialization:Semiconductor fabrication demand for ultra-high purity HNO₃ is creating margin expansion potential outside commodity fertilizer channels.
- Indian PLI scheme alignment:Domestic fertilizer manufacturing incentives are attracting capacity investments to serve South Asian agricultural demand growth.
Industry Challenges
- Platinum catalyst recovery expertise:Specialized metallurgical processing capabilities for spent gauze recycling are concentrated among a limited supplier base.
- Selective catalytic reduction retrofit complexity:Legacy plant NOx abatement upgrades require extended shutdown windows and precise integration with existing absorption trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitric Acid Market |
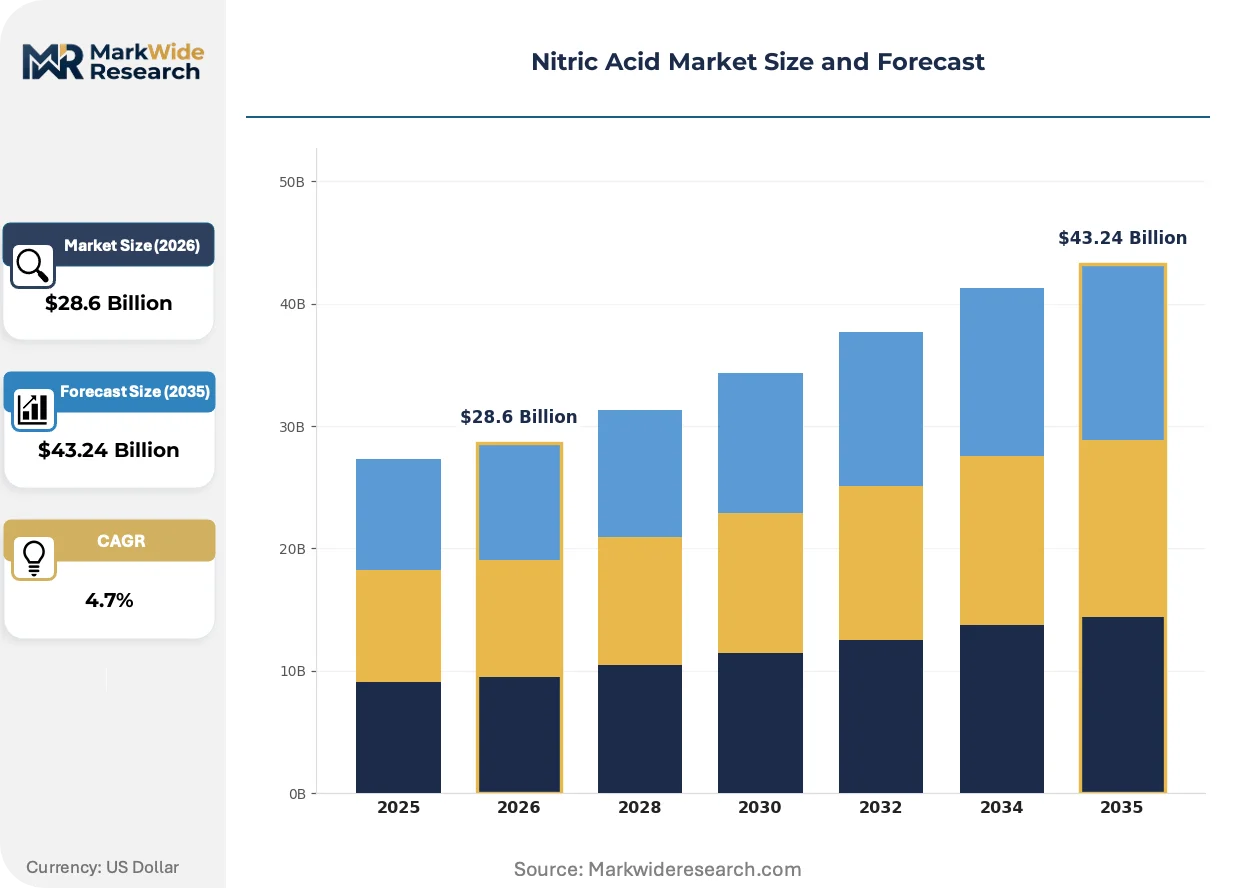
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated, Dilute, Fuming, Red Fuming End Use Industry: Agriculture, Pharmaceuticals, Explosives, Metal Processing Form: Liquid, Gas, Solid, Aerosol Application: Fertilizers, Rocket Propellant, Chemical Synthesis, Water Treatment |
| Companies Covered | CF Industries Holdings, Inc., Yara, BASF SE, Nutrien Ltd., LSB Industries, EuroChem Group, Sasol Limited, OCI Global, Omnia Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitric Acid Market Emerging Trajectories
Process decarbonization and purity grade stratification are fragmenting competitive positioning, with technology leaders separating from commodity producers through feedstock flexibility and specialty certification.
Membrane absorption technology is integrating into dilute acid concentration steps, replacing traditional distillation energy intensity. Fertilizer producers in water-stressed regions are adopting these systems to reduce steam demand and cooling water requirements. The technology is integrating process heat recovery into downstream ammonium nitrate crystallization, tightening energy economics for integrated complexes.
EU F-Gas Regulation phase-down schedules are pressuring refrigerant choices in acid storage and transport logistics, compelling facility operators to evaluate ammonia or CO₂-based cooling alternatives. Industrial gas suppliers are retrofitting bulk storage terminals to accommodate lower-global-warming-potential systems. European adipic acid producers face accelerated compliance timelines compared to other regions, reshaping capital allocation toward emission control rather than capacity expansion.
Specification-driven procurement now dominates electronic chemical and pharmaceutical acid purchasing, with buyers unbundling volume contracts from technical service packages. Semiconductor foundries in Taiwan and South Korea are consolidating supplier panels to three qualified sources per purity tier, compressing qualification cycles from 18 months to 9 months. This pattern is concentrating revenue among integrated chemical majors with dedicated electronic materials divisions.
Nitric Acid Market Segmentation
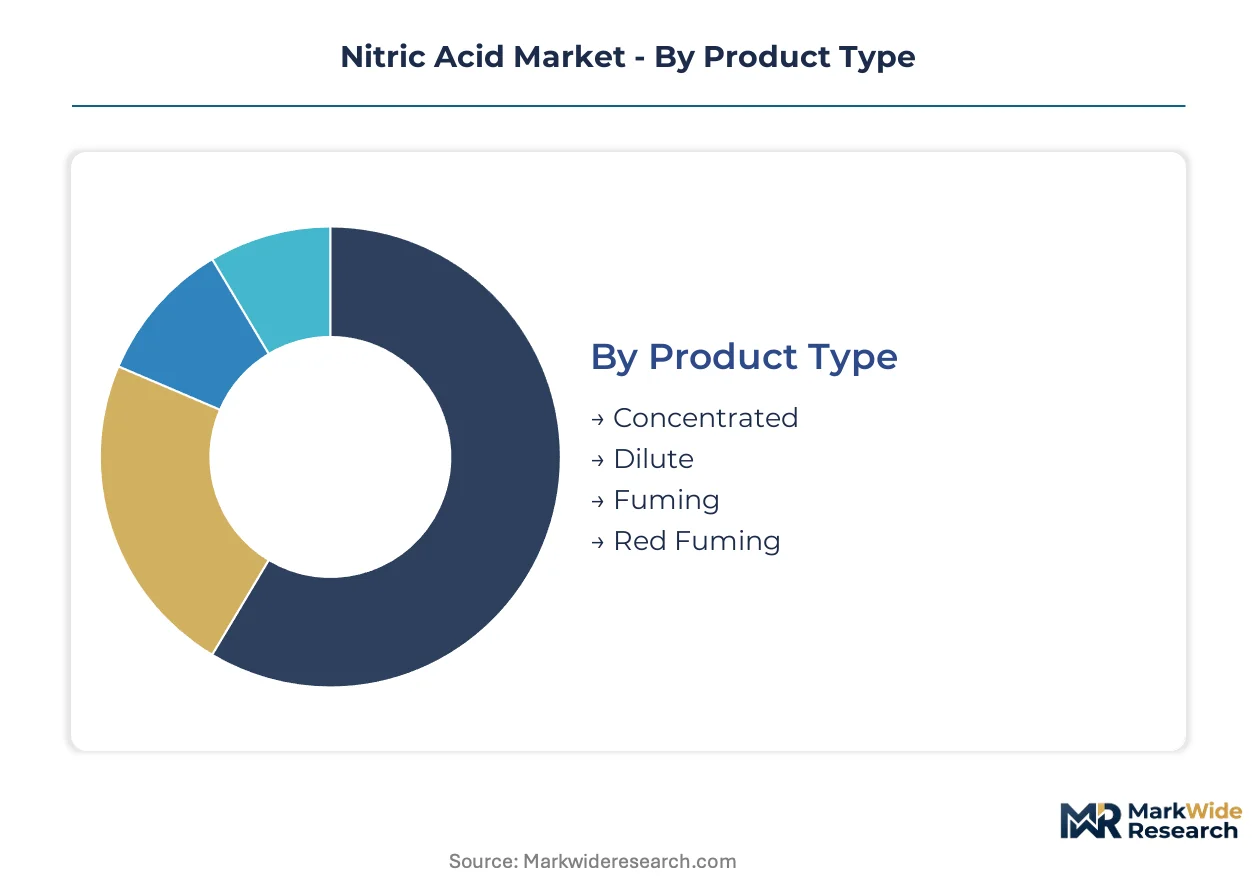
Nitric acid markets fragment across purity grades, physical states, and end-use specifications that dictate fundamentally different production economics and customer relationships. Each segmentation dimension carries distinct margin structures and capital intensity requirements that reshape competitive positioning.
Product Type:
Customization intensity varies sharply across this category, from commodity dilute grades to precision-engineered fuming variants requiring specialized handling infrastructure.
- Concentrated:68-70% HNO₃ concentration serves adipic acid synthesis and nitration chemistry where water content disrupts reaction stoichiometry. Demand concentrates in Germany and Belgium among integrated nylon producers facing EU ETS carbon cost pressure.
- Dilute:50-60% strength dominates ammonium nitrate fertilizer production through neutralization with ammonia. Agricultural economies in India and Brazil absorb volume through domestic manufacturing expansion under PLI-type incentives.
- Fuming:Dissolved NO₂ content above 2% enables specialized nitration reactions in pharmaceutical and dye intermediates.
- Red Fuming:Higher nitrogen dioxide saturation supports rocket propellant and explosives formulation with stringent military specification compliance.
Leading the category by volume: Dilute. Expanding most quickly: Concentrated.
End Use Industry:
Margin tiering separates this category, with agriculture at commodity economics and pharmaceuticals commanding certification premiums.
- Agriculture:Ammonium nitrate fertilizer synthesis absorbs the dominant volume share through integrated ammonia-acid complexes. China, India, and Brazil are expanding domestic capacity to reduce import dependency.
- Pharmaceuticals:cGMP-compliant acid grades for active pharmaceutical ingredient nitration require dedicated production trains and extensive documentation. FDA and EMA validation protocols create supplier stickiness.
- Explosives:Military and mining applications demand red fuming grades with precise nitrogen dioxide content control.
- Metal Processing:Pickling and passivation of stainless steel consumes acid in surface treatment operations.
Agriculture dominates tonnage. Pharmaceuticals show the steepest margin expansion trajectory.
Form:
Physical state determines logistics infrastructure requirements and customer handling protocols across this category.
- Liquid:Bulk tanker and railcar delivery dominates industrial supply chains with established hazard classification frameworks.
- Gas:Nitrogen dioxide vapor streams serve specialized chemical synthesis with on-site generation requirements.
- Solid:Ammonium nitrate and other salt derivatives represent downstream stabilized forms for transport safety.
- Aerosol:Pressurized packaging supports laboratory and small-scale industrial applications.
Liquid form leads by volume. Gas form is gaining share fastest in specialty chemical integration.
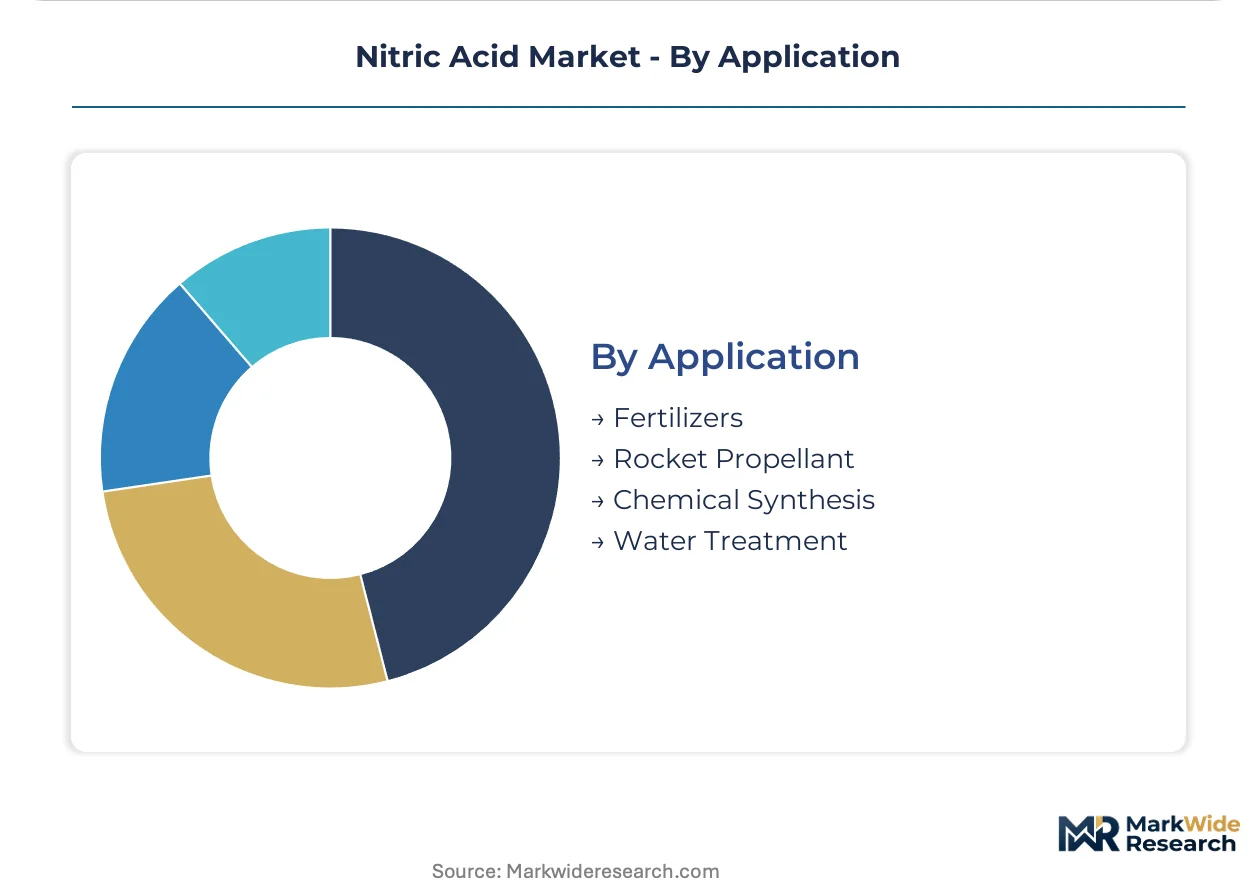
Application:
Customer procurement sophistication varies from bulk commodity tenders to multi-year qualification programs in this category.
- Fertilizers:Ammonium nitrate and calcium ammonium nitrate production anchor global acid demand with price-sensitive procurement patterns.
- Rocket Propellant:Red fuming nitric acid with precise inhibitor content serves hypergolic propulsion systems. ISRO and space agencies in the US maintain qualified supplier panels with multi-year validation cycles.
- Chemical Synthesis:Adipic acid for nylon-6,6 and nitrobenzene for aniline derivatives consume concentrated grades.
- Water Treatment:Metal passivation and pH adjustment applications utilize dilute acid in industrial wastewater systems.
Fertilizers lead by volume. Rocket propellant shows the fastest value growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, India, and Brazil absorb the dominant volume of nitric acid demand through fertilizer manufacturing expansion. Agricultural self-sufficiency programs and import substitution policies are reshaping capacity deployment across these agricultural economies. Regulatory tightening on nitrogen oxide emissions is forcing process technology upgrades in established production clusters.
China
Ammonium nitrate fertilizer output expansion drives acid consumption in Shandong and Jiangsu provinces. MEE enforcement of nitrogen oxide emission standards is accelerating catalytic reduction retrofits at existing facilities. The Yangtze River Delta concentration of chemical complexes is integrating membrane absorption technology to reduce energy intensity in dilute acid concentration.
United States
Merchant acid supply to domestic fertilizer blenders and adipic acid producers sustains Gulf Coast production economics. EPA Clean Air Act NOx mandates are compelling capital deployment into selective catalytic reduction systems at Louisiana and Texas facilities. The Ohio River Valley chemical corridor maintains integrated ammonia-nitrate complexes serving Corn Belt agricultural demand.
India
Domestic fertilizer manufacturing incentives under the PLI scheme are attracting greenfield acid capacity investments. Fertilizer Ministry directives on urea substitution are expanding ammonium nitrate absorption in Punjab and Haryana agricultural regions. The Gujarat chemical belt is developing integrated complexes to reduce import dependency on merchant acid supplies.
Germany
EU ETS carbon cost pressure on adipic acid synthesis is concentrating concentrated-grade demand in Ludwigshafen and Leverkusen chemical clusters. ECHA REACH product stewardship obligations are consolidating compliant supplier networks for cross-border fertilizer trade. The Rhine-Ruhr industrial region is piloting renewable hydrogen ammonia pathways for carbon-neutral acid certification.
Brazil
Soybean and corn cultivation expansion is driving ammonium nitrate fertilizer manufacturing investments in São Paulo and Paraná states. ANVISA chemical handling regulations are shaping product stewardship protocols for acid transport and storage logistics. The Triângulo Mineiro agricultural corridor is developing domestic blending capacity to reduce reliance on imported fertilizer intermediates.
Nitric Acid Market Vendor Landscape
Capacity expansion dominates the current landscape as agricultural economies build domestic manufacturing infrastructure. The vendor base stratifies between integrated chemical majors with captive ammonia supply and merchant acid specialists serving regional fertilizer blenders. Two strategic archetypes prevail: scale-driven integrated producers leveraging natural gas feedstock positions, and specialty-grade specialists certifying electronic and pharmaceutical purity tiers. Geographic expansion into high-growth agricultural markets and technology licensing for process efficiency gains represent the dominant competitive moves.
Within the integrated producer tier, CF Industries Holdings, Inc. exemplifies North American natural gas cost leverage, while Yara anchors European production networks through ammonia-nitrate complex integration. BASF SE occupies a position spanning commodity and specialty-grade acid streams. These three entities represent the scale-certificate spectrum: CF Industries Holdings, Inc. exemplifies feedstock-driven merchant supply, Yara represents regional network density, and BASF SE illustrates dual-track positioning across fertilizer and electronic chemical segments.
| Leading Market Players |
|---|
| CF Industries Holdings, Inc. |
| Yara |
| BASF SE |
| Nutrien Ltd. |
| LSB Industries |
| EuroChem Group |
| Sasol Limited |
| OCI Global |
| Omnia Holdings Limited |
| Others |
Supply Flow & Price Mechanics
Semiconductor foundry consolidation to three qualified suppliers per purity tier is forcing merchant acid producers to absorb qualification cost compression or cede volume to integrated chemical majors with captive electronic materials divisions. This procurement concentration is reshaping supply allocation toward integrated producers with established certification infrastructure and away from spot-market suppliers.
Pricing Analysis
Volume-mass dilute grades for ammonium nitrate fertilizer production trade at commodity economics with thin margins, while electronic-grade and red fuming specialty tiers capture substantial premiums through certification barriers and handling complexity. Three-tier pricing structure across electronic, industrial, and fertilizer grades separates margin capture by purity threshold and documentation burden. Pricing pressure stems from natural gas feedstock volatility exposing merchant suppliers without long-term ammonia contracts to margin compression. Fertilizer blenders exhibit highest price sensitivity through bulk tender processes, whereas semiconductor foundries prioritize supply security over unit cost.
Supply Chain Analysis
Platinum-rhodium catalyst supply rests on South African and Russian mining concentration, creating single-source vulnerability for Ostwald process operators dependent on gauze replacement cycles. Ammonia feedstock draws from natural gas-reforming economics concentrated in the United States, Qatar, and Trinidad and Tobago. Distribution runs through bulk tanker and railcar networks for liquid acid, with membrane absorption technology reducing energy intensity in integrated complexes. Tariff exposure on platinum group metals and catalyst recovery services amplifies cost volatility for non-integrated producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race where captive ammonia supply and electronic-grade certification capabilities determine competitive survival. Players are pursuing backward integration into hydrogen feedstock production to secure cost positions under carbon border adjustment mechanisms.
For Market Incumbents: Deepen captive ammonia supply positions through long-term natural gas contracts or renewable hydrogen offtake agreements to defend against feedstock volatility. Secure platinum catalyst recycling partnerships to reduce gauze replacement cost exposure. Invest in selective catalytic reduction retrofit completion ahead of EPA enforcement acceleration to avoid extended shutdown windows. For New Entrants and Emerging Players: Begin with electronic-grade acid specialization targeting semiconductor foundries in Taiwan and South Korea where qualification cycles have compressed to nine months. The Indian PLI scheme for domestic fertilizer manufacturing offers the most penetrable geography for greenfield dilute acid capacity. A technical service bundling approach unseats volume-contract incumbents by separating procurement from qualification support. For Investors and Strategic Acquirers: The window for entry favors integrated chemical majors with existing ammonia-nitrate complexes and electronic materials divisions capable of dual-track certification. Mid-cap merchant acid suppliers without feedstock integration or specialty-grade positioning face structural margin compression. Watch hydrogen feedstock cost curves and EU carbon border adjustment implementation as inflection indicators for site competitiveness reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Production | Captive natural gas or green hydrogen supply locks in feedstock cost position against merchant volatility. |
| Electronic-Grade Certification Investment | FDA and EMA validation protocols create supplier stickiness in pharmaceutical nitration applications. |
| Selective Catalytic Reduction Retrofit | EPA Clean Air Act compliance ahead of enforcement timelines preserves operating continuity. |
| Platinum Catalyst Recovery Partnership | Specialized metallurgical processing capabilities concentrate among limited suppliers, creating sourcing risk. |
| Long-Term Supply Agreement with Fertilizer Blenders | Contract structures insulate merchant acid producers from Henry Hub price swings. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at integrated ammonia-nitrate complexes, procurement leads at fertilizer blenders, technical R&D directors in electronic chemicals, and distribution channel partners in bulk acid logistics. SEC 10-K disclosures, EPA enforcement databases, ECHA REACH registration dossiers, and Cefic production statistics provided cross-validation. Bottom-up capacity modeling and top-down demand aggregation triangulated volume estimates.
Data-stream reconciliation across production capacity surveys, import-export trade flows, and end-use consumption patterns shaped the analytical framework across the analysis window. Segmentation modeling incorporated grade tier, end-use industry, regional production hub, and certification status dimensions. CAGRs derived from trend extrapolation of capacity deployment schedules and demand elasticity by application. Hydrogen feedstock cost curves and carbon border adjustment mechanism timelines served as scenario variables.
Underlying measurement precision varies by segment; electronic-grade and pharmaceutical-tier volumes carry tighter precision than commodity fertilizer channels due to concentrated supplier panels and documented qualification cycles. Forecasts reflect documented assumptions on capacity utilization rates, feedstock cost trajectories, and regulatory enforcement intensity. A small set of triggers—platinum group metal supply disruptions, EPA NOx mandate acceleration, and EU carbon border adjustment implementation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Sulfide Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market