
 Europe Mastic Remover Market | 2026-2036
Europe Mastic Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mastic Remover Market Insights
Skilled restoration labor availability is bifurcating the Europe mastic remover landscape into premium contractor-grade and accessible DIY formulations. Aramsco leverages broad distribution across continental Europe to sustain contractor channel dominance. Franmar differentiates through soy-derived chemistry that aligns with tightening environmental standards. ArmorPoxy occupies the industrial flooring segment where high-build epoxy removal demands specialized gel formulations.
Mastic removers are formulated chemical agents designed to soften, dissolve, or emulsify adhesive residues from substrates including concrete, wood, and tile, typically containing active solvents such as d-limonene, N-methyl-2-pyrrolidone, or glycol ether blends that penetrate polymer matrices within fifteen to forty-five minutes. Water-based formulations lead volume due to workplace safety mandates, while solvent-based gels command margin pools in heavy industrial stripping where substrate temperature and adhesive age demand aggressive penetration. The construction end-user segment anchors demand as commercial renovation cycles accelerate across Western Europe, with spray can packaging gaining share in maintenance and spot-repair applications.
REACH registration requirements and the EU F-Gas Regulation constrain volatile organic compound thresholds, compelling reformulation investments from manufacturers seeking CE-marked product access. ECHA substance evaluation protocols directly shape ingredient substitution timelines, particularly for NMP and methylene chloride chemistries. Stakeholders must monitor regulatory substance restriction proposals and preemptively validate alternative active ingredients before candidate list inclusions disrupt supply continuity.
Market Dynamics
REACH substance evaluation protocols are systematically eliminating legacy solvents from European mastic remover formulations, forcing manufacturers to rebuild active ingredient portfolios around bio-based alternatives before candidate list inclusions disrupt supply continuity.
Growth Catalysts
- Commercial renovation cycles:Aging public infrastructure and private commercial real estate across Germany, France, and the United Kingdom require systematic adhesive remediation, expanding demand for professional-grade removal agents.
- EU Green Deal procurement mandates:Public sector tenders increasingly specify low-VOC and bio-based solvent alternatives, redirecting institutional purchasing toward compliant formulations.
- Water-based formulation advances:Workplace safety mandates under the Chemical Agents Directive are accelerating adoption of reduced-hazard stripping chemistries in maintenance and spot-repair applications.
Market Restraints
- Raw material substitution costs:Transitioning from N-methyl-2-pyrrolidone and methylene chloride to d-limonene and soy-derived alternatives elevates input costs and compresses margin pools for mid-tier producers.
- Supply concentration in specialty esters:Bio-based active ingredient supply chains concentrate among limited European chemical processors, creating vulnerability to capacity constraints.
- Performance gaps in heavy industrial stripping:Water-based and bio-based formulations exhibit slower penetration rates on aged high-build epoxy systems compared to legacy solvent gels.
Strategic Opportunities
- Eastern European underpenetration:Poland, Romania, and Czech Republic commercial building stocks remain underserved by professional-grade removal agents, presenting first-mover expansion potential.
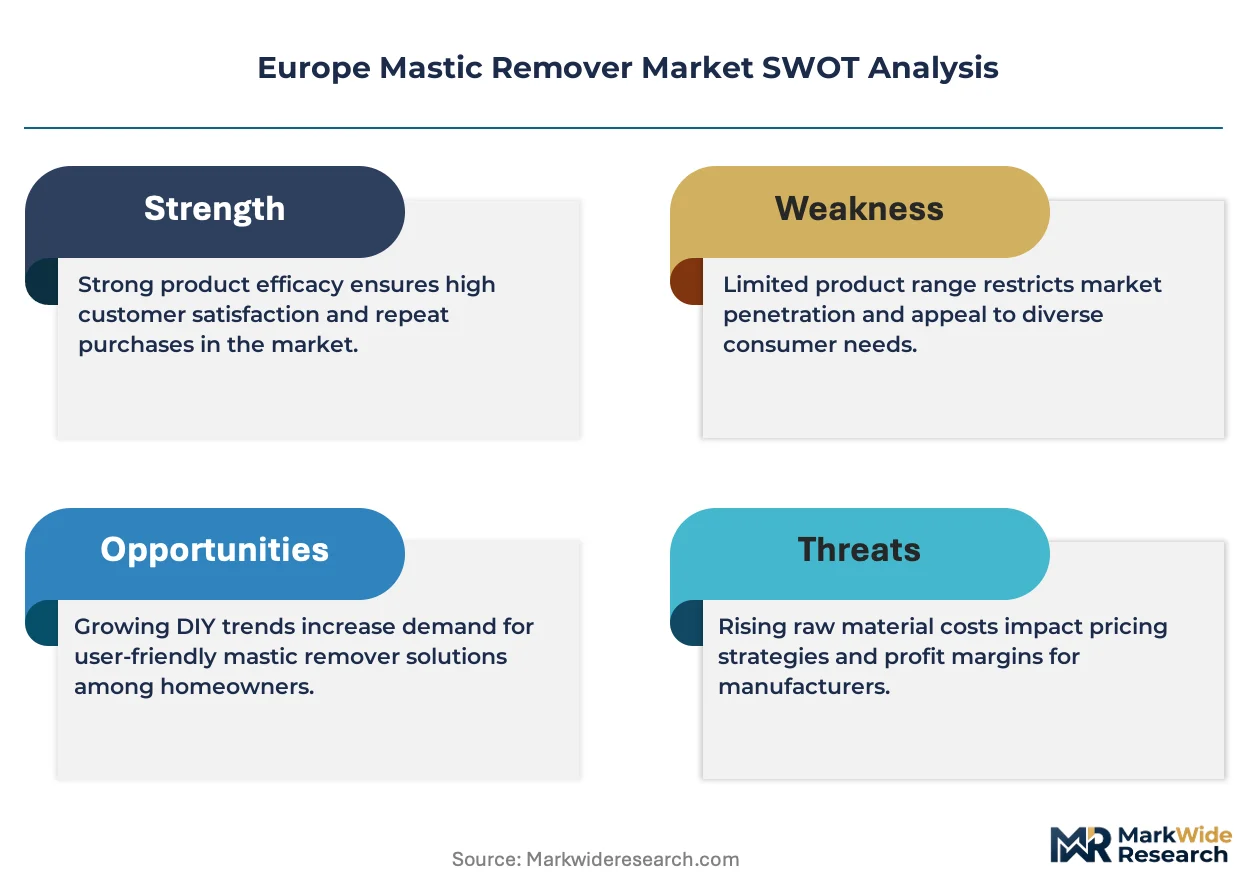
- Spray can packaging innovation:Maintenance and spot-repair applications favor portable delivery formats, creating channel differentiation opportunities against bulk contractor supply.
- CSRD-aligned sustainability reporting:Large corporate renovation contractors face Scope 3 emissions disclosure requirements, elevating preference for suppliers with verified bio-based content and lifecycle documentation.
Industry Challenges
- Skilled restoration labor scarcity:Certified applicators capable of substrate-safe adhesive removal are concentrating in Western European metropolitan clusters, limiting service expansion.
- ECHA compliance timeline compression:Substance restriction proposals advance faster than alternative validation cycles, forcing manufacturers to maintain parallel formulation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mastic Remover Market |
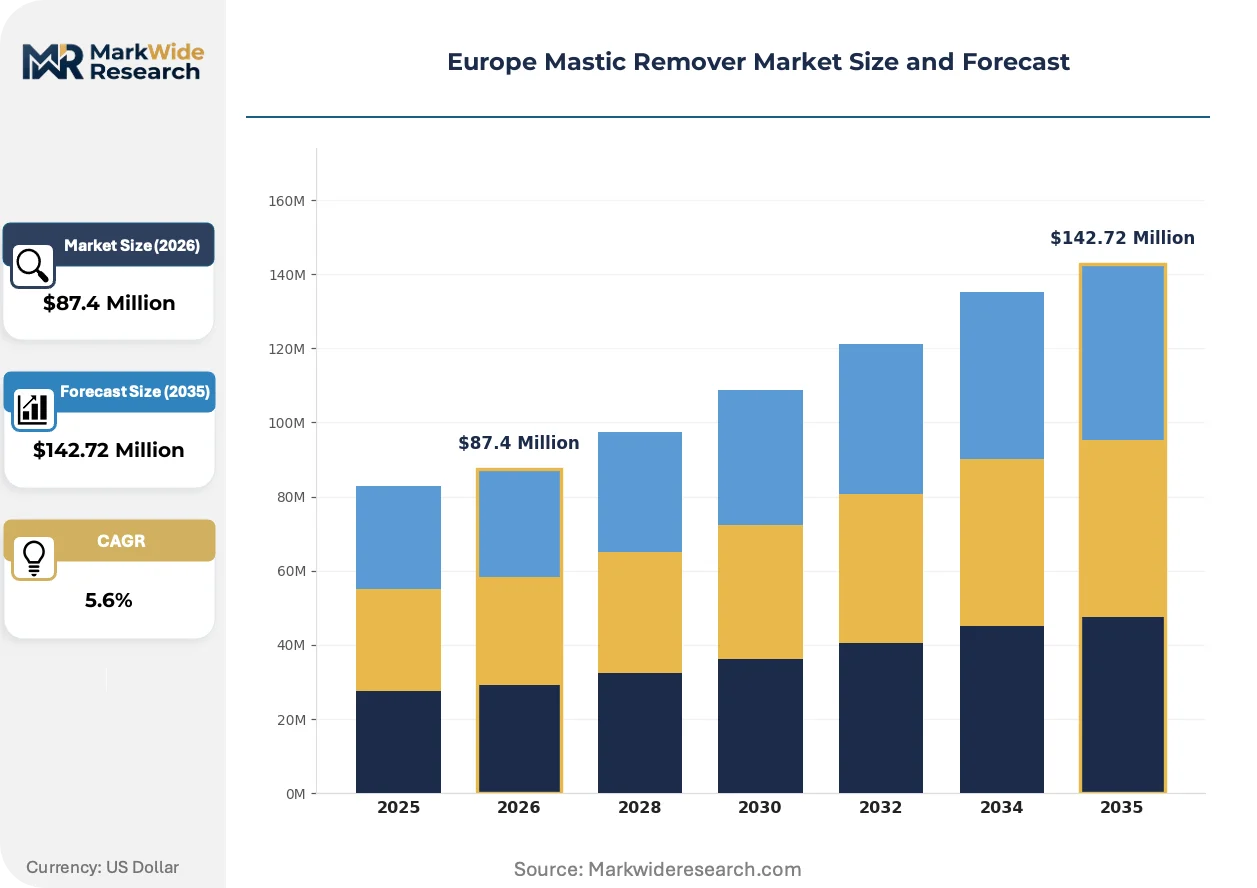
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $142.72 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Foam, Gel Application: Flooring, Wall, Ceiling, Industrial End User: Construction, DIY, Government, Commercial Packaging Type: Spray Can, Bucket, Tube, Cartridge |
| Companies Covered | Abatement Technologies, Abatix Corp, American Building Restoration Products Inc., Aramsco, ArmorPoxy, Citrus Depot, Franmar, ILC Dover LP, Soy Technologies LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mastic Remover Market Trends and Innovations
Formulation chemistry is pivoting toward enzymatic and bio-solvent platforms that penetrate polymer matrices without the respiratory hazards of chlorinated solvents. This shift is compressing product development cycles and reconfiguring raw material procurement networks across the value chain.
Enzymatic mastic removal systems deploy targeted protease and esterase blends to break down adhesive polymer chains at ambient temperatures. Flooring contractors in Germany and the Netherlands are piloting these systems for asbestos-containing tile remediation where heat-activated stripping is prohibited. The technology is decomposing the historical trade-off between stripping speed and workplace safety, enabling single-shift completion of jobs previously requiring extended ventilation protocols.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone are tightening occupational exposure limits and compelling downstream user sectors to validate substitute chemistries. Industrial flooring applicators face the most acute compliance pressure, as NMP-based gel formulations have dominated high-build epoxy removal. Manufacturers are responding with accelerated d-limonene and dibasic ester validation programs to maintain CE-marked product access.
Large commercial renovation contractors are consolidating supplier relationships around full-service chemical management programs that bundle product supply with waste handling and compliance documentation. This behavior shift is squeezing independent distributors and favoring integrated providers capable of cradle-to-grave service packaging. The United Kingdom and France exhibit the most pronounced concentration, where facility management outsourcing has compressed the contractor base into fewer, larger procurement entities.
Europe Mastic Remover Market Segmentation
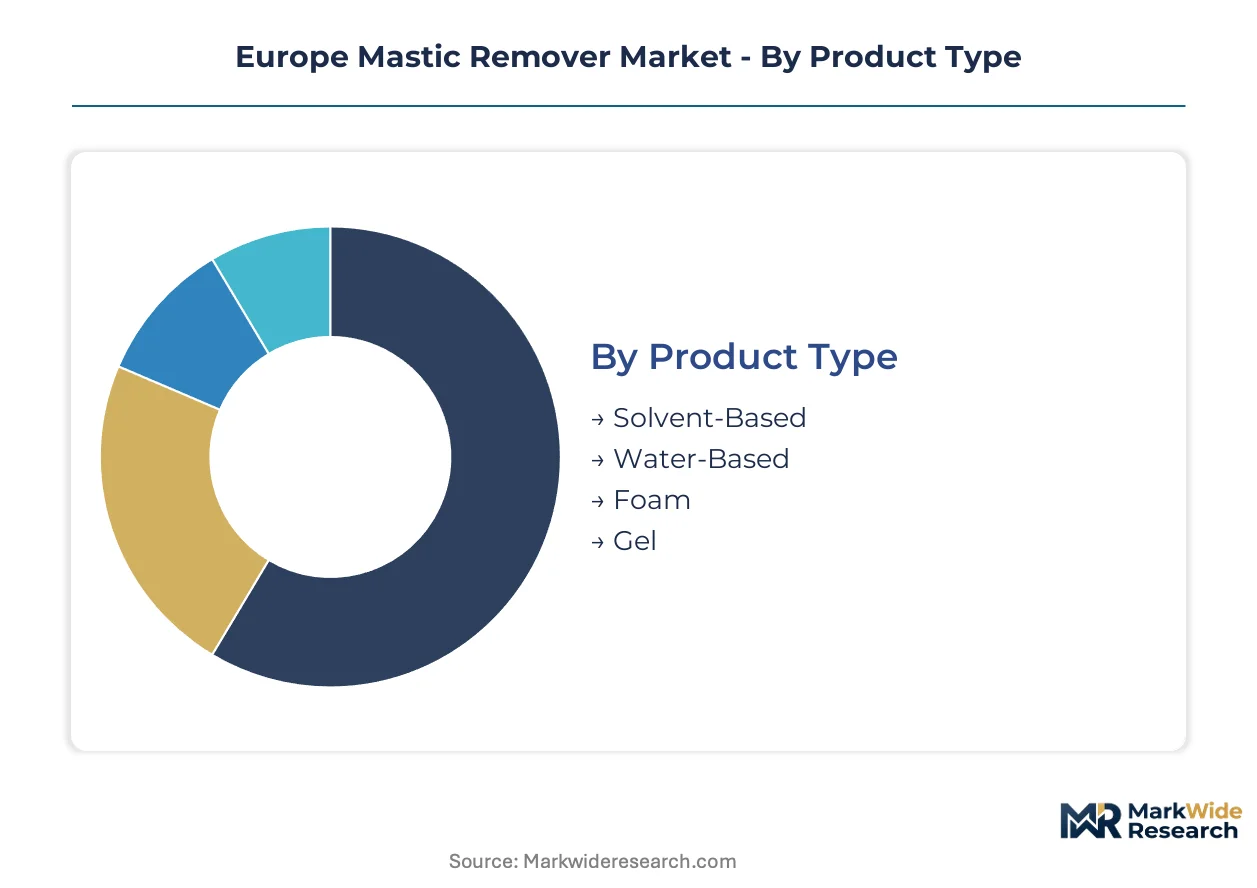
Segmentation in the Europe mastic remover market reveals how regulatory pressure and end-use specialization fragment demand across incompatible technical specifications. Each dimension exposes distinct vulnerability profiles to REACH-driven reformulation costs and bio-based substitution timelines.
Product Type:
Solvent-based formulations face the most acute substitution threat from REACH Annex XVII restrictions on chlorinated solvents and N-methyl-2-pyrrolidone, forcing manufacturers to accelerate validation of bio-derived alternatives.
- Water-Based:Emulsion systems using surfactant-detergent chemistry dominate commercial maintenance contracts across Germany and France. Workplace safety mandates under the Chemical Agents Directive accelerate procurement of reduced-hazard stripping chemistries in healthcare and education facilities.
- Solvent-Based:Aggressive penetration agents containing d-limonene or dibasic esters retain dominance in heavy industrial epoxy removal where substrate temperature and adhesive age demand rapid matrix dissolution. United Kingdom flooring contractors specify these for aged high-build systems where water-based alternatives require extended dwell times.
- Foam:Low-density aerosolized delivery systems cling to vertical surfaces during wall tile remediation, finding adoption in Dutch and Belgian renovation markets where asbestos-containing substrate removal demands controlled application.
- Gel:Thixotropic formulations prevent runoff on overhead ceiling applications, concentrating demand in French commercial fit-out sectors where substrate-safe removal preserves structural integrity.
Water-based formulations retain volume leadership; gel products hold the steepest expansion curve as vertical and overhead application safety requirements tighten.
Application:
Cost tier differentiation separates premium contractor-grade systems from accessible maintenance formulations across surface-specific performance requirements.
- Flooring:The largest addressable segment spanning vinyl, carpet, and epoxy substrate removal. German industrial flooring applicators drive specification of high-penetration gel systems for aged adhesive matrices in manufacturing facility renovation cycles.
- Industrial:Heavy-duty chemical plants and logistics facilities demand specialized formulations for chemically resistant epoxy and polyurethane removal. Polish and Czech Republic commercial building stocks increasingly require professional-grade agents as Western European contractor networks extend eastward.
- Wall:Vertical surface applications favor foam and gel viscosities that resist sagging during dwell periods, concentrating in French and Italian heritage building restoration where substrate preservation outweighs speed priorities.
- Ceiling:Overhead work mandates low-drip formulations with extended cling properties, finding specification in United Kingdom commercial office refurbishment where tenant-occupied stripping requires containment protocols.
Flooring anchors absolute demand volume; industrial applications are climbing the fastest as Eastern European commercial stock ages into systematic remediation cycles.
End User:
Customer type fragmentation reflects divergent procurement sophistication, from institutional tender compliance to price-sensitive spot purchasing.
- Construction:Professional contractors bundle mastic removal within full-service renovation contracts, consolidating supplier relationships around integrated chemical management programs in France and the United Kingdom.
- Commercial:Facility management outsourcing entities specify low-VOC and bio-based alternatives to satisfy CSRD-aligned Scope 3 emissions disclosure requirements, elevating preference for suppliers with verified lifecycle documentation.
- Government:Public sector tenders under EU Green Deal procurement mandates increasingly specify environmental performance criteria, redirecting institutional purchasing toward REACH-compliant formulations in Germany and the Netherlands.
- DIY:Consumer accessible formats concentrate in retail channels for residential renovation, though skilled restoration labor scarcity limits segment expansion beyond metropolitan clusters.
Construction commands the deepest procurement relationships; commercial end users are gaining share fastest as facility management consolidation accelerates.
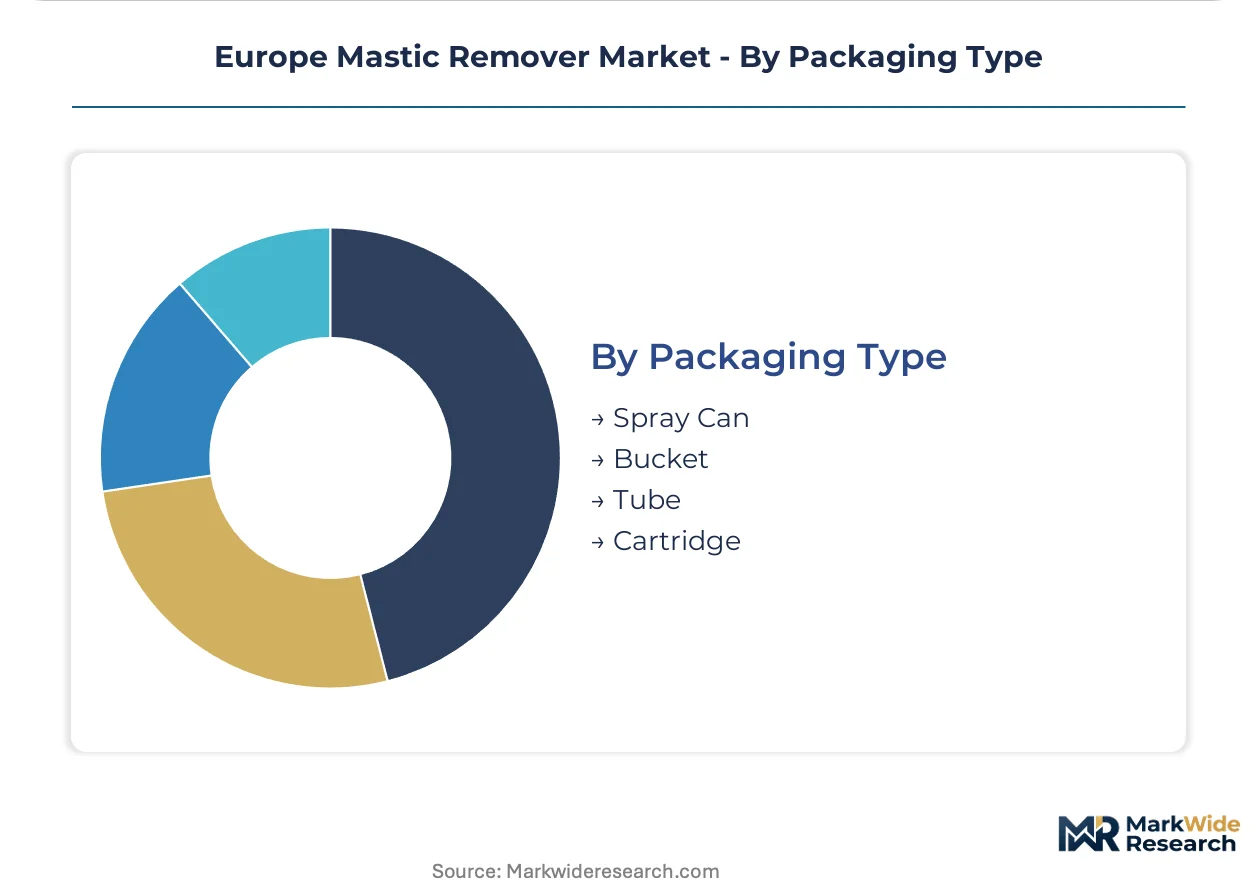
Packaging Type:
Volume scale and application mobility determine format selection, from bulk contractor supply to portable maintenance solutions.
- Bucket:Bulk containers dominate professional contractor supply for large-scale flooring removal projects across German and French commercial renovation markets.
- Spray Can:Portable aerosol delivery gains share in maintenance and spot-repair applications where mobility outweighs unit economics, creating channel differentiation opportunities in United Kingdom facilities management.
- Tube:Squeeze formats target precision application in detail work and edge remediation, finding niche adoption in restoration contracting.
- Cartridge:Caulk-gun compatible systems enable controlled dispensing for linear joint and perimeter removal tasks in specialized flooring applications.
Bucket packaging retains contractor channel dominance; spray can formats are expanding most quickly as maintenance application mobility requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, France, and the United Kingdom exhibit divergent consumption patterns for mastic removers, with German contractors favoring bulk water-based formulations for healthcare facility renovation while UK flooring specialists specify aggressive solvent gels for aged industrial epoxy systems.
Germany
Industrial flooring renovation in manufacturing heartlands and public hospital modernization drive specification of low-VOC emulsion systems. The Chemical Agents Directive enforces strict workplace exposure thresholds, compelling procurement of reduced-hazard chemistries. Bavarian and North Rhine-Westphalian contractor clusters concentrate demand for REACH-compliant bucket formulations in automotive plant refurbishment cycles.
United Kingdom
Tenant-occupied commercial office refurbishment and heritage building restoration create parallel demand streams for containment-compatible gel systems. The Health and Safety Executive enforces asbestos handling protocols that restrict heat-activated stripping methods. London and Southeast England flooring contractors specify extended-cling formulations for overhead ceiling applications in live building environments.
France
Facility management outsourcing consolidation redirects institutional purchasing toward integrated chemical management programs with full lifecycle documentation. EU Green Deal procurement mandates increasingly specify bio-based content verification in public sector tenders. Île-de-France commercial fit-out sectors concentrate demand for thixotropic gel formulations that preserve substrate integrity during wall tile remediation.
Netherlands
Asbestos-containing tile remediation in aging commercial stock pilots enzymatic removal systems where ventilation constraints prohibit traditional solvent use. The National Institute for Public Health and the Environment monitors occupational chemical exposure in restoration contracting. Dutch renovation markets concentrate demand for foam-based aerosol delivery systems that cling to vertical surfaces during controlled abatement procedures.
Poland
Commercial building stock aging into systematic remediation cycles expands demand for professional-grade removal agents as Western European contractor networks extend eastward. EU cohesion fund infrastructure investments accelerate public facility modernization timelines. Warsaw and Kraków metropolitan clusters concentrate emerging specification activity for high-penetration solvent formulations in logistics facility renovation.
Europe Mastic Remover Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding consolidated procurement relationships through cradle-to-grave service packaging while the latter compete on formulation chemistry differentiation. Market structure reflects bifurcation between premium contractor-grade systems and accessible maintenance formats. Three archetypes dominate: integrated chemical management providers, bio-based formulation specialists, and industrial flooring application experts. Competitive dynamics center on REACH compliance acceleration and spray can packaging innovation for maintenance mobility.
Within the bio-based formulation tier, Franmar and Soy Technologies LLC exemplify chemistry differentiation around soy-derived active ingredients, occupying positions aligned with tightening EU environmental standards. Aramsco anchors the integrated distribution archetype, representing channel dominance through broad continental European contractor network coverage. ArmorPoxy sits within the industrial flooring specialization vector, exemplifying high-build epoxy removal expertise through gel formulation development.
| Leading Market Players |
|---|
| Abatement Technologies |
| Abatix Corp |
| American Building Restoration Products Inc. |
| Aramsco |
| ArmorPoxy |
| Citrus Depot |
| Franmar |
| ILC Dover LP |
| Soy Technologies LLC |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for d-limonene and dibasic ester feedstocks concentrate pricing power among German and Dutch chemical processors, compressing margin pools for mid-tier formulators lacking long-term supply contracts or captive bio-refinery capacity.
Pricing Analysis
Long-term offtake agreements dominate procurement between large commercial renovation contractors and integrated chemical management providers, while spot purchasing persists in DIY retail channels and small restoration shops. Three-tier pricing structure across premium contractor-grade, standard professional, and economy maintenance levels differentiates by certification grade and bundled waste-handling services. Cost compression in mid-tier solvent-based gels is intensifying because REACH-driven reformulation elevates soy-derived and enzymatic input costs. DIY consumers exhibit highest price sensitivity; facility management outsourcing entities prioritize lifecycle documentation and CSRD compliance over unit economics.
Supply Chain Analysis
Port congestion at Rotterdam and Antwerp elevates inbound logistics costs for citrus-derived terpenes arriving from Brazilian and Spanish processing centers, forcing manufacturers to maintain higher safety stocks of bio-based active ingredients. Formulation chemistry draws from concentrated supply bases in Germany, the Netherlands, and Belgium, with specialty ester production anchoring in North Rhine-Westphalian chemical parks. Single-source vulnerability pervades enzymatic catalyst supply, where Danish and Dutch biotechnology firms control protease blend manufacturing. Distribution runs through Aramsco's continental European contractor network and specialized industrial flooring distributors serving United Kingdom and French markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic removal systems are disrupting legacy solvent chemistry, with REACH Annex XVII acceleration compressing substitution timelines faster than incumbent reformulation cycles can validate alternatives.
For Market Incumbents: Shield market position by accelerating backward integration into captive bio-refinery capacity for d-limonene and soy-derived feedstocks, insulating margin pools from specialty ester supply concentration. Secure ECHA pre-registration for alternative active ingredients before candidate list inclusions disrupt formulation continuity, prioritizing dibasic ester and enzymatic validation programs.
For New Entrants and Emerging Players: Lead with spray can packaging innovation targeting United Kingdom facilities management maintenance contracts, where mobility requirements outstrip incumbent bulk-format dominance. Eastern European contractor networks in Poland and Czech Republic present white-space expansion opportunity, as Western European flooring specialists extend service coverage into aging commercial stock remediation.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance arbitrage play because REACH-driven ingredient substitution creates durable demand for validated bio-based formulation platforms. Acquisition targets should display integrated chemical management capabilities with cradle-to-grave service packaging and verified lifecycle documentation. Monitor ECHA substance restriction proposal advancement rates as inflection signal for reformulation investment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Refinery Capacity | Captive supply of d-limonene and soy-derived feedstocks insulates margin pools from Dutch and German processor concentration. |
| Enzymatic Formulation Validation Program | Protease and esterase blend registration with ECHA secures CE-marked product access before NMP restrictions tighten. |
| Spray Can Packaging Line Expansion | Portable aerosol delivery captures United Kingdom facilities management maintenance contracts from bulk-dependent incumbents. |
| Eastern European Distribution Partnership | Polish and Czech Republic contractor network access leverages EU cohesion fund infrastructure investment acceleration. |
| CSRD-Aligned Lifecycle Documentation Platform | Verified bio-based content reporting satisfies French and German commercial end-user Scope 3 emissions disclosure requirements. |
Research Methodology
Desk research of ECHA substance evaluation protocols, EU customs trade data, and SEC filings from listed chemical distributors preceded structured interviews with industrial flooring contractors, facility management procurement leads, formulation R&D directors, and specialty chemical distribution channel partners. Primary fieldwork across Germany, France, and the United Kingdom validated secondary estimates of renovation cycle intensity and contractor-grade product specification patterns. Bottom-up triangulation of end-user demand segments with top-down macroeconomic indicators anchored volume and value estimates.
Variance decomposition across product type, application surface, end-user sophistication, and packaging format dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Industry-specific forecast inputs included REACH compliance timeline assumptions, commercial building stock age distributions, and enzymatic technology adoption curves in Dutch asbestos remediation pilot programs.
Forecasts assume regulatory continuity in REACH and EU Green Deal procurement regimes; material policy shifts would require re-modeling. Specific risk factors encompass ECHA acceleration of N-methyl-2-pyrrolidone restrictions, bio-based feedstock supply disruptions from climate-impacted citrus harvests, and skilled restoration labor scarcity constraining service expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Limestone Cleaner Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Liquid Detergent Market