
 Methanesulfonic Acid Market | 2026-2036
Methanesulfonic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Methanesulfonic Acid Market Intelligence
Perfluorooctanesulfonic acid is expanding its displacement by methanesulfonic acid across metal plating and surface treatment applications due to superior biodegradability and lower aquatic toxicity. Solvay S.A. leverages its integrated sulfonic acid chemistry platform to dominate European supply chains for pharmaceutical and electronic grades. Arkema S.A. sustains competitive positioning through specialized polymer-grade formulations, while BASF SE anchors industrial volume with broad channel control across German and Asia-Pacific chemical manufacturers.
Methanesulfonic acid is a strong organic acid with the formula CH3SO3H, featuring a pKa near -1.9 and complete water solubility, manufactured industrially via oxidation of dimethyl disulfide or methanethiol with nitrogen dioxide. It serves primarily as a biodegradable acid catalyst, electrolyte, and cleaning agent where mineral acid residues pose corrosion or environmental liabilities. Pharmaceutical grade commands premium positioning due to stringent impurity thresholds for active pharmaceutical ingredient synthesis, while electronic grade is capturing the fastest expansion as semiconductor fabs in Taiwan and South Korea adopt it for wafer etching and copper plating baths. Industrial grade remains the mature volume anchor, serving agrochemical and dye intermediates with thinner margins but steadier offtake.
REACH registration requirements in Europe and China's MEE wastewater discharge standards are tightening permissible limits on persistent acid catalysts, directly elevating methanesulfonic acid's substitution appeal across regulated processes. FDA scrutiny of residual solvents in drug manufacturing and EPA frameworks for safer chemical design reinforce demand for pharmaceutical-grade material in North American supply chains. Stakeholders must monitor evolving semiconductor material qualification timelines and regional green chemistry procurement mandates to anticipate grade-mix shifts and capacity allocation decisions.
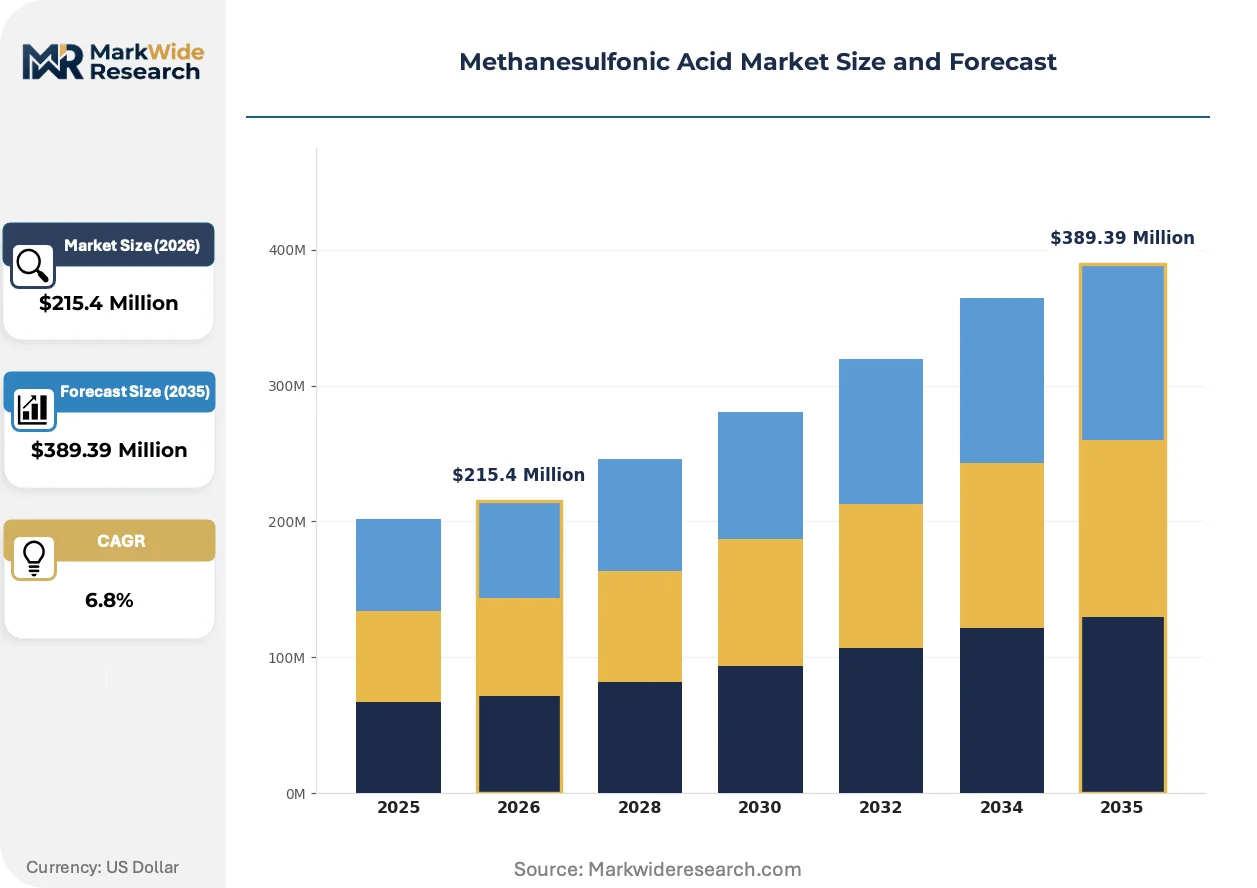
Market Dynamics
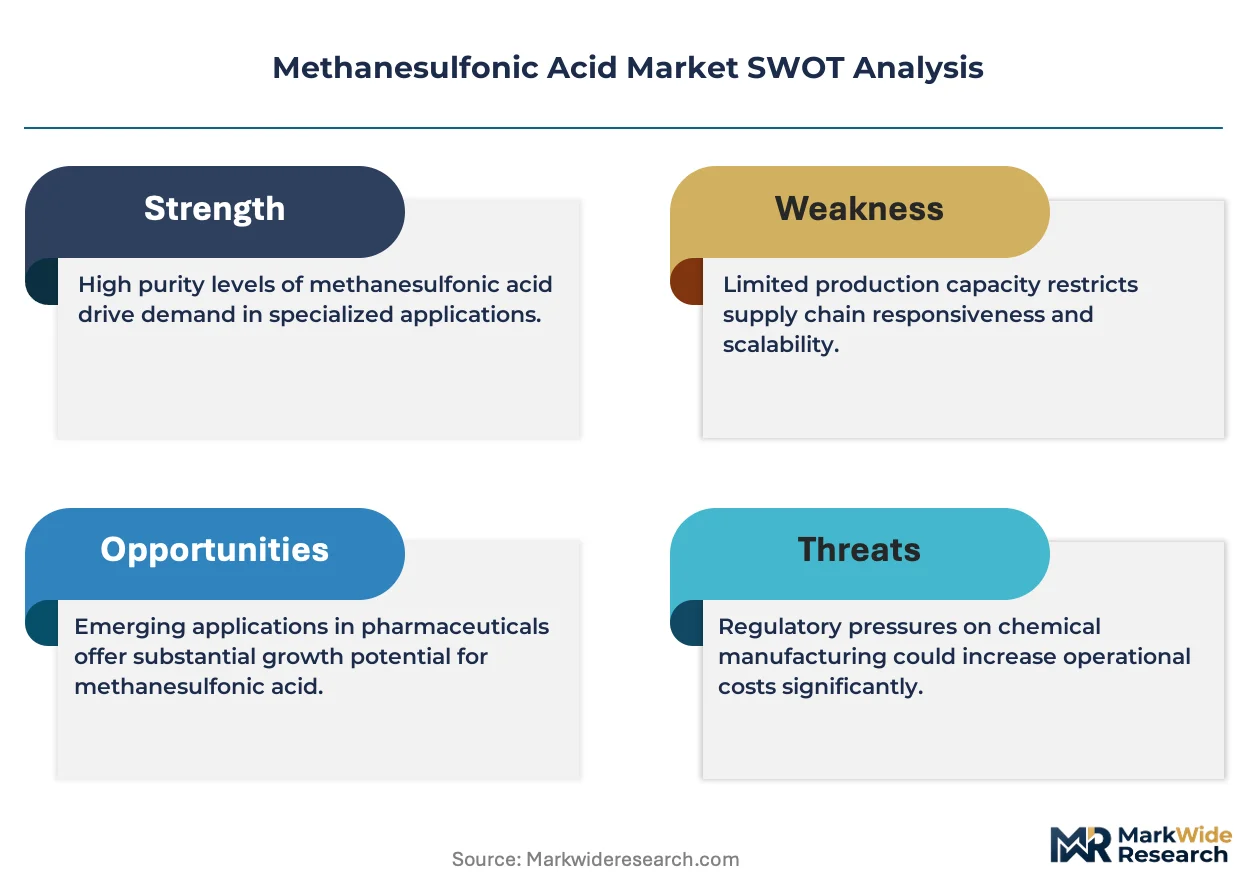
REACH registration timelines and China's MEE wastewater standards are forcing chemical processors to retire persistent acid catalysts, accelerating methanesulfonic acid's displacement of mineral acids across European and East Asian manufacturing clusters.
Growth Catalysts
- Electronic-grade qualification:Semiconductor fabs in Taiwan and South Korea are qualifying methanesulfonic acid for copper plating baths, replacing perfluorinated alternatives with biodegradable electrolytes.
- REACH substitution mandates:ECHA's restrictions on persistent organic pollutants are compelling German and French surface treatment facilities to convert plating lines to sulfonic acid chemistry.
- Agrochemical formulator demand:Chinese and Indian pesticide manufacturers are scaling industrial-grade purchases as a biodegradable catalyst for sulfonamide intermediate synthesis.
Market Restraints
- Dimethyl disulfide feedstock volatility:Methanesulfonic acid production costs track sulfur chemical pricing, exposing margins to petrochemical refinery output fluctuations.
- Specialized logistics requirements:Electronic-grade material demands temperature-controlled transport and stainless-steel containment, limiting viable carrier networks.
- Peracetic acid substitution in cleaning:Food processing and dairy equipment sanitization segments in North America are piloting peracetic acid blends as alternative biodegradable cleaners.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO's tightened residual solvent guidelines are opening qualification pathways for pharmaceutical-grade methanesulfonic acid in API synthesis.
- EU Green Deal procurement incentives:Public chemical tenders in Germany and the Netherlands now weight biodegradability scores, favoring sulfonic acid catalysts in contract awards.
- Semiconductor material convergence:Taiwan's wafer etching chemical suppliers are integrating methanesulfonic acid into mixed-acid formulations for advanced node processing.
Industry Challenges
- Electronic-grade certification timelines:Semiconductor material qualification cycles extend 18-24 months, delaying revenue recognition for new production capacity.
- Specialized sulfonation expertise scarcity:Process engineers with dimethyl disulfide oxidation experience are concentrated at legacy European and Japanese producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methanesulfonic Acid Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Electronic Grade, Reagent Grade Application: Pharmaceuticals, Agrochemicals, Electronics, Dyes End User: Chemical Manufacturers, Research Laboratories, Electronics Firms, Agricultural Companies Packaging Type: Drums, Bags, IBC Containers, Tankers |
| Companies Covered | Varsal, Solvay S.A., Arkema S.A., Zhongke Fine Chemical Co. Ltd., Shinya Chem, BASF SE, Oxon Italia S.p.A., Hebei Yanuo Bioscience Co. Ltd., SIPCAM OXON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methanesulfonic Acid Market Strategic Shifts & Innovations
Process intensification and green chemistry procurement mandates are compressing qualification timelines while elevating purity requirements across pharmaceutical and electronic applications.
Continuous-flow sulfonation reactor technology is converging with automated pH control systems to enable real-time grade switching between industrial and electronic specifications. German specialty chemical producers are piloting these integrated platforms to reduce batch-to-batch variation. The technology is converging with semiconductor fab just-in-time chemical delivery requirements, compressing regional supply lead times.
China's GB standards for wastewater discharge are tightening permissible limits on total acid content and biological oxygen demand. Chemical processors in Jiangsu and Zhejiang provinces face facility upgrade deadlines. Electronic-grade methanesulfonic acid is capturing preference in these clusters due to complete biodegradability and lower aquatic toxicity versus mineral acid alternatives.
Consolidated procurement by multinational agrochemical formulators is displacing spot-market purchasing for industrial-grade material. Bayer Crop Science and Syngenta are negotiating multi-year offtake agreements with sulfonic acid producers. This pattern is most visible in China and India, where integrated formulators are securing captive catalyst supply for herbicide and fungicide intermediate production.
Methanesulfonic Acid Market Segmentation
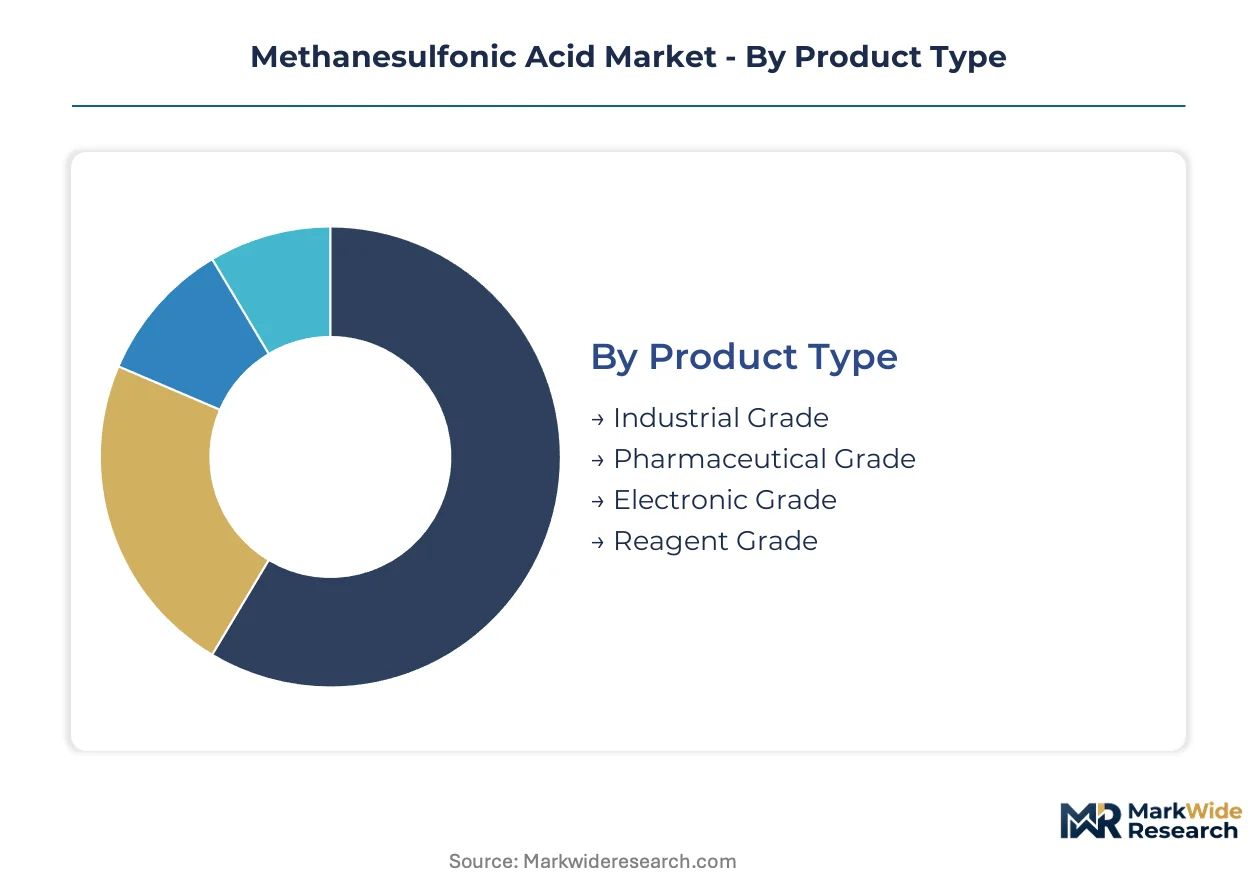
Grade purity thresholds and packaging integrity requirements drive fundamentally different procurement patterns across methanesulfonic acid applications. Semiconductor fabs, pharmaceutical API synthesizers, and agrochemical formulators each impose distinct specification boundaries that fragment supply chains into non-interchangeable tiers.
Product Type:
Purchasing decisions pivot on contamination tolerance thresholds and regulatory documentation burden rather than unit price alone.
- Electronic Grade:Specifications demand sub-ppb metal ion content and particle counts below SEMI Grade 3 thresholds for copper plating bath stability. Taiwan Semiconductor Manufacturing and Samsung Foundry qualify suppliers through 18-24 month material validation cycles, creating captive supply relationships that resist spot-market arbitrage.
- Pharmaceutical Grade:Residual solvent profiles must satisfy ICH Q3C guidelines with complete batch traceability for API regulatory filings. CDSCO's tightened residual solvent guidelines in India and FDA scrutiny of genotoxic impurities are elevating documentation requirements for contract manufacturers.
- Industrial Grade:Serves agrochemical sulfonation and dye intermediate synthesis with standardized acidity specifications. Chinese pesticide manufacturers in Jiangsu province dominate volume offtake through multi-year catalyst supply agreements.
- Reagent Grade:Laboratory-scale quantities for analytical method development and academic research. Distribution concentrates through specialized chemical distributors rather than direct producer relationships.
Industrial grade leads on scale; electronic grade leads on momentum.
Application:
End-use chemistry determines acid concentration requirements, thermal stability needs, and waste treatment compliance intensity.
- Electronics:Wafer etching and copper electrodeposition in Taiwan and South Korean fabs. Biodegradability advantages over perfluorinated alternatives align with corporate sustainability commitments from TSMC and SK Hynix.
- Pharmaceuticals:Catalytic esterification and salt formation in active pharmaceutical ingredient synthesis. European contract manufacturers favor methanesulfonic acid for its complete biodegradability versus p-toluenesulfonic acid alternatives.
- Agrochemicals:Sulfonamide herbicide and fungicide intermediate production. Bayer Crop Science and Syngenta negotiate consolidated procurement contracts covering three-to-five year catalyst supply horizons.
- Dyes:Azo coupling reactions and pigment intermediate sulfonation. Indian dye manufacturers in Gujarat cluster represent mature demand with thinner margin structures.
Electronics expands most quickly; agrochemicals anchors volume stability.
End User:
Organizational scale and technical capability determine whether procurement flows through distributors or direct producer contracts.
- Chemical Manufacturers:Integrated sulfonation operations at agrochemical and specialty chemical producers. BASF and Solvay maintain backward integration into sulfonic acid chemistry for captive catalyst supply.
- Electronics Firms:Semiconductor fabs and printed circuit board manufacturers with just-in-time chemical delivery requirements. South Korean and Taiwanese facilities impose stringent logistics protocols including temperature-controlled transport.
- Research Laboratories:Academic and government research institutions with small-batch, high-frequency ordering patterns. Sigma-Aldrich and Thermo Fisher distribution networks dominate this channel.
- Agricultural Companies:Integrated formulators and contract manufacturers producing pesticide active ingredients. Chinese agricultural chemical conglomerates consolidate purchases through centralized procurement platforms.
Chemical manufacturers lead on procurement scale; electronics firms lead on specification intensity.
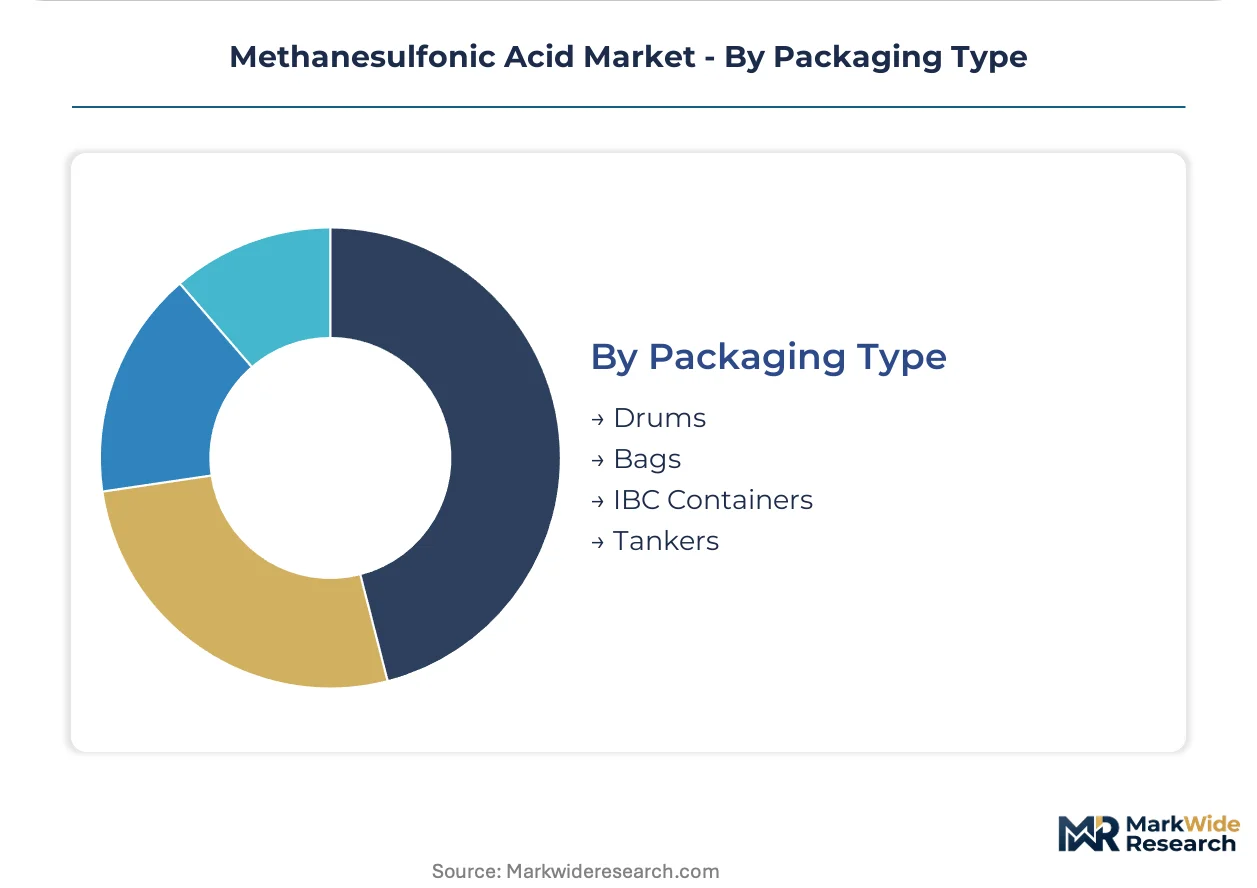
Packaging Type:
Volume per shipment and contamination risk tolerance dictate container selection across the value chain.
- IBC Containers:Intermediate bulk quantities for pharmaceutical and electronic-grade material where drum handling costs exceed container rental economics. Stainless-steel construction prevents iron contamination critical for semiconductor applications.
- Drums:Standard 200-liter polyethylene or fluoropolymer-lined steel containers for industrial-grade shipments. Agrochemical formulators in India and China favor drum packaging for flexibility across multi-product manufacturing campaigns.
- Tankers:Bulk liquid transport for large-volume industrial-grade contracts. Dedicated tanker fleets serve Bayer CropScience and Syngenta manufacturing complexes with direct pipeline connections.
- Bags:Solid methanesulfonic acid salt formulations for specific pharmaceutical salt synthesis applications. Limited adoption due to hygroscopicity challenges in standard polymer packaging.
Drums lead on shipment frequency; IBC containers lead on value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor manufacturing clusters command the highest specification requirements for electronic-grade material, while European chemical processors drive substitution mandates under REACH frameworks. Indian pharmaceutical contract manufacturers and Chinese agrochemical formulators anchor industrial-grade volume offtake.
China
Jiangsu and Zhejiang province chemical processors are converting sulfonation lines to methanesulfonic acid catalysts ahead of MEE wastewater discharge deadlines. GB standards tightening on total acid content and biological oxygen demand are forcing facility upgrades. Shanghai and Ningbo port clusters concentrate import logistics for electronic-grade material serving Yangtze River Delta semiconductor fabs.
South Korea
Samsung Foundry and SK Hynix qualification programs are driving copper plating bath adoption in Pyeongtaek and Yongin semiconductor complexes. The country's national environmental regulator enforces strict aquatic toxicity limits that favor biodegradable electrolyte alternatives. Gyeonggi-do province chemical suppliers are scaling dedicated production lines for sub-ppb purity specifications.
Germany
BASF and Solvay integrated sulfonic acid platforms supply captive catalyst for Ludwigshafen and Antwerp chemical manufacturing hubs. ECHA restrictions on persistent organic pollutants are compelling surface treatment facilities in North Rhine-Westphalia to convert plating lines. Bavarian specialty chemical producers pilot continuous-flow reactor technology for real-time grade switching.
United States
FDA scrutiny of residual solvents in API synthesis is elevating pharmaceutical-grade documentation requirements for New Jersey and Massachusetts contract manufacturers. EPA frameworks for safer chemical design reinforce demand across North American supply chains. Texas and Louisiana petrochemical corridors face feedstock volatility from dimethyl disulfide supply fluctuations.
India
CDSCO tightened residual solvent guidelines are opening qualification pathways for pharmaceutical-grade material in Hyderabad and Ahmedabad API synthesis clusters. Gujarat dye manufacturers represent mature industrial-grade demand with thinner margin structures. Maharashtra-based agrochemical formulators are negotiating multi-year catalyst supply agreements for sulfonamide intermediate production.
Methanesulfonic Acid Market Key Industry Players
Global majors compete with regional champions across integrated sulfonic acid chemistry platforms and specialized grade formulations. The vendor base stratifies into three tiers: multinational chemical conglomerates with backward integration into dimethyl disulfide oxidation, mid-scale regional producers serving pharmaceutical and electronic specifications, and spot-market industrial-grade suppliers concentrated in Chinese chemical parks. Dominant competitive moves include capacity expansion for electronic-grade qualification timelines and strategic partnerships with semiconductor material distributors.
Within the integrated chemistry tier, Solvay S.A. and BASF SE exemplify European-based conglomerates with captive sulfonic acid production. Arkema S.A. occupies a position among specialty chemical formulators with polymer-grade expertise. Chinese regional champions including Zhongke Fine Chemical Co. Ltd. and Hebei Yanuo Bioscience Co. Ltd. represent the mid-scale segment serving domestic agrochemical and dye intermediate demand.
| Leading Market Players |
|---|
| Varsal |
| Solvay S.A. |
| Arkema S.A. |
| Zhongke Fine Chemical Co. Ltd. |
| Shinya Chem |
| BASF SE |
| Oxon Italia S.p.A. |
| Hebei Yanuo Bioscience Co. Ltd. |
| SIPCAM OXON |
| Others |
Cost & Logistics Intelligence
Semiconductor fab qualification timelines stretching 18-24 months for electronic-grade material are compressing supplier pricing power while elevating premiums for certified producers with validated supply chains in Taiwan and South Korea. This procurement rigidity forces supply chain investments into temperature-controlled stainless-steel containment and dedicated logistics networks, embedding cost structures that resist spot-market arbitrage.
Pricing Analysis
Dimethyl disulfide feedstock volatility passes directly into production cost structures, exposing margins to sulfur chemical pricing swings from petrochemical refinery output fluctuations. Three-tier pricing structure across electronic, pharmaceutical, and industrial grade levels separates sub-ppb purity specifications from standard acidity thresholds. Cost compression in industrial-grade shipments is intensifying because Chinese agrochemical formulators are consolidating procurement through multi-year offtake negotiations. Agrochemical manufacturers in Jiangsu province demonstrate highest price sensitivity, while semiconductor fabs in Pyeongtaek and Yongin accept premium positioning for qualified electronic-grade supply.
Supply Chain Analysis
Temperature-controlled freight requirements for electronic-grade material elevate logistics costs and limit viable carrier networks to specialized chemical transport operators. Manufacturing concentration rests on Germany, China, and Belgium, where integrated sulfonic acid chemistry platforms serve captive catalyst demand for Ludwigshafen and Antwerp chemical hubs. Raw material draws from dimethyl disulfide oxidation feedstocks, nitrogen dioxide supply, and stainless-steel containment infrastructure. Single-source vulnerability concentrates in European process engineers with dimethyl disulfide oxidation expertise. Distribution runs through direct producer contracts for electronic and pharmaceutical grades, while industrial-grade shipments flow via regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic-grade qualification momentum in Taiwan and South Korean semiconductor fabs is shifting procurement toward premium specifications with complete biodegradability documentation, transforming this into a late-cycle quality story where certification barriers protect margin structures.
For Market Incumbents: Anticipate peracetic acid substitution pressure in North American food processing cleaning applications by accelerating pharmaceutical-grade certification investments ahead of CDSCO residual solvent guideline enforcement. Defend channel control through backward integration into dimethyl disulfide oxidation capacity and captive supply relationships with Yangtze River Delta semiconductor material distributors. Prioritize continuous-flow reactor technology deployment for real-time grade switching between industrial and electronic specifications. For New Entrants and Emerging Players: Continuous-flow sulfonation reactor automation offers a technology-first wedge into electronic-grade production without legacy batch-process retrofit costs. Target Indian pharmaceutical contract manufacturing in Hyderabad and Ahmedabad clusters where CDSCO tightened guidelines are opening qualification pathways for new pharmaceutical-grade suppliers. Pursue joint venture structures with established semiconductor material distributors to compress 18-24 month fab validation timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale regional producers possessing dimethyl disulfide oxidation expertise and existing electronic-grade pilot lines awaiting qualification completion. Long-term viability centers on supply chain positioning for biodegradable acid catalyst substitution mandates under REACH and China's MEE wastewater frameworks. Monitor semiconductor material qualification completion announcements from Taiwan and South Korean fabs as inflection indicators for electronic-grade revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Dedicated electronic-grade lines in Gyeonggi-do province address Samsung Foundry qualification demand. |
| Backward Integration | Captive dimethyl disulfide oxidation at Ludwigshafen insulates BASF from sulfur chemical price volatility. |
| Long-term Supply Agreement | Bayer CropScience multi-year offtake contracts lock in industrial-grade volume for sulfonamide intermediate production. |
| Green Manufacturing Transition | Continuous-flow reactor technology enables real-time grade switching with reduced batch-to-batch variation. |
| Joint Venture | Taiwan wafer etching chemical suppliers integrate methanesulfonic acid into mixed-acid formulations for advanced node processing. |
Research Approach
Bottom-up end-use modeling reconciled against top-down sulfonic acid chemistry capacity tracking forms the analytical core of this study. Primary interviews with plant managers at German and Chinese specialty chemical producers, procurement leads at Taiwan semiconductor fabs, distribution channel partners serving Indian pharmaceutical contract manufacturers, and technical R&D directors at agrochemical formulators were validated against secondary sources including ECHA REACH registration databases, China MEE wastewater discharge filings, CDSCO pharmaceutical guidelines, and SEC 10-K disclosures from integrated chemical conglomerates. This triangulation approach ensures demand-side consumption patterns align with supply-side production capacity across grade tiers.
Input-output matrix framing connects dimethyl disulfide feedstock availability to electronic-grade output volumes across the projection horizon. Segmentation dimensions modeled include grade purity tier, end-use industry application, packaging format specifications, and regional production hub concentration. CAGRs were derived from regression analysis against semiconductor capital expenditure cycles and agrochemical formulation trends. Industry-specific forecast inputs incorporate semiconductor material qualification timeline distributions and REACH substitution mandate implementation schedules.
The model holds under stable regulatory enforcement timelines for REACH and China's MEE standards; deviation in semiconductor fab qualification acceleration or feedstock supply disruptions would shift capacity allocation decisions. Forecasts reflect documented assumptions regarding grade-mix evolution and regional procurement consolidation patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Polyferric Sulfate Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Global 2-Methylpropene Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Middle East Ammonia Market
Bulk Chemicals
Magnesium Lactate Market