
 Global Vanadium Pentoxide Market | 2026-2036
Global Vanadium Pentoxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vanadium Pentoxide Market Intelligence
A shift from single-source contracts toward multi-supplier procurement strategies is broadening access to varied purity grades for end-users. This change mitigates supply chain risks associated with geographic concentration. Pangang Group Vanadium and Titanium Resources Co. Ltd. dominates high-volume production, while specialists like U.S. Vanadium LLC focus on high-purity applications for aerospace and chemical catalysts. Meanwhile, EVRAZ leverages its integrated steelmaking operations to supply the ferrovanadium market.
Vanadium pentoxide is an inorganic compound, typically appearing as a yellow to red crystalline powder. Its primary industrial value comes from its function as a precursor to ferrovanadium and as a key component in vanadium electrolytes. The steel manufacturing application remains the largest consumer, primarily utilizing powder and flake forms for alloying. However, the energy storage application, which demands high-purity granules for battery systems, represents the fastest-growing segment.
Producers must navigate a complex regulatory environment governed by bodies like Europe's ECHA under REACH and the U.S. EPA. These regulations impose strict controls on handling, waste disposal, and workplace exposure, influencing production costs. In parallel, China's MEE policies on industrial emissions impact processing methods. Stakeholder success will depend on aligning product purity with the specific technical and cost demands of distinct end-user applications.
Market Dynamics
The competitive landscape is bifurcating between the established, high-volume demands of steel manufacturing and the high-purity, specification-driven requirements of the emerging energy storage sector. This division influences everything from capital investment priorities to regional supply chain development.
Growth Catalysts
- Grid-Scale Energy Storage:Vanadium redox flow batteries (VRFBs) offer long-duration storage ideal for stabilizing grids with high renewable penetration, a key objective of frameworks like the EU Green Deal and China's dual carbon goals.
- Aerospace and Defense Alloys:The inherent strength-to-weight ratio of vanadium alloys makes them critical for high-performance aerospace components, sustaining a consistent demand for high-purity material grades from this specialized sector.
- Chemical Sector Expansion:Vanadium pentoxide's role as a catalyst in the production of sulfuric acid and other industrial chemicals links its demand directly to the expansion of the broader chemical manufacturing industry.
Market Restraints
- Price Volatility:Significant fluctuations in vanadium raw material prices create budget uncertainty for large-scale projects, particularly in the cost-sensitive energy storage sector, potentially delaying final investment decisions.
- Geographic Supply Concentration:The heavy concentration of vanadium mining and primary processing in China and Russia introduces considerable geopolitical and supply chain risk for consumers in other regions.
- Substitution Threats in Steel:In certain steel applications, other alloying elements like niobium or titanium can be substituted for vanadium, particularly during periods of high vanadium prices, capping demand in the metallurgical segment.
Strategic Opportunities
- Next-Generation Battery Chemistries:Research into advanced battery designs, including solid-state electrolytes and hybrid flow batteries, presents an opportunity for developing new vanadium compounds with enhanced performance characteristics.
- Domestic Production Incentives:Policies like the U.S. Inflation Reduction Act (IRA) encourage the development of domestic supply chains for critical battery materials, creating an opening for new North American vanadium processing facilities.
- Circular Economy Models:Developing efficient, cost-effective methods for recycling and recovering vanadium from spent catalysts and batteries offers a path to reduce reliance on primary extraction and improve supply security.
Industry Challenges
- Capital-Intensive Processing:The high capital expenditure required to construct and commission new vanadium processing plants that comply with modern environmental standards, such as those from the EPA, creates a high barrier to entry.
- Electrolyte Standardization:A lack of universally accepted standards for vanadium electrolyte purity, performance, and degradation testing slows commercialization and complicates interoperability between different VRFB systems.
- Waste Stream Management:The processing of vanadium generates hazardous waste materials that require specialized handling and disposal methods, adding significant operational complexity and cost under regulations like Europe's REACH.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vanadium Pentoxide Market |
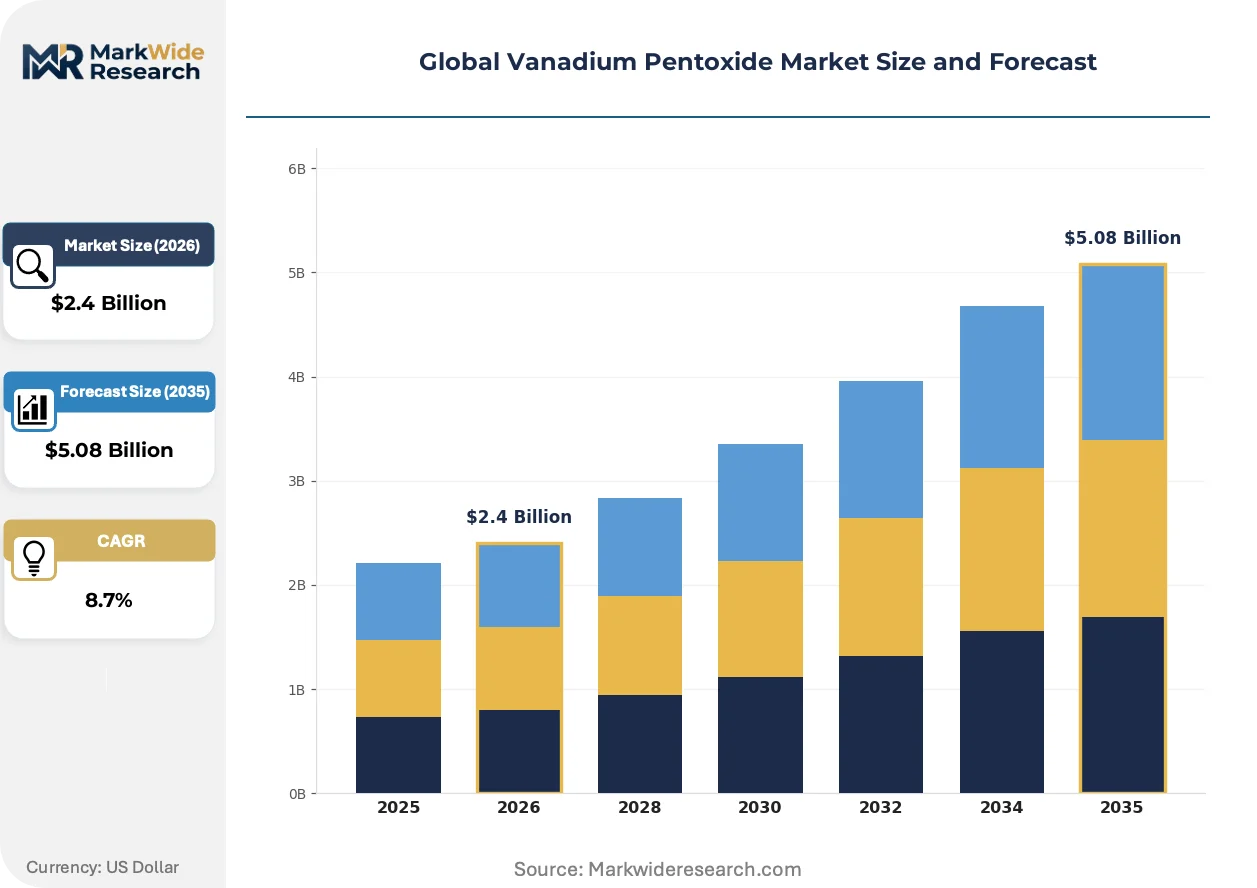
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Flakes, Pellets, Tablets Application: Steel Manufacturing, Chemical Industry, Catalysts, Energy Storage, Ceramics End User Industry: Metal Production, Chemical Processing, Battery Manufacturing, Glass Fabrication, Aerospace Distribution Channel: Direct Sales, Distributors, E-commerce, Industrial Suppliers, Specialty Retailers |
| Companies Covered | Pangang Group Vanadium and Titanium Resources Co. Ltd., U.S. Vanadium LLC, EVRAZ, Treibacher Industrie AG, Bushveld Minerals, Largo Resources Ltd., Chengyu Vanadium Titanium Technology, Beijing Jianlong Heavy Industry Group, Glencore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vanadium Pentoxide Market Strategic Shifts & Innovations
Innovation is following two distinct paths, one focused on optimizing cost and volume for metallurgical applications and the other centered on achieving ultra-high purity and electrochemical performance for battery systems. This divergence is reshaping R&D priorities and investment strategies across the value chain.
High-purity vanadium electrolyte serves as the charge-carrying medium in vanadium redox flow batteries, enabling long-duration energy storage. Utility-scale energy developers and grid operators are adopting this technology as part of major grid modernization projects. This specific application is consolidating the market's growth trajectory around energy storage, redirecting capital and research efforts toward battery-grade material science.
China's MEE policies on industrial emissions and waste are tightening standards for mineral processing operations, including vanadium extraction. This regulatory pressure forces producers to invest in cleaner processing technologies and more sophisticated waste treatment facilities to maintain operating licenses. The steel and ferrovanadium segments are most affected, as they must absorb these compliance costs or risk production curtailments.
A notable behavioral change involves end-users moving away from single-supplier contracts toward diversified sourcing models to ensure supply security. This shift disrupts the established relationships between large miners and industrial consumers, opening the door for smaller, specialized producers of different purity grades. The trend is most prominent among battery manufacturers in Asia who are building resilient supply chains for critical materials.
Global Vanadium Pentoxide Market Segmentation
Segmentation provides a granular understanding of the Global Vanadium Pentoxide Market, highlighting the distinct demand patterns and purity requirements across various applications. This analysis differentiates between high-volume, traditional industrial uses and the emerging, high-specification demands of advanced technologies.
Product Type:
Vanadium pentoxide product types exhibit varying integration depths within end-user processes, ranging from bulk materials directly incorporated into alloys to highly refined forms for specialized chemical synthesis.
- Powder:This common form is extensively used in metallurgical applications, offering a high surface area for efficient alloying. Demand concentrates in China's steel manufacturing sector for ferrovanadium production, driven by robust infrastructure development.
- Granules:Preferred for high-purity applications, such as vanadium electrolytes in redox flow batteries, ensuring consistent electrochemical performance and minimal impurities. Demand is concentrating in Asia for large-scale energy storage projects, propelled by ambitious grid modernization initiatives.
- Flakes:Utilized in specific alloying processes where controlled dimensions are beneficial for material integration.
- Pellets:Formed for ease of handling and precise dosing in various industrial furnaces and chemical reactors.
- Tablets:Employed in smaller batch chemical reactions requiring accurate measurement and controlled dissolution rates.
Volume placements concentrate in Powder forms; the faster expansion belongs to Granules.
Application:
Applications for vanadium pentoxide differentiate significantly by required volume and the associated cost structures, from bulk industrial uses to niche, high-value chemical processes.
- Steel Manufacturing:This segment consumes the largest share of vanadium pentoxide, primarily for alloying to enhance the strength, toughness, and wear resistance of steel. Demand concentrates in global automotive and construction sectors, driven by material performance requirements for safety and durability.
- Energy Storage:This application requires ultra-high purity vanadium pentoxide for electrolytes in vanadium redox flow batteries, enabling long-duration grid stabilization and renewable energy integration. Demand is concentrating in Europe and China, supported by national renewable energy integration policies.
- Chemical Industry:Utilizes vanadium pentoxide as a key catalytic agent in various synthesis reactions, including the production of sulfuric acid.
- Catalysts:Employed in environmental applications and industrial processes for promoting oxidation reactions and reducing emissions.
- Ceramics:Incorporated for color pigmentation and property modification in advanced ceramic materials and glazes.
The largest consumption originates from Steel Manufacturing, while Energy Storage exhibits the most dynamic growth.
End User Industry:
End-user industries for vanadium pentoxide are segmented by their market maturity and established procurement practices, influencing material specifications and supply chain engagement.
- Metal Production:Represents a mature end-user segment with established demand for vanadium pentoxide in ferrovanadium alloys for steel and other metals. Demand concentrates in industrial economies, driven by consistent global steel production volumes.
- Battery Manufacturing:An emerging end-user segment demanding high-purity vanadium pentoxide for redox flow battery electrolytes, critical for grid-scale energy storage. Demand concentrates in China and the United States, propelled by critical minerals policies and grid decarbonization targets.
- Chemical Processing:Relies on vanadium pentoxide as a catalyst for various industrial chemical syntheses, including maleic anhydride production.
- Glass Fabrication:Employs vanadium compounds for specialized optical properties, UV absorption, and coloring agents in glass production.
- Aerospace:Requires high-performance vanadium alloys for lightweight, high-strength structural components in aircraft and spacecraft.
Traditional industrial consumers in Metal Production maintain stable demand, whereas Battery Manufacturing is rapidly expanding its material requirements.
Distribution Channel:
Distribution channels for vanadium pentoxide reflect varying degrees of direct supplier engagement and specialized logistical requirements across the supply chain.
- Direct Sales:This channel characterizes transactions for large volumes of industrial-grade vanadium pentoxide directly from primary producers to major end-users, such as large steel mills. This channel dominates in China for steel manufacturers, ensuring consistent supply and negotiated pricing.
- Distributors:Facilitate access for smaller to medium-sized enterprises and specialized applications, providing inventory management, localized delivery, and technical support. This channel is critical in Europe for diverse chemical and catalyst buyers, offering flexibility and regional reach.
- E-commerce:Serves niche buyers and researchers requiring smaller quantities of specific vanadium pentoxide grades for specialized projects.
- Industrial Suppliers:Offer integrated solutions, often bundling vanadium pentoxide with other raw materials and services for manufacturing clients.
- Specialty Retailers:Cater to highly specialized applications, including academic research and development laboratories, providing tailored product specifications.
The bulk of material flow occurs via Direct Sales, with Distributors providing essential market access for diverse clientele.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive vanadium mining and processing capabilities anchor global vanadium pentoxide supply. This concentration influences regional market dynamics and investment flows across the value chain. Demand for this critical material is bifurcating between traditional industrial uses and emerging energy storage applications.
China
China's robust industrial base drives significant vanadium pentoxide demand for steel manufacturing and emerging energy storage. MEE policies on industrial emissions tighten standards for mineral processing, influencing production methods. The country's dual carbon goals accelerate investment in grid-scale battery projects, particularly within the Yangtze River Delta for VRFB production.
United States
The United States market sees demand from high-performance aerospace alloys and the developing energy storage sector. The U.S. Inflation Reduction Act (IRA) incentivizes domestic supply chains for critical battery materials, fostering new processing facilities. EPA regulations on handling and waste disposal shape production costs, impacting operations in industrial hubs like the Pacific Northwest.
Germany
European demand, particularly from Germany, originates from its sophisticated chemical industry and grid modernization initiatives. The EU Green Deal promotes renewable energy integration, driving vanadium redox flow battery adoption across the continent. ECHA regulations under REACH impose strict controls on handling and waste disposal, influencing production costs for chemical plants in the Rhine-Ruhr region.
Russia
Russia maintains a significant position as a primary producer of vanadium, mainly for its ferrovanadium market. Domestic environmental standards influence processing methods and production costs for local industries. Geographic supply concentration from the Ural Mountains region introduces geopolitical risks, impacting global supply chain stability for consumers seeking diversified sources.
Global Vanadium Pentoxide Market Key Industry Players
Capacity expansion dominates the current landscape, driven by the bifurcating demands of steel manufacturing and energy storage. The market structure exhibits a tiered consolidation, with large-scale producers supplying traditional industrial sectors. Specialized players focus on high-purity materials for advanced applications, addressing niche requirements. Strategic partnerships and technology licensing represent other key competitive moves among market participants aiming for market share.
At the scale-driven end, Chinese-based Pangang Group Vanadium and Titanium Resources Co. Ltd. anchors high-volume production for metallurgical applications, exemplifying integrated resource management and broad market reach. U.S. Vanadium LLC, a North American entity, represents the specialized segment, focusing on high-purity materials tailored for aerospace and chemical catalysts. EVRAZ, with its vertically integrated steelmaking operations, occupies a position supplying the ferrovanadium market, leveraging captive production capabilities and established industrial customer bases.
| Leading Market Players |
|---|
| Pangang Group Vanadium and Titanium Resources Co. Ltd. |
| U.S. Vanadium LLC |
| EVRAZ |
| Treibacher Industrie AG |
| Bushveld Minerals |
| Largo Resources Ltd. |
| Chengyu Vanadium Titanium Technology |
| Beijing Jianlong Heavy Industry Group |
| Glencore |
| Others |
Cost & Logistics Intelligence
Vanadium spot prices, influenced by global mining output and geopolitical shifts, cascade through the supply chain into distinct pricing tiers for different purity grades. This volatility creates budget uncertainty for large-scale projects, particularly in the cost-sensitive energy storage sector.
Pricing Analysis
Purity certification and integrated technical support differentiate pricing for vanadium pentoxide. The dominant pricing structure combines contract-based long-term offtake for bulk industrial uses with value-based pricing for high-purity battery-grade materials. Price differentiation drivers include material purity grade and the volume scale of the transaction. Pricing pressure stems from geographic supply concentration and potential substitution threats in metallurgical applications. Steel manufacturing represents the most price-sensitive segment, while aerospace and high-purity chemical catalyst buyers exhibit lower price sensitivity.
Supply Chain Analysis
Direct sales channels manage large-volume contracts for industrial-grade vanadium pentoxide, primarily serving major steel mills. The supply chain draws heavily from vanadium ore and processing facilities concentrated in China and Russia. This geographic concentration creates significant geopolitical and single-source vulnerability risks for global consumers. Distributors provide essential market access for smaller to medium-sized enterprises and specialized applications, offering localized inventory and technical assistance for diverse clientele.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vanadium pentoxide market is defined by a vertical-integration race, with players actively pursuing upstream control over raw material processing to secure high-purity electrolyte production.
For Market Incumbents:
Lock in long-term supply agreements for battery-grade vanadium pentoxide with emerging energy storage developers. This strategy mitigates demand-side uncertainty and strengthens market position against new entrants. Invest in advanced processing technologies to meet increasingly stringent purity standards for vanadium redox flow batteries, addressing the threat of electrolyte standardization. Expand capacity in regions like North America to capitalize on domestic production incentives such as the U.S. Inflation Reduction Act.
For New Entrants and Emerging Players:
E-commerce platforms for specialized chemical buyers offer an entry point for high-purity vanadium pentoxide grades. Target niche high-purity applications, such as chemical catalysts or small-batch R&D, where established players may lack agility. The most penetrable segment involves supplying specialized chemical firms requiring tailored material specifications. A focused go-to-market angle emphasizes rapid customization and certified small-volume supply chains for specific technical requirements.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor vertically integrated processors in North America, particularly those with established or developing high-purity production capabilities. The long-term viability of the market is anchored by the accelerating demand for vanadium redox flow batteries in grid-scale energy storage. A critical signal to watch is the progress toward global standardization of vanadium electrolyte purity and performance metrics, which will unlock broader VRFB adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Battery-Grade V2O5 | Increases supply of critical material for rapidly expanding energy storage sector. |
| Backward Integration into Vanadium Mining | Secures raw material access and mitigates supply chain risks for processors. |
| Green Manufacturing Technology Adoption | Ensures compliance with tightening environmental regulations, particularly in China. |
| Long-term Supply Agreements with VRFB Makers | Provides demand stability and strengthens relationships with key growth segment. |
| Technology Licensing for Advanced Electrolytes | Positions companies to capitalize on next-generation battery chemistry innovations. |
Research Approach
Multi-period observation of production volumes, trade flows, and patent filings anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with plant managers, procurement leads, and R&D directors from leading vanadium pentoxide producers and end-users. Secondary data was validated through customs data, company annual reports, IEA reports, and regulatory documents from bodies like ECHA and the EPA, triangulating top-down and bottom-up market perspectives.
Segment-specific weighting informed the forecast framework, disaggregating market data across critical dimensions including product type, application, end-user industry, and regional regulatory frameworks. CAGRs were derived from historical market sizing and projected demand scenarios over the projection horizon. Key industry-specific forecast inputs included global renewable energy deployment targets and steel production forecasts, reflecting their direct influence on vanadium pentoxide consumption.
The model holds under stable regulatory conditions and predictable commodity price trends; deviation in geopolitical stability or rapid technological shifts in battery chemistry would shift forecast trajectories. Periodic stress-testing of base assumptions is recommended to account for market uncertainties.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Furfural Market
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Refined Naphthalene Market
Bulk Chemicals
Ethylene Oxide Market