
 Ethylene and Propylene Market | 2026-2036
Ethylene and Propylene Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene and Propylene Market Foresight
The US Gulf Coast is reshaping global ethylene and propylene supply dynamics through massive cracker expansions along the Texas-Louisiana corridor. Saudi Basic Industries Corporation anchors its position through captive feedstock access at Jubail Industrial City. LyondellBasell Industries N.V. leverages its Channelview complex to sustain differentiated polyethylene output. Dow Inc operates an integrated propylene oxide-styrene chain that competes on derivative margin capture.
Ethylene and propylene are light olefin hydrocarbons produced primarily via steam cracking of naphtha, ethane, or propane at temperatures exceeding 800°C, yielding polymer-grade purity essential for downstream plastics synthesis. Steam cracking technology dominates capacity deployment due to its flexibility across feedstock slates, while metathesis processes gain traction for on-purpose propylene where conventional yields fall short. The packaging end-use segment leads volume absorption through polyethylene resin demand, whereas automotive applications concentrate margin pools in specialized copolymer grades.
The US Environmental Protection Agency enforces air emissions standards under the Clean Air Act that constrain cracker expansion timelines, while China's Ministry of Ecology and Environment imposes carbon intensity benchmarks that redirect capital toward ethane-fed configurations. The EU Green Deal's carbon border adjustments reshape import competitiveness for Middle Eastern producers supplying European derivative markets. Stakeholders must monitor feedstock cost differentials between ethane and naphtha as the decisive variable for regional capacity economics.
Market Dynamics
The ethylene and propylene market is pivoting around feedstock cost arbitrage between ethane and naphtha, with cracker operators reconfiguring slate flexibility to capture margin swings. This structural tension between light and heavy feedstock economics is redirecting capital deployment across coastal corridors.
Growth Catalysts
- Flexible packaging expansion:Food and beverage brands are specifying high-clarity polyethylene films for extended shelf-life applications, pulling polymer-grade ethylene demand through converter networks.
- China's dual carbon framework:MEE carbon intensity benchmarks are accelerating investment in ethane-fed crackers along the Bohai Rim, displacing coal-chemical olefin routes.
- Propylene dehydrogenation:On-purpose PDH units are scaling across the US Gulf Coast to bridge the propylene supply gap from lighter ethane cracking yields.
Market Restraints
- Ethane price volatility:Mont Belvieu hub pricing swings compress cracker margins when natural gas liquids fractionation bottlenecks emerge.
- Middle Eastern supply concentration:Jubail and Yanbu industrial clusters control substantial export-oriented polyethylene capacity, creating single-source dependency risks for Asian converters.
- Steam cracking CO2 intensity:Furnace emissions profiles face tightening scrutiny under EU Green Deal carbon border adjustments, disadvantaging naphtha-heavy configurations.
Strategic Opportunities
- India's petrochemical deficit:Domestic polyethylene consumption outpaces local ethylene capacity by a substantial margin, creating import substitution potential for integrated complexes at Dahej and Paradip.
- Chemical recycling feedstock:Pyrolysis oil from post-consumer plastic waste is qualifying as cracker co-feedstock under emerging mass-balance certification schemes.
- Carbon capture integration:Post-combustion capture on cracking furnaces qualifies for US IRA 45Q tax credits, improving project returns for Gulf Coast brownfield expansions.
Industry Challenges
- Specialized furnace engineering talent:Cracker furnace design and pyrolysis optimization expertise concentrates among a narrow cohort of contractors, extending project timelines.
- Polymer-grade certification delays:Propylene purity specifications for polypropylene catalyst systems require extended qualification cycles with downstream licensees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene and Propylene Market |
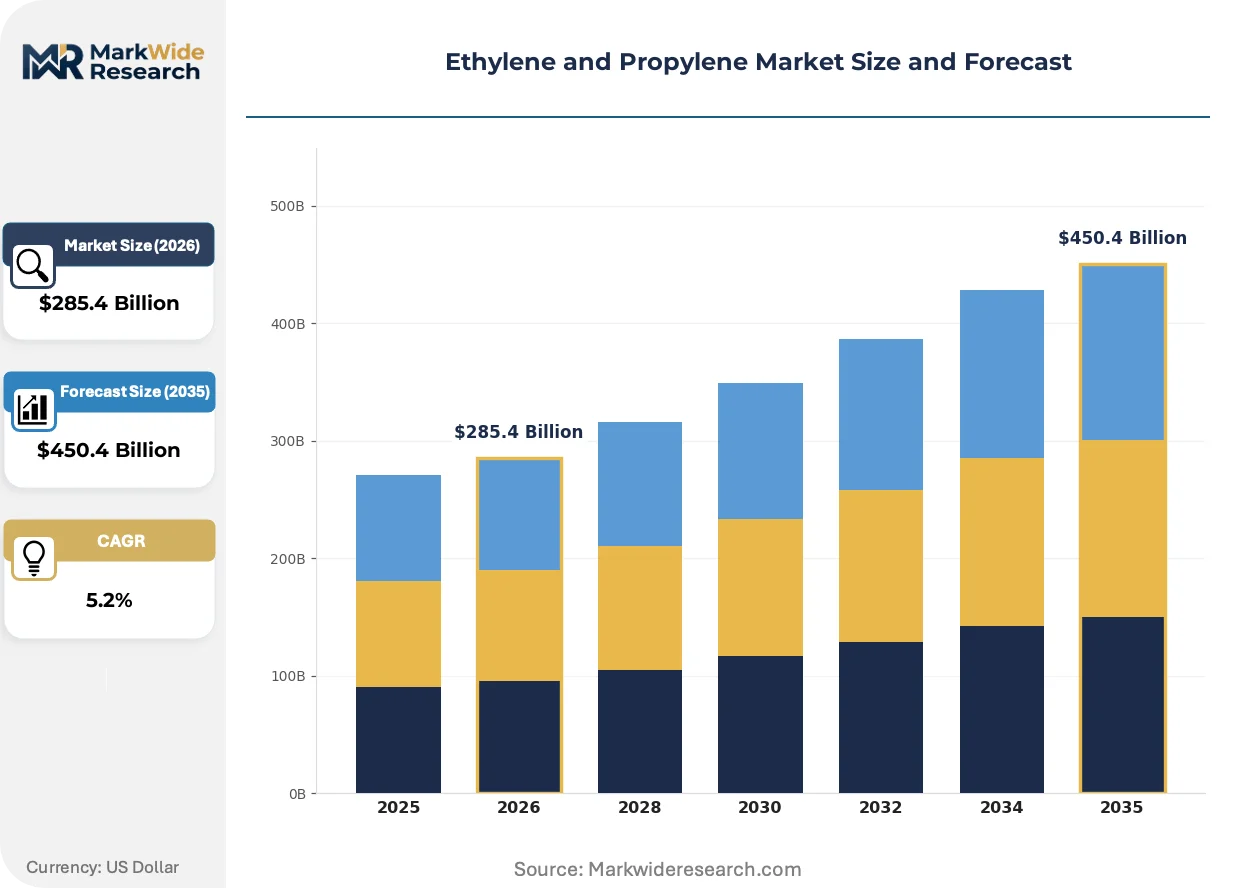
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $450.4 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene, Propylene, Copolymers, Oligomers End Use Industry: Automotive, Packaging, Construction, Agriculture Technology: Steam Cracking, Catalytic Cracking, Dehydrogenation, Metathesis Application: Resins, Fibers, Coatings, Adhesives |
| Companies Covered | China Petroleum & Chemical Corporation, Saudi Basic Industries Corporation, Chevron Phillips Chemical Company LLC, LyondellBasell Industries N.V., Dow Inc, INEOS Group, Exxon Mobil Corporation, Total S.A, National Petrochemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene and Propylene Market Shifts & Advancements
Digital instrumentation and advanced process control are penetrating steam cracking operations, enabling real-time yield optimization that was previously unreachable. This technological infusion is compressing the feedback loop between furnace conditions and product slate.
Advanced process control systems integrating machine learning models with distributed control architecture are digitizing furnace temperature profiling and steam-to-hydrocarbon ratio management. Ethylene producers in the US Gulf Coast are deploying these systems fastest, drawn by ethane price volatility that rewards instantaneous yield shifts. The technology is digitizing margin capture by automating responses to feedstock quality variation that previously required manual intervention.
The EU Green Deal's carbon border adjustment mechanism is imposing emissions accounting requirements on imported polyethylene and polypropylene derivatives. European converters are now demanding certified low-carbon olefin feedstock, pressuring Middle Eastern exporters to document cracker emissions intensity. Packaging manufacturers in Germany and the Netherlands are responding by dual-sourcing from US ethane-based supply and qualifying circular feedstock grades.
Brand-owner sustainability mandates are compressing the qualification cycle for recycled-content resins. Major beverage and personal care companies are inserting post-consumer recycled polyethylene specifications into procurement contracts, bypassing traditional converter intermediaries. This specification shift is most visible in North American flexible packaging, where direct brand-to-resin-supplier negotiations are displacing distributor-mediated purchasing.
Ethylene and Propylene Market Segmentation
Segmentation in ethylene and propylene markets reveals how feedstock flexibility, derivative specifications, and end-use performance requirements fragment commercial strategies. Understanding these dimensions exposes where margin pools concentrate and where capital deployment faces structural constraints.
Product Type:
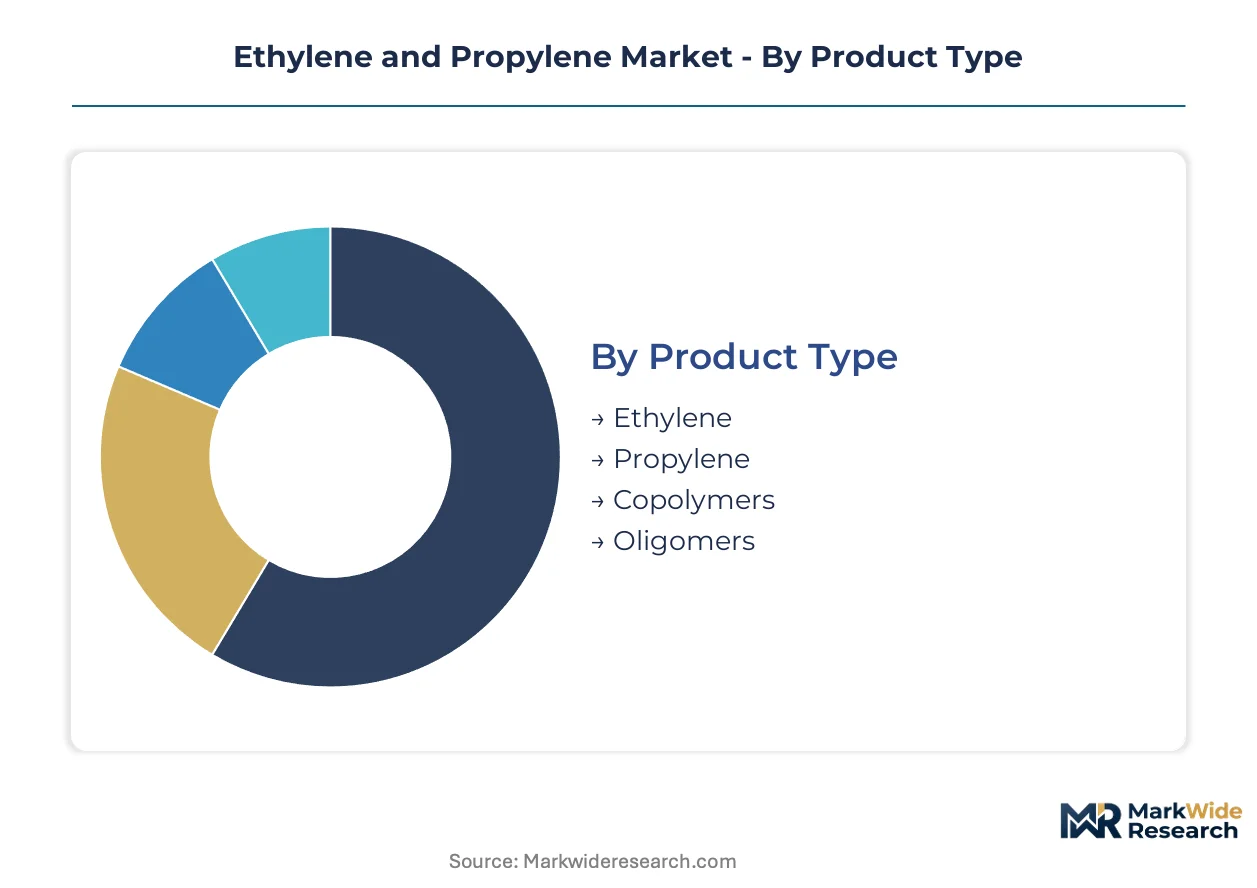
Volume concentration across product grades determines cracker configuration economics and regional trade flow patterns.
- Ethylene:Polymer-grade material with 99.9% purity specification serves as the primary feedstock for high-density and linear low-density polyethylene chains. Demand concentrates along the US Gulf Coast ethane-fed corridor where LyondellBasell and Dow operate integrated complexes, though China's MEE carbon benchmarks are accelerating ethane cracker investments at Bohai Rim sites to displace coal-chemical routes.
- Propylene:Chemical-grade and polymer-grade specifications split between refinery fluid catalytic cracking byproduct and on-purpose dehydrogenation output. PDH units at Channelview and Corpus Christi bridge supply gaps as ethane cracking yields decline, while Saudi Aramco's Jubail complex leverages captive propane feedstock for export-oriented polypropylene.
- Copolymers:Ethylene-vinyl acetate and ethylene-propylene rubber grades command specialty premiums in automotive sealing and flexible packaging lamination.
- Oligomers:Linear alpha-olefins and polybutene-1 serve surfactant and viscosity modifier applications with tighter specification windows.
Ethylene commands the established base. The steepest expansion runs through polymer-grade propylene as PDH capacity scales.
End Use Industry:
Application-driven purity requirements and volume scale reshape how producers configure derivative integration and geographic positioning.
- Packaging:Flexible film converters specify metallocene-catalyzed linear low-density polyethylene for clarity and seal integrity in food contact applications. Major beverage brands now source directly from resin suppliers at Baytown and Mont Belvieu, bypassing traditional distributor channels, while EU Green Deal carbon border adjustments pressure German and Dutch converters to dual-source from US ethane-based supply.
- Automotive:Interior trim and under-hood applications absorb polypropylene copolymers with high impact resistance and thermal stability specifications. Electric vehicle battery housing demand is pulling specialized ethylene-propylene rubber compounds through Tier 1 supplier networks at Detroit and Stuttgart.
- Construction:Pipe extrusion and geomembrane applications consume medium-density polyethylene with long-term hydrostatic stress ratings.
- Agriculture:Mulch films and irrigation tubing specify UV-stabilized linear low-density grades with controlled degradation profiles.
Packaging absorbs the dominant volume share. Automotive applications capture the highest margin per kilogram through specialized copolymer grades.
Technology:
Process selection locks in feedstock flexibility, emissions intensity, and capital recovery timelines for decades.
- Steam Cracking:Furnace temperatures exceeding 850°C crack naphtha, ethane, or propane into light olefins with co-product hydrogen and pyrolysis gasoline. US Gulf Coast operators deploy advanced process control systems integrating machine learning with distributed control architecture to automate yield shifts in response to Mont Belvieu ethane price volatility.
- Catalytic Cracking:Refinery-integrated fluid catalytic cracking units yield propylene as a byproduct with lower purity than steam cracking, constraining polypropylene catalyst compatibility.
- Dehydrogenation:PDH technology scales across Texas and Louisiana to produce on-purpose propylene where conventional steam cracking yields fall short.
- Metathesis:Olefin conversion technology interconverts ethylene and butenes into propylene, gaining traction where feedstock arbitrage favors this chemistry.
Steam cracking retains the installed capacity base. Dehydrogenation is climbing the fastest as propane-to-propylene economics improve.
Application:
Downstream conversion technology and certification requirements segment how olefin producers qualify customers and structure contracts.
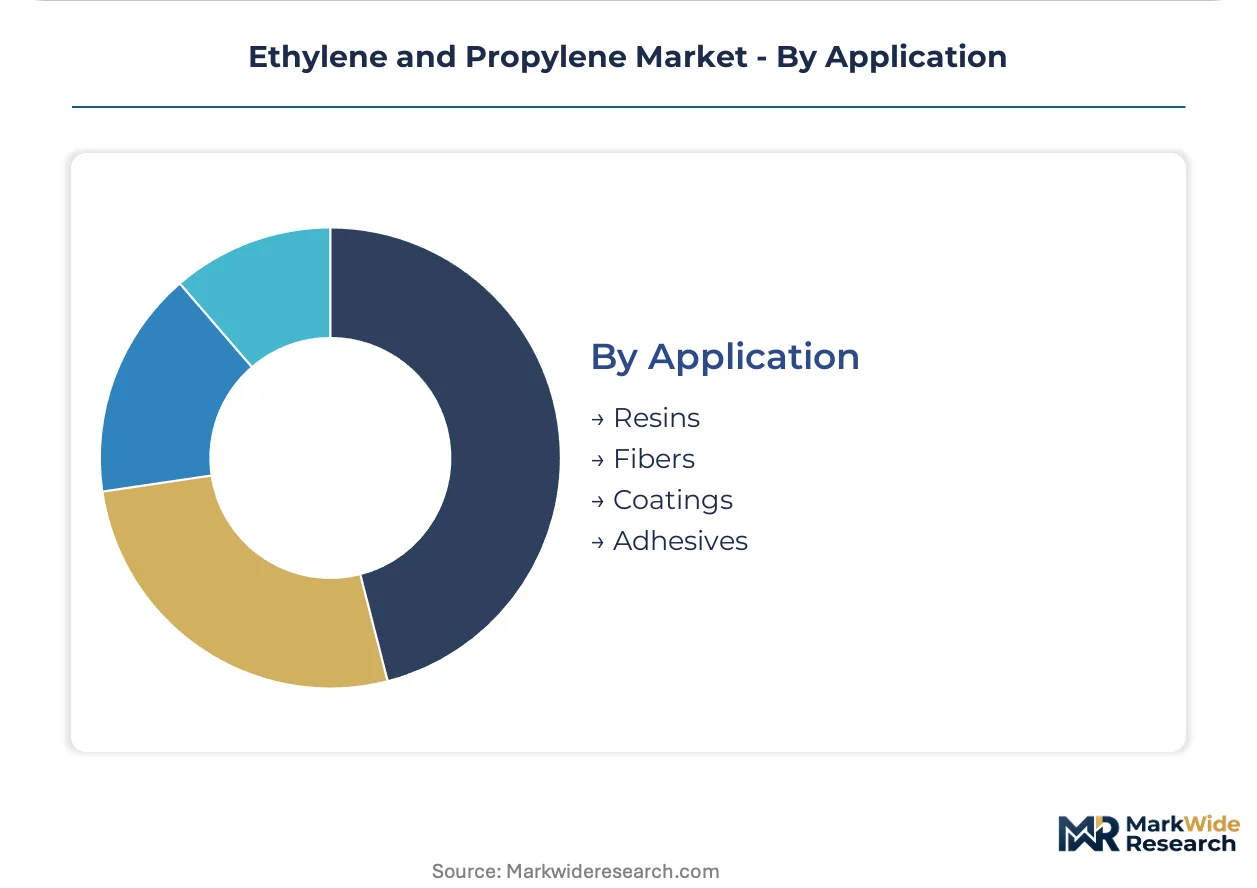
- Resins:Polyethylene and polypropylene pellet production dominates volume flows, with polymer-grade specifications requiring extended qualification cycles with catalyst licensors at polypropylene reactor sites.
- Fibers:Polypropylene staple and filament applications serve nonwoven hygiene products and industrial geotextiles with melt-flow index precision requirements.
- Coatings:Ethylene-vinyl acetate emulsions and polyethylene dispersions serve architectural and industrial protective applications.
- Adhesives:Hot-melt formulations based on ethylene-vinyl acetate and amorphous polyalphaolefin specify tackifier compatibility and thermal stability.
Resins anchor the volume foundation. Fibers are gaining share fastest through hygiene product demand and geotextile infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene and propylene capacity clusters along coastal corridors where feedstock import infrastructure and derivative demand overlap. The United States, China, Saudi Arabia, Germany, and India concentrate the decisive investment flows reshaping trade patterns.
United States
Mont Belvieu ethane pricing drives cracker margin calculations for Gulf Coast operators. The EPA enforces Clean Air Act emissions standards that constrain expansion timelines at Texas and Louisiana sites. Channelview and Baytown complexes anchor the world's largest ethane-fed polyethylene export capacity.
China
Flexible packaging converters along the Yangtze Delta pull polymer-grade ethylene through integrated logistics hubs. The MEE dual carbon framework redirects capital toward Bohai Rim ethane crackers displacing coal-chemical routes. Dahej and Paradip industrial zones concentrate import substitution investments for polyethylene deficit coverage.
Saudi Arabia
Jubail Industrial City leverages captive propane feedstock for export-oriented polypropylene and polyethylene output. The SFDA maintains chemical product registration requirements affecting derivative export documentation. Yanbu petrochemical corridor expands olefin capacity targeting European and Asian converter markets.
Germany
Automotive Tier 1 suppliers at Stuttgart and Wolfsburg specify high-purity propylene copolymers for electric vehicle battery housings. The EU Green Deal carbon border adjustment mechanism imposes emissions accounting on imported polyethylene derivatives. Ludwigshafen and Cologne chemical clusters face feedstock cost pressure from US ethane-based competition.
India
Domestic polyethylene consumption outruns local ethylene capacity by substantial margins across Maharashtra and Gujarat. The PLI scheme for chemicals incentivizes integrated petrochemical complex development at Dahej and Paradip. Reliance Industries operates the Jamnagar refinery-integrated cracker serving western Indian packaging converters.
Ethylene and Propylene Market Competitive Landscape
State-affiliated energy majors and integrated chemical conglomerates split the market between feedstock-captive and derivative-integrated models. The structure concentrates among ten to twelve operators controlling substantial ethylene and propylene capacity globally. National oil companies and diversified chemical multinationals constitute the dominant archetypes. Competitive moves center on cracker feedstock flexibility investments and polyethylene derivative integration into packaging converter networks.
Within the state-affiliated tier, China Petroleum & Chemical Corporation and Saudi Basic Industries Corporation exemplify feedstock-captive positioning through refinery integration and industrial city development. Among diversified chemical conglomerates, LyondellBasell Industries N.V. and Dow Inc occupy positions emphasizing polymer-grade derivative output and advanced process control deployment. Chevron Phillips Chemical Company LLC represents the Gulf Coast ethane-fed archetype with polyethylene export orientation.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| Saudi Basic Industries Corporation |
| Chevron Phillips Chemical Company LLC |
| LyondellBasell Industries N.V. |
| Dow Inc |
| INEOS Group |
| Exxon Mobil Corporation |
| Total S.A |
| National Petrochemical Company |
| Others |
Supply & Pricing Matrix
Single-source dependency on Jubail and Yanbu industrial clusters concentrates pricing power among Saudi exporters while simultaneously exposing Asian converters to supply disruption cascades. This concentration dynamic compresses standard-grade polyethylene margins through volume competition while amplifying premium-tier spreads for certified low-carbon and polymer-grade propylene specifications.
Pricing Analysis
The EU Green Deal's carbon border adjustment mechanism dictates the pricing tier structure across European derivative markets, separating certified low-carbon olefin feedstock from conventional naphtha-based supply. Three-tier pricing structure across premium, standard, and economy levels reflects emissions certification status, polymer-grade purity specifications, and volume offtake commitments. Cost compression in standard-grade polyethylene is intensifying because US Gulf Coast ethane-fed capacity expands export volumes. Brand-owner procurement teams at major beverage and personal care companies demonstrate the least price sensitivity for mass-balance certified recycled-content resins, while flexible film converters in Southeast Asia remain most sensitive to feedstock cost swings.
Supply Chain Analysis
Export-control restrictions on advanced furnace engineering and pyrolysis optimization technology limit technology transfer to emerging cracker projects in India and Southeast Asia. Feedstock supply concentrates in the United States, Saudi Arabia, and China, with Mont Belvieu ethane hub pricing anchoring global cost benchmarks. Raw material dependencies span naphtha from refinery integration, ethane from natural gas liquids fractionation, and propane for dehydrogenation units. Single-source vulnerability runs through Middle Eastern polyethylene export capacity serving Asian converter networks. Distribution runs through integrated logistics corridors at Channelview, Baytown, and Jubail connecting cracker output to deepwater export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethylene and propylene market rewards operators who command scarce pyrolysis furnace engineering expertise and captive feedstock access. Narrow contractor availability for cracker design and advanced process control integration extends project timelines and inflates capital costs for late entrants.
For Market Incumbents: Pre-empt margin erosion by locking in long-term ethane supply agreements at Mont Belvieu before fractionation capacity bottlenecks intensify. Deploy advanced process control systems integrating machine learning with distributed control architecture to automate yield shifts in response to feedstock volatility. Expand polymer-grade propylene capacity through PDH investments at Corpus Christi or Channelview to capture automotive copolymer premiums. For New Entrants and Emerging Players: Build out chemical recycling feedstock qualification capabilities to supply mass-balance certified pyrolysis oil under emerging certification schemes. Target India's polyethylene deficit at Dahej and Paradip industrial zones where domestic consumption outruns local ethylene capacity. Lead with circular feedstock positioning to bypass established distributor channels and contract directly with sustainability-mandated brand owners. For Investors and Strategic Acquirers: The market sits at a feedstock-reconfiguration phase that favors ethane-captive operators with downstream derivative integration. Long-term viability hinges on exposure to flexible packaging demand growth and carbon-intensity arbitrage between regulatory jurisdictions. Target acquisition candidates with furnace upgrade pathways and IRA 45Q tax credit eligibility for carbon capture retrofits. Watch for MEE carbon intensity benchmark tightening as the inflection signal accelerating Chinese ethane cracker investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethane Supply | Mont Belvieu hub access insulates crackers from NGL fractionation bottlenecks and price spikes. |
| Carbon Capture Retrofit Deployment | Post-combustion capture on cracking furnaces qualifies for IRA 45Q credits at Gulf Coast sites. |
| PDH Capacity Expansion | On-purpose propylene units at Channelview bridge supply gaps from lighter ethane cracking yields. |
| Chemical Recycling Feedstock Qualification | Pyrolysis oil certification under mass-balance schemes opens circular resin premiums with brand owners. |
| Advanced Process Control Integration | Machine learning automation at Texas and Louisiana complexes compresses yield optimization feedback loops. |
Research Methodology
A spread of perspectives from cracker operations managers, downstream polyethylene procurement leads at flexible packaging converters, advanced process control specialists, and carbon accounting consultants converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical conglomerates, and MEE regulatory disclosure documents. Bottom-up capacity modeling triangulated against top-down demand projections from end-use industry absorption rates.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with capacity utilization rates and feedstock cost differentials driving regional competitiveness assessments. Segmentation dimensions spanned product grade tier, end-use industry concentration, technology configuration, and regional production hub clustering. CAGRs derived from trend extrapolation of historical capacity additions correlated with announced project pipelines and regulatory-driven investment redirection. Industry-specific forecast inputs incorporated ethane-naphtha price spread volatility and MEE carbon intensity benchmark implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-affiliated energy majors to accelerate greenfield capacity would shift outcomes substantially. Material shifts in EU Green Deal carbon border adjustment enforcement stringency or MEE dual carbon framework implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Soda Ash Market
Bulk Chemicals
Global Sodium Hydrosulfite Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Global Dicyandiamide Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Isopentane Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market