
 Stacker Crane Market | 2026-2036
Stacker Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Stacker Crane Market Outlook
Modular crane configurations bundled with warehouse management software are realigning procurement patterns across distribution networks. Swisslog Holding AG leverages its software-hardware integration to anchor premium contracts in cold-chain logistics. Daifuku Co., Ltd. sustains manufacturing scale advantages through in-house production of drive assemblies and control systems. Jungheinrich AG competes on electromechanical specialization, particularly in narrow-aisle European installations.
A stacker crane is a rail-guided overhead handling machine engineered to store and retrieve palletized or containerized loads within high-bay racking systems, typically operating at lift heights exceeding 30 meters with positioning accuracy within millimeters. Its primary commercial purpose is maximizing cubic storage density while minimizing labor exposure in temperature-controlled and hazardous material environments. Automated stacker systems lead the product type category by installed base, though semi-automated variants capture margin pools in mid-tier warehousing retrofits. Electromechanical technology dominates new orders due to energy efficiency mandates, while hybrid systems represent the fastest-growing technology segment for heavy-duty ports and automotive sequencing centers.
ISO 12480-1 crane safety standards, EN 528 warehouse equipment directives, and OSHA overhead crane regulations collectively shape product certification requirements and market access barriers across major economies. The EU Machinery Directive and emerging state-level energy codes in the United States are forcing control-system upgrades that favor regenerative drive architectures. Stakeholders must monitor divergence between regional automation standards and assess whether captive service networks or third-party integration partnerships offer superior returns in multi-site deployments.
Market Dynamics
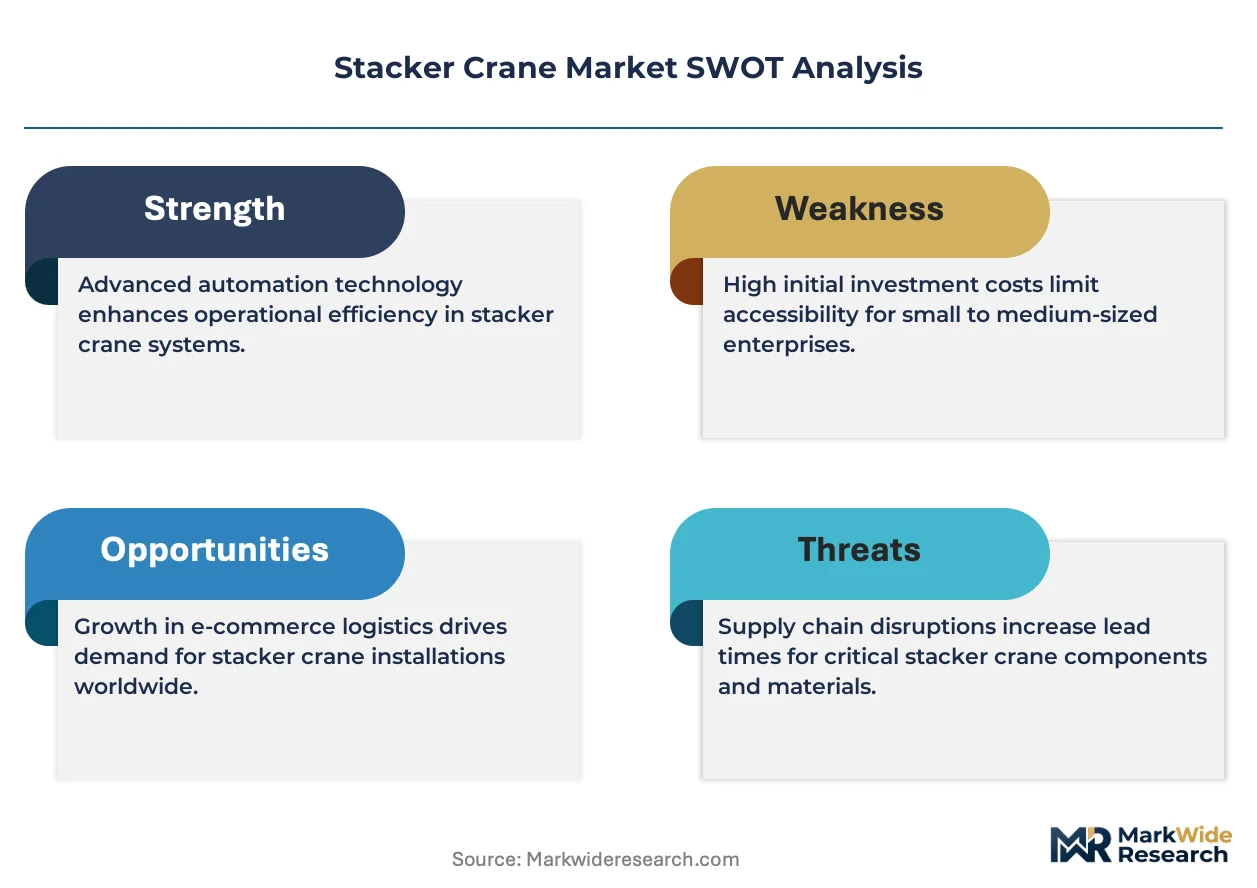
E-commerce fulfillment networks are compressing order cycle times, forcing warehouse operators to prioritize vertical storage density over horizontal expansion. This structural shift favors rail-guided automated retrieval systems capable of millimeter-precision positioning at heights exceeding 30 meters.
Growth Catalysts
- EN 528 warehouse safety directives:European mandates for automated equipment retrofitting are accelerating replacement cycles in legacy distribution centers across Germany and France.
- Cold-chain logistics expansion:Temperature-controlled pharmaceutical and food storage facilities require stacker cranes with specialized sealing and corrosion-resistant drive assemblies.
- Automotive sequencing centers:Just-in-time parts delivery to assembly lines demands high-throughput retrieval systems with sub-minute cycle times.
Market Restraints
- Specialized steel input costs:High-strength rail alloys and precision-machined drive components expose manufacturers to commodity volatility.
- Control system supplier concentration:Proprietary PLC architectures from German and Japanese automation houses create vendor lock-in risks for end-users.
- OSHA overhead crane regulations:US safety compliance timelines extend project commissioning by 4-8 months in multi-site deployments.
Strategic Opportunities
- India's warehouse automation gap:Organized retail and third-party logistics penetration remains below 15 percent, creating first-mover advantage for electromechanical system providers.
- Battery-electric port equipment convergence:Integration of regenerative drives with lithium-ion power systems opens heavy-duty container handling applications previously reserved for hydraulic gantries.
- EU Green Deal industrial incentives:Subsidies for energy-efficient material handling equipment favor regenerative drive architectures over conventional motor-generator sets.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of precision positioning systems requires rare combinations of mechanical, electrical, and software diagnostic skills.
- ISO 12480-1 certification timelines:Third-party safety validation for custom high-bay configurations creates bottlenecks in project delivery schedules.
- Warehouse management system integration:Legacy ERP architectures in mid-tier distribution networks resist real-time data exchange with modern crane control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stacker Crane Market |
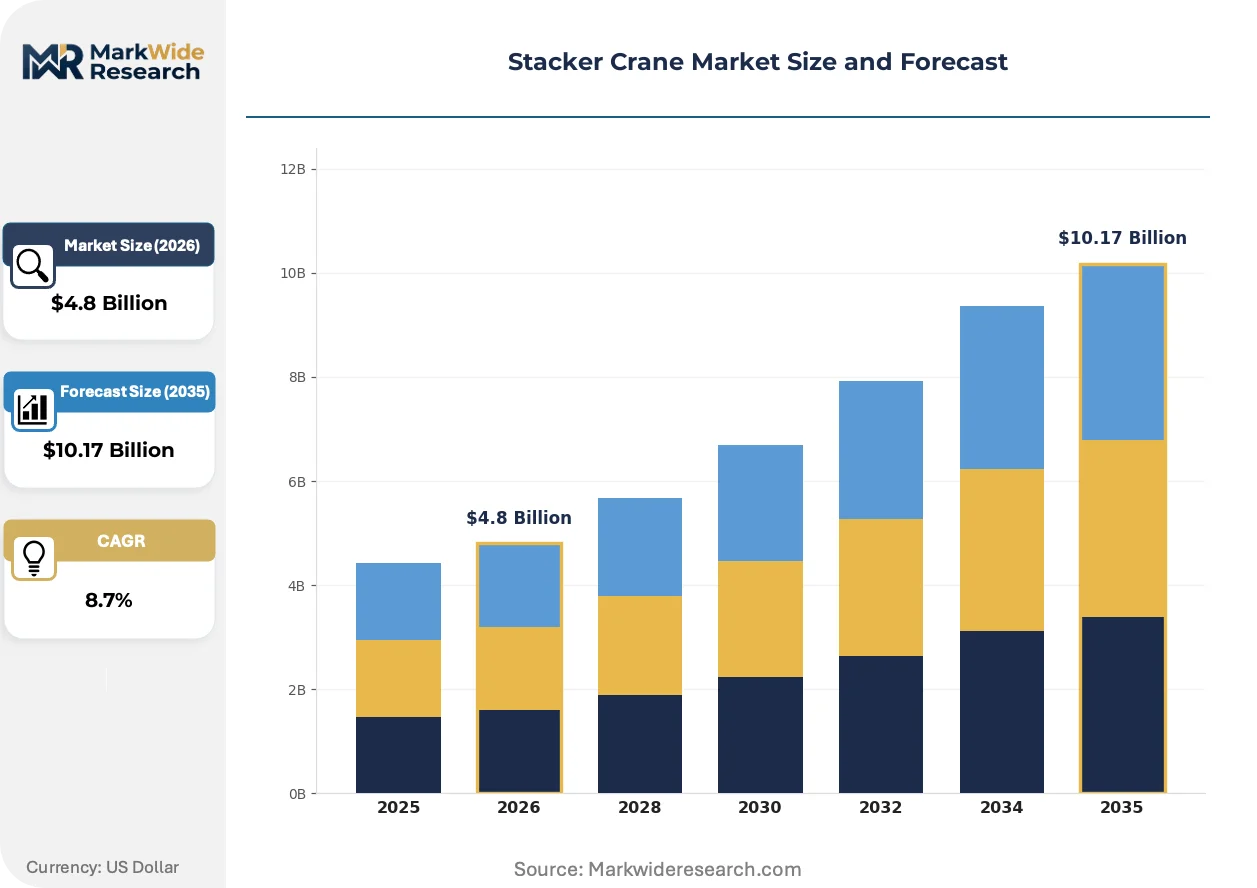
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Stacker, Manual Stacker, Semi-Automated Stacker, Pallet Stacker End User: Warehousing, Manufacturing, Distribution Centers, Retail Technology: Electromechanical, Hydraulic, Pneumatic, Hybrid Capacity: Light Duty, Medium Duty, Heavy Duty, Ultra Heavy Duty |
| Companies Covered | Swisslog Holding AG, Toyota Industries Corporation, Daifuku Co., Ltd., Mecalux S.A., Murata Machinery, Ltd., KION Group AG, Jungheinrich AG, Konecranes, SSI Schaefer Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stacker Crane Market Strategic Shifts
Regenerative energy recovery and predictive maintenance algorithms are displacing conventional drive architectures across new installations. Equipment buyers now prioritize total cost of ownership metrics over upfront capital expenditure.
Regenerative electromechanical drive technology is absorbing kinetic energy from descending loads and returning it to facility power grids. Cold-chain operators in the Netherlands and Denmark are adopting these systems to offset refrigeration power draws. The technology is absorbing maintenance budget allocations previously directed toward brake pad replacement and heat dissipation infrastructure.
REACH chemical safety regulations are restricting lubricant formulations used in rail and wheel assemblies. Equipment manufacturers must reformulate greases and bearing packs to eliminate SVHC substances while maintaining wear resistance. Automotive sequencing facilities in Germany face accelerated compliance deadlines compared to general warehousing applications.
Asset-light leasing structures are displacing traditional capital purchase models for mid-tier warehouse operators. Third-party logistics providers in the United States are bundling crane availability guarantees with racking and software subscriptions. Food and beverage distribution networks show the fastest uptake of performance-based contracts linking payment to retrieval throughput metrics.
Stacker Crane Market Segmentation
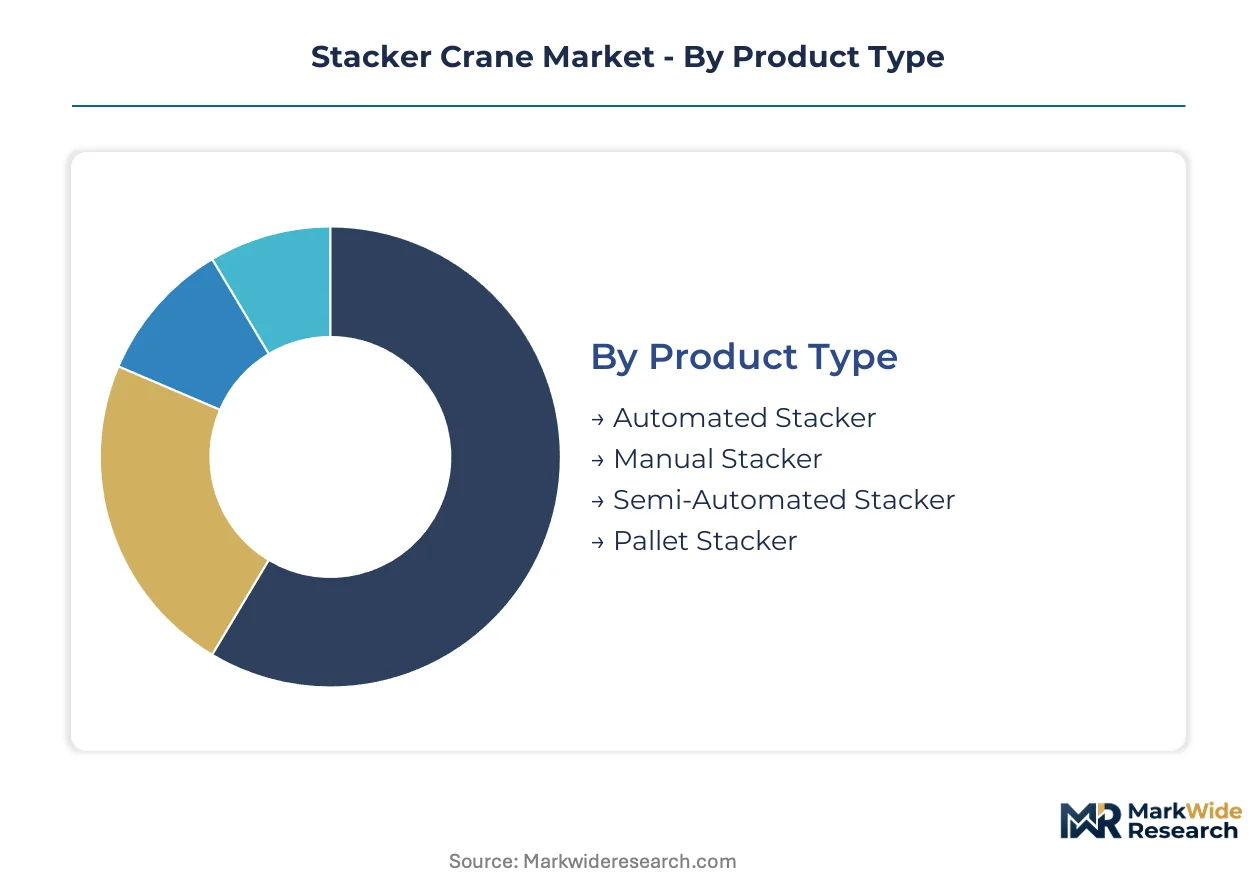
Stacker crane procurement patterns diverge sharply across automation levels, load specifications, and operational environments. Buyers optimize for throughput velocity, cubic density, and integration complexity rather than unit cost alone.
Product Type:
Automation architecture determines capital deployment schedules and labor substitution economics.
- Automated Stacker:Rail-guided systems with programmable logic controllers execute storage and retrieval cycles without operator intervention. E-commerce fulfillment centers in Germany and the United States specify these for high-bay installations exceeding 30 meters, driven by order cycle compression and 24-hour throughput requirements.
- Semi-Automated Stacker:Operator-supervised machines with automated positioning and manual load engagement. Mid-tier warehousing retrofits in France favor this configuration where EN 528 compliance mandates equipment upgrades but full automation capital exceeds operational budgets.
- Manual Stacker:Human-operated walk-behind or ride-on units for low-throughput applications. Small-batch pharmaceutical distribution in Switzerland maintains demand for these units where SKU variety exceeds retrieval velocity.
- Pallet Stacker:Single-pallet handling equipment with telescopic mast configurations. Food and beverage cold-chain facilities in the Netherlands deploy these for temperature-controlled environments where standard unit loads predominate.
Mature deployment sits with Manual Stacker configurations in legacy warehousing. Newer deployment is concentrated in Automated Stacker systems across omnichannel distribution networks.
End User:
Operational intensity and load variability shape specification requirements across facility types.
- Warehousing:High-bay distribution facilities with multi-shift operations. Third-party logistics providers in the United States prioritize vertical storage density over horizontal expansion, compressing rack spacing to 1.5-meter aisles.
- Manufacturing:Just-in-time parts delivery to assembly lines demands sub-minute retrieval cycles. Automotive sequencing centers in Germany specify regenerative drive architectures to offset energy costs from continuous operation.
- Distribution Centers:Cross-dock and fulfillment nodes with high SKU turnover. Cold-chain pharmaceutical facilities require corrosion-resistant drive assemblies and specialized sealing for temperature cycling.
- Retail:Back-of-store and regional replenishment operations. Organized retail penetration in India remains below 15 percent, creating specification gaps between modern trade requirements and existing material handling infrastructure.
Volume concentration rests with Warehousing applications in developed markets. Steepest expansion trajectory appears in Distribution Centers serving temperature-controlled pharmaceutical networks.
Technology:
Energy recovery capabilities and precision positioning differentiate competitive offerings.
- Electromechanical:AC servo motors with regenerative braking dominate new orders. EU Green Deal industrial incentives favor these systems over conventional motor-generator sets in Dutch and Danish cold-chain installations.
- Hybrid:Combines electromechanical precision with hydraulic power for heavy container handling. Port equipment convergence with lithium-ion power systems opens applications previously reserved for hydraulic gantries in automotive sequencing.
- Hydraulic:Fluid power systems for ultra-heavy loads exceeding 50 tons. Steel and paper mills in Japan maintain installed bases where load shock absorption outweighs energy efficiency priorities.
- Pneumatic:Compressed air drives for explosive atmosphere compliance. Chemical handling facilities specify these where electrical spark risks prohibit standard motor configurations.
Technology leadership concentrates with Electromechanical architectures. Fastest technology shift appears in Hybrid systems for heavy-duty port and automotive applications.
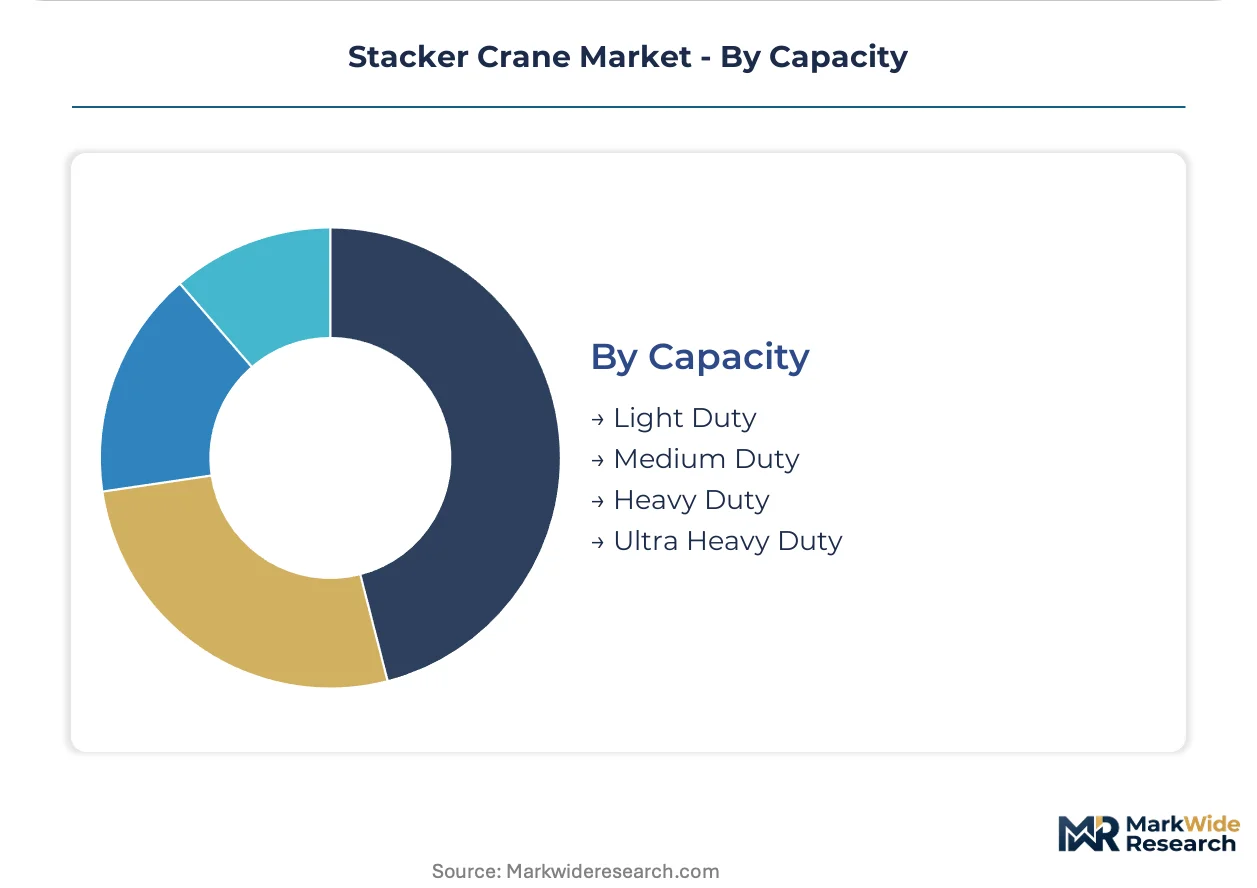
Capacity:
Structural steel requirements and drive component sizing scale non-linearly with rated load.
- Heavy Duty:5-15 ton rated capacity for automotive powertrain components and steel coil handling. German manufacturing clusters specify these for sequencing centers where part weight and retrieval frequency peak simultaneously.
- Medium Duty:1-5 ton range for standard palletized goods. General warehousing in the United States deploys these across multi-site networks with standardized maintenance protocols.
- Light Duty:Under 1 ton for retail backrooms and small-batch operations. Swiss pharmaceutical distribution maintains demand where unit loads remain below 500 kilograms.
- Ultra Heavy Duty:Exceeding 15 tons for port container handling and specialized industrial applications. Chinese port automation projects specify custom rail alloys and reinforced mast structures for these loads.
Revenue concentration aligns with Medium Duty specifications across standardized distribution networks. Specification expansion concentrates in Heavy Duty systems for automotive and metals processing verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany, China, and Japan while consumption spreads across automated warehouse clusters in the United States and European distribution networks. Manufacturing scale advantages favor integrated drive assembly producers in East Asia and electromechanical specialists in Central Europe. End-user demand fragments across cold-chain pharmaceutical facilities, automotive sequencing centers, and e-commerce fulfillment nodes.
United States
E-commerce fulfillment networks in Pennsylvania and Ohio compress order cycle times through high-bay installations exceeding 30 meters. OSHA overhead crane regulations extend project commissioning timelines by 4-8 months in multi-site deployments. Third-party logistics providers in the Chicago and Dallas-Fort Worth metro areas prioritize vertical storage density over horizontal expansion.
Germany
Automotive sequencing centers in Bavaria and Baden-Württemberg demand sub-minute retrieval cycles for just-in-time powertrain components. EN 528 warehouse safety directives accelerate replacement cycles in legacy distribution centers across North Rhine-Westphalia. Cold-chain pharmaceutical facilities near Frankfurt and Hamburg specify corrosion-resistant drive assemblies for temperature cycling environments.
China
Port automation projects in Shanghai and Shenzhen specify custom rail alloys for ultra-heavy container handling exceeding 15 tons. MIIT industrial upgrading programs subsidize electromechanical system adoption in Yangtze River Delta manufacturing clusters. E-commerce fulfillment expansion in Beijing-Tianjin-Hebei drives demand for millimeter-precision positioning systems.
Japan
Steel and paper mills in Chubu maintain hydraulic system installed bases where load shock absorption outweighs energy efficiency priorities. METI energy efficiency mandates push regenerative drive architectures in Kanto logistics facilities. Automotive component sequencing near Nagoya requires high-throughput retrieval systems with continuous operation profiles.
Netherlands
Cold-chain operators in Rotterdam and Venlo adopt regenerative electromechanical drives to offset refrigeration power draws. EU Green Deal industrial incentives favor energy-efficient material handling equipment over conventional motor-generator sets. Food distribution networks across the Randstad show fastest uptake of performance-based contracts linking payment to retrieval throughput.
Stacker Crane Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across automation architecture and electromechanical drive segments. Market structure tilts toward consolidated positions among integrated hardware-software providers and fragmented competition among regional component fabricators. Three archetypes dominate: captive service network operators, in-house drive assembly producers, and warehouse management software integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with M&A activity concentrated in control system and sensor technology acquisitions.
Within the integrated automation tier, Swisslog Holding AG and Daifuku Co., Ltd. occupy anchor positions as exemplars of software-hardware bundling strategies. Jungheinrich AG represents the electromechanical specialization archetype, particularly in narrow-aisle European installations. These three companies illustrate the competitive divergence between conglomerate-scale manufacturing and focused component expertise.
| Leading Market Players |
|---|
| Swisslog Holding AG |
| Toyota Industries Corporation |
| Daifuku Co., Ltd. |
| Mecalux S.A. |
| Murata Machinery, Ltd. |
| KION Group AG |
| Jungheinrich AG |
| Konecranes |
| SSI Schaefer Group GmbH |
| Others |
Value Chain & Pricing Dynamics
Regenerative electromechanical drive adoption simultaneously compresses lifecycle cost economics and concentrates procurement leverage among integrated hardware-software bundlers. European cold-chain operators in the Netherlands and Denmark now specify energy-recovery architectures as baseline requirements, forcing tier-two fabricators to absorb certification costs or exit mid-tier warehousing retrofits.
Pricing Analysis
Margin tightening in semi-automated stacker configurations reflects EN 528 compliance retrofit mandates across French and German legacy distribution centers. Three-tier pricing structure across premium, standard, and economy levels separates Swisslog-style software-hardware bundles from Jungheinrich electromechanical specialists and regional component assemblers. Price differentiation hinges on ISO 12480-1 certification grade and captive service network coverage. Third-party logistics providers in the United States exhibit highest price sensitivity due to asset-light leasing model adoption, while pharmaceutical cold-chain facilities prioritize corrosion-resistant drive assemblies over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese PLC architecture suppliers, creating vendor lock-in risks for end-users specifying proprietary control systems. High-strength rail alloys draw from Chinese and German steel mills, while precision-machined drive components rest on Taiwanese and South Korean machining centers. Supply chain risk centers on REACH chemical safety regulatory restrictions affecting lubricant formulations for rail and wheel assemblies. Distribution runs through captive service networks of integrated automation providers and third-party logistics bundlers in North American and European warehouse clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in stacker crane procurement is concentrating around captive control of drive assembly production and warehouse management software integration. Players securing upstream component fabrication or downstream service network density will capture margin pools eroding from pure equipment vendors.
For Market Incumbents: Acquire sensor technology and predictive maintenance algorithm capabilities to defend against emerging pure-play software entrants. Backward integration into high-strength rail alloy sourcing mitigates commodity volatility exposure from German and Chinese steel suppliers. Expand captive service network density in India's sub-15 percent organized retail penetration zone before first-mover electromechanical specialists establish maintenance protocol standards. For New Entrants and Emerging Players: Capture India's warehouse automation gap through electromechanical system partnerships with domestic third-party logistics providers. Target mid-tier French warehousing retrofits where EN 528 mandates equipment upgrades but full automation capital exceeds operational budgets. Lead with battery-electric port equipment convergence offerings linking regenerative drives to lithium-ion power systems for heavy-duty container handling applications. For Investors and Strategic Acquirers: Exit pathways concentrate in control system and sensor technology acquisitions by integrated automation conglomerates. Long-term viability favors vertically integrated hardware-software bundlers with captive service networks spanning multi-site deployments. Watch for divergence between regional automation standards as inflection indicator for integration partnership versus in-house capability build decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive Assemblies | Daifuku-style in-house production of servo motors and control systems insulates margin from Japanese PLC supplier concentration. |
| Software-Hardware Bundling | Swisslog's warehouse management system integration anchors premium contracts in cold-chain pharmaceutical networks. |
| Regenerative Drive Architecture Certification | EU Green Deal subsidy eligibility in Dutch and Danish facilities favors electromechanical systems over motor-generator sets. |
| Captive Service Network Expansion | Multi-site deployment coverage in Germany and the United States reduces third-party integration dependency and accelerates commissioning timelines. |
| Predictive Maintenance Algorithm Development | Machine learning-enabled positioning diagnostics displace scheduled maintenance contracts and extend equipment lifecycle revenue. |
Study Parameters
Document review covered SEC filings of automation conglomerates, EU machinery directive implementation reports, and OSHA overhead crane enforcement databases, complemented by interviews with warehouse operations directors, maintenance engineers at cold-chain facilities, procurement leads at third-party logistics providers, and electromechanical system integration specialists. Secondary validation drew from EN 528 compliance documentation, ISO 12480-1 certification timelines, and customs data on high-strength rail alloy trade flows. Bottom-up installation base estimates and top-down equipment spending forecasts were triangulated against primary field intelligence.
Unit shipment and revenue estimates across the projection horizon reflect segmentation by automation architecture, load capacity tier, and end-use intensity. The analytical framework modeled electromechanical versus hydraulic technology adoption curves, regenerative drive penetration in cold-chain versus ambient warehousing, and geographic concentration of automotive sequencing center investments. CAGRs were derived from regression analysis of historical installation data against e-commerce fulfillment center capex cycles and EN 528 replacement wave timing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to divergence between regional automation standards and mechatronics technician availability for precision positioning system maintenance. Forecasts reflect assumptions on EU Green Deal subsidy continuity and MIIT industrial upgrading program durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Torque Limiting Couplings Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Cherry Picker Crane Market