
 Asia Pacific Mobile Crane Market | 2026-2036
Asia Pacific Mobile Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Mobile Crane Market Outlook
Market Context
China's GB standards for mobile crane safety and stability is rebalancing the cost-of-entry calculus for manufacturers serving the Asia Pacific region. XCMG leverages its integrated supply base in Xuzhou to dominate domestic procurement cycles while sustaining export competitiveness across Southeast Asia. Liebherr anchors premium positioning through its all-terrain specialization and European-origin engineering credibility in markets like Australia and Japan. Zoomlion Heavy Industry Science & Technology competes aggressively on lift capacity scaling and local production economics within China's domestic infrastructure pipeline.
Technical Definition and Segment Structure
Asia Pacific mobile cranes are self-propelled lifting machines mounted on wheeled or crawler undercarriages, typically featuring telescopic or lattice booms with rated capacities from below 10 tons to above 50 tons, designed for load handling in construction sites, mining operations, port terminals, and energy installations where stationary tower cranes lack mobility. All-terrain and rough terrain configurations command disproportionate margin pools in Australia's remote mining districts and Indonesia's archipelago logistics networks where ground conditions vary unpredictably. Truck mounted units retain volume leadership across India's highway-linked construction corridors, while crawler cranes above 50 tons concentrate in China's offshore wind installation and nuclear energy expansion programs.
Regulatory Framework and Outlook
Japan's METI enforces JIS standards for crane structural integrity and operator certification, while India's BIS mandates indigenous testing protocols for imported lifting equipment, and Australia's state-level occupational safety regulators impose inspection regimes that filter out non-compliant suppliers. These overlapping compliance architectures shape product localization strategies and aftermarket service investments for every manufacturer seeking multi-country presence. Stakeholders must monitor how China's evolving dual carbon goals recalibrate energy sector crane specifications and whether India's PLI scheme for construction machinery expands to include mobile crane components.
Market Dynamics
China's dual carbon goals are forcing crane manufacturers to re-engineer diesel-electric hybrid powertrains while Australia's port infrastructure boom pulls heavy-lift crawler capacity toward coastal mining corridors. This regulatory-energy nexus is compressing product development cycles and redrawing equipment deployment maps across the region.
Growth Catalysts
- India's Smart Cities Mission:Urban infrastructure densification in 100 designated cities is accelerating crawler crane deployment for metro rail and elevated corridor construction.
- Offshore Wind Installation Surge:China's coastal provinces are commissioning 800-ton plus crawler units for turbine foundation placement in the Taiwan Strait and Yellow Sea.
- ASEAN Port Modernization:Indonesia's Patimban and Malaysia's Kuantan port expansions are absorbing all-terrain cranes for container handling and vessel servicing.
Market Restraints
- High-Tensile Steel Volatility:Boom and mast fabrication costs fluctuate with specialty alloy pricing from South Korean and Japanese mills.
- Component Supply Concentration:Hydraulic pump and valve assemblies for units above 300 tons rely heavily on German and Italian subsystem suppliers.
- GB Standard Certification Friction:China's revised crane stability testing protocols extend type-approval timelines for imported machinery by 8-14 months.
Strategic Opportunities
- Vietnam's Manufacturing Relocation Wave:Electronics and automotive factory construction in Bac Ninh and Hai Phong industrial zones is creating demand for 50-150 ton truck-mounted units.
- Telematics-Rental Convergence:IoT-enabled fleet management platforms are allowing equipment lessors to offer utilization-guaranteed contracts.
- Philippines Build! Build! Build! Continuation:The infrastructure program's bridge and dam components require rough-terrain cranes for geotechnically challenging island sites.
Industry Challenges
- Certified Operator Scarcity:Australia's state-level crane licensing regimes face 6-9 month backlogs for high-capacity crawler endorsements.
- Aftermarket Parts Localization:Establishing compliant spare parts stocking in India requires BIS-certified warehousing that adds 15-20% to inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Mobile Crane Market |
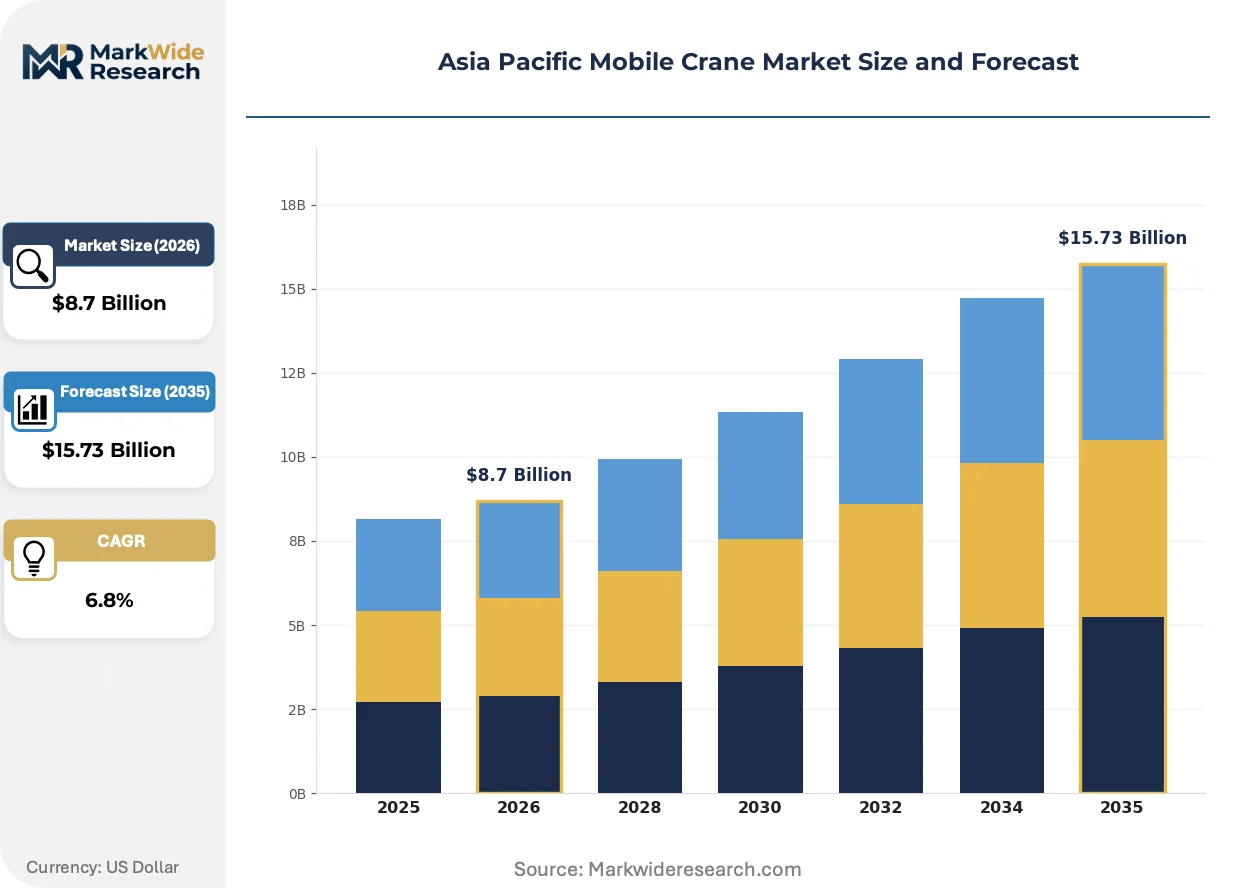
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck Mounted, Crawler, All-Terrain, Rough Terrain Lift Capacity: Below 10 Tons, 10-20 Tons, 20-50 Tons, Above 50 Tons End User: Construction, Mining, Shipping, Energy Distribution Channel: Direct Sales, Distributors, Online Retail, Rental Services |
| Companies Covered | Liebherr, XCMG, Xuzhou Construction Machinery Group, Sumitomo Heavy Industries Construction Cranes, Kobelco Construction Machinery, Zoomlion Heavy Industry Science & Technology, Tadano, Terex Corporation, Sany Heavy Industry, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Mobile Crane Market Strategic Shifts
Electrification and autonomous load sensing are converging to redefine crane operability in emissions-sensitive and labor-constrained environments. Manufacturers are racing to integrate battery-hybrid powertrains with real-time stability monitoring.
Telematics-enabled predictive maintenance is expanding into fleet management contracts across Australia's Pilbara mining hubs. Rio Tinto and BHP are mandating connectivity modules for all new crawler acquisitions to optimize utilization across remote sites. This capability is compressing traditional ownership economics and accelerating rental market penetration.
Japan's METI has tightened JIS B 8813 structural integrity testing for cranes operating in seismic zones. The regulation now requires dynamic load testing at 1.25 times rated capacity for all imported lattice boom units. Australian port operators and nuclear maintenance contractors are absorbing compliance costs through extended procurement cycles and third-party verification services.
Rental-first procurement is displacing direct ownership among mid-tier construction firms in India and Southeast Asia. Equipment lessors like Sany's subsidiary networks are bundling operator training and maintenance into monthly rate structures. This shift is most visible in India's highway construction corridors where project-based contracting favors operational expenditure over capital deployment.
Asia Pacific Mobile Crane Market Segmentation
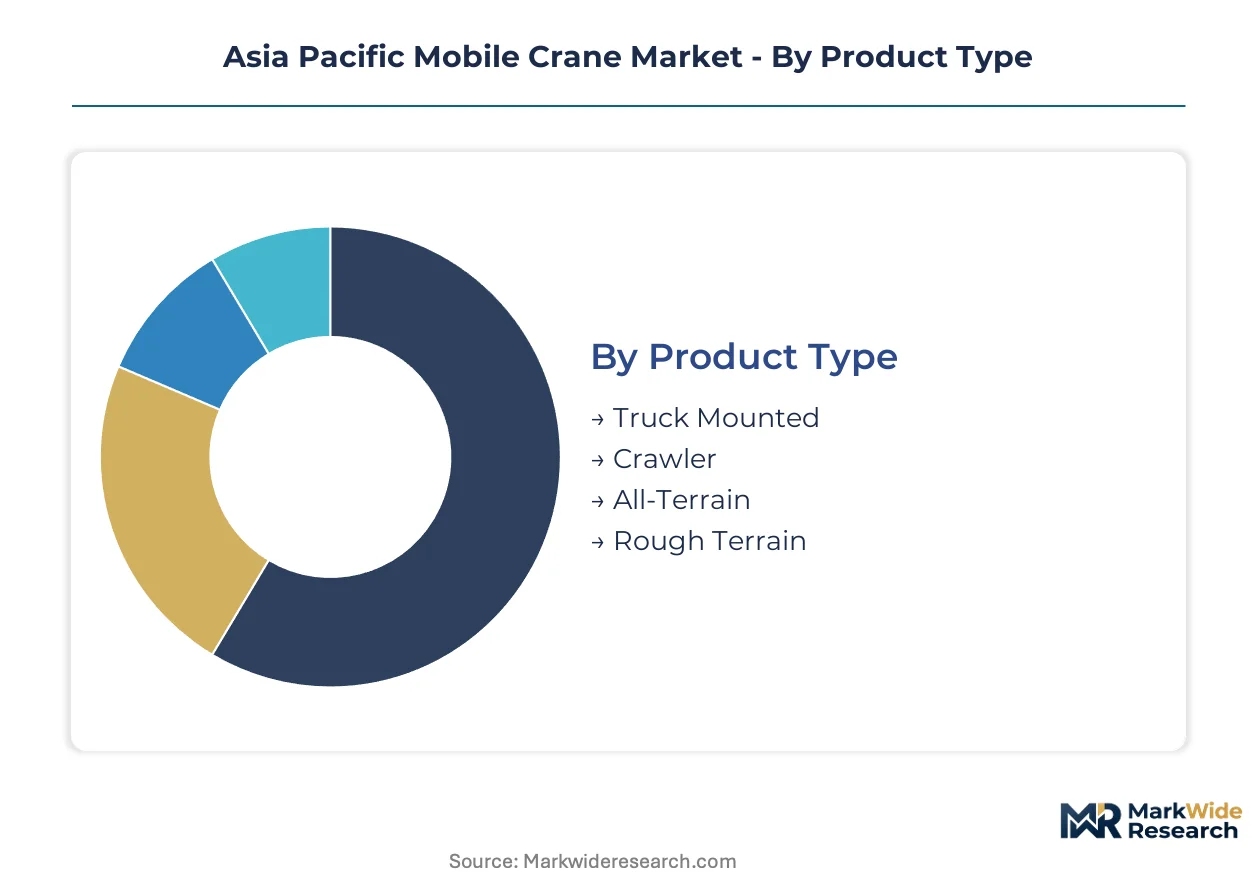
Segmentation in the Asia Pacific mobile crane market reveals how capital deployment, regulatory compliance, and project scale intersect to determine equipment selection. Understanding these divisions clarifies why manufacturers maintain parallel product architectures despite overlapping technical capabilities.
Product Type:
Capital intensity varies sharply across configurations, with crawler and all-terrain units demanding substantially higher upfront investment than truck-mounted alternatives due to specialized undercarriage engineering and stability systems.
- Truck Mounted:These units integrate telescopic booms onto commercial truck chassis, enabling rapid highway transit between urban construction sites. India's highway-linked smart city corridors absorb the highest regional volumes as contractors prioritize mobility over raw lift capacity.
- Crawler:Tracked undercarriages distribute ground pressure across unstable terrain, supporting lattice boom assemblies above 300 tons. Australia's Pilbara mining hubs and China's offshore wind installation zones concentrate demand where ground bearing capacity fluctuates unpredictably.
- All-Terrain:Multi-axle carriers with hydro-pneumatic suspension navigate paved highways and unprepared jobsites without disassembly. Premium positioning in Japan's seismic-sensitive urban cores and Indonesia's archipelago logistics networks justifies elevated acquisition costs.
- Rough Terrain:Compact outrigger-based designs with single-engine powertrains serve geotechnically challenging sites across the Philippines' island infrastructure program and Vietnam's industrial zone construction.
Most installed capacity flows through truck-mounted configurations. Expansion is steepest in crawler units serving energy sector applications.
Lift Capacity:
Application scale dictates capacity selection, with modular construction methods and pre-fabricated component weights driving specification clustering in the 20-50 ton range across Southeast Asian manufacturing facility builds.
- Below 10 Tons:Compact truck-mounted and pick-and-carry designs handle maintenance operations and light commercial construction. Australia's urban maintenance contractors and India's small-scale housing developers represent concentrated demand pockets.
- 10-20 Tons:Mid-range telescopic units dominate general building construction and machinery installation. Vietnam's electronics factory construction wave in Bac Ninh and Hai Phong industrial zones absorbs significant regional volume.
- 20-50 Tons:Highway-capable truck cranes with five-section booms serve bridge construction and precast concrete placement. China's domestic infrastructure pipeline and Indonesia's Trans-Java toll road expansion anchor regional deployment.
- Above 50 Tons:Heavy-lift crawler and all-terrain configurations manage refinery maintenance, nuclear component handling, and offshore wind turbine foundation installation. Australia's port infrastructure boom and China's Taiwan Strait wind farms concentrate ultra-heavy capacity.
The 20-50 ton band carries the highest unit volume. Above-50-ton installations are climbing the fastest as energy transition investments accelerate.
End User:
Customer sophistication and procurement sophistication diverge markedly, with mining and energy sector buyers demanding telematics integration and predictive maintenance bundling that construction contractors rarely specify.
- Construction:General building, highway, and urban infrastructure projects generate baseline demand across all product categories. India's Smart Cities Mission and the Philippines' Build! Build! Build! program sustain the largest regional volume.
- Mining:Remote operations in Australia's Pilbara and Indonesia's coal corridors require ruggedized crawler configurations with 24/7 utilization guarantees. Rio Tinto and BHP mandate connectivity modules for fleet optimization.
- Shipping:Port terminal expansion across Malaysia's Kuantan and Indonesia's Patimban drives demand for all-terrain cranes in vessel servicing and container handling applications.
- Energy:Nuclear maintenance, offshore wind installation, and power plant construction specify the highest-capacity units with certified operator requirements. China's coastal wind provinces and Japan's nuclear restart program concentrate specialized demand.
Construction absorbs the majority of unit shipments. Energy sector procurement is expanding most quickly as dual carbon goals reshape equipment specifications.
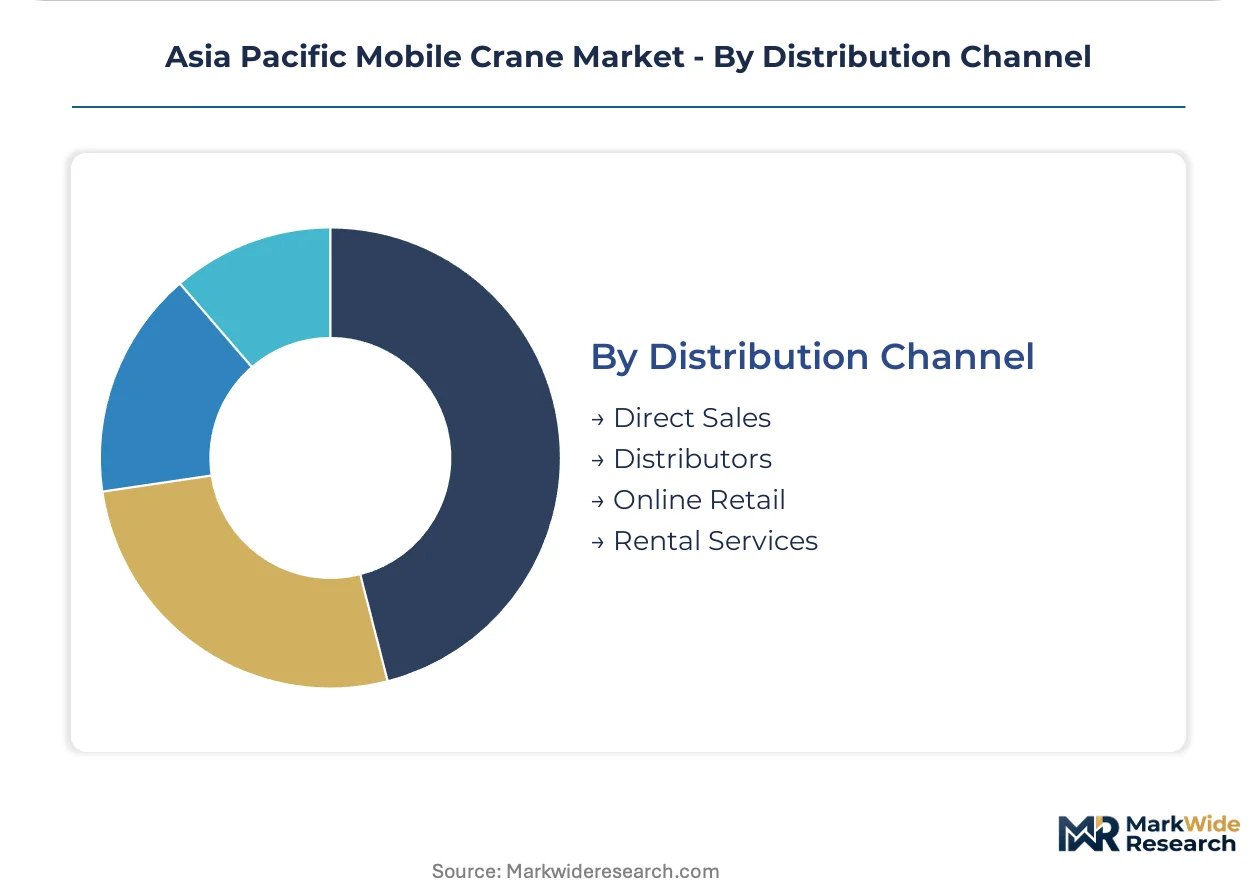
Distribution Channel:
Channel economics reflect customer working capital constraints and project duration patterns, with rental penetration highest where contract-based construction favors operational expenditure structures.
- Direct Sales:Manufacturer-to-end-user transactions dominate large mining and energy accounts with dedicated procurement teams. Australia's major resource operators and China's state-owned construction enterprises prefer direct negotiation for fleet standardization.
- Distributors:Authorized dealer networks provide localized service and spare parts stocking, critical for BIS compliance in India and GB standard certification navigation in China. Inventory carrying costs run 15-20% above direct channels.
- Online Retail:Digital platforms facilitate used equipment trading and spare parts procurement, though complete crane transactions remain limited to smaller capacity classes and established dealer networks.
- Rental Services:Equipment lessors bundle operator training, maintenance, and telematics into monthly rate structures. India's highway construction corridors and Southeast Asian project contracting favor rental-first procurement to preserve capital flexibility.
Direct sales and distributor networks handle the preponderance of heavy-capacity transactions. Rental services are gaining share fastest among mid-tier construction contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile crane manufacturing scaled through Japanese and German engineering traditions before Chinese state-owned enterprises consolidated domestic supply chains in the 2000s. Regional demand now fragments across distinct regulatory and project environments. Each national market imposes unique certification burdens that reshape equipment sourcing patterns.
China
Offshore wind installation in Fujian and Guangdong provinces absorbs 800-ton crawler units for turbine foundation placement. GB standards from SAMR extend type-approval timelines for imported machinery by 8-14 months. Xuzhou's integrated supply cluster anchors domestic procurement while sustaining export competitiveness across Southeast Asia.
India
Metro rail construction in 100 smart cities accelerates crawler crane deployment for elevated corridor segments. BIS mandates indigenous testing protocols that add 15-20% to spare parts inventory carrying costs. Highway-linked construction corridors in Maharashtra and Gujarat favor truck-mounted configurations for rapid site-to-site transit.
Australia
Port infrastructure expansion across Western Australia's Pilbara mining hubs pulls heavy-lift crawler capacity toward coastal terminals. State-level occupational safety regulators impose inspection regimes that filter non-compliant suppliers from fleet procurement. Rio Tinto and BHP mandate telematics connectivity for all new crawler acquisitions.
Japan
Nuclear maintenance restart programs and seismic-sensitive urban cores concentrate demand for all-terrain configurations with certified operator requirements. METI enforces JIS B 8813 structural integrity testing requiring dynamic load verification at 1.25 times rated capacity. Kanto and Kansai industrial zones absorb premium-positioned European-origin engineering.
Indonesia
Patimban port expansion and Trans-Java toll road construction create demand for rough-terrain cranes across geotechnically challenging sites. Archipelago logistics networks favor all-terrain configurations with hydro-pneumatic suspension for unpredictable ground conditions. Java's manufacturing corridor absorbs mid-range truck-mounted units for factory construction.
Asia Pacific Mobile Crane Market Competitive Environment
The competitive structure tilts toward state-backed integrated manufacturers with captive supply chains and premium-tier European specialists with engineering credibility. Domestic Chinese players leverage scale economics and government procurement preference to dominate volume segments. Two strategic archetypes define positioning: vertically integrated national champions and technology-licensed regional assemblers. Capacity expansion and telematics-enabled fleet management partnerships constitute the dominant competitive moves across the region.
Among Germany-based engineering specialists, Liebherr anchors premium positioning through all-terrain specialization. XCMG and Xuzhou Construction Machinery Group exemplify the integrated supply chain archetype with domestic procurement dominance. Zoomlion Heavy Industry Science & Technology occupies a position between scale-driven manufacturing and energy-sector specification climbing. These three represent the structural tension between cost-engineered volume and performance-validated positioning.
| Leading Market Players |
|---|
| Liebherr |
| XCMG |
| Xuzhou Construction Machinery Group |
| Sumitomo Heavy Industries Construction Cranes |
| Kobelco Construction Machinery |
| Zoomlion Heavy Industry Science & Technology |
| Tadano |
| Terex Corporation |
| Sany Heavy Industry |
| Others |
Value Chain & Pricing Dynamics
Certified welder and hydraulic technician concentrations in Xuzhou and Changzhou feed labor-cost differentials that widen pricing-tier spreads between premium European-origin units and domestically produced alternatives across the Asia Pacific mobile crane market.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with certification grade under GB standards and after-sales service bundling as the primary differentiation drivers. Pricing pressure stems from high-tensile steel volatility emanating from South Korean and Japanese specialty mills. Construction contractors in India's highway corridors exhibit the highest price sensitivity, while Australian mining operators prioritize telematics integration over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for hydraulic pump and valve assemblies above 300 tons compel manufacturers to qualify both German and Italian subsystem suppliers simultaneously. Geographic supply concentration centers on China for fabricated boom structures, Japan for precision-engineered components, and South Korea for high-grade steel alloys. Raw material dependencies include specialty alloy plate, precision-machined hydraulic manifolds, and electronic control modules. Single-source vulnerability in German hydraulic component supply poses structural risk. Distribution runs through authorized dealer networks with BIS-certified warehousing in India and GB standard navigation support in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with China's evolving dual carbon goals and GB standard certification timelines driving demand for re-engineered hybrid powertrains and extended type-approval services.
For Market Incumbents: To counter GB standard certification friction extending type-approval timelines by 8-14 months for imported machinery, anchor defensive positioning through captive supply chain control in Xuzhou and accelerated indigenous testing protocol partnerships with India's BIS. Certification investment in seismic-zone JIS B 8813 compliance for Japan's nuclear restart program represents a critical lever for premium-tier retention. For New Entrants and Emerging Players: Enter via Vietnam's Bac Ninh and Hai Phong electronics manufacturing corridors, where 50-150 ton truck-mounted unit demand outpaces established service networks. The Philippines' Build! Build! Build! island infrastructure program offers the most penetrable geography for rough-terrain configurations. Telematics-enabled rental fleet partnerships provide the optimal go-to-market angle for capital-constrained mid-tier contractors. For Investors and Strategic Acquirers: State-backed construction enterprises with integrated supply chains are the most active acquirer in this space, consolidating regional distributor networks to secure GB and BIS certification pathways. Long-term viability hinges on electrification transition readiness and aftermarket service density. Monitor China's offshore wind installation commissioning rates as the critical inflection signal for ultra-heavy crawler capacity deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Powertrain Development | Hybrid diesel-electric systems align with China's dual carbon goals and Australia's emissions-sensitive mining contracts. |
| Telematics Platform Integration | IoT-enabled fleet management satisfies Rio Tinto and BHP connectivity mandates across Pilbara mining hubs. |
| Certification Infrastructure Investment | Indigenous BIS and GB testing capabilities reduce type-approval friction for imported machinery. |
| Aftermarket Service Network Expansion | BIS-certified warehousing in India addresses 15-20% inventory carrying cost premiums. |
| Joint Venture with Local Assemblers | Technology licensing partnerships navigate ASEAN port modernization and Indonesian archipelago logistics requirements. |
Study Parameters
Bottom-up construction and mining sector modeling reconciled against top-down crane manufacturing capacity tracking forms the analytical core of this study. Primary interviews with maintenance directors at Australian mining operations, OEM procurement teams in China's state-owned construction enterprises, aftermarket service heads across Southeast Asian distributor networks, and plant engineers at Japanese nuclear facilities combined with secondary validation from customs trade data, SAMR GB standard filings, BIS certification registries, and IEA offshore wind project databases. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map lift capacity specifications to end-use application intensity across the projection horizon. Segmentation dimensions include product type configuration, lift capacity tier, end-user industry vertical, and distribution channel structure. CAGRs derive from equipment deployment trajectories in India's smart city corridors, China's Taiwan Strait wind farms, and Australia's port infrastructure expansion. Industry-specific forecast inputs incorporate high-tensile steel pricing indices and certified operator availability backlogs.
Inputs from SAMR certification timelines and BIS testing protocol disclosures were available through the study window; gaps in real-time fleet utilization data from telematics platforms introduce uncertainty bands around rental market penetration assumptions. Deviation in China's offshore wind installation commissioning rates or India's PLI scheme expansion into construction machinery components would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Loader Bucket Attachments Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Explosion Proof Crane Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
Wood Chipper Market