
 Clinching Machines Market | 2026-2036
Clinching Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Clinching Machines Market Outlook
Distributor networks across industrial automation are reshaping how clinching equipment reaches metal fabricators and automotive Tier-1 suppliers. TOX Pressotechnik leverages direct technical service centers to sustain specification influence with German automotive OEMs. Bollhoff Group anchors its position through application engineering teams embedded in customer plants. Eckold AG competes via specialized portable clinching systems for on-site repair and custom fabrication workflows.
Clinching machines join sheet metal layers through localized cold-forming without fasteners, heat, or consumables, typically achieving joint strengths of 500-2000 N/mm depending on material thickness and die geometry. The process eliminates thermal distortion and spatter associated with resistance welding, making it essential for aluminum and coated steel assemblies in lightweight vehicle structures. Stationary machines dominate installed base volumes in high-throughput automotive body shops where cycle time requirements under six seconds per joint predominate. Electric technology captures expanding share as servo-driven systems deliver programmable force-displacement curves with energy consumption below comparable pneumatic units. Automated machines represent the fastest-growing configuration category as integrators embed clinching stations into robotic cells for electric vehicle platform production.
EPA emissions standards and OSHA workplace exposure limits push manufacturers toward mechanical joining methods that eliminate weld fume ventilation requirements. CE marking under the EU Machinery Directive and ISO 15654 joint quality specifications shape product design and market access validation for European and export-bound suppliers. Stakeholders must monitor how battery enclosure sealing requirements and multi-material bonding specifications redirect clinching die development priorities across transportation electrification supply chains.
Market Dynamics
Electric servo clinching technology is collapsing the installed base advantage of pneumatic systems across automotive body-in-white production, forcing equipment suppliers to restructure R&D budgets and field service organizations around programmable force-displacement architectures.
Growth Catalysts
- REACH-compliant lubrication mandates:ECHA restrictions on hexavalent chromium coatings in metal forming fluids push OEMs toward dry clinching processes that eliminate chemical surface preparation entirely.
- Aluminum-intensive vehicle architectures:Automotive OEMs in Germany and Japan are expanding clinching capacity to replace resistance spot welding in multi-material electric vehicle platforms where thermal distortion must be minimized.
- OSHA weld fume exposure limits:Tighter permissible exposure levels for manganese and hexavalent chromium drive fabricators toward mechanical joining methods that eliminate ventilation infrastructure and respiratory protection programs.
Market Restraints
- High-precision die manufacturing concentration:Specialized tool steel suppliers in Bavaria and Baden-Württemberg control critical geometries for aluminum clinching, creating single-source vulnerability for Tier-1 integrators.
- Copper and rare earth magnet cost volatility:Electric servo motors depend on neodymium-iron-boron magnets and wound copper rotors, exposing machine builders to commodity swings that compress margin on fixed-price contracts.
- Structural adhesive substitution threat:Two-part epoxy and acrylic bonding systems from chemical suppliers achieve comparable shear strength on dissimilar metal joints without capital equipment requirements.
Strategic Opportunities
- Battery enclosure sealing applications:Electric vehicle manufacturers in Guangdong province require clinching stations that integrate with laser welding cells for aluminum tray assembly, creating demand for hybrid joining workstations.
- Portable on-site repair systems:Custom fabrication shops and maintenance contractors seek handheld electric clinching tools for field service of HVAC ductwork and architectural metalwork without factory infrastructure.
- EU Green Deal industrial decarbonization incentives:Member state recovery funds prioritize capital equipment that eliminates process heat and consumables, directing public procurement toward cold-forming joining technologies.
Industry Challenges
- Multi-material joint simulation expertise:Finite element modeling of aluminum-to-steel and aluminum-to-magnesium clinching requires specialized material science knowledge that resides primarily with German automotive OEM engineering centers.
- ISO 15654 certification timelines:Third-party validation of joint quality specifications for new die geometries and material combinations extends product development cycles by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinching Machines Market |
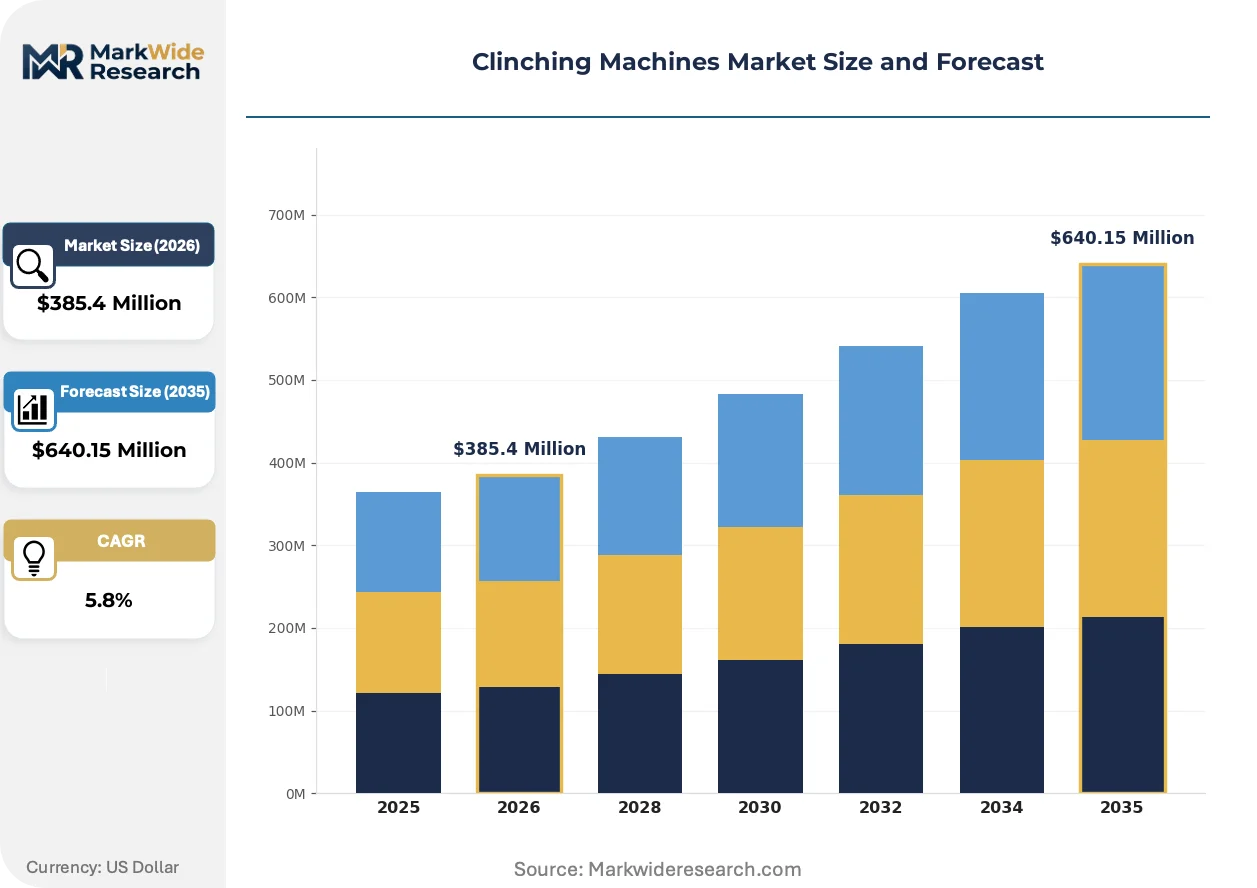
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Machines, Stationary Machines, Automated Machines, Manual Machines Application: Automotive Assembly, Aerospace Manufacturing, Electronics Production, Metal Fabrication End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Small Manufacturers Technology: Pneumatic, Hydraulic, Electric, Hybrid |
| Companies Covered | TOX Pressotechnik, Bollhoff Group, Eckold AG, KUKA AG, Atlas Copco, BalTec Corporation, BTM Company, Norlok Technology Inc., Wuxi Novo Automation Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinching Machines Market Strategic Shifts
Process electrification and digital thread integration are collapsing the traditional boundaries between joining equipment and quality assurance systems, embedding real-time force monitoring directly into production control architectures.
Electric servo clinching is collapsing the performance gap between mechanical joining and adaptive welding through programmable ram velocity profiles that adjust mid-cycle for material thickness variation. Automotive OEMs in Michigan and Bavaria are specifying these systems for aluminum door ring and floor pan applications where joint consistency determines crashworthiness ratings. The technology is collapsing equipment lifecycle expectations as predictive maintenance algorithms replace scheduled downtime intervals.
EPA emissions standards under the Clean Air Act are compressing the viable process window for resistance welding in metal fabrication facilities, accelerating capital redeployment toward zero-emission joining methods. The regulatory pressure is forcing body shop engineers to validate clinching for structural joints previously reserved for spot welding, particularly in coated steel applications where weld spatter contamination poses quality risks. Tier-1 suppliers in Ontario and South Carolina are responding by installing hybrid cells that retain welding capability while expanding clinching capacity for aluminum-intensive subassemblies.
Specification influence is migrating from equipment distributors to embedded application engineering teams that co-develop joining processes during vehicle platform design phases. Bollhoff Group and TOX Pressotechnik are displacing traditional sales channels by placing technical staff inside customer plants to optimize die selection and process parameters. This pattern concentrates most visibly in Germany where automotive OEMs consolidate supplier panels and demand direct accountability for joint performance validation.
Clinching Machines Market Segmentation
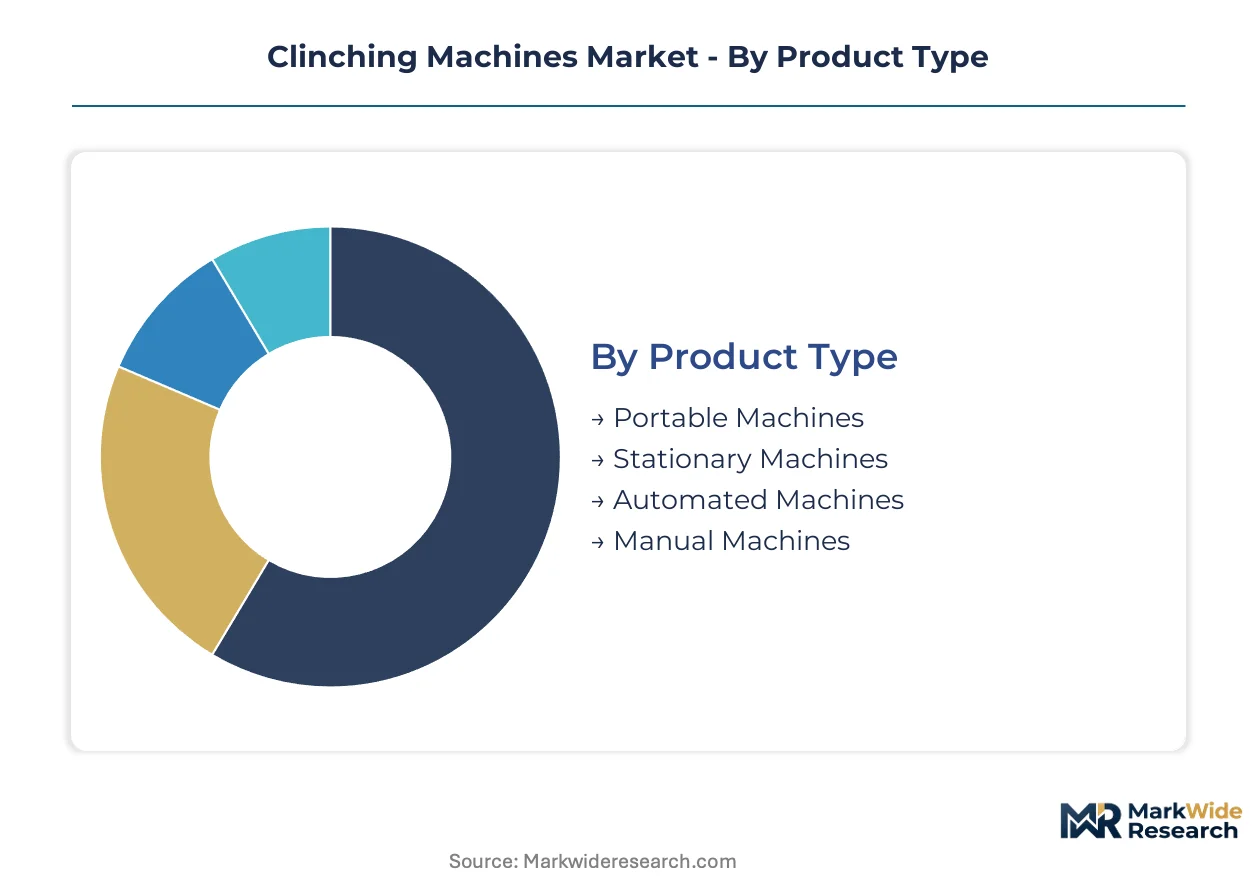
Clinching machine procurement patterns diverge sharply by operational tempo, with high-throughput automotive lines demanding sub-six-second cycle architectures while field service applications prioritize portability over speed. Understanding these velocity-driven segment boundaries enables suppliers to align R&D spending with actual utilization profiles rather than nominal equipment categories.
Product Type:
Stationary machines turn over slowest in installed base terms, often remaining in service for fifteen-plus years, while portable and automated configurations refresh on compressed timelines driven by battery chemistry advances and robotic integration cycles respectively.
- Stationary Machines:Floor-mounted units with fixed C-frame architectures dominate high-volume automotive body-in-white installations. Bavarian and Michigan OEMs specify these for aluminum door ring and floor pan production where joint consistency determines crashworthiness ratings. Cycle time requirements under six seconds per joint lock in pneumatic and early electric generations for decade-long depreciation schedules.
- Automated Machines:Robotic cell-integrated clinching stations with programmable force-displacement curves capture expanding share in Guangdong electric vehicle battery tray assembly. These systems integrate with laser welding cells for hybrid joining workstations, collapsing the boundary between mechanical joining and adaptive welding through real-time quality feedback loops.
- Portable Machines:Handheld electric units serve HVAC ductwork contractors and architectural metalwork maintenance crews requiring on-site repair capability without factory infrastructure. Battery-powered variants from Eckold AG address field service workflows.
- Manual Machines:Lever-actuated benchtop units serve small fabrication shops with intermittent production schedules and minimal capital budgets. These systems handle prototype runs and custom one-off assemblies.
Stationary machines anchor the volume base while automated configurations gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive automotive specifications from price-sensitive metal fabrication procurement, with aerospace and electronics occupying intermediate positions defined by certification burden rather than throughput scale.
- Automotive Assembly:Body-in-white production for aluminum-intensive electric vehicle platforms drives specification of electric servo clinching with programmable ram velocity. German and Japanese OEMs are expanding clinching capacity to replace resistance spot welding where thermal distortion must be minimized.
- Metal Fabrication:Job shops and contract manufacturers serving architectural and industrial equipment markets prioritize equipment flexibility over single-purpose speed. These buyers respond to OSHA weld fume exposure limits by eliminating ventilation infrastructure.
- Aerospace Manufacturing:Aircraft structural assemblies require specialized die geometries for aluminum-to-titanium joints, with ISO 15654 certification timelines extending product validation cycles. Tier-1 aerostructures suppliers in Germany and France drive demand.
- Electronics Production:Miniaturized clinching systems join thin-gauge metal enclosures for power electronics and battery management systems. Guangdong province concentration aligns with electric vehicle supply chain clustering.
Automotive assembly commands the premium tier while metal fabrication represents the broadest addressable base.
End User:
Customer type determines specification authority, with OEM engineering centers dictating process parameters that cascade through Tier-1 supplier equipment procurement.
- OEMs:Vehicle manufacturers in Germany, Japan, and Michigan retain direct specification control over joining processes during platform design phases. TOX Pressotechnik and Bollhoff Group embed application engineering teams inside these customer plants.
- Tier-1 Suppliers:Automotive subsystem integrators in Ontario and South Carolina install hybrid cells retaining welding capability while expanding clinching capacity for aluminum-intensive subassemblies. These buyers respond to OEM process mandates while optimizing capital deployment.
- Aftermarket Providers:Maintenance contractors and collision repair networks seek portable clinching systems compatible with existing shop air infrastructure. These users prioritize equipment mobility and rapid setup.
- Small Manufacturers:Independent fabrication shops with limited technical staff favor manual or entry-level pneumatic systems with simplified die change procedures. Price sensitivity dominates procurement decisions.
OEMs anchor specification influence while Tier-1 suppliers represent the largest equipment procurement volume.
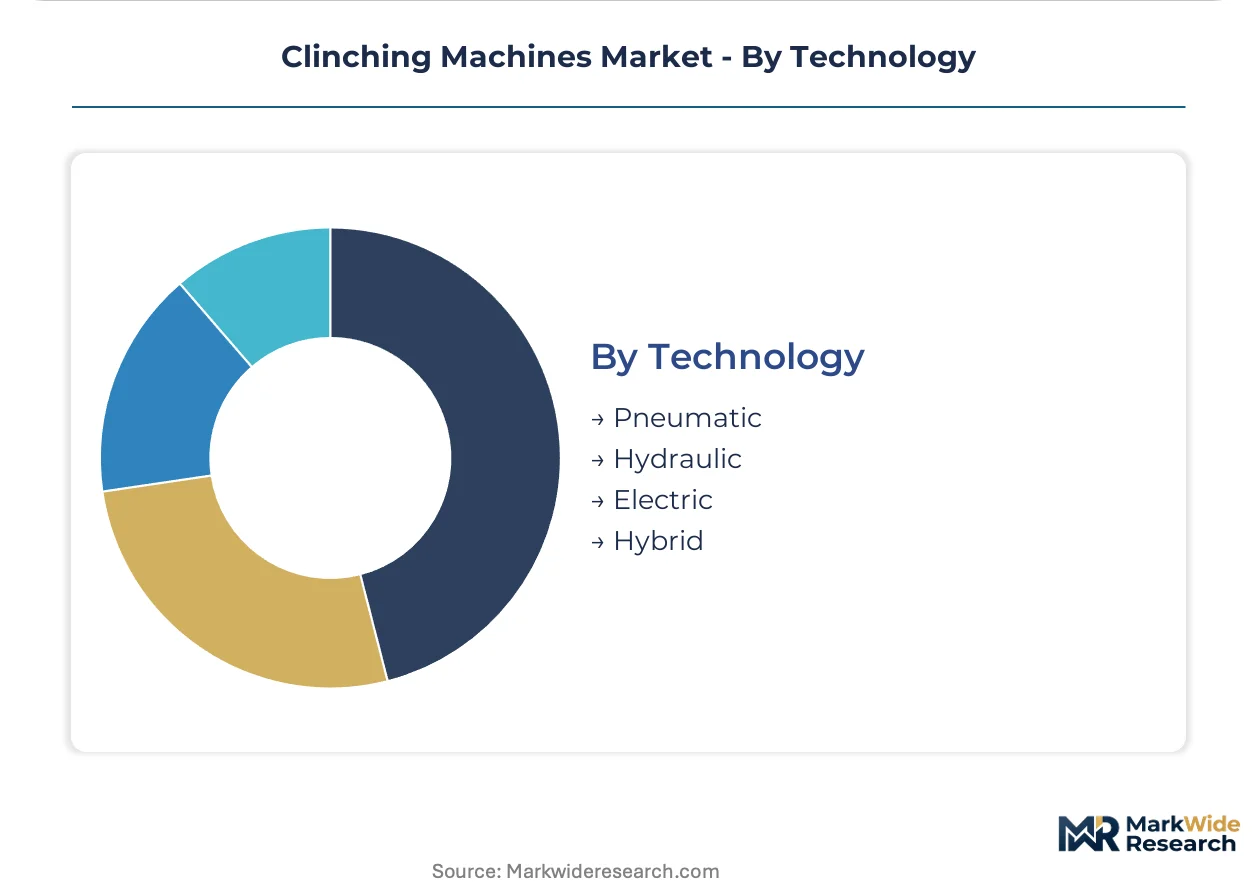
Technology:
Maturity gradients separate legacy pneumatic installed bases from emerging electric architectures, with hydraulic systems occupying declining niches and hybrid configurations capturing transitional applications.
- Electric:Servo-driven systems with programmable force-displacement curves deliver energy consumption below comparable pneumatic units. These systems are displacing compressed-air infrastructure in Michigan and Bavarian automotive plants.
- Pneumatic:Compressed-air systems retain installed base dominance in legacy automotive facilities where infrastructure amortization extends replacement cycles. These machines face margin pressure from rising electricity costs and maintenance intervals.
- Hydraulic:High-force systems for thick-gauge steel applications persist in heavy truck and industrial equipment manufacturing. Market share contracts as electric servo torque density improves.
- Hybrid:Combined pneumatic-electric architectures address transitional applications requiring force profiles beyond electric servo capacity without full hydraulic infrastructure. These systems serve specialty vehicle and off-highway equipment producers.
Pneumatic technology retains the largest installed base while electric systems climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs command premium pricing for aluminum clinching specifications, while Guangdong manufacturers compete on equipment throughput metrics for battery tray assembly contracts.
Germany
Bavarian OEMs specify electric servo clinching for aluminum-intensive electric vehicle platforms, displacing resistance spot welding in door ring and floor pan production. ECHA REACH restrictions on hexavalent chromium coatings redirect procurement toward dry clinching processes. Stuttgart and Munich engineering centers embed application teams from equipment suppliers during platform design phases.
United States
Michigan body shops install hybrid cells retaining welding capability while expanding clinching capacity for aluminum subassemblies. EPA Clean Air Act emissions standards compress the viable process window for resistance welding, accelerating capital redeployment. Detroit-area Tier-1 suppliers respond to OEM mandates while optimizing capital deployment across Ontario and South Carolina facilities.
China
Guangdong province electric vehicle manufacturers require clinching stations integrated with laser welding cells for aluminum battery tray assembly. MIIT industrial policy prioritizes capital equipment that eliminates process heat and consumables in manufacturing upgrades. Shenzhen and Dongguan clusters drive demand for automated robotic cell configurations with real-time quality feedback.
Japan
Automotive OEMs expand clinching capacity to replace spot welding in multi-material platforms where thermal distortion must be minimized. METI energy efficiency standards favor electric servo systems with programmable force-displacement curves over pneumatic infrastructure. Nagoya and Tokyo engineering centers concentrate finite element modeling expertise for aluminum-to-steel joint simulation.
Canada
Ontario Tier-1 suppliers install hybrid joining cells to serve aluminum-intensive vehicle programs from Detroit-based OEMs. Health Canada workplace exposure guidelines for manganese and hexavalent chromium accelerate adoption of mechanical joining methods. Windsor and Oshawa industrial corridors concentrate equipment procurement for cross-border automotive supply chains.
Clinching Machines Market Competitive Environment
Integrated automation suppliers and specialized joining equipment manufacturers split the market based on specification authority versus application engineering depth. The vendor base concentrates around German and North American engineering centers where automotive OEMs retain direct process control. Three archetypes dominate: full-line automation integrators with clinching modules, dedicated joining technology specialists with embedded service teams, and portable equipment fabricators serving field service workflows. Competitive moves center on co-development partnerships during vehicle platform design and geographic expansion through technical service center establishment.
Within the specialized joining tier, TOX Pressotechnik and Bollhoff Group exemplify the embedded application engineering model, while Eckold AG occupies a position among portable system specialists. TOX Pressotechnik represents the direct technical service center approach with specification influence at German automotive OEMs. Bollhoff Group exemplifies the plant-embedded team archetype for process co-development during platform design. Eckold AG anchors the handheld electric segment for on-site repair and custom fabrication workflows without factory infrastructure.
| Leading Market Players |
|---|
| TOX Pressotechnik |
| Bollhoff Group |
| Eckold AG |
| KUKA AG |
| Atlas Copco |
| BalTec Corporation |
| BTM Company |
| Norlok Technology Inc. |
| Wuxi Novo Automation Technology |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in specialized tool steel forging for aluminum clinching dies concentrates pricing power with Bavarian and Baden-Württemberg suppliers, forcing machine builders to absorb cost volatility or pass through surcharges to automotive OEMs on fixed-price contracts. This utilization squeeze tightens margins across electric servo configurations while reinforcing long-term supply agreements as the dominant procurement posture.
Pricing Analysis
The customization-premium spread separates configured-to-order electric servo systems from standard pneumatic units by roughly thirty to fifty percent, with programmable force-displacement architectures commanding project-based pricing tied to joint validation timelines. Price differentiation hinges on ISO 15654 certification tier and embedded application engineering depth, with German automotive OEMs showing lowest sensitivity and small metal fabrication shops exhibiting acute pressure response. Pricing pressure stems from rare earth magnet cost volatility compressing margin on fixed-price electric servo contracts. Tier-1 suppliers in Ontario and South Carolina occupy the mid-sensitivity band, balancing OEM mandates against capital deployment efficiency.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning as electric vehicle battery tray assembly migrates toward Guangdong province. Geographic supply concentration centers on Germany for precision die geometries, China for rare earth magnet processing, and Japan for high-torque servo motor components. Raw material dependencies draw from neodymium-iron-boron magnet feedstock, specialized tool steel alloys, and wound copper rotor stock. Single-source vulnerability persists for aluminum clinching die geometries controlled by Bavarian suppliers. Distribution runs through embedded application engineering teams rather than traditional distributor networks, with TOX Pressotechnik and Bollhoff Group maintaining direct technical service centers at customer plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance contracts and die refurbishment programs expand faster than hardware shipments, converting capital equipment sales into recurring revenue streams anchored by joint performance guarantees.
For Market Incumbents: Entrench specification influence by embedding application engineering teams inside German and Japanese OEM plants during platform design phases, mirroring the Bollhoff Group and TOX Pressotechnik model. Deepen backward integration into specialized tool steel forging to mitigate single-source vulnerability from Bavarian suppliers. Prioritize certification investment for ISO 15654 validation of new aluminum-to-magnesium die geometries ahead of structural adhesive substitution threats. For New Entrants and Emerging Players: Establish a beachhead in portable electric clinching systems for HVAC ductwork contractors and architectural metalwork maintenance crews, where factory infrastructure requirements exclude incumbent automated solutions. Target Guangdong battery enclosure sealing applications as the most penetrable segment, where hybrid joining workstations integrating clinching with laser welding cells remain undersupplied. Pursue a go-to-market angle anchored by battery-powered handheld units compatible with existing field service workflows. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among embedded application engineering specialists with multi-year service contracts tied to OEM platform cycles, suggesting superior cash flow quality relative to pure equipment vendors. Long-term viability over a five-to-ten year horizon favors suppliers with demonstrated ISO 15654 certification velocity and direct technical service center density in automotive engineering corridors. Acquisition targets should display die co-development capabilities with German OEMs. The signal to watch is electric vehicle platform standardization announcements from Michigan and Bavarian engineering centers, which trigger clinching capacity investment waves.| Strategic Initiative | Industry Significance |
|---|---|
| Die Co-Development Partnerships | Locks in specification influence during German OEM platform design phases. |
| Electric Servo R&D Expansion | Addresses METI energy efficiency standards favoring programmable force-displacement systems. |
| Technical Service Center Buildout | Replicates Bollhoff Group's embedded team model in Guangdong and Michigan corridors. |
| Predictive Maintenance Platform Launch | Converts hardware sales into recurring revenue via algorithm-driven die replacement scheduling. |
| REACH-Compliant Dry Clinching Certification | Captures ECHA-mandated procurement shifts away from hexavalent chromium surface preparation. |
Study Parameters
Operator-level perspectives from maintenance directors at Tier-1 automotive suppliers, OEM platform engineers in Bavaria and Michigan, and aftermarket service heads at portable equipment distributors anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from SEC filings of industrial automation suppliers, MIIT industrial policy disclosures, and ECHA REACH restriction updates. Bottom-up equipment shipment analysis triangulated against top-down automotive production forecasts across the analysis window.
Scenario-bracketing around aluminum-intensive vehicle architecture adoption rates and electric servo penetration timelines structured the analytical framework. Segmentation dimensions modeled include product type, application, technology, and end user, with regional production cluster as an industry-specific overlay. CAGRs derived from curve-fitting against historical clinching equipment deployment patterns and OEM capital expenditure disclosures. Forecast inputs incorporated battery enclosure sealing requirements and multi-material joint simulation expertise concentration.
Sensitivities concentrate around rare earth magnet price volatility, ISO 15654 certification timeline extensions, and structural adhesive shear strength improvements. Forecasts reflect assumptions about automotive OEM platform standardization and ECHA enforcement intensity without claiming certainty. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Global Forklift Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Pipe Jacking Machines Market