
 Eye and Eye Turnbuckle Market | 2026-2036
Eye and Eye Turnbuckle Market Size, Share, and Industry Trends Forecast 2026-2036
Eye and Eye Turnbuckle Market Analytics
The EU Green Deal's sustainable maritime infrastructure mandates is pivoting procurement specifications across European shipyards toward low-carbon rigging solutions. The Crosby Group LLC leverages its forged steel expertise to dominate North American heavy-lift channels. Peerless Industrial Group anchors its position through backward integration into heat-treatment facilities. Suncor Stainless, Inc. specializes in marine-grade 316 stainless turnbuckles for saltwater environments.
An eye and eye turnbuckle is a tensioning device with internally threaded barrels and eye-ended end fittings that rotate to extend or retract, typically manufactured through hot forging, CNC machining, and electropolishing to achieve precise load ratings. Its primary purpose is to adjust cable, rod, and chain tension in structural rigging systems. Stainless steel variants command premium positioning due to corrosion resistance demands in marine applications, while construction-sector procurement favors medium and large sizes for scaffolding and structural bracing. The contractor end-user segment sustains the highest volume throughput, though shipbuilders generate superior per-unit margins through specification-grade certification requirements.
OSHA scaffold safety standards, the EU Machinery Directive's CE marking requirements, and China's GB/T standards for lifting accessories collectively shape product design, testing protocols, and market access conditions across major supply corridors. ASTM A489 and ISO 2415 provide the dimensional and proof-load benchmarks that differentiate specification-grade from commodity turnbuckle supply. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their cascading impact on alloy sourcing economics and regional manufacturing competitiveness.
Market Dynamics
Marine infrastructure corrosion mandates are forcing material substitution toward duplex stainless grades, compressing commodity carbon steel volumes while expanding specification-grade procurement channels across shipbuilding and offshore energy sectors.
Growth Catalysts
- EU Green Deal maritime infrastructure mandates:European shipyards now specify low-carbon rigging hardware with documented lifecycle emissions, accelerating demand for electropolished stainless turnbuckles in port modernization projects.
- Yangtze River Delta port expansion:China's terminal automation programs require precision-tensioned cable systems, driving specification-grade eye and eye turnbuckle procurement for container crane rigging.
- OSHA scaffold safety standard revisions:US construction contractors face tightened fall-protection hardware requirements, expanding medium and large turnbuckle deployment for structural bracing systems.
Market Restraints
- Nickel and molybdenum price volatility:Alloy surcharge fluctuations compress margins on marine-grade 316 stainless variants, forcing producers to index-contract raw material exposure.
- Forging capacity concentration in East Asia:Hot-forming equipment for large turnbuckle bodies clusters in China's Hebei and Shandong provinces, creating single-source vulnerability for specification-grade supply.
- Carbon steel substitution ceiling:Coastal and chemical-environment applications hit corrosion-performance limits with zinc-plated carbon grades, blocking downward material migration.
Strategic Opportunities
- India port-led development corridors:Sagarmala program investments in Vizhinjam, Mundra, and Paradip terminals create specification-grade hardware demand for new heavy-lift infrastructure.
- CE marking convergence with ISO 2415:Unified testing protocols reduce dual-certification costs, opening EU market access for mid-tier Asian producers with ISO-accredited laboratories.
- Digital load-monitoring integration:Embedded strain-sensor turnbuckle assemblies enable predictive maintenance contracts, shifting revenue from hardware sales to subscription-based tension monitoring services.
Industry Challenges
- Heat-treatment technician scarcity:Controlled quenching and tempering of forged end fittings requires specialized metallurgical expertise concentrated in aging workforces across European and North American forging operations.
- CE technical documentation timelines:EU Machinery Directive compliance files demand extensive design-dossier preparation, extending product launch cycles by four to six months for new turnbuckle specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye and Eye Turnbuckle Market |
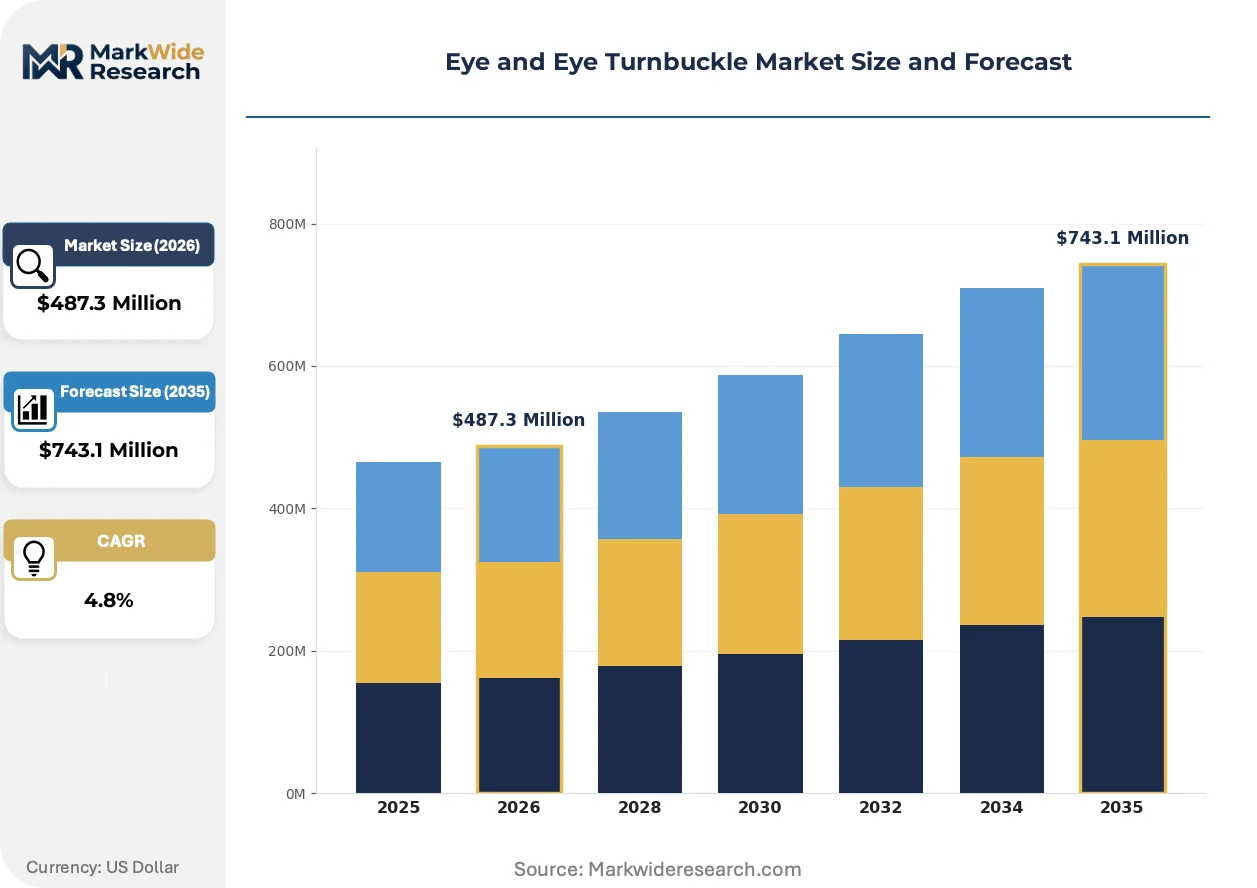
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Bronze, Nylon, Alloy Application: Construction, Marine, Agriculture, Industrial Size: Small, Medium, Large, Extra Large End User: Contractors, Shipbuilders, Farmers, Manufacturers |
| Companies Covered | The Crosby Group LLC, Peerless Industrial Group, Suncor Stainless, Inc., Chicago Hardware & Fixture Company, Qingdao Dexing Rigging Co., Ltd., Van Beest B.V., Columbus McKinnon, UU LIFTING, Petersen Stainless Rigging Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye and Eye Turnbuckle Market Evolving Landscape
Material science advances and regulatory carbon-accounting requirements are compressing traditional grade hierarchies while opening premium positioning for traceable, low-embodied-energy rigging hardware.
Electropolished duplex stainless steel (2205/2507 grades) is absorbing specification-grade demand previously captured by 316 austenitic variants in North Sea offshore wind installations. Project engineers at turbine foundation contractors specify these higher-strength, lower-nickel compositions for subsea cable tensioning systems. The shift is absorbing premium pricing power from legacy 316 suppliers while rewarding mills with vacuum-arc remelting capability.
REACH Annex XVII restrictions on hexavalent chromium plating are eliminating traditional zinc-chromate corrosion protection for carbon steel turnbuckle bodies in European supply chains. Mechanical galvanizing and zinc-aluminum flake coatings now dominate CE-marked construction hardware. German automotive-transport rigging suppliers have completed material qualification programs ahead of the 2024 enforcement window.
Consolidated procurement through engineering-procurement-construction contractors is displacing fragmented distributor purchasing in US offshore wind port construction. Bechtel and Fluor specify certified turnbuckle lots with mill-test-report traceability for Vineyard Wind and Revolution Wind projects. This concentration is most visible in New Bedford and Bridgeport marine terminal developments, where tier-one contractors mandate direct-mill relationships over distribution intermediaries.
Eye and Eye Turnbuckle Market Segmentation
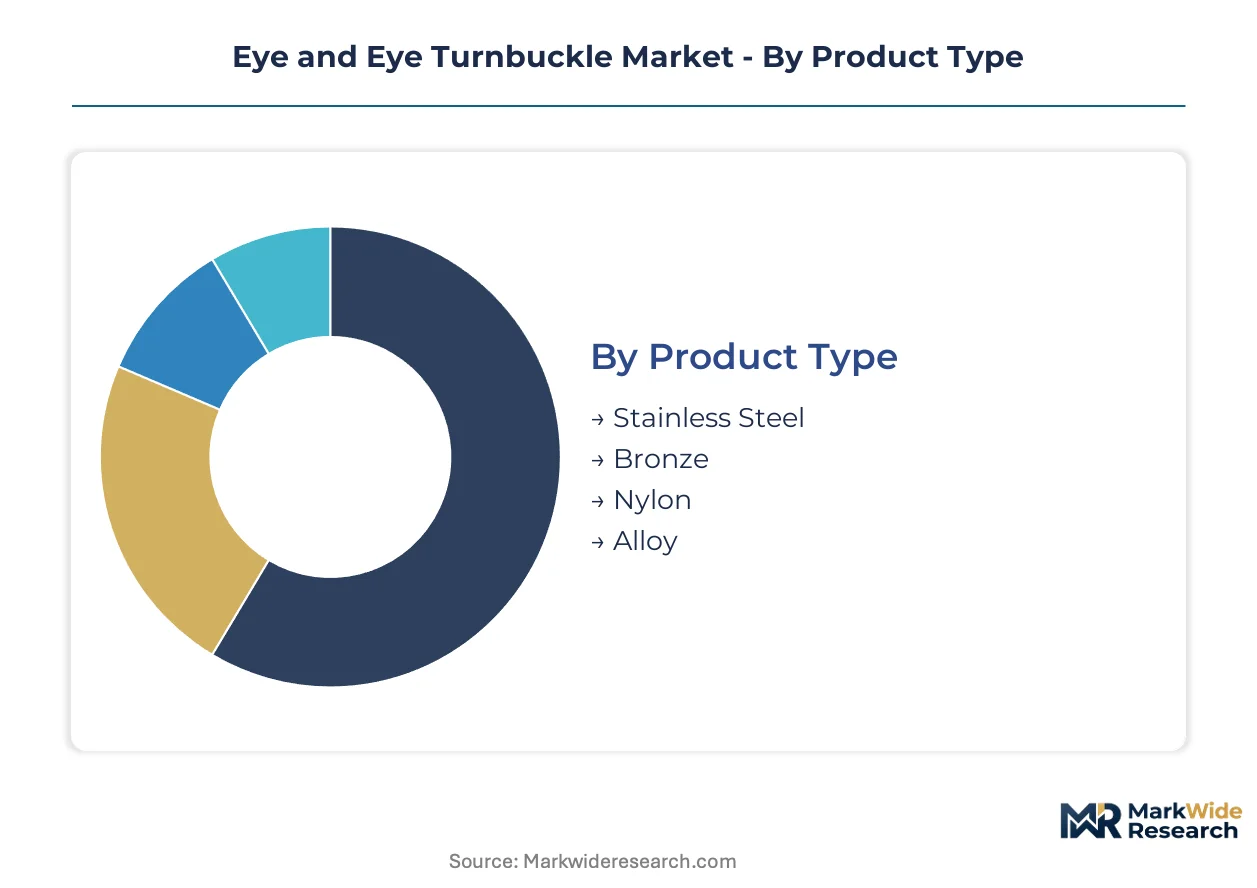
Segmentation in the eye and eye turnbuckle market reveals how capital deployment, corrosion resistance requirements, and certification standards fragment procurement channels across marine, construction, and industrial verticals.
Product Type:
Capital intensity peaks with vacuum-arc remelting capacity for duplex stainless grades, while commodity carbon steel forging requires lower upfront metallurgical investment but sacrifices margin durability.
- Stainless Steel:Electropolished 316 and 2205 duplex grades dominate saltwater and chemical-environment specifications. Yangtze River Delta port automation projects specify these variants for container crane rigging with full mill-test-report traceability. The EU Green Deal's lifecycle emissions documentation favors low-carbon austenitic and duplex compositions.
- Bronze:Naval brass and silicon-bronze alloys serve specialty marine applications requiring galvanic compatibility with aluminum superstructures. North Sea offshore wind contractors specify these for turbine foundation cable systems where dissimilar metal corrosion risks block steel deployment.
- Nylon:Glass-reinforced polymer bodies offer non-conductive, lightweight tensioning for temporary electrical utility installations and stage rigging where metal detection or weight constraints apply.
- Alloy:High-strength low-alloy steels bridge the cost-performance gap for construction scaffolding and structural bracing in non-corrosive inland environments.
Most installed capacity flows through stainless steel variants. Expansion is steepest in duplex grades as nickel price volatility compresses 316 margins.
Application:
Application segmentation tracks divergent certification burdens — marine and offshore energy demand specification-grade documentation while construction tolerates commodity-grade supply with shorter qualification cycles.
- Construction:Medium and large turnbuckle deployment for scaffolding structural bracing dominates volume throughput. OSHA scaffold safety standard revisions tightened fall-protection hardware requirements across US commercial and residential building sites.
- Marine:Shipbuilders generate superior per-unit margins through corrosion-resistant specification-grade certification. Gulf Coast US shipyards expanded procurement of duplex stainless rigging hardware for Jones Act vessel construction.
- Agriculture:Grain silo tensioning systems and livestock enclosure rigging favor zinc-plated carbon steel at economy price points with minimal documentation overhead.
- Industrial:Overhead crane maintenance and material handling equipment retrofits sustain replacement demand through distributor channels with standardized load ratings.
Construction absorbs the highest unit volumes. Marine applications command the steepest pricing premiums and slowest procurement cycles.
Size:
Size segmentation aligns with load-rating certification tiers — small sizes move through distribution inventory while extra-large bodies require forged-to-order production with extended lead times.
- Small:Turnbuckles under 10mm diameter serve architectural cable railings and light-duty theatrical rigging. These stock-keeping units rotate rapidly through industrial distributor catalogs with minimal technical support.
- Medium:The 10-25mm range anchors construction-sector procurement for scaffolding and temporary structural bracing. US contractors favor these sizes for OSHA-compliant fall-protection installations.
- Large:25-50mm bodies support heavy-lift marine and industrial applications. Hebei and Shandong forging clusters concentrate hot-forming capacity for this specification-grade segment.
- Extra Large:Above 50mm, turnbuckles enter project-specific engineering with custom proof-load testing. Offshore wind port developments in New Bedford and Bridgeport specify these for heavy-lift barge mooring systems.
Medium sizes dominate procurement frequency. Extra-large units carry the longest production backlogs and highest engineering margins.
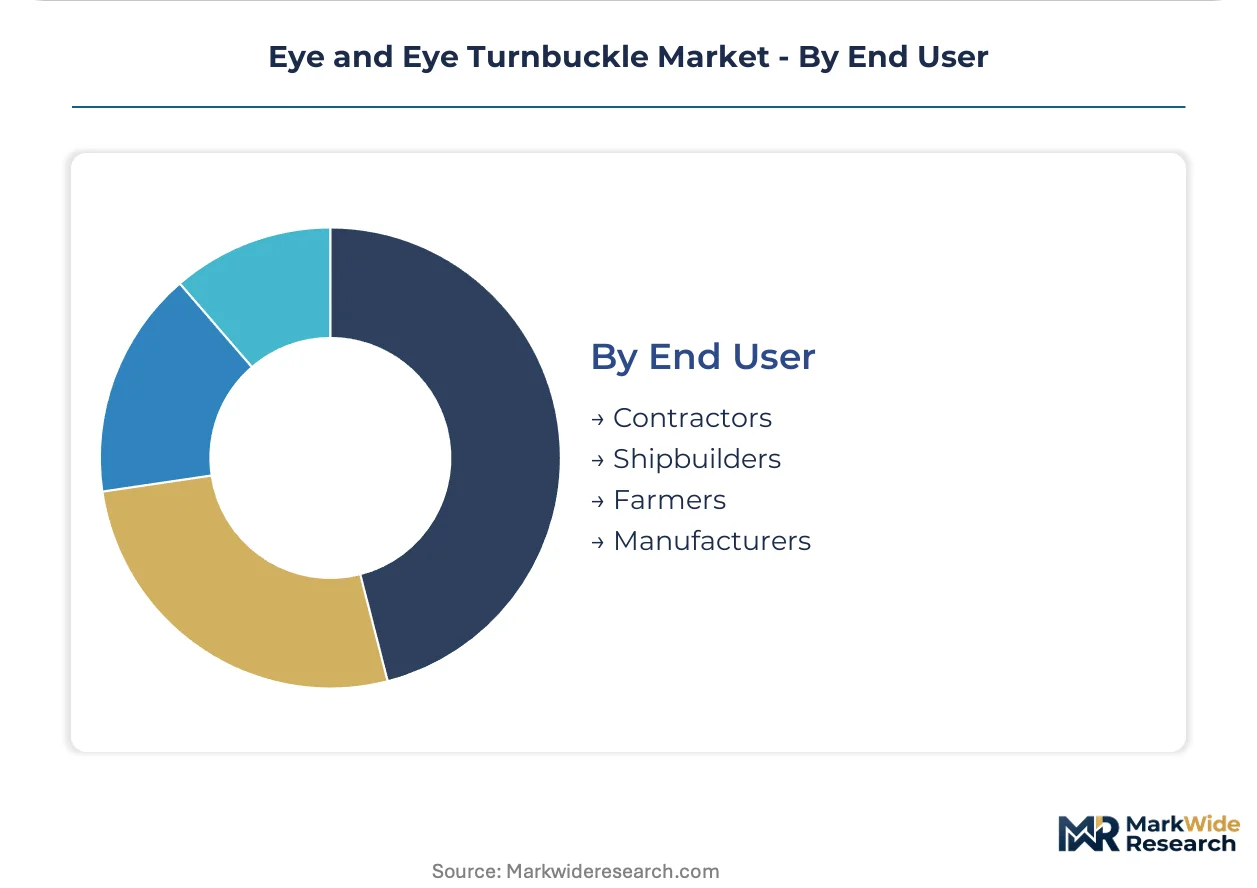
End User:
End-user segmentation separates specification-grade documentation requirements from commodity purchasing patterns, with shipbuilders and tier-one contractors driving premium positioning.
- Contractors:Fragmented construction procurement favors distributor relationships with rapid fulfillment over mill-direct specification-grade supply. OSHA compliance documentation requirements vary by project risk classification.
- Shipbuilders:European and US Gulf Coast yards mandate low-carbon rigging hardware with full lifecycle emissions traceability under EU Green Deal and Jones Act procurement guidelines.
- Farmers:Agricultural procurement prioritizes functional load ratings over certification depth, with cooperative buying groups aggregating demand for economy-grade carbon steel variants.
- Manufacturers:OEM equipment builders specify turnbuckles as integrated subcomponents, requiring design-dossier preparation and CE technical documentation for EU Machinery Directive compliance.
Contractors sustain the highest volume throughput. Shipbuilders impose the most stringent qualification protocols and generate the strongest pricing power for certified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eye and eye turnbuckle manufacturing traces its industrial lineage to 19th-century British maritime engineering, with Birmingham forges establishing the precision-forging techniques that later migrated to North American and East Asian production centers. Contemporary demand geography reflects this heritage while shifting toward automated port infrastructure and offshore energy installations.
United States
Gulf Coast shipyards in Louisiana and Texas expanded procurement of corrosion-resistant rigging hardware for Jones Act vessel construction. OSHA scaffold safety standard revisions tightened fall-protection requirements across commercial building sites. New Bedford and Bridgeport marine terminals specify extra-large turnbuckles with mill-test-report traceability for offshore wind port developments.
China
Terminal automation programs along the Yangtze River Delta require precision-tensioned cable systems for container crane rigging. GB/T standards for lifting accessories mandate proof-load testing protocols that differentiate specification-grade from commodity supply. Hebei and Shandong provinces concentrate hot-forming capacity for large turnbuckle bodies, creating single-source vulnerability for certified production.
Germany
REACH Annex XVII restrictions on hexavalent chromium plating eliminated traditional zinc-chromate corrosion protection for carbon steel turnbuckle bodies in European supply chains. German automotive-transport rigging suppliers completed material qualification programs for mechanical galvanizing and zinc-aluminum flake coatings ahead of enforcement windows. The Ruhr industrial corridor maintains heat-treatment expertise for forged end fittings.
India
Sagarmala program investments in Vizhinjam, Mundra, and Paradip terminals create specification-grade hardware demand for new heavy-lift infrastructure. BIS certification requirements for lifting accessories shape product design and testing protocols for domestic procurement. Gujarat and Maharashtra coastal zones concentrate ship repair yards driving stainless steel turnbuckle replacement cycles.
Netherlands
North Sea offshore wind contractors specify electropolished duplex stainless grades for subsea cable tensioning systems at turbine foundations. CE marking convergence with ISO 2415 reduces dual-certification costs for specification-grade supply. Rotterdam port modernization projects under EU Green Deal mandates prioritize low-carbon rigging hardware with documented lifecycle emissions.
Eye and Eye Turnbuckle Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the eye and eye turnbuckle market. Forging operations with captive heat-treatment facilities command premium positioning in specification-grade channels, while distributors and trading houses aggregate commodity volumes with minimal metallurgical investment. Three archetypes dominate: integrated forgers with vacuum-arc remelting capability, regional specialists in marine-grade stainless variants, and construction-focused distributors with rapid fulfillment networks. Competitive dynamics center on backward integration into raw material sourcing and geographic expansion through CE marking accreditation.
Within the integrated forging tier, The Crosby Group LLC and Columbus McKinnon occupy positions anchored by forged steel expertise and heavy-lift channel dominance. Among European specialists, Van Beest B.V. and Petersen Stainless Rigging Ltd. exemplify the marine-grade certification archetype with positioning in saltwater and offshore energy specifications. At the Asia-Pacific manufacturing end, Qingdao Dexing Rigging Co., Ltd. represents the scale-driven export fabricator archetype serving global distributor networks with standardized load ratings.
| Leading Market Players |
|---|
| The Crosby Group LLC |
| Peerless Industrial Group |
| Suncor Stainless, Inc. |
| Chicago Hardware & Fixture Company |
| Qingdao Dexing Rigging Co., Ltd. |
| Van Beest B.V. |
| Columbus McKinnon |
| UU LIFTING |
| Petersen Stainless Rigging Ltd. |
| Others |
Value Network & Pricing Analysis
Consolidated procurement by engineering-procurement-construction contractors at offshore wind port developments commands project-based pricing with mill-test-report traceability requirements, compressing distributor margins while rewarding direct-mill relationships.
Pricing Analysis
Three-tier pricing structure across specification-grade, distributor-grade, and commodity levels dominates the market, with certification depth and alloy composition as the primary price differentiation drivers. Cost compression in marine-grade 316 stainless variants is intensifying because nickel and molybdenum price volatility forces producers into index-contract raw material exposure. Shipbuilders demonstrate the lowest price sensitivity due to Jones Act and EU Green Deal compliance mandates, while agricultural cooperatives purchasing zinc-plated carbon steel variants exhibit the highest price elasticity.
Supply Chain Analysis
Direct-to-shipbuilder channels handle specification-grade demand with full documentation, while construction-sector procurement flows through industrial distributor networks with rapid fulfillment. Hot-forming capacity clusters in China's Hebei and Shandong provinces, with secondary forging operations in Germany's Ruhr corridor and India's Gujarat coastal zone. The supply chain rests on nickel, molybdenum, and scrap steel feedstocks. Single-source vulnerability for large turnbuckle bodies creates structural risk, as specification-grade production depends on concentrated East Asian forging equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eye and eye turnbuckle market functions as a stable compounder anchored by durable marine infrastructure replacement cycles and regulatory corrosion mandates that perpetually refresh specification-grade demand.
For Market Incumbents: Cement market position through backward integration into vacuum-arc remelting capacity for duplex stainless grades, insulating margin structures from nickel price volatility. Capture channel control by establishing direct-mill relationships with tier-one EPC contractors at offshore wind port developments, displacing distributor intermediaries that currently fragment construction-sector procurement. For New Entrants and Emerging Players: CE marking convergence with ISO 2415 in European markets opens a window for mid-tier Asian producers with ISO-accredited laboratories to penetrate specification-grade channels previously blocked by dual-certification cost barriers. Target India's Sagarmala program investments in Vizhinjam and Mundra terminals, where BIS certification requirements create qualified supply shortages. Lead with digital load-monitoring integration as a service-based wedge, shifting revenue from hardware sales to predictive maintenance subscriptions. For Investors and Strategic Acquirers: Engineering-procurement-construction contractors with captive marine terminal development pipelines are the most active acquirer in this space, seeking to secure specification-grade hardware supply for Vineyard Wind-class projects. Focus acquisition screening on regional specialists with captive heat-treatment facilities and marine-grade 316 or duplex stainless certification depth. Monitor carbon-border adjustment mechanism implementation timelines as the critical inflection signal for alloy sourcing economics and regional manufacturing competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum-Arc Remelting | Captive duplex stainless production insulates margins from nickel price volatility at Hebei and Shandong forging clusters. |
| CE Marking Accreditation Expansion | Unified ISO 2415 testing protocols reduce certification costs for mid-tier Asian producers seeking European port modernization contracts. |
| Digital Load-Monitoring Integration | Embedded strain-sensor assemblies enable subscription-based predictive maintenance services at North Sea offshore wind installations. |
| Direct-Mill EPC Relationships | Bypassing distributor intermediaries captures consolidated procurement at New Bedford and Bridgeport marine terminal developments. |
| Heat-Treatment Technician Pipeline Development | Addressing metallurgical expertise scarcity in aging European and North American workforces secures specification-grade production continuity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with shipyard procurement officers, EPC contractor material specifiers, heat-treatment facility managers, and industrial distributor category buyers with secondary validation from customs trade data, SEC filings of listed rigging hardware manufacturers, OSHA scaffold safety standard revision records, and EU Green Deal maritime infrastructure procurement disclosures. Bottom-up volume estimates from application-level deployment data triangulated against top-down market sizing from trade flow analysis.
Historical reference periods anchored the forecast window to observed specification-grade procurement cycles at Yangtze River Delta port automation projects and Gulf Coast Jones Act vessel construction programs. The analytical framework modeled segmentation dimensions including material grade tier, end-use vertical, size category, and certification depth across the projection horizon. CAGRs derived from regression analysis of alloy price-adjusted procurement volumes, with industry-specific inputs including nickel futures volatility indices and offshore wind port development pipeline tracking.
Revisions become necessary when carbon-border adjustment mechanisms alter alloy sourcing economics, REACH Annex XVII restrictions expand beyond hexavalent chromium plating, or forging capacity consolidation in East Asia triggers supply disruption. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and raw material price trajectory stability. Periodic stress-testing of base assumptions against nickel-molybdenum spread movements and shipyard orderbook fluctuations is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Global Pipe and Tube Bending Machine Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Material Handling Equipment Telematics Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Global Bop Handling Systems Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
High-Precision Gear Reducer Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market