
 Tube Rotator Market | 2026-2036
Tube Rotator Market Size, Share, and Industry Trends Forecast 2026-2036
Tube Rotator Market Outlook
Aftermarket service revenue is reconfiguring margin pools away from unit sales toward lifecycle contracts in the tube rotator landscape. Thomas Scientific leverages its broad distribution network to sustain recurring calibration and maintenance income. Benchmark Scientific differentiates through specialized repair programs that anchor long-term customer relationships. Merck competes by extending premium service tiers to research facilities with high-throughput screening demands.
A tube rotator is a laboratory device that rotates sample containers at controlled speeds, typically ranging from 1 to 100 revolutions per minute, to ensure homogeneous mixing of liquids, suspensions, or cultures without introducing shear forces that would damage sensitive biological materials. Electric rotators dominate the product type landscape due to their programmable speed control and reproducibility in regulated environments. Laboratory use represents the fastest-growing application segment as pharmaceutical companies automate their quality control workflows. IoT-enabled technology is gaining traction among research facilities seeking remote monitoring and audit trail capabilities for compliance documentation.
The FDA enforces quality system regulations that mandate design controls and process validation for laboratory equipment used in drug development, compelling manufacturers to invest in documentation-heavy engineering cycles. ISO 9001 and ISO 13485 certification requirements shape supplier qualification criteria for pharmaceutical end users seeking to minimize audit risk. Stakeholders must monitor how evolving data integrity guidelines from regulatory bodies redefine connectivity and electronic record features as baseline expectations rather than premium differentiators.
Market Dynamics
Aftermarket service revenue is reconfiguring margin pools away from unit sales toward lifecycle contracts in the tube rotator landscape. Thomas Scientific leverages its broad distribution network to sustain recurring calibration and maintenance income. Benchmark Scientific differentiates through specialized repair programs that anchor long-term customer relationships. Merck competes by extending premium service tiers to research facilities with high-throughput screening demands.
Growth Catalysts
- Automated quality control workflows:Pharmaceutical companies are expanding their adoption of automated sample preparation equipment to meet throughput demands in drug development pipelines.
- FDA quality system regulation:The tightening validation requirements for laboratory equipment compel manufacturers to invest in documentation-heavy engineering cycles that favor established suppliers.
- German CRO density:Demand concentrates in Germany due to its dense cluster of contract research organizations and analytical laboratories requiring reliable mixing equipment.
Market Restraints
- Precision motor supply concentration:High-torque brushless DC motor production concentrates among Asian suppliers, exposing equipment manufacturers to lead time volatility and tariff exposure.
- ISO 13485 certification timelines:The eighteen-month average certification cycle for medical device quality management systems delays market entry for new entrants targeting clinical diagnostics.
- Orbital shaker substitution:Orbital shakers with programmable motion profiles capture applications requiring aggressive mixing, compressing addressable demand for gentle-rotation tube rotators in cell culture workflows.
Strategic Opportunities
- IoT-enabled audit trails:Research facilities seeking remote monitoring capabilities create demand for connected devices with electronic record features for compliance documentation.
- India's PLI scheme for medical devices:Production-linked incentive schemes for domestic manufacturing attract contract assembly investments serving South Asian diagnostic laboratories.
- Cell and gene therapy manufacturing:GMP-grade tube rotators for gentle handling of viral vectors and cell suspensions represent an emerging application with premium pricing potential.
Industry Challenges
- Mechatronics engineering scarcity:The intersection of precision mechanical design and embedded firmware development limits the talent pool available for next-generation product development.
- Legacy LIMS integration:Research facilities with established laboratory information management systems require complex middleware development to connect IoT-enabled rotators to existing data architectures.
- CE marking documentation burden:The Medical Device Regulation's expanded technical file requirements extend time-to-market for products claiming clinical diagnostic utility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tube Rotator Market |
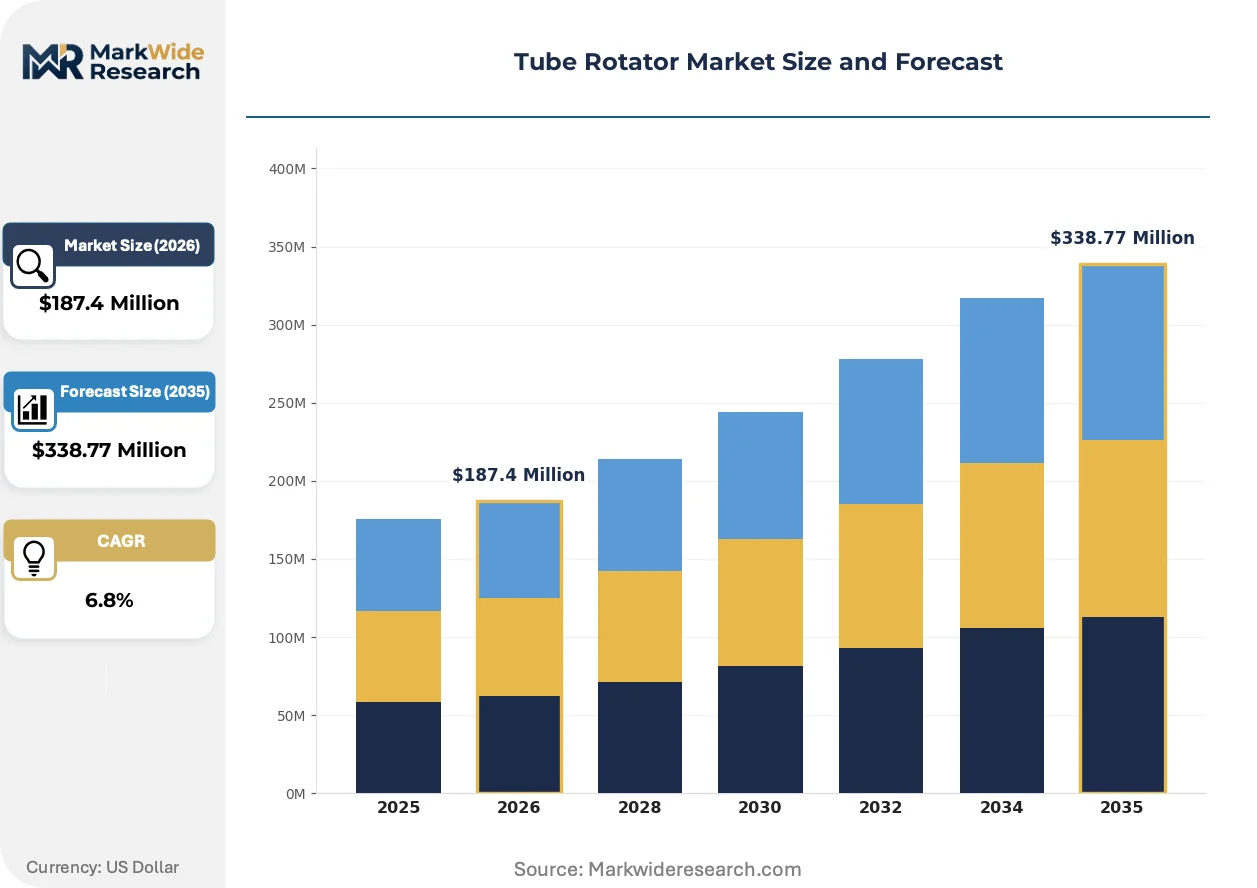
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Rotators, Electric Rotators, Pneumatic Rotators, Hydraulic Rotators Application: Manufacturing, Food Processing, Chemical Handling, Laboratory Use End User: Industrial Plants, Research Facilities, Food Processing Units, Pharmaceutical Companies Technology: Automation, IoT-Enabled, Mechanical, Hybrid Systems |
| Companies Covered | Thomas Scientific, Merck, Abdos Labtech, CAPP ApS, Scientific Industries, Benchmark Scientific, Crystal Technology and Industries, Labnet, Boekel Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tube Rotator Market Strategic Shifts
Digital connectivity and predictive maintenance capabilities are redefining baseline expectations for laboratory mixing equipment. Manufacturers must now embed compliance-ready data architectures from the design phase rather than retrofitting connectivity as a premium feature.
Cloud-based instrument management platforms are virtualizing the traditional service relationship between manufacturers and research facilities. Thermo Fisher and Eppendorf deploy these systems across their installed bases, enabling remote diagnostics and automated calibration scheduling. This virtualization compresses the addressable market for third-party service providers while locking customers into proprietary ecosystems.
REACH restrictions on perfluorinated compounds are forcing material transitions in rotor coatings and seals used in aggressive chemical environments. The ECHA's 2023 proposal to limit PFAS in professional equipment accelerates substitution toward ceramic and PEEK-based wetted components. German analytical laboratories, operating under strict chemical safety ordinances, are already qualifying these alternative materials ahead of formal enforcement timelines.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships in academic and government research segments. Vizient and Premier contract for multi-site equipment standardization, extracting volume discounts and unified service terms. This concentration is most visible across NIH-funded research institutes in the United States, where capital equipment purchasing now routes through centralized supply agreements rather than individual laboratory discretion.
Tube Rotator Market Segmentation
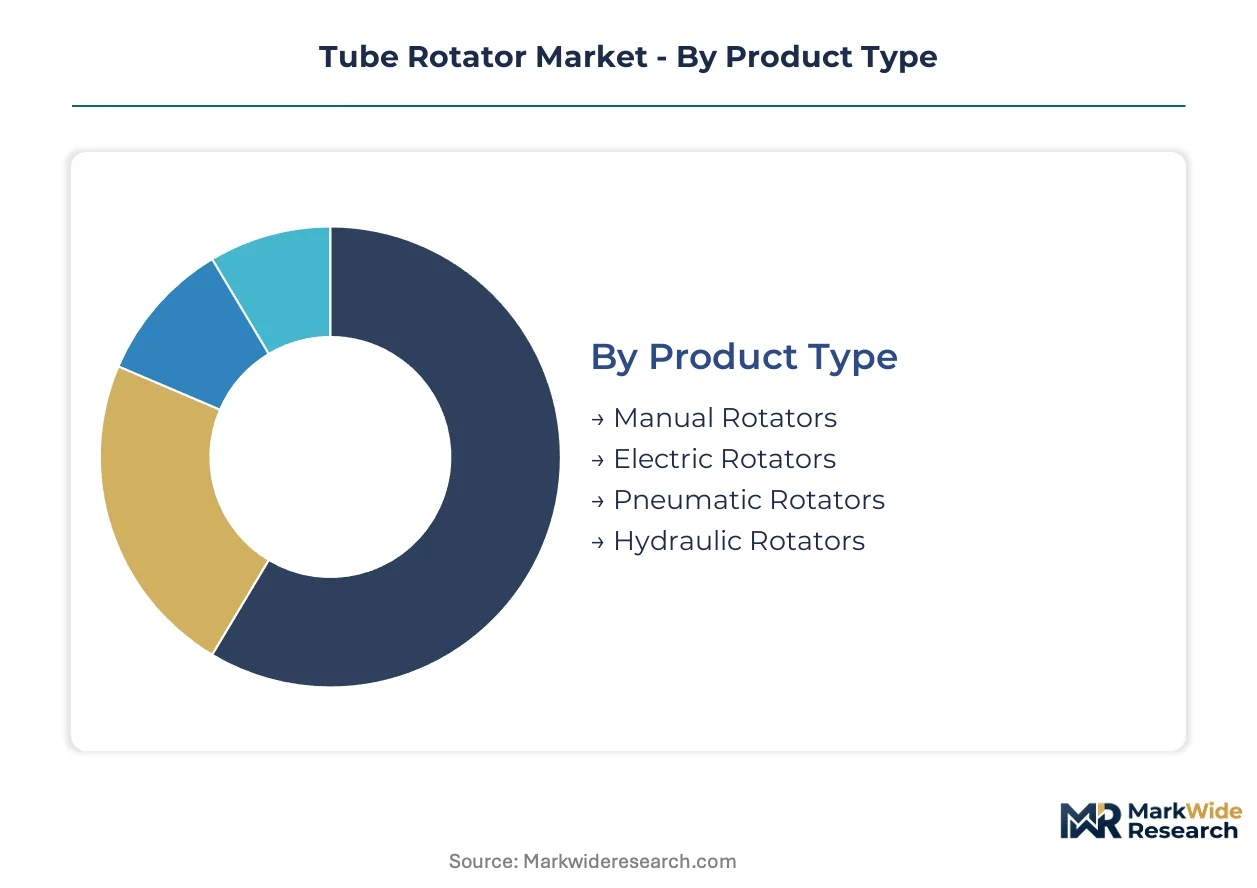
Tube rotator procurement patterns diverge sharply across operational environments, with pharmaceutical quality control workflows demanding precision engineering while food processing prioritizes washdown durability. Understanding these segment boundaries clarifies where specification premiums apply versus commodity competition.
Product Type:
Cost tier stratification separates entry-level manual units from precision electric systems with programmable control architectures.
- Manual Rotators:Hand-cranked mechanical rotation without electrical components suits basic mixing in resource-constrained settings. Demand concentrates in educational laboratories across India and Southeast Asia where capital budgets limit automation investment.
- Electric Rotators:Brushless DC motor systems deliver programmable speed control from 1 to 100 RPM with digital display interfaces. German pharmaceutical manufacturers specify these units for GMP-compliant drug stability testing where batch reproducibility is mandatory.
- Pneumatic Rotators:Compressed-air drive systems eliminate spark hazards in flammable solvent environments. Chemical synthesis facilities specify these for hexane and ether-based extractions.
- Hydraulic Rotators:High-torque fluid power systems handle dense slurries and viscous suspensions beyond electric motor capacity. Mining laboratories and industrial quality control departments deploy these for ore sample preparation.
Electric rotators command the established base. The steepest expansion runs through IoT-enabled variants with remote monitoring capabilities.
Application:
Volume concentration and throughput requirements reshape equipment specification across operational contexts.
- Manufacturing:Heavy-duty rotators integrate into production lines for adhesive mixing, coating preparation, and polymer blending. Automotive sealant manufacturers in Michigan and Bavaria operate these in continuous-duty cycles.
- Food Processing:Stainless steel construction with IP65 washdown ratings supports dairy culture incubation and beverage emulsion preparation. French cheese producers and Wisconsin dairy cooperatives specify these for pathogen-sensitive fermentation control.
- Chemical Handling:Corrosion-resistant wetted components handle acids, bases, and organic solvents in analytical sample prep. REACH compliance drives material selection toward ceramic and PEEK alternatives.
- Laboratory Use:Precision speed control with minimal vibration supports cell culture, blood sample mixing, and molecular biology protocols. Pharmaceutical companies automate quality control workflows with these units, gaining share fastest among all application segments.
Laboratory use is climbing the fastest. Manufacturing retains the largest installed base across industrial economies.
End User:
Customer type determines service model expectations, with research facilities demanding calibration contracts and industrial plants prioritizing parts availability.
- Industrial Plants:High-throughput mixing operations in coatings, adhesives, and polymer production require 24/7 operational reliability. Tier-one automotive suppliers in Germany and Japan specify these for just-in-time manufacturing support.
- Research Facilities:Universities, government institutes, and private R&D centers need audit-trail documentation and IQ/OQ/PQ validation packages. NIH-funded institutes in the United States route procurement through Vizient and Premier group purchasing organizations.
- Food Processing Units:Dairy, meat, and beverage producers face USDA and FDA sanitary requirements with clean-in-place protocols. Wisconsin and California processing cooperatives dominate North American demand concentration.
- Pharmaceutical Companies:Drug developers and contract manufacturers require ISO 13485-certified equipment with electronic batch records. German CRO density in Munich and Hamburg sustains premium demand for GMP-grade systems.
Pharmaceutical companies anchor premium pricing tiers. Research facilities are expanding most quickly through federal funding cycles.
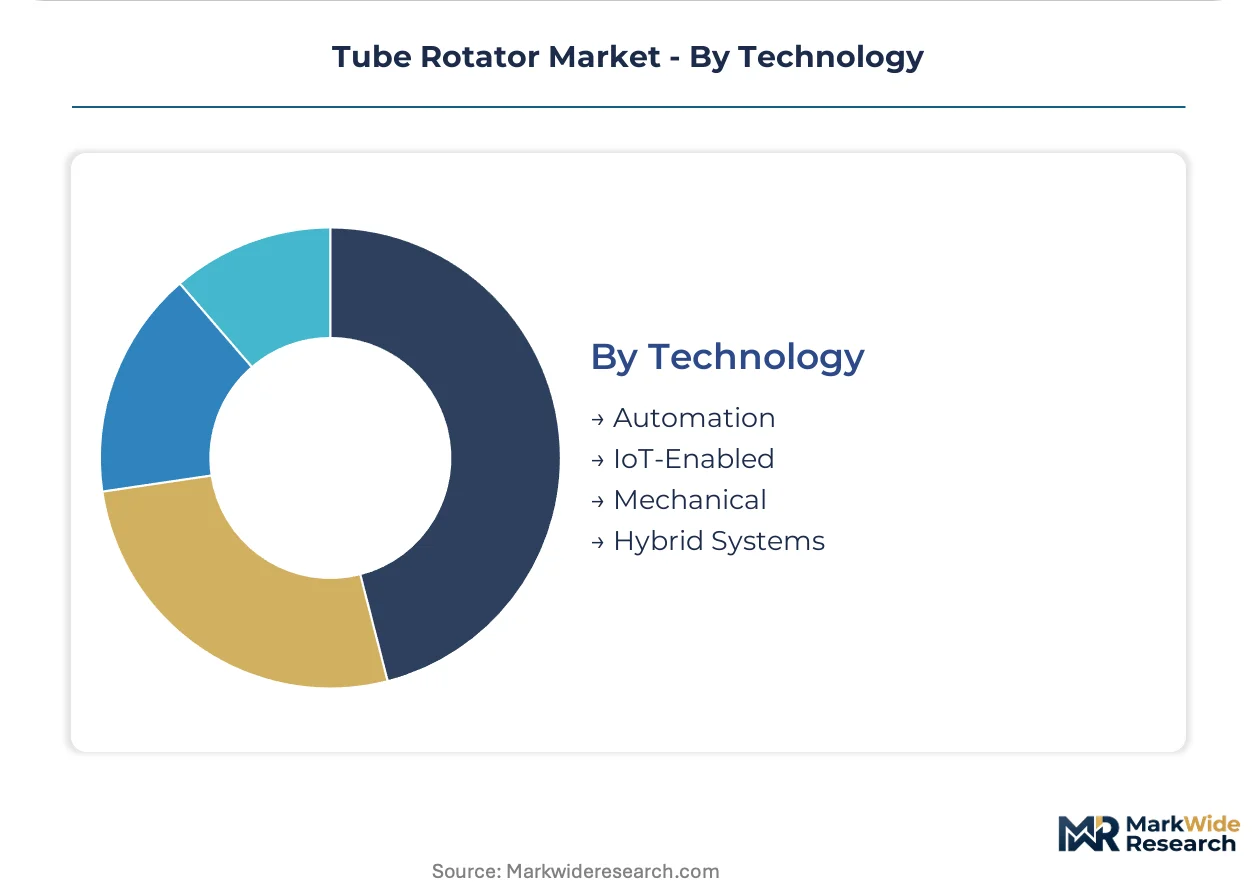
Technology:
Maturity gradients separate legacy mechanical designs from connected architectures requiring firmware development capabilities.
- Automation:Programmable logic controllers enable timed protocols, speed ramping, and multi-step mixing sequences. High-throughput screening facilities at Merck and Thermo Fisher deploy these for unattended overnight operation.
- IoT-Enabled:Cloud-connected sensors transmit vibration, temperature, and operational data to centralized instrument management platforms. Eppendorf and Thermo Fisher deploy these systems to enable predictive maintenance and remote diagnostics.
- Mechanical:Gear-driven and belt-driven rotation without electronic control suits basic applications where simplicity reduces failure modes. Emerging market laboratories and educational institutions specify these for lowest total cost of ownership.
- Hybrid Systems:Combined electric drive with mechanical backup or pneumatic assist addresses applications requiring redundant operational modes. Cell and gene therapy manufacturers specify these for critical viral vector handling where process interruption is unacceptable.
Mechanical systems retain the largest legacy installed base. IoT-enabled configurations are gaining share fastest through compliance documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: German pharmaceutical laboratories prioritize GMP-validated precision systems, while Indian educational institutions favor manual units constrained by capital budgets, and US research facilities route procurement through consolidated purchasing organizations that reshape supplier relationships.
Germany
Munich and Hamburg host dense clusters of contract research organizations demanding GMP-grade tube rotators for drug stability testing. The country's Medical Device Regulation implementation extends CE marking documentation timelines for clinical diagnostic equipment. Bavarian analytical laboratories are qualifying ceramic and PEEK-based wetted components ahead of ECHA's PFAS restriction enforcement.
United States
NIH-funded research institutes concentrate demand for IoT-enabled systems with electronic batch records and audit trail capabilities. FDA quality system regulations mandate design controls and process validation for laboratory equipment used in drug development workflows. Michigan automotive sealant manufacturers operate heavy-duty rotators in continuous-duty just-in-time production cycles.
India
Educational laboratories across Maharashtra and Karnataka specify manual rotators where automation investment remains capital-constrained. The Production-Linked Incentive scheme for medical devices attracts contract assembly investments serving South Asian diagnostic laboratories. Gujarat-based pharmaceutical manufacturers are expanding quality control automation to meet export certification requirements.
China
Biopharmaceutical manufacturing in Jiangsu and Zhejiang provinces drives demand for high-throughput screening equipment with programmable protocols. NMPA medical device registration requirements shape supplier qualification criteria for domestic drug developers. Shanghai research facilities are deploying cloud-connected instrument management platforms for predictive maintenance capabilities.
Japan
Cell and gene therapy manufacturers in Kanto and Kansai regions specify hybrid systems with redundant operational modes for critical viral vector handling. METI industrial standards influence equipment specification for precision mechanical design in regulated environments. Osaka-based chemical synthesis facilities deploy pneumatic rotators for flammable solvent extraction protocols.
Tube Rotator Market Competitive Environment
Capability concentration sits with precision engineering specialists; scale advantage sits with diversified laboratory equipment conglomerates. The market structures around three tiers: premium-tier vendors with GMP certification and validation packages; mid-market suppliers competing on delivery speed and regional service density; and value-tier fabricators serving price-sensitive educational segments. Consolidation pressure intensifies as group purchasing organizations extract volume discounts and cloud-based instrument management platforms lock customers into proprietary ecosystems.
Within the premium service tier, Thomas Scientific leverages its broad distribution network to sustain recurring calibration income, while Benchmark Scientific differentiates through specialized repair programs anchoring long-term relationships. Merck occupies a position extending premium service tiers to research facilities with high-throughput screening demands. These three exemplify how aftermarket revenue reconfigures margin pools away from unit sales toward lifecycle contracts.
| Leading Market Players |
|---|
| Thomas Scientific |
| Merck |
| Abdos Labtech |
| CAPP ApS |
| Scientific Industries |
| Benchmark Scientific |
| Crystal Technology and Industries |
| Labnet |
| Boekel Scientific |
| Others |
Value Chain & Pricing Dynamics
Brushless DC motor production concentrates among Asian suppliers, anchoring margin pools in aftermarket service contracts and lifecycle revenue rather than unit manufacturing. Equipment manufacturers face lead time volatility that feeds downstream into pricing premiums for GMP-certified systems with validated documentation packages.
Pricing Analysis
Long-term service contracts dominate the pricing architecture, with pharmaceutical buyers locking in multi-year calibration and maintenance agreements alongside initial equipment procurement. Price differentiation rests on ISO 13485 certification tier and after-sales bundling density, with GMP-grade systems commanding substantial premiums over educational-tier alternatives. Cost compression in the manual rotator segment intensifies as Indian educational institutions prioritize lowest total cost of ownership. Research facilities exhibit least price sensitivity due to grant-funded procurement and audit-risk minimization priorities.
Supply Chain Analysis
Extended payment terms from European and North American OEMs strain working capital for precision motor suppliers concentrated in China, Taiwan, and South Korea. Component sourcing draws from Japanese bearings specialists, German sensor manufacturers, and Chinese machined aluminum housings. Single-source vulnerability in high-torque motor controllers exposes equipment assemblers to tariff exposure and logistics chokepoints. Distribution runs through scientific supply distributors, direct manufacturer relationships for large pharmaceutical accounts, and consolidated group purchasing organizations serving academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
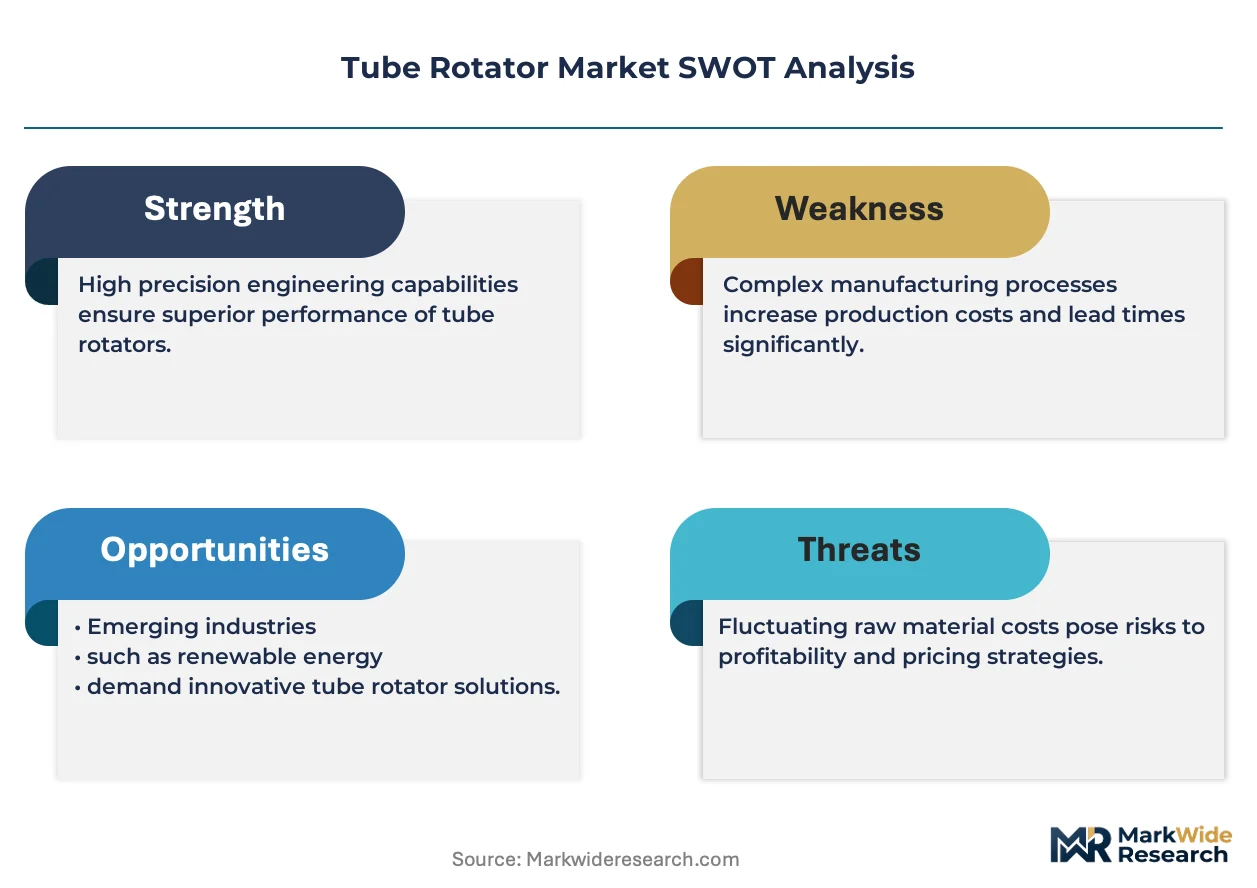
Orbital shaker substitution threatens gentle-rotation tube rotators in cell culture workflows, compelling incumbents to defend application-specific positioning through compliance differentiation and service entrenchment.
For Market Incumbents: Entrench service relationships through predictive maintenance platforms and IQ/OQ/PQ validation bundling that locks pharmaceutical customers into proprietary ecosystems. Deepen backward integration into brushless DC motor assembly to reduce Asian supplier dependency and compress lead times for GMP-grade orders. Defend against orbital shaker substitution by emphasizing shear-force minimization in cell therapy applications where biological material integrity is non-negotiable. For New Entrants and Emerging Players: Mid-market research facilities in India and Southeast Asia represent the most penetrable entry point, where capital constraints limit automation investment and manual rotator demand concentrates. Cell and gene therapy manufacturing in Japan and Germany offers premium pricing potential for hybrid systems with redundant operational modes. Pursue contract assembly partnerships under India's PLI scheme to establish regional manufacturing credibility and bypass eighteen-month ISO 13485 certification barriers for imported equipment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed laboratory equipment distributors seeking platform consolidation and aftermarket revenue expansion. Five-to-ten year viability hinges on IoT-enabled audit trail capabilities becoming baseline rather than premium features. Monitor FDA data integrity guideline evolution as the critical signal for whether connectivity investments convert to sustainable competitive moats or become commoditized table stakes.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Cloud-connected instrument management enables predictive maintenance and locks customers into proprietary ecosystems at Thermo Fisher scale. |
| GMP Certification Pathway | ISO 13485 and FDA quality system compliance opens pharmaceutical procurement channels and supports premium pricing tiers. |
| Backward Integration into Motors | In-house brushless DC assembly reduces Asian supplier dependency and compresses lead times for validated equipment orders. |
| Service Contract Expansion | Lifecycle revenue reconfigures margin pools away from unit sales toward recurring calibration and maintenance income streams. |
| Material Transition Program | Ceramic and PEEK component qualification ahead of ECHA PFAS restrictions secures German analytical laboratory demand concentration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical quality control directors, biomedical engineers at contract research organizations, aftermarket service heads at scientific distributors, and procurement managers at group purchasing organizations. Secondary validation drew from FDA quality system regulation filings, ECHA REACH restriction proposals, ISO certification databases, and customs trade data for laboratory equipment imports. Bottom-up equipment shipment analysis and top-down pharmaceutical capital expenditure forecasting were triangulated to constrain volume estimates.
Calibration against historical adoption curves and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application environment, end-user procurement structure, and technology connectivity level. CAGRs were derived from fitted growth curves adjusted for pharmaceutical automation spending cycles and medical device certification backlog durations. Forecast inputs incorporated German CRO density indices and NIH funding allocation patterns for research facility demand projection.
Practitioners should monitor FDA data integrity guideline enforcement intensity and ECHA PFAS restriction implementation timing for early signals of connectivity feature commoditization or material cost shock transmission. Macroeconomic deviation in pharmaceutical R&D spending, regulatory acceleration in medical device quality management requirements, or technological disruption from orbital shaker programmable motion profiles would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Dust Extractors Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
United States Hand Holes Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Forklift Truck Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Pneumatic Conveying Diverters Market