
 Global Surgical Power Tools Market | 2026-2036
Global Surgical Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Power Tools Market Foresight
Subscription-based leasing and pay-per-use instrument programs are rewriting capital deployment patterns for surgical power tools. Stryker leverages its service infrastructure to bundle maintenance with hardware placement, sustaining recurring revenue streams. Zimmer Biomet anchors its competitive stance through specialized orthopedic power systems that dominate joint reconstruction workflows. B. Braun competes via in-house production of sterilizable handpiece components, controlling quality thresholds across European hospital networks.
Surgical power tools are motorized instruments delivering controlled mechanical energy to bone and tissue through rotating, oscillating, or reciprocating action at speeds typically ranging from 5,000 to 80,000 RPM, designed for precision cutting, drilling, or ablation in sterile operative fields. Battery-powered cordless platforms now lead technology adoption as lithium-ion cell density improvements enable sustained torque output without pneumatic tethering, while orthopedic surgery applications command the largest revenue pool due to volume-driven instrument wear and replacement cycles. Reamers and high-speed cutters represent faster-growing product categories as spinal and neurosurgical procedures require finer cutting geometries.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers seeking multi-regional distribution. ISO 13485 quality management systems and IEC 60601 electrical safety standards further constrain design choices for battery-powered and electric platforms. Stakeholders must monitor regulatory divergence between FDA's predicate-based framework and MDR's stricter clinical evidence demands when allocating R&D budgets across geographic portfolios.
Market Dynamics
Battery-powered cordless platforms are compressing replacement cycles for pneumatic systems while EU MDR sterilization validation requirements extend product development timelines and reshape competitive entry economics.
Growth Catalysts
- Ambulatory surgery center expansion:United States healthcare networks are scaling same-day joint procedures, driving instrument procurement volumes for outpatient-compatible cordless systems.
- EU MDR technical documentation mandates:Stricter clinical evidence requirements for powered surgical instruments are consolidating supplier relationships around established quality management systems.
- Lithium-ion energy density improvements:Cell chemistry advances now sustain torque output across multi-hour orthopedic cases without tethering constraints.
Market Restraints
- Raw material concentration:Rare earth magnet supply chains for high-RPM motor assemblies concentrate in Chinese processing facilities, exposing cost volatility.
- Sterilization validation costs:FDA 510(k) biocompatibility testing and repeated autoclave-cycle verification extend development budgets for new handpiece geometries.
- Pneumatic infrastructure sunk costs:Hospital networks with existing compressed-gas line investments face capital inefficiency when switching to battery platforms.
Strategic Opportunities
- India surgical infrastructure:Government PLI scheme incentives for medical device manufacturing are attracting power tool assembly investments to serve South Asian demand.
- Neurosurgical micro-cutting:Finer reamer geometries for spinal decompression procedures command premium pricing and faster replacement cycles than standard orthopedic attachments.
- Subscription service models:Leasing programs bundling maintenance with hardware placement are penetrating German hospital procurement frameworks.
Industry Challenges
- Servicing technician scarcity:Specialized repair capabilities for sealed battery handpieces concentrate at manufacturer-certified facilities, creating geographic coverage gaps.
- Legacy system integration:New cordless platforms must interface with existing surgical navigation systems and sterilization tracking software.
- IP licensing complexity:Motor control algorithms and torque-feedback patents fragment across multiple component suppliers, complicating in-house development pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Power Tools Market |
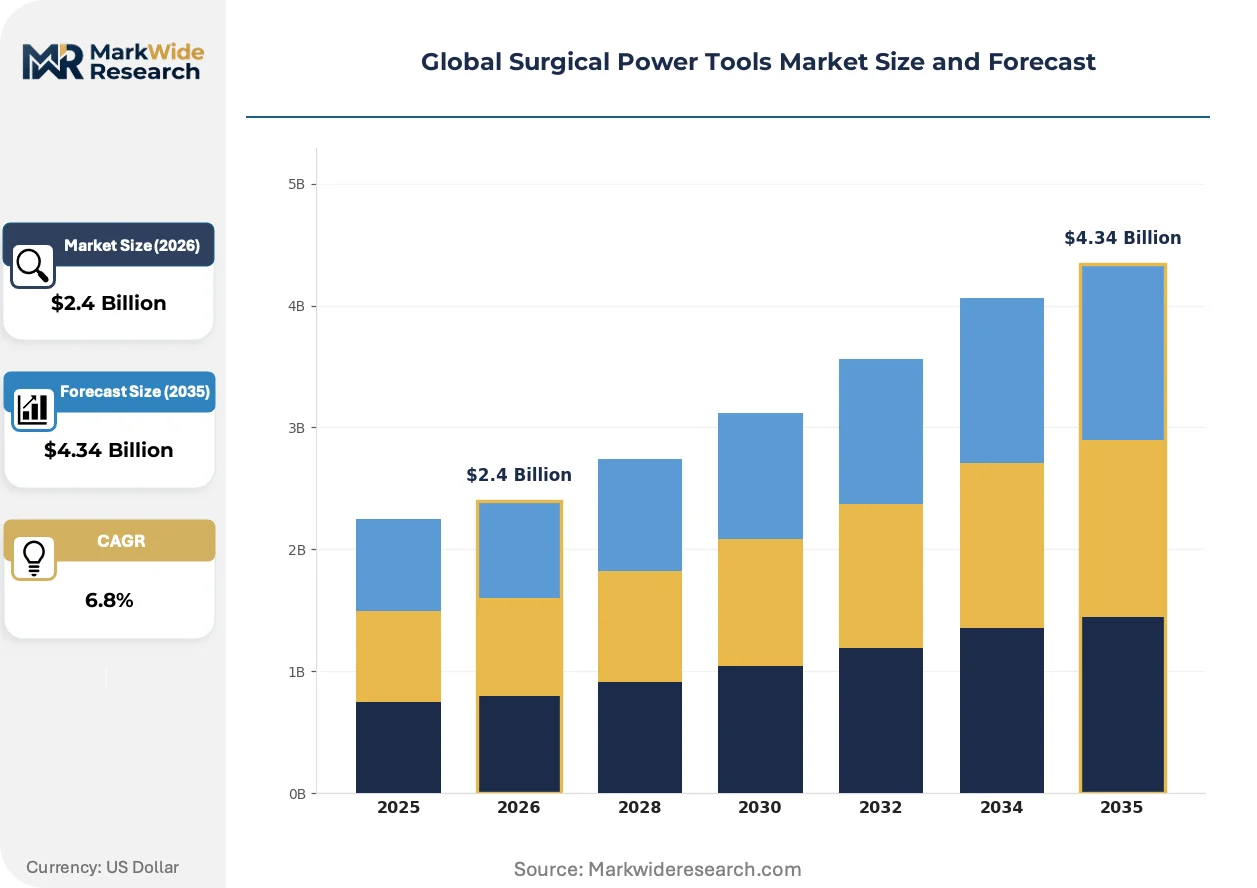
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Saws, Reamers, Handpieces, Oscillating Tools, High-Speed Cutters Technology: Battery Powered, Pneumatic, Electric, Hydraulic, Corded, Cordless Application: Orthopedic Surgery, Neurosurgery, Plastic Surgery, Dental Surgery, ENT Surgery, Spinal Surgery End User: Hospitals, Ambulatory Surgery Centers, Dental Clinics, Specialized Surgical Centers |
| Companies Covered | Medtronic, Stryker, Zimmer Biomet, Johnson & Johnson, CONMED Corporation, B. Braun, Arthrex, DePuy Synthes, Karl Storz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Power Tools Market Shifts & Advancements
Power delivery architectures and regulatory evidence frameworks are simultaneously evolving, compressing product lifecycles while elevating the technical bar for market participation.
Brushless DC motor technology is migrating from high-end neurosurgical systems into standard orthopedic handpieces as torque precision and thermal management improve. German and United States hospital procurement departments are specifying these platforms for joint reconstruction workflows. The shift is compressing margins for pneumatic instrument incumbents while rewarding suppliers with captive motor manufacturing capabilities.
EU MDR's stricter clinical evidence requirements for Class IIa powered surgical instruments are extending technical documentation timelines by twelve to eighteen months. Manufacturers must now generate clinical evaluation reports and post-market surveillance data beyond predicate-device comparisons. Spinal fusion power systems face the steepest compliance burden, with notified bodies demanding biomechanical performance validation for high-speed cutting attachments.
Hospital procurement departments are unbundling maintenance contracts from hardware purchases, forcing instrument suppliers to compete on transparent service pricing. German university hospital networks pioneered this shift, with United States integrated delivery networks now adopting similar request-for-proposal structures. After-sales revenue streams are concentrating around suppliers with regional technical service footprints and rapid-turnaround sterilizable component inventories.
Global Surgical Power Tools Market Segmentation
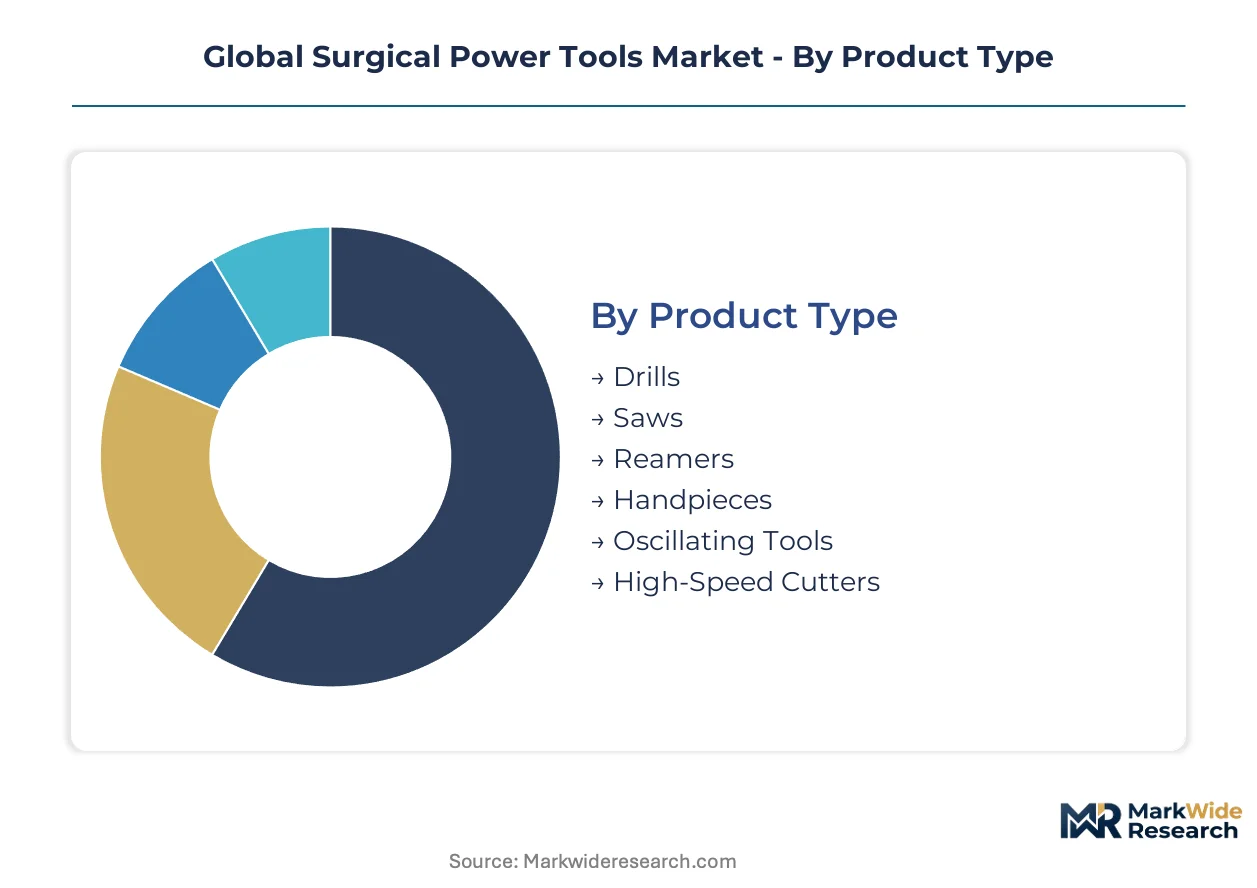
Surgical power tools segment across multiple dimensions that determine procurement cycles, service revenue potential, and regulatory pathways. Product type and technology choices dictate replacement frequency and sterilization validation burdens, while application and end-user splits reveal where cordless platforms displace legacy pneumatic infrastructure fastest.
Product Type:
Replacement cycles vary dramatically across instrument categories, with high-wear cutting tools turning over fastest while precision handpieces endure longer amortization schedules.
- Drills:Rotary instruments operating at 5,000 to 15,000 RPM for cortical bone penetration and fixation hole preparation. Demand concentrates in United States ambulatory surgery centers performing same-day joint procedures, driven by instrument wear from high-volume arthroplasty workflows.
- Reamers:Tapered cutting instruments generating precise medullary canal geometry for implant seating. German orthopedic departments specify these for revision arthroplasty cases, where bone quality variability demands frequent attachment replacement.
- Saws:Oscillating or reciprocating blades for osteotomy and bone resection. Used extensively in trauma and joint reconstruction settings.
- Handpieces:Reusable motor housings interfacing with sterile attachments. Central to modular instrument systems across European hospital networks.
- Oscillating Tools:Multi-purpose instruments for soft tissue and bone work. Deployed in plastic and reconstructive surgical suites.
- High-Speed Cutters:Precision instruments exceeding 60,000 RPM for fine bone removal. Essential in spinal decompression and neurosurgical access procedures.
Drills anchor the volume base while high-speed cutters gain share at the steepest rate.
Technology:
Cost tiers separate tethered infrastructure-dependent systems from premium cordless platforms that eliminate pneumatic installation requirements.
- Battery Powered:Lithium-ion cell architectures delivering sustained torque without compressed gas lines. United States integrated delivery networks prioritize these for new ambulatory facility construction, avoiding sunk pneumatic infrastructure costs.
- Cordless:Battery-integrated handpieces with sealed sterilizable housings. German university hospitals specify these for operating theater flexibility, though battery degradation drives replacement economics.
- Pneumatic:Compressed-air-driven systems dominating legacy installed bases. Remains prevalent in facilities with existing gas infrastructure.
- Electric:Mains-powered motors with corded sterilizable attachments. Common in fixed-installation operating theaters.
- Hydraulic:Fluid-pressure systems for high-torque applications. Limited deployment in specialized orthopedic settings.
- Corded:Tethered power delivery with continuous electrical supply. Retained in cost-sensitive procurement environments.
Pneumatic systems retain the largest installed base while battery-powered platforms expand most quickly.
Application:
Procedure volume and instrument wear rates create divergent margin profiles across surgical specialties.
- Orthopedic Surgery:Joint reconstruction, trauma fixation, and sports medicine procedures driving highest instrument consumption. China scales these programs through hospital network expansion, generating recurring attachment replacement demand.
- Spinal Surgery:Decompression and fusion procedures requiring fine cutting geometries and navigation integration. United States specialty centers pay premium pricing for precision reamer systems.
- Neurosurgery:Cranial access and tumor resection with strict thermal management requirements. Demands highest motor control precision.
- Plastic Surgery:Craniofacial and aesthetic procedures with lower instrument wear rates. Smaller addressable market.
- Dental Surgery:Implant placement and bone grafting with specialized attachment geometries. Distinct regulatory pathway.
- ENT Surgery:Sinus and airway procedures using micro-cutting attachments. Niche volume segment.
Orthopedic surgery commands the revenue base while spinal surgery climbs the fastest.
End User:
Customer type determines procurement authority, service contract structure, and sterilization workflow integration.
- Hospitals:Acute care facilities with centralized sterile processing departments. United States hospital networks negotiate enterprise service agreements bundling maintenance with capital placement.
- Ambulatory Surgery Centers:Same-day procedure facilities prioritizing cordless portability and rapid turnover. German outpatient networks drive subscription-based leasing adoption.
- Specialized Surgical Centers:Orthopedic and spine-focused facilities with dedicated instrument inventories. Require specialized technical service footprints.
- Dental Clinics:Private practices with lower-volume procurement and distinct distributor relationships. Separate from hospital supply chains.
Hospitals anchor the volume base while ambulatory surgery centers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, and China concentrate purchasing authority for surgical power tools, with ambulatory surgery networks in each market accelerating cordless platform adoption.
United States
Integrated delivery networks in Texas and Florida are constructing same-day joint replacement facilities that specify battery-powered drill systems without pneumatic infrastructure. FDA 510(k) clearance pathways for powered surgical instruments maintain predicate-based review timelines that favor established manufacturers with extensive submission histories. The Greater Boston medical technology cluster hosts service facilities that perform rapid-turnaround repairs for sealed handpiece battery modules.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia are unbundling maintenance contracts from hardware purchases, forcing suppliers to compete on transparent service pricing. EU MDR technical documentation requirements for Class IIa powered surgical instruments extend product development timelines by twelve to eighteen months. The Tuttlingen surgical instrument manufacturing cluster maintains in-house production capabilities for sterilizable handpiece components serving European hospital networks.
China
Hospital network expansion in Jiangsu and Zhejiang provinces is scaling orthopedic surgery programs that generate recurring attachment replacement demand. The national pharmaceutical regulator NMPA enforces biocompatibility testing standards for powered surgical instruments that align with international ISO 10993 protocols. The Yangtze River Delta medical device manufacturing corridor is attracting power tool assembly investments under government PLI scheme incentives for domestic production.
Japan
Metropolitan Tokyo hospital systems are integrating cordless platforms with existing surgical navigation infrastructure for spinal fusion procedures. PMDA regulatory review maintains stringent electrical safety standards under IEC 60601 frameworks for battery-powered medical devices. The Osaka-Kobe medical technology cluster specializes in precision motor control systems for high-speed neurosurgical cutters.
India
Corporate hospital chains in Maharashtra and Karnataka are expanding procurement of powered instrumentation for trauma and joint reconstruction workflows. The Central Drugs Standard Control Organization CDSCO is harmonizing medical device registration requirements with ASEAN regulatory frameworks to accelerate market access. The Delhi-NCR medical device assembly corridor is developing component sourcing relationships for lithium-ion battery packs in cordless surgical handpieces.
Global Surgical Power Tools Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: diversified medical technology conglomerates with service infrastructure breadth, orthopedic-focused instrument specialists with procedure-specific attachment portfolios, and component manufacturers with captive motor or sterilization capabilities. Dominant competitive moves include strategic partnerships bundling maintenance with hardware placement and backward integration into battery cell or precision motor supply.
Among diversified medical technology conglomerates, Medtronic, Stryker, and Johnson & Johnson exemplify channel-controlling positions that leverage enterprise service agreements across hospital networks. These entities represent archetypes that sustain recurring revenue through subscription-based leasing programs and rapid-turnaround technical service footprints. Their scale positions anchor competitive dynamics in the United States and German procurement frameworks where bundled offerings penetrate integrated delivery networks.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Zimmer Biomet |
| Johnson & Johnson |
| CONMED Corporation |
| B. Braun |
| Arthrex |
| DePuy Synthes |
| Karl Storz |
| Others |
Supply & Pricing Matrix
Rare earth magnet supply chain concentration in Chinese processing facilities exposes battery-powered surgical handpiece manufacturers to simultaneous cost volatility and tiered pricing compression. This single-source dependency for neodymium-dysprosium motor assemblies forces premium cordless platforms to absorb commodity spikes while economy pneumatic systems exploit fixed infrastructure amortization.
Pricing Analysis
Cost-plus contracts with rare earth magnet indexation dominate procurement between motor suppliers and handpiece assemblers. Three-tier pricing structure across premium cordless, standard electric, and economy pneumatic levels separates sterilizable battery platforms with EU MDR certification from uncertified corded alternatives. Pricing pressure stems from German hospital networks unbundling maintenance contracts and demanding transparent service pricing. Ambulatory surgery centers exhibit highest price sensitivity due to capital-constrained procurement frameworks, while United States integrated delivery networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Export-control regimes restricting high-performance rare earth magnet technology flows from China to Western motor manufacturers fragment supplier qualification pathways. Handpiece assembly concentrates in Germany, China, and the United States, while lithium-ion cell production feeds from South Korean and Japanese chemical suppliers. Supply chain risk centers on single-source vulnerability for precision-machined sterilizable housings from Tuttlingen-area specialists. Distribution runs through hospital group purchasing organizations and specialized surgical instrument distributors with regional technical service footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-powered surgical power tools are approaching a platform-economics inflection where interoperability with surgical navigation systems and sterilization tracking software determines competitive viability. This ecosystem shift rewards suppliers controlling both hardware architecture and data interface protocols.
For Market Incumbents: Pre-empt cordless platform commoditization by backward integration into precision motor manufacturing and captive battery cell supply. Lock in hospital network relationships through subscription-based leasing programs that bundle rapid-turnaround technical service with hardware placement. Defend against emerging Asian manufacturers by accelerating EU MDR certification timelines for next-generation handpiece geometries.
For New Entrants and Emerging Players: India's underpenetrated corporate hospital chains in Maharashtra and Karnataka offer white-space expansion with government PLI scheme production incentives. Target neurosurgical micro-cutting attachments where premium pricing and faster replacement cycles exceed standard orthopedic margins. Enter through distributor partnerships with existing technical service infrastructure rather than building captive repair networks.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component manufacturers with captive sterilizable housing production and motor control algorithm IP. Acquisition targets should demonstrate established notified body relationships for EU MDR technical documentation and regional service footprints in United States or German procurement clusters. Monitor FDA 510(k) clearance velocity and EU MDR certificate issuance rates as early signals of competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Stricter clinical evidence requirements for Class IIa powered instruments consolidate supplier relationships around established quality systems. |
| Battery Supply Agreement | Lithium-ion cell chemistry partnerships with South Korean or Japanese suppliers secure energy density improvements for multi-hour orthopedic cases. |
| Hospital System Partnership | Enterprise service agreements with United States integrated delivery networks bundle maintenance with capital placement for recurring revenue. |
| Sterilizable Component Backward Integration | In-house production of handpiece housings controls quality thresholds and accelerates autoclave-cycle verification timelines. |
| Software Companion Development | Navigation system integration and sterilization tracking interfaces determine competitive viability in German university hospital procurement. |
Research Methodology
A spread of perspectives from orthopedic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and power tool manufacturer product managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR certificate registries, hospital procurement contract disclosures, and trade flow records for surgical instrument imports. Bottom-up attachment replacement modeling and top-down healthcare capital expenditure triangulation anchored volume estimates.
Demand-supply balance framing shaped the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, technology platform, surgical application specialty, and end-user facility category. CAGRs derived from procedure volume growth trajectories, instrument wear rate assumptions, and cordless platform penetration curves. Industry-specific inputs incorporated lithium-ion energy density improvement timelines and EU MDR technical documentation extension effects on product launch cadence.
Practitioners should monitor rare earth magnet export control escalations, EU MDR notified body capacity constraints, and ambulatory surgery center construction permitting velocity for early signals of forecast deviation. Material shifts in Chinese rare earth processing policy or FDA predicate-device pathway reform would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
Animal Ultrasound Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Slit Lamps Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Gel Implants Market
Medical Devices
Retinal Implant Market
Medical Devices
PDA Closure Devices Market