

Balloon Catheters for Bile Stone Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Balloon Catheters for Bile Stone Removal Market Insights
Japanese medical device manufacturing is recalibrating output priorities as domestic OEMs expand catheter production lines for biliary applications. Boston Scientific leverages integrated endoscopy platforms to bundle balloon catheters with visualization systems across North American hospital networks. Cook Medical anchors its position through deep specialization in interventional radiology and gastroenterology accessories, sustaining long-term contracts with academic medical centers.
Balloon catheters for bile stone removal are elastomeric devices with inflatable distal segments, typically constructed from polyurethane or silicone composites, designed for dilating strictured bile ducts and extracting obstructing calculi during minimally invasive procedures. The double-lumen configuration dominates current procedural preference because simultaneous guidewire retention and contrast injection reduce operative complexity, while single-lumen variants retain cost-sensitive positioning in emerging markets. Endoscopic retrograde procedures generate the largest procedural volume segment, though percutaneous transhepatic approaches are gaining traction for complex intrahepatic stone burdens where endoscopic access proves anatomically challenging.
The FDA's 510(k) clearance framework governs device entry into the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for balloon catheter CE marking across European markets. Japan's PMDA maintains distinct quality management system inspections that shape manufacturing location decisions for Asia-Pacific suppliers. Stakeholders must monitor evolving reimbursement thresholds for outpatient biliary procedures as payers recalibrate coverage for same-day interventions.
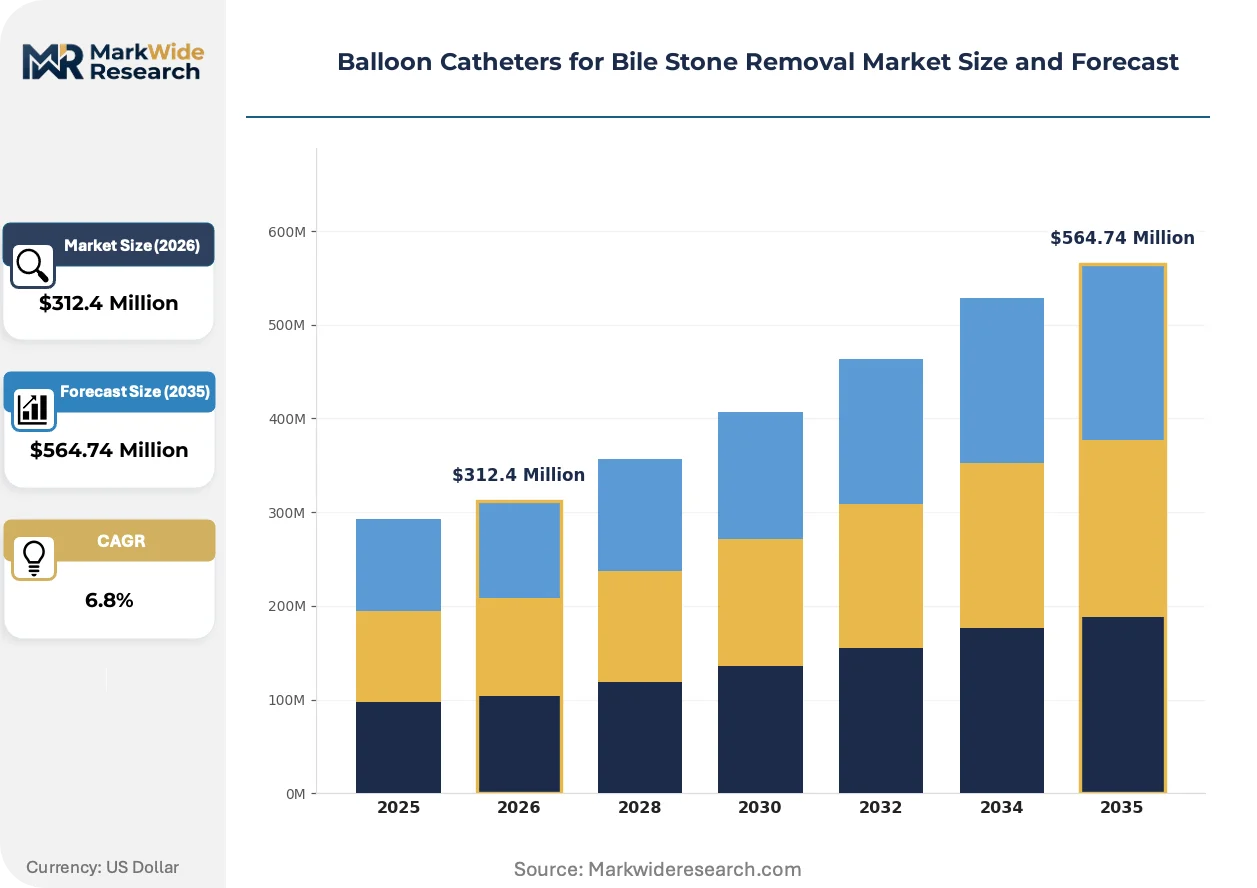
Market Dynamics
The shift toward same-day biliary interventions is compressing hospital length-of-stay metrics and redirecting procedural volume toward outpatient-capable facilities. This structural force is reshaping capital allocation across catheter manufacturers and endoscopy platform suppliers.
Growth Catalysts
- Outpatient Reimbursement Expansion:CMS payment adjustments for ambulatory surgery centers in the United States are accelerating site-of-service migration for ERCP procedures.
- Polyurethane Material Advances:Enhanced elastomeric composites are improving balloon compliance profiles and reducing procedural failure rates in complex stricture dilations.
- EU MDR Harmonization:Streamlined CE marking pathways under the Medical Device Regulation are reducing time-to-market variance across European notified bodies.
Market Restraints
- Silicone Feedstock Volatility:Medical-grade silicone price fluctuations are compressing gross margins for catheter manufacturers dependent on balloon membrane supply.
- Single-Source Component Risk:Concentrated production of high-pressure inflation lumens in select German precision extrusion facilities creates supply vulnerability.
- Endoscopist Training Bottlenecks:Prolonged credentialing timelines for advanced ERCP techniques are limiting procedural throughput expansion in community hospitals.
Strategic Opportunities
- India Community Hospital Penetration:Underdeveloped biliary intervention infrastructure in tier-2 and tier-3 Indian cities presents first-mover positioning for cost-optimized catheter portfolios.
- AI-Enhanced Fluoroscopy Integration:Convergence of real-time stone localization algorithms with balloon catheter deployment systems is reducing radiation exposure and contrast utilization.
- Japan's Aging Infrastructure Incentive:METI subsidies for domestic medical device manufacturing are attracting catheter production facility investments to Osaka and Aichi prefectures.
Industry Challenges
- Specialized Interventionalist Shortage:The limited pipeline of gastroenterologists completing advanced therapeutic endoscopy fellowships is constraining addressable procedure growth.
- 510(k) Predicate Device Scarcity:FDA clearance pathways for novel balloon catheter designs face narrowing predicate options, extending regulatory timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balloon Catheters for Bile Stone Removal Market Trends and Innovations
Digital integration and material science advances are converging to redefine procedural efficiency benchmarks in biliary stone management. These developments are compressing the gap between diagnostic imaging and therapeutic intervention.
Shape-memory polymer balloon membranes are integrating pressure-responsive expansion characteristics that adapt to ductal anatomy without operator adjustment. Academic medical centers in the United States are piloting these systems for complex intrahepatic stone burdens. This material transition is integrating autonomous compliance control into catheter design, reducing fluoroscopy time and contrast volume per procedure.
The EU Medical Device Regulation's enhanced clinical evidence requirements are mandating prospective registry data for Class IIa balloon catheter renewals. Manufacturers must now submit post-market surveillance documentation spanning multiple member states. Smaller catheter producers without dedicated regulatory affairs infrastructure are consolidating or exiting the European market entirely.
Hospital procurement committees are unbundling balloon catheter purchasing from endoscopy platform bundling arrangements. Independent catheter sourcing is gaining traction among United States IDNs seeking to decouple device costs from capital equipment leases. This disintermediation is most visible in the Southeast and Midwest regions where GPO leverage has historically favored integrated supplier contracts.
Balloon Catheters for Bile Stone Removal Market Segmentation
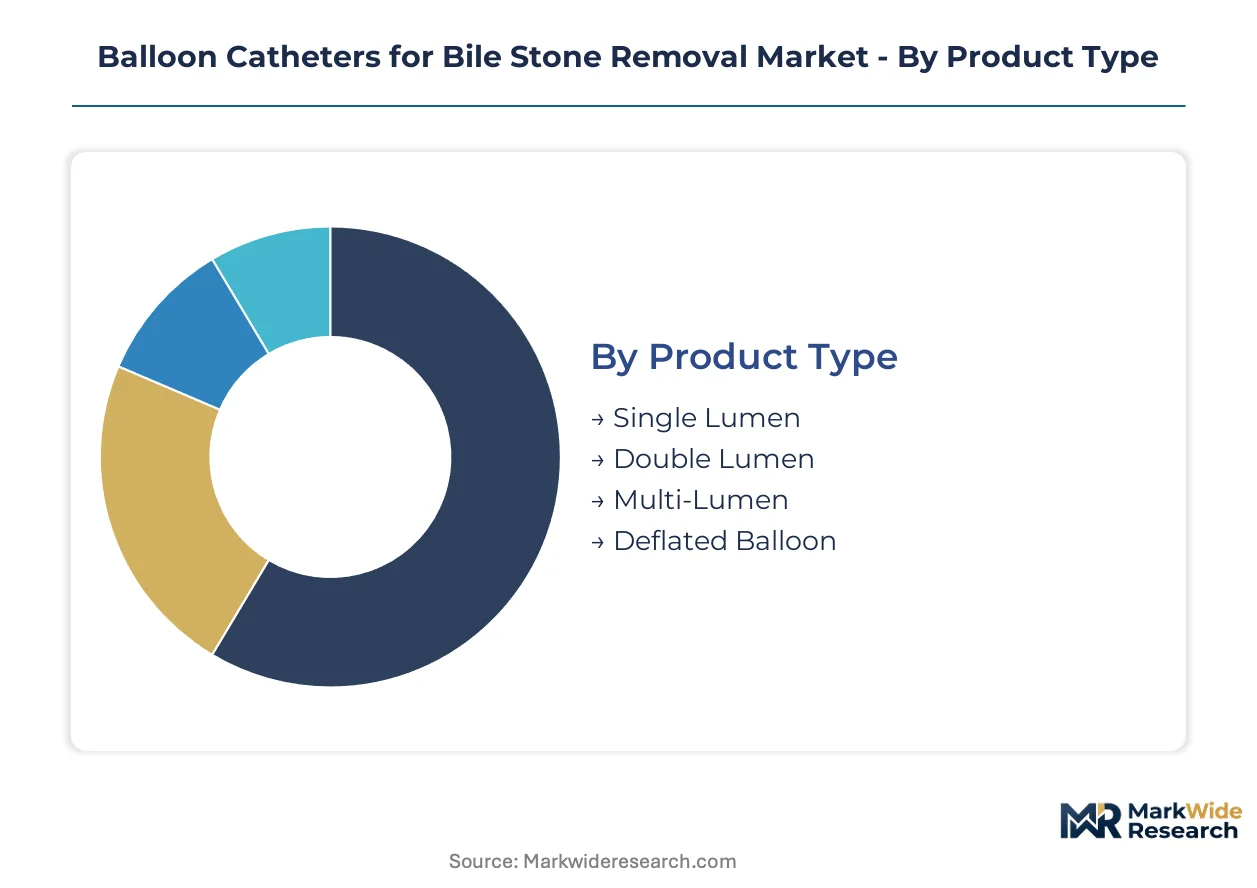
Balloon catheter segmentation reflects divergent technical requirements across biliary anatomies and care delivery settings. Specification choices determine reimbursement eligibility, procedural workflow compatibility, and manufacturing cost structures for suppliers competing across multiple clinical environments.
Product Type:
Catheter architecture governs guidewire management, contrast delivery, and inflation pressure tolerance during stone extraction sequences.
- Single Lumen:Simplified construction with one continuous channel for balloon inflation only. Cost-sensitive positioning in Indian and Southeast Asian public hospital tenders where basic stricture dilation dominates procedural volume.
- Double Lumen:Parallel channels enable simultaneous guidewire retention and contrast injection through the same device. Demand concentrates in United States ambulatory surgery centers where CMS reimbursement codes reward reduced operative complexity and shorter room turnover times.
- Multi-Lumen:Three or more discrete channels support pressure monitoring, irrigation, and accessory instrument passage. Academic medical centers in Germany and Japan deploy these configurations for complex intrahepatic stone burdens requiring multiple tool exchanges.
- Deflated Balloon:Pre-shaped collapsed membrane designed for low-profile insertion through tight strictures. Compact packaging reduces sterilization logistics costs for high-volume outpatient facilities in Texas and Florida.
Double Lumen leads on scale; Multi-Lumen leads on momentum.
Therapy Area:
Stone location dictates catheter compliance requirements, working length specifications, and retrieval accessory compatibility.
- Cholangiolithiasis:Intrahepatic duct stones proximal to the hilum. Japanese tertiary centers drive specialized catheter demand for percutaneous transhepatic approaches where endoscopic access fails anatomically.
- Choledocholithiasis:Common bile duct stones represent the dominant procedural category. United States gastroenterology centers generate concentrated catheter consumption through high ERCP volumes in Medicare-aged populations.
- Hepatolithiasis:Recurrent intrahepatic stone formation prevalent in East Asian populations. Chinese hospitals in Guangdong and Sichuan provinces sustain distinct catheter specifications for repeated intervention sequences.
- Gallbladder Lithiasis:Cystic duct stone migration requiring specialized retrieval balloons. Limited catheter differentiation as most cases convert to laparoscopic cholecystectomy in Western markets.
Choledocholithiasis dominates revenue contribution; Hepatolithiasis shows steepest expansion trajectory in Asia-Pacific tertiary networks.
Procedure Type:
Access route selection determines catheter flexibility, radiopacity requirements, and compatibility with fluoroscopy table configurations.
- Endoscopic Retrograde:Duodenoscope-mediated access through the ampulla of Vater. Standard catheter specifications with 180-200cm working length dominate procurement contracts at United States integrated delivery networks.
- Percutaneous Transhepatic:Radiological access through the liver parenchyma. Shorter 80-120cm catheter variants with enhanced torque response gain traction in German interventional radiology departments managing complex stone burdens.
- Surgical Extraction:Open or laparoscopic common bile duct exploration. Declining procedural volume reduces dedicated catheter demand outside emerging markets where surgical infrastructure exceeds endoscopic capacity.
- Lithotripsy Adjunct:Balloon stabilization during electrohydraulic or laser fragmentation. Specialized high-pressure membranes from Japanese suppliers integrate with fragmentation platforms in South Korean academic centers.
Endoscopic Retrograde anchors installed base; Percutaneous Transhepatic is climbing the fastest as anatomical complexity cases migrate to interventional radiology.
End User:
Facility type shapes catheter specification priorities, inventory management protocols, and supplier contracting leverage.
- Specialty Clinics:Focused hepatobiliary practices with limited procedure volume. Cost-optimized single-lumen procurement through group purchasing organizations in the United States Midwest.
- Ambulatory Surgery Centers:Same-day discharge mandates drive demand for reliable double-lumen systems with minimal failure rates. CMS site-of-service payment differentials accelerate capital allocation toward these facilities across Texas, Florida, and Arizona.
- Gastroenterology Centers:High-throughput endoscopy suites with dedicated ERCP programs. Bundled catheter and disposable purchasing from integrated platform suppliers like Boston Scientific dominates hospital-affiliated centers.
- Diagnostic Laboratories:Limited therapeutic role restricts catheter procurement to research or training applications. Minimal commercial significance outside academic credentialing programs.
Ambulatory Surgery Centers lead on volume growth rate; Gastroenterology Centers lead on absolute consumption scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting balloon catheter manufacturing toward jurisdictions with streamlined quality management inspections, while demand concentrates in markets with aging demographics and established endoscopic infrastructure. Production facility investments are clustering where government incentives offset compliance costs.
United States
Medicare reimbursement codes for ambulatory surgery centers are accelerating site-of-service migration for ERCP procedures. The FDA's 510(k) premarket notification pathway governs device clearance timelines and predicate device requirements. Texas and Florida hospital networks are expanding outpatient biliary intervention capacity to capture CMS payment differentials.
Japan
Domestic OEMs are recalibrating output priorities toward biliary catheter production lines as METI subsidies attract manufacturing investments. The PMDA maintains distinct quality management system inspections that shape supplier location decisions. Osaka and Aichi prefectures are emerging as catheter production clusters with concentrated precision extrusion capabilities.
Germany
Interventional radiology departments in academic medical centers are driving demand for complex intrahepatic stone management devices. The EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking renewals. Precision extrusion facilities in Baden-Württemberg supply high-pressure inflation lumens to catheter manufacturers across Europe.
India
Underdeveloped biliary intervention infrastructure in tier-2 and tier-3 cities presents positioning opportunities for cost-optimized catheter portfolios. The CDSCO regulates medical device imports and domestic manufacturing under the Medical Devices Rules. Maharashtra and Karnataka hospital networks are expanding endoscopy suites to address rising choledocholithiasis prevalence.
South Korea
Academic medical centers are piloting AI-enhanced fluoroscopy integration with balloon catheter deployment systems. The MFDS oversees medical device licensing and post-market surveillance requirements. Seoul metropolitan area hospitals are consolidating procurement for lithotripsy adjunct procedures requiring specialized high-pressure membranes.
Balloon Catheters for Bile Stone Removal Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cost-optimized positioning in price-sensitive Asian markets. The vendor base stratifies across integrated platform suppliers, specialized interventional radiology fabricators, and regional cost leaders. Three archetypes dominate: endoscopy platform bundlers, interventional accessory specialists, and precision extrusion component suppliers. Competitive moves concentrate on hospital procurement committee unbundling negotiations and manufacturing facility relocation to capture government incentives.
Within the integrated platform tier, Boston Scientific exemplifies the bundling archetype through combined endoscopy and catheter offerings. Cook Medical occupies a specialist position anchored in interventional radiology and gastroenterology accessories. Olympus represents the visualization-integrated fabricator archetype with duodenoscope-mediated procedural ecosystems. These three entities illustrate how competitive positioning fragments across platform breadth versus clinical specialization vectors.
| Leading Market Players |
|---|
| Boston Scientific |
| Cook Medical |
| Olympus |
| CONMED |
| Medtronic |
| Teleflex |
| B. Braun Melsungen |
| Cardinal Health |
| Terumo |
| Others |
Pricing and Supply Chain Analysis
EU MDR clinical evidence mandates gate qualified supply access and premium-tier pricing eligibility, as manufacturers without dedicated regulatory infrastructure face forced consolidation while compliant producers capture reimbursement-linked procurement contracts across German and French hospital networks. This sustainability-driven regulatory filter concentrates pricing power among firms with multi-state registry capabilities, compressing margins for non-compliant competitors.
Pricing Analysis
Distributor margin layers absorb 15-25 points before hospital procurement committees, with contract-based long-term offtake dominating GPO-negotiated supply agreements for United States integrated delivery networks. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification grade, with German academic medical centers least sensitive and Indian tier-3 public hospitals most price-responsive. Cost compression in single-lumen segments intensifies because polyurethane feedstock volatility forces manufacturers to absorb input swings rather than pass through to tender-sensitive buyers.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Boston Scientific and Cook Medical, while specialized distributors serve mid-tier gastroenterology centers. Geographic supply concentration centers on Germany for precision extrusion, Japan for silicone membrane fabrication, and United States for final sterile packaging. Raw material dependencies draw from medical-grade silicone, high-purity polyurethane granules, and radiopaque filler compounds. Single-source vulnerability in Baden-Württemberg extrusion facilities creates structural risk, as alternative qualified suppliers require 18-24 month qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with METI subsidies in Japan offering 15-20% cost offsets against EU MDR compliance expenditures, redirecting manufacturing investments toward Osaka and Aichi prefectures.
For Market Incumbents: Deploy backward integration into silicone membrane production to offset feedstock volatility exposure. Consolidate regulatory affairs infrastructure across European notified bodies to defend against 510(k) predicate scarcity. Lock in multi-year GPO contracts with United States ambulatory surgery centers before procurement unbundling accelerates in Southeast and Midwest regions. For New Entrants and Emerging Players: CDSCO streamlined import pathways in India open a window for cost-optimized single-lumen portfolios targeting Maharashtra and Karnataka tier-2 hospital expansions. White-space concentration exists in percutaneous transhepatic catheter variants for German interventional radiology departments. Pursue direct tender participation rather than distributor-dependent models to capture public hospital procurement volume. For Investors and Strategic Acquirers: Roll-up economics work for precision extrusion specialists because EU MDR compliance costs force smaller catheter producers toward exit or acquisition. Monitor PMDA quality management inspection queue depth as inflection indicator for Japanese manufacturing capacity allocation shifts. Long-term viability favors targets with dual FDA-CE marking capabilities and established academic medical center relationships.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates United States market entry for novel double-lumen configurations. |
| CE Marking Pathway | Unlocks German and French procurement contracts under EU MDR harmonization. |
| Hospital System Partnership | Secures bundled catheter purchasing with Texas and Florida ASC networks. |
| Software Companion Development | Enables AI-enhanced fluoroscopy integration piloted in South Korean academic centers. |
| Reimbursement Strategy | Aligns CMS site-of-service codes with ambulatory surgery center expansion. |
Research Methodology
Multiple input streams — structured interviews with interventional radiologists and gastroenterologists, GPO contracts managers, and biomedical engineers at academic medical centers — were reconciled against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and Japanese PMDA quality inspection records. Bottom-up catheter unit demand estimates from hospital procurement systems were triangulated with top-down manufacturer production capacity assessments.
Data-stream reconciliation anchored volume projections across product type, therapy area, procedure type, and end user segments throughout the forecast period. CAGRs were derived from procedural volume elasticity to aging demographic shifts and reimbursement rate adjustments. Industry-specific inputs incorporated endoscopist fellowship completion rates and ambulatory surgery center capital expenditure cycles.
Revisions become necessary when silicone feedstock price volatility exceeds historical bands or when FDA predicate device availability constricts novel catheter clearance pathways. Forecasts reflect documented assumptions regarding CMS payment stability and EU MDR inspection timeline consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.