
 Slit Lamps Market | 2026-2036
Slit Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Slit Lamps Market Analysis
Outpatient eye care centers is rotating toward table-top and digital slit lamp configurations as hospital budget constraints shift procurement authority to clinic networks. Haag-Streit Group leverages its Swiss manufacturing heritage to sustain premium positioning in optical precision instruments. TOPCON Corporation anchors its competitive stance through integrated diagnostic platforms that combine slit lamp examination with fundus imaging capabilities. ZEISS Group differentiates via advanced optical engineering and established relationships with academic medical centers.
A slit lamp is a binocular microscope with an adjustable light source that produces a thin beam of illumination, enabling stereoscopic examination of anterior and posterior ocular structures at magnifications typically ranging from 6x to 40x. The device serves as the foundational diagnostic tool for assessing corneal pathology, cataract progression, and anterior chamber depth in clinical ophthalmology. Table-top configurations retain the dominant installed base due to optical stability and ergonomic design for high-volume practices, while digital slit lamps capture growing interest as teleophthalmology and remote consultation protocols expand. Enhanced imaging technology commands premium pricing by integrating anterior segment optical coherence tomography and high-resolution photography into the examination workflow.
The FDA regulates slit lamps as Class II medical devices under 21 CFR 886.1850, requiring substantial equivalence demonstrations for market clearance and shaping product development timelines for manufacturers targeting the United States. The EU Medical Device Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations on devices bearing CE marking, altering competitive dynamics for European market access. China's NMPA implements national standards for ophthalmic instrument safety and performance that influence design specifications for products distributed through domestic procurement channels. Stakeholders must monitor how divergent regulatory timelines across these jurisdictions affect product launch sequencing and capital allocation for R&D portfolios.
Market Dynamics
Teleophthalmology protocols are compressing the installed base lifecycle for traditional optical instruments, forcing manufacturers to accelerate digital imaging integration timelines and recalibrate service revenue models around software subscriptions rather than hardware replacement cycles.
Growth Catalysts
- EU Medical Device Regulation:Stricter clinical evidence requirements for CE marking are elevating barriers for low-cost competitors, creating premium positioning opportunities for established optical engineering firms with robust quality management systems.
- Outpatient clinic networks:Decentralized eye care delivery is generating demand for portable diagnostic configurations that maintain optical precision without fixed installation requirements.
- Anterior segment OCT convergence:Integration of optical coherence tomography into slit lamp platforms is expanding reimbursable procedure codes and capturing higher per-examination revenue for ophthalmology practices.
Market Restraints
- Optical component supply concentration:German and Japanese precision lens manufacturers control critical supply tiers, exposing downstream device assemblers to extended lead times during demand surges.
- High-resolution sensor cost volatility:CMOS and CCD imaging sensors face price instability tied to semiconductor fabrication capacity allocation, compressing margin buffers for mid-tier device configurations.
- Fundus camera substitution:Dedicated retinal imaging systems are capturing anterior segment examination workflows in primary care settings, narrowing the addressable market for conventional slit lamp-only installations.
Strategic Opportunities
- Rural China penetration:County-level hospital procurement programs under centralized purchasing organizations are creating volume opportunities for domestically manufactured digital configurations meeting NMPA performance standards.
- Artificial intelligence diagnostic overlay:Machine learning algorithms for automated cataract grading and corneal pathology detection are opening software-as-a-service revenue streams atop hardware platforms.
- Direct-to-consumer telehealth channels:Remote consultation platforms are incubating demand for patient-operated anterior segment imaging devices with simplified optical alignment mechanisms.
Industry Challenges
- Optomechatronics engineering scarcity:The intersection of precision optics, mechanical stability, and digital imaging expertise commands premium compensation, constraining R&D team scaling for mid-size manufacturers.
- FDA 510(k) substantial equivalence pathway:Predicate device identification and clinical comparison studies extend clearance timelines, delaying product launches and accelerating capital burn during development phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slit Lamps Market |
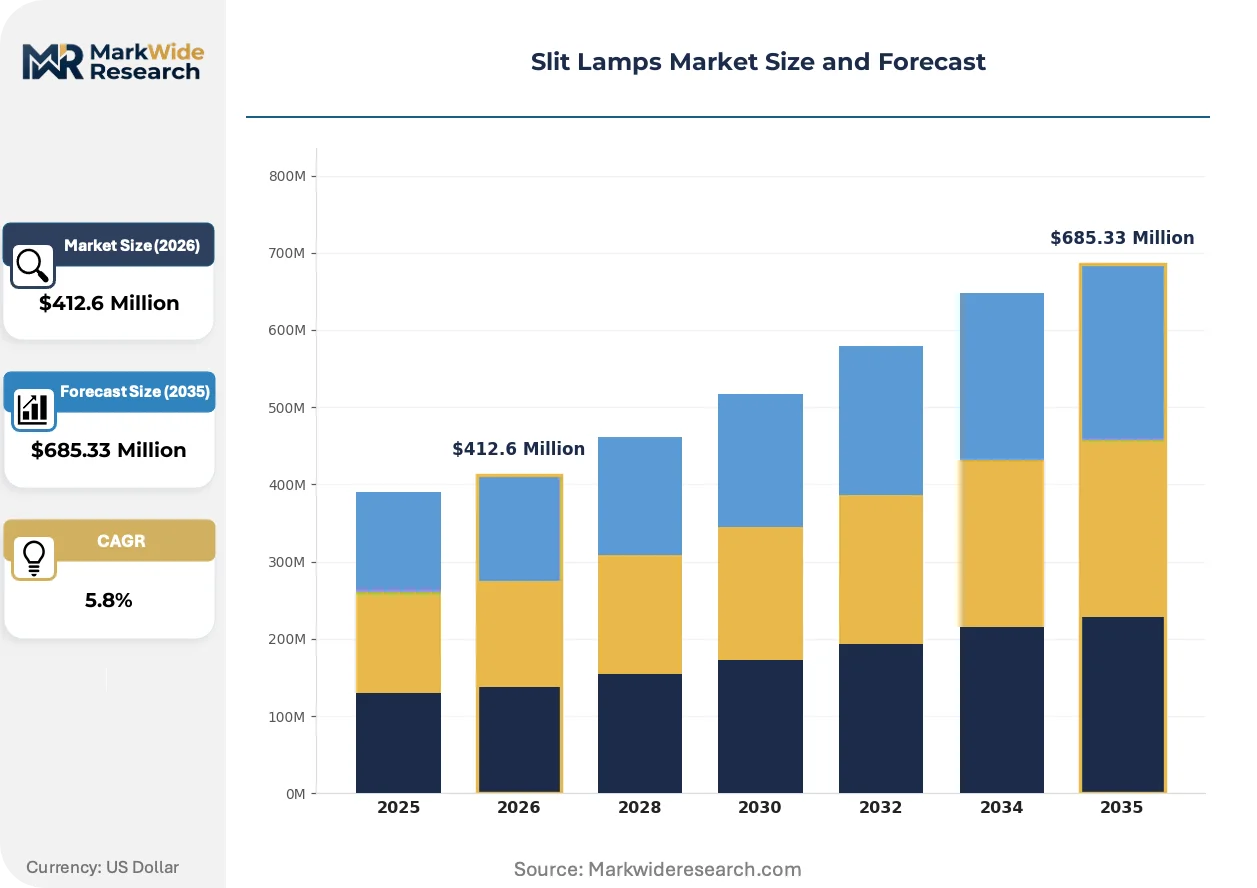
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Table-Top, Digital, LED End User: Ophthalmology Clinics, Hospitals, Research Labs, Eye Care Centers Technology: Optical Coherence Tomography, Traditional Slit Lamp, Enhanced Imaging, Automated Application: Diagnostic Procedures, Surgical Planning, Research Studies, Education |
| Companies Covered | Haag-Streit Group, TOPCON Corporation, ZEISS Group, NIDEK CO., LTD, Keeler, Reichert, Inc., Takagi Seiko Co., Ltd, Inami & CO., Ltd, HEINE Optotechnik GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slit Lamps Market Emerging Trajectories
Digital imaging architectures are displacing purely optical examination workflows, while regulatory frameworks on both sides of the Atlantic recalibrate evidence requirements for diagnostic device market access. These forces are compressing traditional product development cycles and redistributing competitive advantage toward software-integrated platform providers.
Portable slit lamp configurations with battery-powered LED illumination and wireless image transmission are miniaturizing the examination footprint without sacrificing stereoscopic visualization quality. Community health centers and mobile screening programs are adopting these units for diabetic retinopathy detection campaigns. The technology is miniaturizing hardware margins while expanding addressable patient populations beyond traditional clinic infrastructure constraints.
The EU Medical Device Regulation's post-market surveillance obligations are mandating systematic clinical follow-up data collection for CE-marked diagnostic ophthalmic equipment. Manufacturers must establish European Authorized Representatives and maintain vigilance systems reporting adverse events within compressed timeframes. High-volume product lines face disproportionate compliance cost absorption, favoring diversified diagnostic platform portfolios over single-device specialists.
Hospital group purchasing organizations in China are consolidating procurement authority for ophthalmic instruments under provincial centralized tendering mechanisms. Domestic distributors are losing direct hospital relationships as manufacturers engage procurement platforms directly. This concentration is most visible in tertiary hospital networks across Jiangsu and Guangdong provinces, where annual volume commitments determine pricing tiers and exclusive supply arrangements.
Slit Lamps Market Segmentation
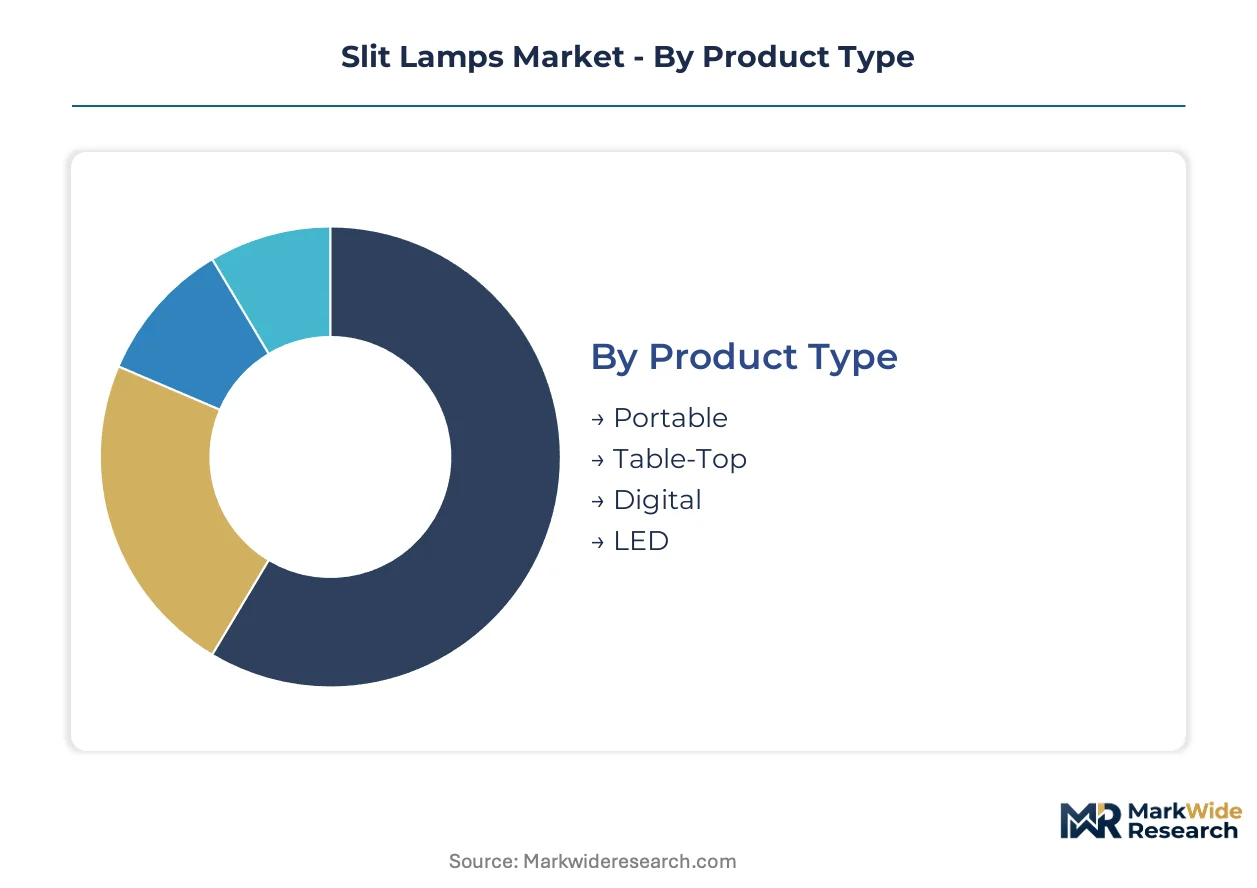
Slit lamp purchasing decisions split across optical precision requirements, facility infrastructure constraints, and reimbursement code eligibility. Each segmentation dimension carries distinct margin profiles and competitive intensity levels that shape manufacturer portfolio prioritization.
Product Type:
Portable configurations face the most acute substitution pressure from smartphone-mounted anterior segment adapters, while fixed installations defend against erosion through integrated diagnostic workflows.
- Table-Top:Fixed-base optical systems with mechanical stability and superior illumination control dominate high-volume ophthalmology practices. Hospital procurement in China and Germany concentrates on these units for tertiary care networks, though budget compression is elongating replacement cycles.
- Digital:CMOS-integrated imaging platforms with wireless transmission enable teleophthalmology consultations and electronic health record documentation. Outpatient clinic networks in the United States and Japan are prioritizing these configurations as remote consultation protocols expand reimbursable service codes.
- Portable:Battery-powered LED units with collapsible optical paths serve mobile screening programs and community health centers.
- LED:Solid-state illumination modules replace halogen sources across retrofit and new installation categories.
Table-Top configurations anchor the volume base while Digital variants gain share at the steepest rate.
End User:
Cost tier stratification separates capital-rich hospital systems from price-sensitive independent practitioners, with research institutions occupying a narrow premium niche.
- Ophthalmology Clinics:Independent and group practice settings generate the highest procedure volume per installed unit, with purchasing authority shifting toward clinic network administrators rather than individual physicians. NMPA procurement platforms in China are consolidating these buyers under provincial tendering mechanisms.
- Hospitals:Integrated delivery networks demand multi-function diagnostic platforms with interoperability certifications for picture archiving systems. EU Medical Device Regulation compliance costs are favoring established suppliers with diversified service capabilities in France and Germany.
- Research Labs:Academic medical centers and contract research organizations specify custom optical configurations for longitudinal studies.
- Eye Care Centers:Retail-oriented vision care chains prioritize patient throughput and space efficiency over advanced imaging capabilities.
Hospitals command the highest per-unit expenditure while Ophthalmology Clinics generate the steepest expansion trajectory in absolute installation growth.
Technology:
Application-driven specification divergence separates reimbursable diagnostic codes from capital equipment categories, with margin concentration in integrated imaging modules.
- Enhanced Imaging:High-resolution photography and anterior segment optical coherence tomography integration capture premium pricing by expanding reimbursable procedure codes. ZEISS and TOPCON are anchoring competitive positioning through proprietary software ecosystems that lock in recurring revenue streams.
- Optical Coherence Tomography:Cross-sectional tomographic imaging modules embedded within slit lamp platforms enable quantitative corneal thickness measurement and angle assessment. FDA 510(k) clearance pathways for these hybrid devices are extending development timelines for manufacturers targeting the United States market.
- Traditional Slit Lamp:Pure optical examination without digital capture retains installed base dominance in emerging markets and resource-constrained settings.
- Automated:Motorized alignment and image acquisition systems reduce operator dependence for screening applications.
Traditional Slit Lamp technology anchors the installed base while Enhanced Imaging climbs the fastest on revenue contribution.
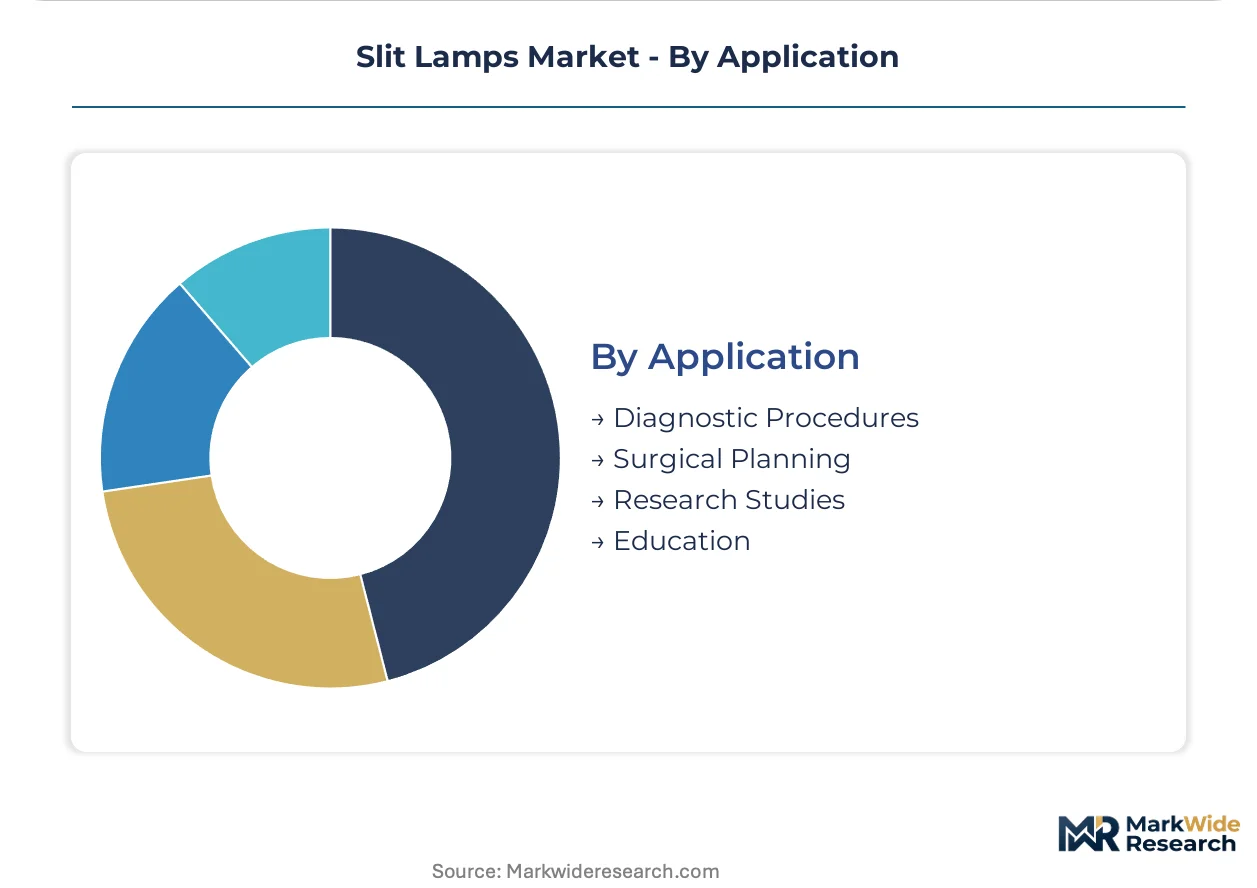
Application:
Customer type differentiation separates episodic surgical planning from recurring diagnostic revenue, with education representing a low-volume, high-visibility reference market.
- Diagnostic Procedures:Routine anterior and posterior segment examination constitutes the core clinical utility, with reimbursement rates determining equipment amortization periods. Germany's statutory health insurance system maintains favorable fee schedules for comprehensive slit lamp examinations compared to primary care markets.
- Surgical Planning:Pre-operative cataract grading and intraocular lens calculation workflows demand precise biometry integration. Academic medical centers in Switzerland and Japan are specifying these configurations for residency training programs.
- Research Studies:Longitudinal clinical trials and epidemiological surveys require calibrated, reproducible imaging protocols.
- Education:Teaching institutions and simulation centers purchase units for skills training and competency assessment.
Diagnostic Procedures anchor the volume base while Surgical Planning gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement managers and outpatient clinic administrators concentrate purchasing authority across three dominant markets. The United States, Germany, and China account for the majority of installed base replacements and first-time digital platform acquisitions.
United States
Academic medical centers in Boston and the Research Triangle anchor demand for integrated diagnostic platforms with OCT capabilities. FDA 510(k) substantial equivalence requirements extend clearance timelines for hybrid imaging devices. The Cleveland Clinic and Mayo Clinic networks specify multi-function configurations for residency training programs.
Germany
Tertiary hospital networks in Bavaria and Baden-Württemberg prioritize optical precision instruments for cataract surgery planning workflows. EU Medical Device Regulation post-market surveillance obligations favor established suppliers with diversified service capabilities. The Stuttgart and Munich metropolitan clusters concentrate ophthalmic instrument manufacturing and clinical reference sites.
China
Provincial centralized tendering mechanisms in Jiangsu and Guangdong provinces consolidate procurement for county-level hospital networks. NMPA national standards for ophthalmic instrument safety influence design specifications for domestic distribution. Shanghai and Beijing anchor research collaborations between manufacturers and tertiary care institutions.
Japan
Outpatient clinic networks in Tokyo and Osaka drive replacement demand for compact digital configurations with wireless documentation. METI industrial standards for medical device quality management shape supplier qualification processes. The Nagoya medical device cluster supports precision optical component fabrication for regional manufacturers.
Switzerland
Specialized eye hospitals in Zurich and Geneva specify premium optical systems for anterior segment research applications. Swissmedic device registration requirements maintain stringent clinical evidence thresholds for market entry. The Basel pharmaceutical corridor generates crossover demand for diagnostic instruments supporting clinical trial endpoints.
Slit Lamps Market Vendor Landscape
Player mix skews toward diversified optical engineering conglomerates with century-long manufacturing heritage. Market structure concentrates around three tiered positions: premium Swiss and German specialists, integrated Japanese diagnostic platform providers, and mid-tier regional assemblers serving price-sensitive procurement channels. Strategic differentiation centers on proprietary software ecosystems, optical component backward integration, and exclusive supply arrangements with academic medical centers. Capacity expansion and technology licensing represent the dominant competitive moves for maintaining installed base loyalty.
Among the precision optics specialists, Haag-Streit Group and ZEISS Group exemplify the premium-tier archetype through Swiss and German engineering heritage. TOPCON Corporation occupies a position within the integrated diagnostic platform segment, representing the convergence strategy that combines slit lamp examination with complementary imaging modalities. These three manufacturers anchor the competitive structure, with their geographic origins and organizational forms reflecting distinct strategic approaches to regulatory compliance and customer relationship management.
| Leading Market Players |
|---|
| Haag-Streit Group |
| TOPCON Corporation |
| ZEISS Group |
| NIDEK CO., LTD |
| Keeler |
| Reichert, Inc. |
| Takagi Seiko Co., Ltd |
| Inami & CO., Ltd |
| HEINE Optotechnik GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
LED illumination modules replacing halogen sources across retrofit and new installation categories simultaneously shift component sourcing toward East Asian semiconductor foundries and compress aftermarket service revenue margins that historically subsidized hardware pricing. This substitution dynamic concentrates optical component procurement authority with German and Japanese precision lens manufacturers while forcing device assemblers to absorb sensor cost volatility through tiered configuration strategies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Swiss-engineered optical systems from mid-tier integrated platforms and domestically manufactured portable units. Price differentiation hinges on FDA 510(k) clearance status and optical coherence tomography integration depth. Pricing pressure stems from CMOS sensor cost volatility tied to semiconductor fabrication capacity allocation. Independent ophthalmology clinics exhibit highest price sensitivity while academic medical centers prioritize performance specifications over procurement cost.
Supply Chain Analysis
Inventory lead times for high-resolution imaging sensors extend during semiconductor demand surges, exposing device assemblers to production scheduling disruptions. Optical component supply concentrates in Germany, Japan, and Switzerland. Critical inputs include precision-ground lenses, CMOS/CCD sensors, and LED illumination modules. Single-source vulnerability persists for anterior segment OCT subassemblies. Distribution runs through hospital group purchasing organizations in China and integrated delivery networks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital group purchasing organization consolidation across Jiangsu and Guangdong provinces has shifted procurement authority from individual clinicians to centralized tendering platforms, amplifying buyer leverage in volume negotiations.
For Market Incumbents: Compound installed base loyalty through proprietary software ecosystem development and exclusive supply arrangements with academic medical centers. Deepen backward integration into precision optical component manufacturing to defend against German and Japanese lens supplier pricing power. Prioritize CE marking pathway investments ahead of EU Medical Device Regulation surveillance obligation deadlines. For New Entrants and Emerging Players: AI diagnostic overlay services represent an underdeveloped layer where established manufacturers lack specialized machine learning engineering capacity. Target county-level hospital networks in rural China through NMPA-certified digital configurations meeting centralized procurement technical specifications. Deploy software-as-a-service revenue models atop hardware partnerships to bypass capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors platform-integrated diagnostic providers over single-device specialists. Long-term viability centers on recurring software revenue streams rather than hardware replacement cycles. Monitor FDA 510(k) clearance velocity for hybrid OCT-slit lamp devices as inflection indicator for competitive positioning stability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU Medical Device Regulation compliance elevates barriers for low-cost competitors favoring established quality management systems. |
| Software Companion Development | Machine learning algorithms for automated cataract grading open recurring revenue atop hardware platforms. |
| Hospital System Partnership | Exclusive supply arrangements with academic medical centers lock in reference site influence and residency training adoption. |
| Backward Integration into Optics | In-house precision lens production reduces exposure to German and Japanese supplier lead time volatility. |
| Reimbursement Strategy | Anterior segment OCT integration expands reimbursable procedure codes capturing higher per-examination revenue. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ophthalmology clinic administrators, hospital procurement managers, biomedical engineers, and GPO contracts specialists; and secondary validation against FDA 510(k) filings, NMPA registration databases, EU Medical Device Regulation vigilance reports, and hospital procurement platform tender records. Bottom-up installation base modeling and top-down revenue triangulation anchored market size estimation across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product configuration type, end-user facility category, technology integration level, and regional regulatory cluster. CAGRs derived from weighted average replacement cycle analysis and digital platform adoption curve modeling. Forecast inputs incorporated teleophthalmology protocol expansion rates and anterior segment OCT reimbursement code eligibility patterns.
Forecasts assume regulatory continuity in FDA 510(k) substantial equivalence pathways, EU MDR post-market surveillance obligations, and NMPA national standards enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Skincare Devices Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Bathroom and Toilet Assist Devices Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Trocars Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
Neuromodulation Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
ADA Substitute Market