
 Global Submarine Launched Missile Market | 2026-2036
Global Submarine Launched Missile Market Size, Share, and Industry Trends Forecast 2026-2036
Global Submarine Launched Missile Market Foresight
Hypersonic glide vehicle integration is rotating the specification tier upward across major procurement programs. Lockheed Martin Corporation leverages its Trident II D5LE life-extension expertise to sustain long-term contracts with the US Navy. BAE Systems plc anchors European supply chains through its submarine-launched cruise missile work for the Royal Navy. Raytheon Technologies Corporation competes on advanced guidance packages that differentiate its offerings in contested environments.
Submarine launched missiles are self-propelled precision weapons fired from submerged platforms, typically employing solid-propellant rocket motors or turbojet propulsion with ranges from hundreds to thousands of nautical miles depending on type and mission profile. Their primary purpose is to deliver nuclear or conventional payloads against land targets, surface vessels, or strategic infrastructure while exploiting the concealment and survivability of undersea launch platforms. Ballistic missile systems dominate value pools due to their nuclear strategic role and the massive infrastructure required for development and deployment. Cruise missile segments are expanding fastest as conventional strike missions multiply and guidance technology advances enable precision targeting against mobile and hardened objectives.
The US Navy's Strategic Systems Programs office, the UK's Defence Nuclear Organisation, and France's Direction des Applications Militaires each enforce distinct certification standards that shape supplier qualification and technology transfer rules. NATO STANAG frameworks and national nuclear surety protocols further constrain market access, privileging incumbent contractors with cleared supply chains and proven launch histories. Stakeholders must monitor emerging non-proliferation treaty pressures and the spread of dual-use submarine technology to middle-tier naval powers.
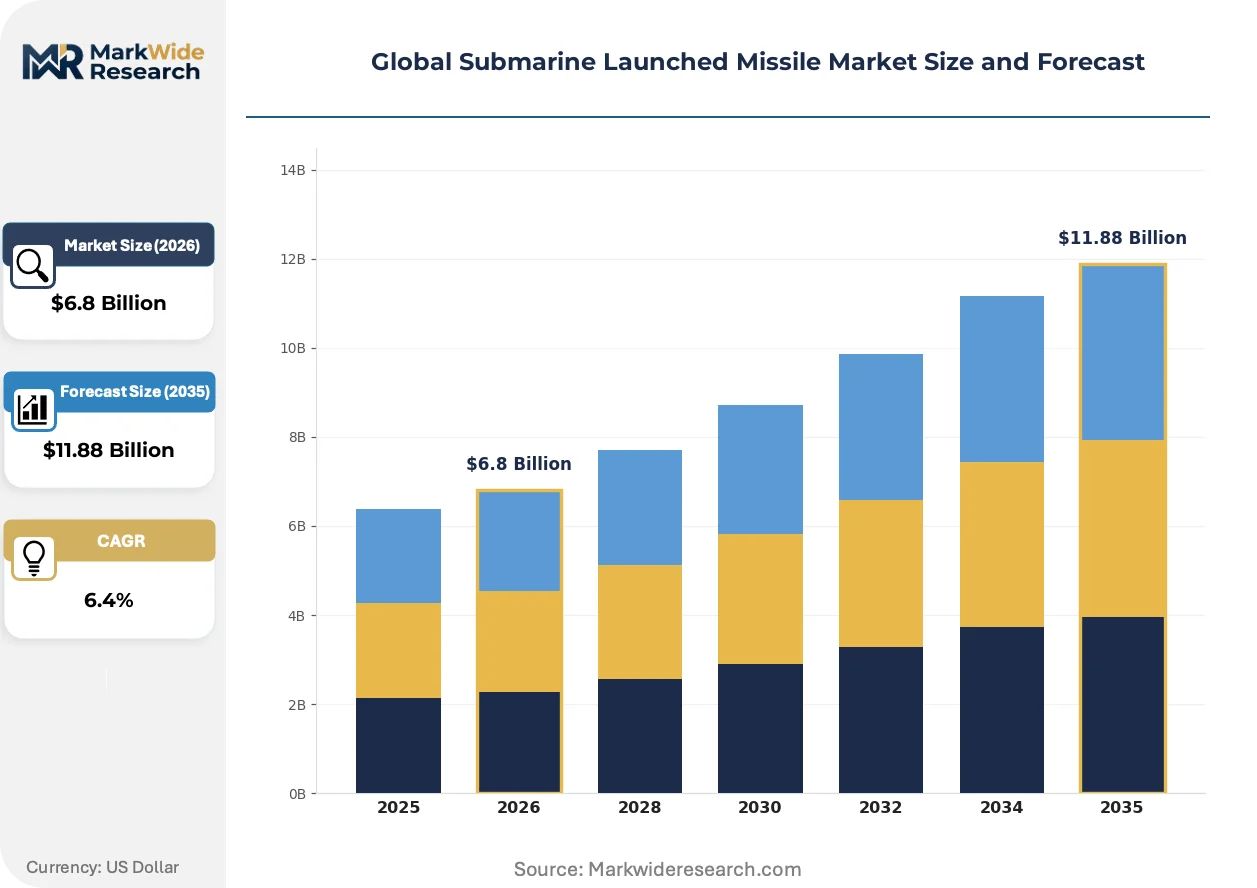
Market Dynamics
Solid-fuel propulsion maturation and reduced acoustic signature requirements are compressing development timelines while expanding performance envelopes across next-generation underwater deterrent programs.
Growth Catalysts
- Hypersonic glide vehicle integration:The US Navy's Strategic Systems Programs office and comparable agencies in Russia and China are mandating maneuverable reentry capabilities that extend strike ranges and complicate missile defense. This specification tier rotation is pulling demand upward across procurement cycles.
- Indo-Pacific maritime disputes:Territorial tensions between China, Japan, and claimant states in the South China Sea are accelerating fleet modernization investments. Submarine-based strike platforms offer concealment advantages that surface vessels cannot match.
- NATO STANAG frameworks:Standardized interoperability protocols for submarine-launched cruise missiles are reducing integration costs for member navies. This regulatory harmonization is expanding addressable market volume across European defense procurement.
Market Restraints
- Weapons-grade plutonium supply concentration:Fuel stockpile availability concentrates in Russia and the United States, constraining warhead production scalability for newer nuclear powers seeking submarine-launched ballistic missile capability.
- Nuclear surety protocol complexity:National certification standards enforced by the UK's Defence Nuclear Organisation and France's Direction des Applications Militaires impose multi-year qualification timelines that extend program costs.
- Acoustic signature reduction costs:Advanced damping materials and precision manufacturing for pump-jet propulsors require specialized titanium alloys and composite formulations with volatile input pricing.
Strategic Opportunities
- Conventional prompt global strike missions:Non-nuclear hypersonic payloads are opening submarine platforms to conventional regional deterrence roles previously reserved for strategic nuclear forces.
- AUKUS technology transfer pathways:The trilateral security pact between Australia, the United Kingdom, and the United States is creating cleared supply chain access for Australian submarine-launched missile integration.
- Dual-use submarine technology diffusion:Middle-tier naval powers including Brazil and South Korea are acquiring air-independent propulsion systems that enable diesel-electric boats to host land-attack cruise missiles.
Industry Challenges
- Systems engineering talent scarcity:The specialized skill set combining underwater launch dynamics, solid-rocket motor design, and nuclear warhead integration concentrates within a handful of cleared national laboratories and prime contractors.
- Legacy platform integration complexity:Newer missile variants must maintain backward compatibility with Ohio-class and Vanguard-class hulls nearing mid-life while accommodating Columbia-class and Dreadnought-class interface specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Submarine Launched Missile Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Missile Type: Ballistic Missile, Cruise Missile, Anti-Ship Missile, Tactical Missile Launch Platform: Diesel-Electric Submarine, Nuclear-Powered Submarine, Midget Submarine, Autonomous Underwater Vehicle Guidance Technology: Inertial Navigation, GPS Guidance, Infrared Homing, Active Radar Homing, Wire-Guided End User: Naval Forces, Defense Contractors, Maritime Security Agencies, Strategic Command Units |
| Companies Covered | Lockheed Martin Corporation, BAE Systems plc, Raytheon Technologies Corporation, Northrop Grumman Corporation, General Dynamics Corporation, MBDA, The Boeing Company, BrahMos Aerospace, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Submarine Launched Missile Market Shifts & Advancements
Guidance package miniaturization and multi-domain targeting architectures are redefining mission flexibility for submerged launch platforms. These advances are compressing the capability gap between strategic ballistic and tactical cruise missile systems.
Hypersonic boost-glide technology is bifurcating the ballistic missile segment into traditional parabolic trajectory systems and maneuverable atmospheric flight vehicles. The US Navy and Chinese People's Liberation Army Navy are prioritizing the latter for their second-strike survivability advantages. This technology trajectory is forcing legacy Trident-class life-extension programs to incorporate modular payload bays capable of hosting mixed conventional-nuclear loads.
EU dual-use export control regulations and the Wassenaar Arrangement are tightening technology transfer restrictions on submarine-launched cruise missile subsystems. European prime contractors are responding by localizing guidance computer production within member states to maintain access to integrated European projects. The Royal Navy's Dreadnought-class program exemplifies this supply chain reconfiguration, with BAE Systems anchoring domestic content requirements above sixty percent.
Buyers are consolidating procurement authority under strategic systems commands rather than distributed fleet commands. The US Navy's Strategic Systems Programs office now controls all submarine-launched missile acquisition, compressing vendor negotiation cycles and reducing specification variance between hull classes. This concentration pattern is most visible in the United Kingdom, where the Defence Nuclear Organisation has absorbed previously separate Royal Navy procurement functions for the Successor program.
Global Submarine Launched Missile Market Segmentation
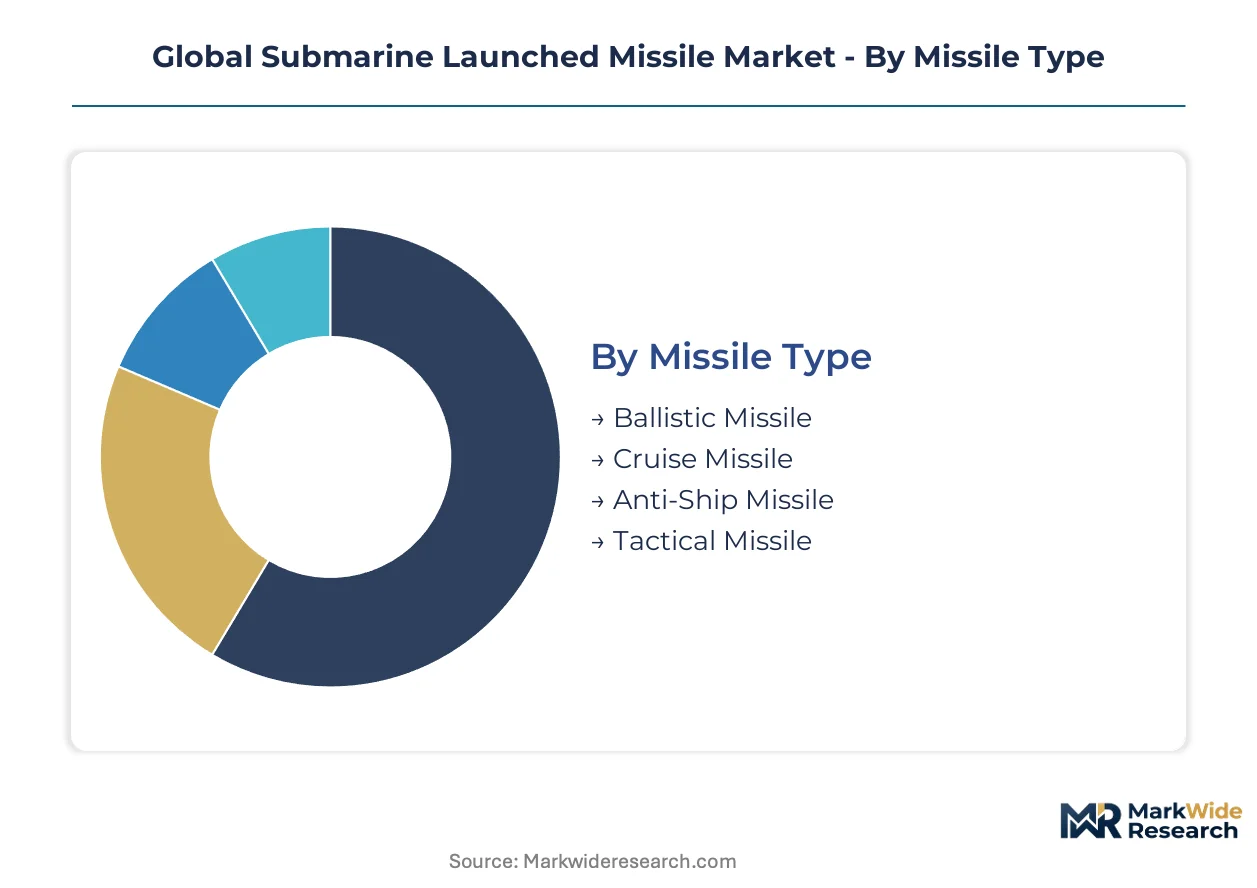
Segmentation in the submarine launched missile market reveals how platform requirements diverge between strategic nuclear deterrence and conventional strike missions. Procurement patterns cluster around missile type and launch platform compatibility, with guidance technology and end-user specifications determining supplier qualification tiers.
Missile Type:
Ballistic missiles concentrate procurement budgets within domestic strategic programs. Cruise and tactical variants drive export-led demand as middle-tier naval powers modernize conventional strike capabilities.
- Ballistic Missile:Solid-propellant systems with intercontinental range deliver nuclear payloads through parabolic trajectories. US Navy Strategic Systems Programs and comparable Russian and Chinese agencies anchor demand through life-extension and next-generation procurement cycles. Weapons-grade plutonium supply constraints limit new entrant proliferation.
- Cruise Missile:Turbojet or ramjet propulsion enables terrain-hugging flight profiles for conventional land-attack and anti-ship missions. Indo-Pacific fleet modernization programs in Japan, Australia, and South Korea are accelerating submarine-launched cruise missile integration as territorial maritime disputes intensify.
- Anti-Ship Missile:Sea-skimming terminal guidance systems target surface combatants. Naval forces in the United States, Russia, and China dominate procurement.
- Tactical Missile:Shorter-range precision systems support littoral operations and special mission profiles. Maritime security agencies in coastal states represent emerging demand pockets.
Ballistic missiles command the established base. The steepest expansion runs through cruise missiles.
Launch Platform:
Platform segmentation tracks propulsion technology maturation, with nuclear-powered hulls requiring decade-long construction timelines and diesel-electric alternatives offering faster procurement pathways for budget-constrained navies.
- Nuclear-Powered Submarine:Unlimited endurance supports continuous at-sea deterrence patrols. The US Navy's Columbia-class and Royal Navy's Dreadnought-class programs anchor demand for compatible missile interface specifications.
- Diesel-Electric Submarine:Air-independent propulsion advances enable extended submerged endurance for conventional missile carriage. Brazil and South Korea are expanding procurement as middle-tier powers seek affordable undersea strike capability.
- Midget Submarine:Compact hulls support special operations and coastal infiltration missions. Israeli and North Korean naval forces operate specialized fleets.
- Autonomous Underwater Vehicle:Experimental platforms test distributed payload carriage concepts. Defense contractors in the United States and China lead prototype development.
Nuclear-powered platforms absorb the dominant procurement value. Diesel-electric hulls are climbing the fastest as conventional mission requirements multiply.
Guidance Technology:
Guidance segmentation reflects precision requirements across mission profiles, with multi-mode systems commanding premium positioning for contested electromagnetic environments.
- Inertial Navigation:Self-contained systems resist jamming for strategic ballistic trajectories. US and UK nuclear forces mandate this baseline capability.
- GPS Guidance:Satellite augmentation enables meter-level accuracy for conventional strike. Anti-jam receiver development concentrates in US and European defense supply chains.
- Infrared Homing:Terminal seekers engage surface vessel thermal signatures. Russian and Chinese anti-ship programs prioritize this modality.
- Active Radar Homing:Fire-and-forget terminal guidance supports over-the-horizon engagements. Indo-Pacific naval modernization drives integration demand.
- Wire-Guided:Fiber-optic tethering enables human-in-the-loop control for complex littoral environments. Specialized maritime security applications sustain niche procurement.
Inertial navigation retains the strategic foundation. GPS-augmented multi-mode systems are gaining share fastest as conventional precision requirements intensify.
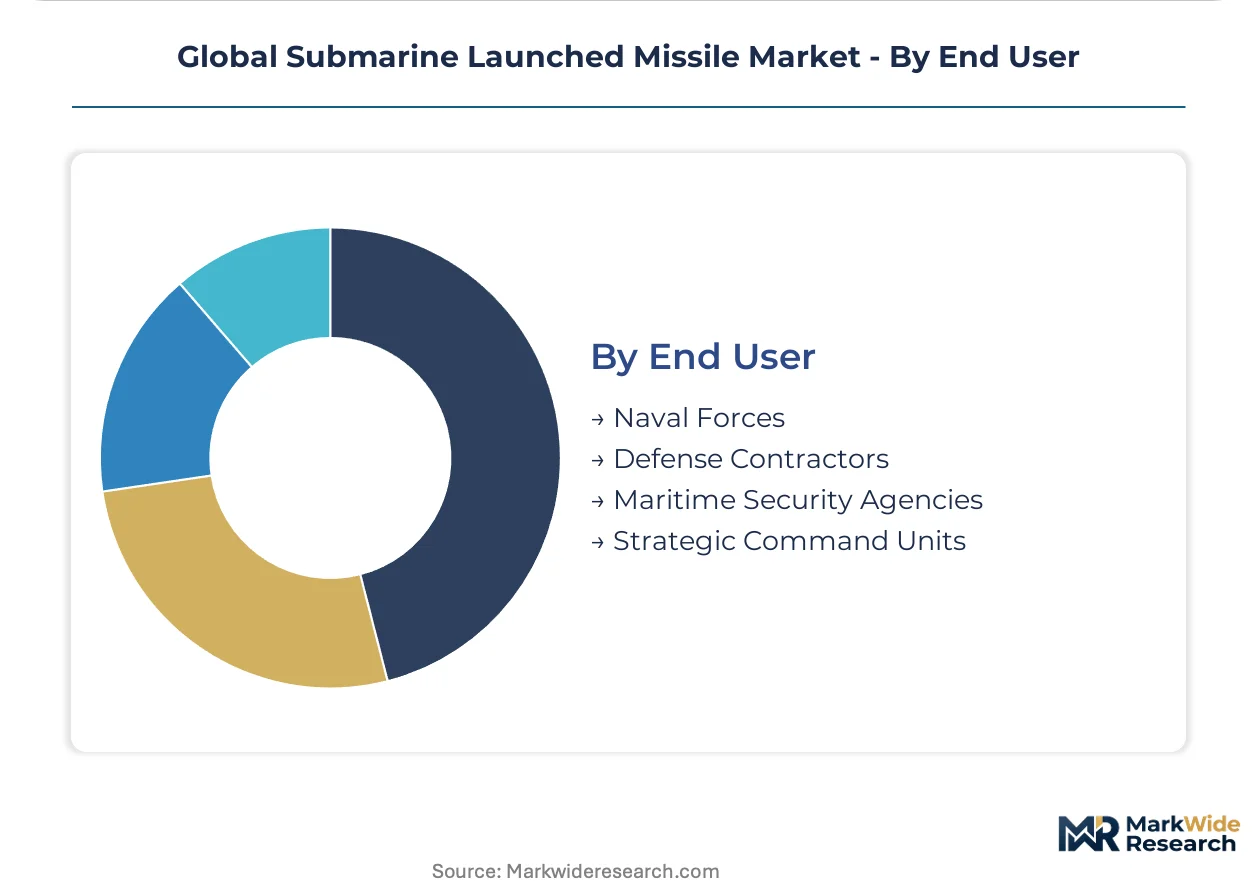
End User:
End-user segmentation maps to command authority concentration, with strategic systems offices consolidating procurement functions previously distributed across fleet commands.
- Naval Forces:National submarine services operate the primary launch platforms. The US Navy, Royal Navy, and Chinese People's Liberation Army Navy anchor global procurement volume through fleet modernization programs.
- Defense Contractors:Prime integrators manage subsystem qualification and platform integration. Lockheed Martin, BAE Systems, and Raytheon Technologies sustain cleared supply chain access.
- Maritime Security Agencies:Coast guard and border protection services acquire tactical systems for exclusive economic zone enforcement. Limited procurement concentrates in contested waterways.
- Strategic Command Units:Unified combatant commands control nuclear release authority and targeting coordination. US Strategic Command and comparable Russian and Chinese organizations enforce certification standards.
Naval forces command the established base. Defense contractors are expanding most quickly as platform integration complexity drives outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prime contractor consolidation and nuclear surety certification requirements concentrate development activity within five national defense industrial bases. Each anchors distinct supply chain configurations shaped by sovereign deterrent priorities and alliance technology-sharing agreements.
United States
Strategic Systems Programs office consolidation underpins Columbia-class ballistic missile submarine procurement alongside Trident II D5LE life-extension cycles. The National Nuclear Security Administration enforces warhead surety standards that constrain supplier qualification to cleared domestic entities. Groton, Connecticut and Newport News, Virginia host the primary hull fabrication and reactor integration complexes for next-generation undersea deterrent platforms.
United Kingdom
Dreadnought-class replacement programs and AUKUS technology transfer obligations drive missile interface specification updates across the Successor program. The Defence Nuclear Organisation absorbed Royal Navy procurement functions, centralizing vendor negotiation authority under unified command. Barrow-in-Furness maintains the sole domestic submarine construction capability, with BAE Systems anchoring domestic content requirements above sixty percent.
France
Direction des Applications Militaires certification standards enforce multi-year qualification timelines for M51 ballistic missile refresh programs and MdCN cruise missile integration. The Commissariat à l'énergie atomique et aux énergies alternatives manages weapons-grade material stockpiles that constrain warhead production scalability. Île-de-France hosts the primary guidance system and payload integration cluster, with Le Creusot supplying specialized naval reactor components.
Russia
Borei-class and Yasen-class production lines sustain solid-propellant ballistic missile deployment alongside hypersonic boost-glide technology maturation. Rosatom coordinates weapons-grade plutonium supply concentration that underpins warhead production for submarine-launched systems. Severodvinsk and Komsomolsk-on-Amur anchor the hull construction and missile integration industrial base, with Rubin and Malakhit design bureaus competing for platform contracts.
China
Jin-class and Type 094A ballistic missile submarine expansion accelerates JL-3 intercontinental range system deployment alongside hypersonic glide vehicle integration mandates. The China Academy of Engineering Physics encloses nuclear warhead design and certification within state-controlled research complexes. Bohai Shipyard in Huludao and Jiangnan Shipyard in Shanghai concentrate hull fabrication and missile integration capacity for the People's Liberation Army Navy submarine force.
Global Submarine Launched Missile Market Competitive Landscape
Concentration sits with prime contractors holding cleared supply chain access and proven launch histories across multiple national programs. The vendor base structures around three tiers: strategic system integrators with nuclear surety certification, cruise missile specialists with dual-use export control compliance, and emerging state-owned enterprises capturing domestic procurement in middle-tier naval powers. Competitive moves cluster on strategic partnerships for technology transfer and portfolio diversification into hypersonic payload integration.
Among US-based defense primes, Lockheed Martin Corporation and Raytheon Technologies Corporation occupy positions anchoring the strategic system integrator tier through sustained naval service relationships. BAE Systems plc exemplifies the European specialist archetype, with domestic content requirements and NATO STANAG framework alignment shaping competitive positioning. These three entities represent the cleared supply chain core that national certification standards privilege across US, UK, and allied procurement cycles.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems plc |
| Raytheon Technologies Corporation |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| MBDA |
| The Boeing Company |
| BrahMos Aerospace |
| Thales Group |
| Others |
Supply & Pricing Matrix
Long-term cost-plus contracts with fixed escalation clauses lock in weapons-grade plutonium access and titanium alloy supply while capping price volatility for prime contractors serving the US Navy Strategic Systems Programs and comparable agencies in France and the United Kingdom. These arrangements privilege incumbent suppliers with cleared facility access and multi-decade certification histories, compressing competitive entry and stabilizing procurement budgets across nuclear surety programs.
Pricing Analysis
NATO STANAG frameworks and national nuclear surety protocols dictate the pricing tier structure across European and allied procurement cycles. Three-tier pricing structure across certified strategic, dual-use conventional, and developmental experimental levels separates prime integrators from subsystem specialists and prototype vendors. Cost compression in cruise missile guidance packages is intensifying because EU dual-use export controls are forcing localization of computer production within member states. Defense contractors with established cleared supply chains exhibit the lowest price sensitivity, while middle-tier naval powers in Brazil and South Korea face acute budget constraints on diesel-electric platform integration.
Supply Chain Analysis
Extended lead times for specialized titanium alloys and weapons-grade plutonium stockpiles stretch procurement cycles beyond sixty months for critical inputs. Supply concentrates in the United States, Russia, and France for fissile material refining and warhead assembly, while the United Kingdom and China anchor guidance system fabrication. The supply chain draws from pump-jet propulsor manufacturing in Germany, solid-rocket motor casing production in the United States, and precision gyroscope sourcing from France and the United Kingdom. Single-source vulnerability pervades weapons-grade plutonium availability, with Rosatom and the National Nuclear Security Administration controlling exportable stockpiles. Distribution runs through national strategic systems commands rather than commercial defense channels, with hull fabrication concentrated at Groton, Barrow-in-Furness, and Severodvinsk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hypersonic glide vehicle integration is compressing development timelines while rotating specification tiers upward, creating asymmetric opportunities across cleared and conventional supply chain tiers. Regulatory fragmentation between NATO STANAG frameworks and national nuclear surety protocols is amplifying competitive moats for certified incumbents.
For Market Incumbents: Compound cleared supply chain advantages by securing multi-year titanium alloy offtake agreements and expanding hypersonic payload integration capacity before specification mandates harden. Lockheed Martin and BAE Systems face emerging pressure from Chinese state-owned enterprises capturing domestic procurement, necessitating accelerated AUKUS technology transfer pathway exploitation to maintain allied market share. For New Entrants and Emerging Players: Lead with air-independent propulsion-enabled diesel-electric platforms as the most penetrable segment, targeting Brazil and South Korea where conventional strike missions are displacing strategic nuclear requirements. Partner with established guidance computer suppliers in France or the United Kingdom to navigate EU dual-use export controls, leveraging NATO STANAG interoperability protocols as a regulatory fast-track for subsystem qualification. For Investors and Strategic Acquirers: Specialist guidance package developers with anti-jam GPS and multi-mode seeker capabilities represent the highest-conviction acquisition archetype for portfolio exposure to conventional precision strike expansion. Long-term viability hinges on positioning ahead of hypersonic boost-glide technology maturation, with the signal to monitor being US Navy Strategic Systems Programs office consolidation of conventional prompt global strike procurement authority under unified command structures.| Strategic Initiative | Industry Significance |
|---|---|
| Hypersonic Payload Integration | US Navy Strategic Systems Programs mandates maneuverable reentry capabilities across next-generation procurement cycles. |
| Cleared Supply Chain Localization | BAE Systems anchors domestic content above sixty percent for Royal Navy Dreadnought-class programs under Defence Nuclear Organisation oversight. |
| AUKUS Technology Transfer Pathway | Trilateral security pact creates cleared access for Australian submarine-launched missile integration without independent certification timelines. |
| Dual-Use Export Control Compliance | EU regulations force guidance computer production relocation into member states to maintain integrated European project access. |
| Solid-Propellant Motor Life Extension | Trident II D5LE programs sustain Lockheed Martin contracts through modular payload bay upgrades for mixed conventional-nuclear loads. |
Research Methodology
A spread of perspectives from strategic systems program officers, submarine platform engineers, nuclear surety certification leads, and defense procurement directors converged on the working assumptions shaping demand projections across the analysis window. Primary field engagement with hull fabrication specialists at Groton and Barrow-in-Furness supplemented secondary validation against US Navy budget justification materials, UK Ministry of Defence equipment plans, and France's Direction des Applications Militaires technical directives. Bottom-up platform deployment schedules were triangulated with top-down national deterrent budget allocations.
Segmentation dimensions modeled include missile type across ballistic, cruise, anti-ship, and tactical variants; launch platform propulsion architecture spanning nuclear-powered, diesel-electric, and air-independent systems; guidance technology from inertial baseline to GPS-augmented multi-mode configurations; and end-user command authority concentration. CAGRs were derived from deployment schedule phasing and procurement cycle acceleration patterns, with hypersonic integration mandates and Indo-Pacific fleet modernization programs serving as primary demand elasticity inputs.
The analysis sits within stated boundaries; outcomes outside sustained AUKUS technology transfer execution, weapons-grade plutonium supply stability, or NATO STANAG framework harmonization would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and conventional mission expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Cluster Munitions Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Smart Bombs Market