
 Asia-Pacific Engineering Plastics Market | 2026-2036
Asia-Pacific Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Engineering Plastics Market Outlook
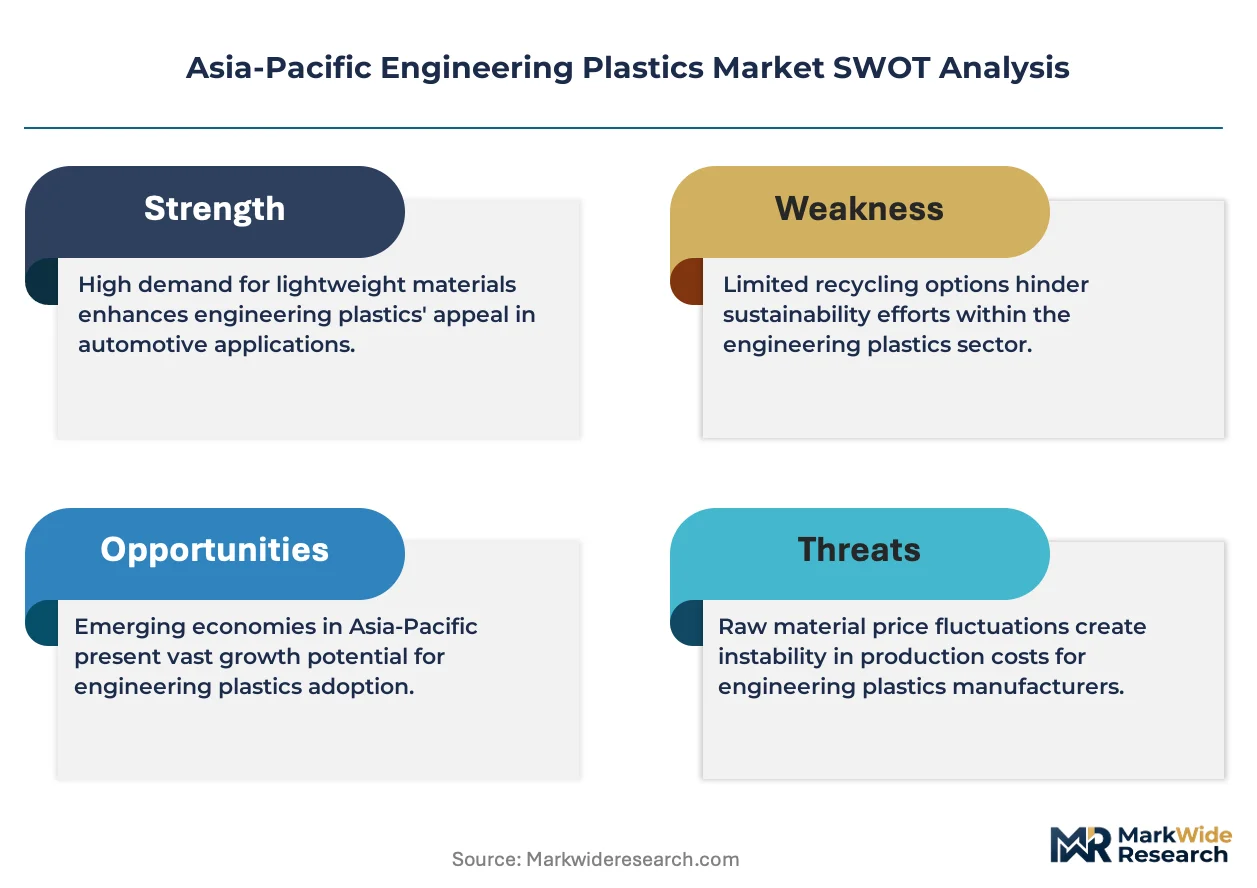
Steel is decoupling from under-hood and structural automotive applications as engineering plastics achieve comparable load-bearing performance at reduced mass. SABIC leverages its petrochemical feedstock integration to stabilize polycarbonate resin supply across Northeast Asian markets. Asahi Kasei Corporation anchors its position through specialized polyamide grades engineered for thermal management in electrified powertrains. LG Chem competes aggressively on acrylonitrile butadiene styrene capacity, controlling cost curves that pressure regional mid-tier producers.
Asia-Pacific engineering plastics comprise thermoplastic polymers engineered to withstand mechanical stress, thermal cycling, and chemical exposure beyond commodity polymer thresholds, typically exhibiting tensile strengths exceeding 50 MPa and continuous service temperatures above 100°C. These materials serve primarily as metal substitutes in precision-manufactured components where weight reduction and design freedom carry premium value. Polyamide dominates volume flows into automotive and industrial equipment channels where abrasion resistance and fatigue performance command priority. Polycarbonate captures margin pools in electrical insulation and transparent housing applications requiring optical clarity plus flame retardancy. Injection molding remains the anchor processing method, though extrusion gains share in thermal management sheet and film formats for battery pack applications.
China's MIIT enforces GB standards governing material flammability and recyclability in automotive and electrical applications, while Japan's METI administers JIS standards that shape product qualification for industrial equipment exports. REACH-aligned substance restrictions from European trade partners cascade into Asia-Pacific formulation requirements, compelling producers to phase legacy flame retardants and plasticizers. South Korea's MFDS and KOSHA frameworks add compliance layers for consumer goods and workplace safety applications. Stakeholders must monitor regulatory divergence between national standards regimes and assess whether centralized formulation platforms or market-specific product lines yield superior compliance economics.
Market Dynamics
Automotive OEM electrification programs are compressing material qualification timelines while China's dual carbon goals force reformulation of legacy flame-retardant systems across the Yangtze River Delta manufacturing corridor.
Growth Catalysts
- MIIT GB standards compliance:China's flammability and recyclability mandates for automotive and electrical applications are pulling high-performance polyamide and polycarbonate grades into domestic supply chains.
- EV thermal management expansion:Battery pack manufacturers require engineered polymers with continuous service temperatures above 150°C for module housings and cooling manifolds.
- Injection molding automation:Precision manufacturing clusters in Japan and South Korea are reducing cycle times for complex geometries in under-hood components.
Market Restraints
- Bisphenol A feedstock volatility:Polycarbonate resin producers face margin compression from petrochemical price swings tied to regional refinery capacity.
- Mid-tier producer consolidation:Northeast Asian acrylonitrile butadiene styrene oversupply is forcing exit of smaller compounders lacking backward integration into monomer supply.
- REACH-aligned substance restrictions:European trade partner requirements are cascading into Asia-Pacific formulation bans on legacy halogenated flame retardants.
Strategic Opportunities
- Southeast Asia manufacturing migration:Vietnam and Thailand are attracting automotive Tier-1 investment seeking alternatives to China's concentration risk.
- Extrusion-based thermal management films:Battery pack producers are specifying sheet formats for inter-cell insulation barriers beyond traditional injection molding.
- METI efficiency mandates:Japan's industrial equipment export standards are creating premium qualification pathways for fatigue-resistant polyamide grades.
Industry Challenges
- Multi-jurisdiction certification timelines:Producers must sequence GB, JIS, and MFDS approvals for cross-regional automotive platforms.
- Polymer compounding talent scarcity:Formulation chemists with expertise in flame-retardant synergists and glass-fiber interface optimization command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Engineering Plastics Market |
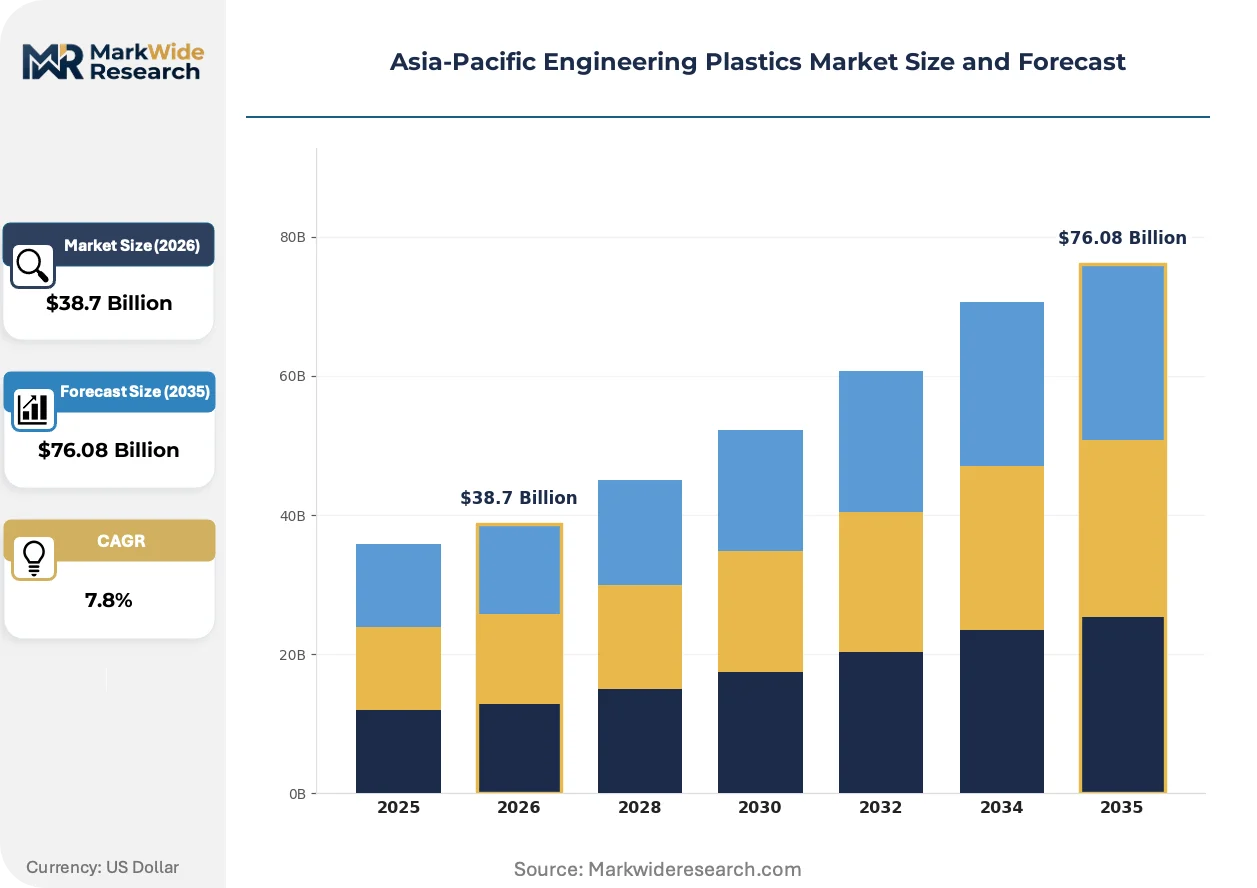
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $76.08 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Polyamide, Polyethylene Terephthalate, Acrylonitrile Butadiene Styrene End User: Automotive OEMs, Electrical Appliances, Consumer Goods, Industrial Equipment Application: Structural Components, Electrical Insulation, Thermal Management, Housing Processing Method: Injection Molding, Extrusion, Blow Molding, Thermoforming |
| Companies Covered | SABIC, Asahi Kasei Corporation, Covestro AG, Far Eastern New Century Corporation, CHIMEI, LG Chem, Sumitomo Chemical Co., Ltd., Solvay, Mitsubishi Chemical Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Engineering Plastics Market Strategic Shifts
Material science advances are collapsing the performance gap between engineering plastics and metal alloys while regulatory pressure on carbon intensity forces supply chain reconfiguration across Northeast Asian petrochemical networks.
High-heat polyamide compounds reinforced with long-glass fiber are converging with aluminum die-cast components in electric motor housings and transmission brackets. Tier-1 suppliers in Japan and South Korea have accelerated qualification programs for these hybrid material systems. The convergence is compressing traditional metal-to-plastic conversion timelines from 36 months to 18 months for new EV platforms.
China's MIIT is tightening GB standards for material recyclability in automotive applications, requiring producers to document closed-loop recovery pathways. Compounders must now reformulate legacy additive packages to maintain flame-retardant performance without substances restricted under REACH-aligned trade requirements. Electrical insulation grades face the steepest compliance burden as export-oriented manufacturers dual-certify for domestic and European markets.
Automotive OEMs are consolidating supplier relationships around compounders offering integrated material-recycling services rather than virgin resin alone. Battery pack manufacturers in the Yangtze River Delta now specify take-back clauses in procurement contracts for production scrap and end-of-life modules. The service bundling is most advanced in China where ESG disclosure requirements from domestic OEMs outpace regional peers.
Asia-Pacific Engineering Plastics Market Segmentation
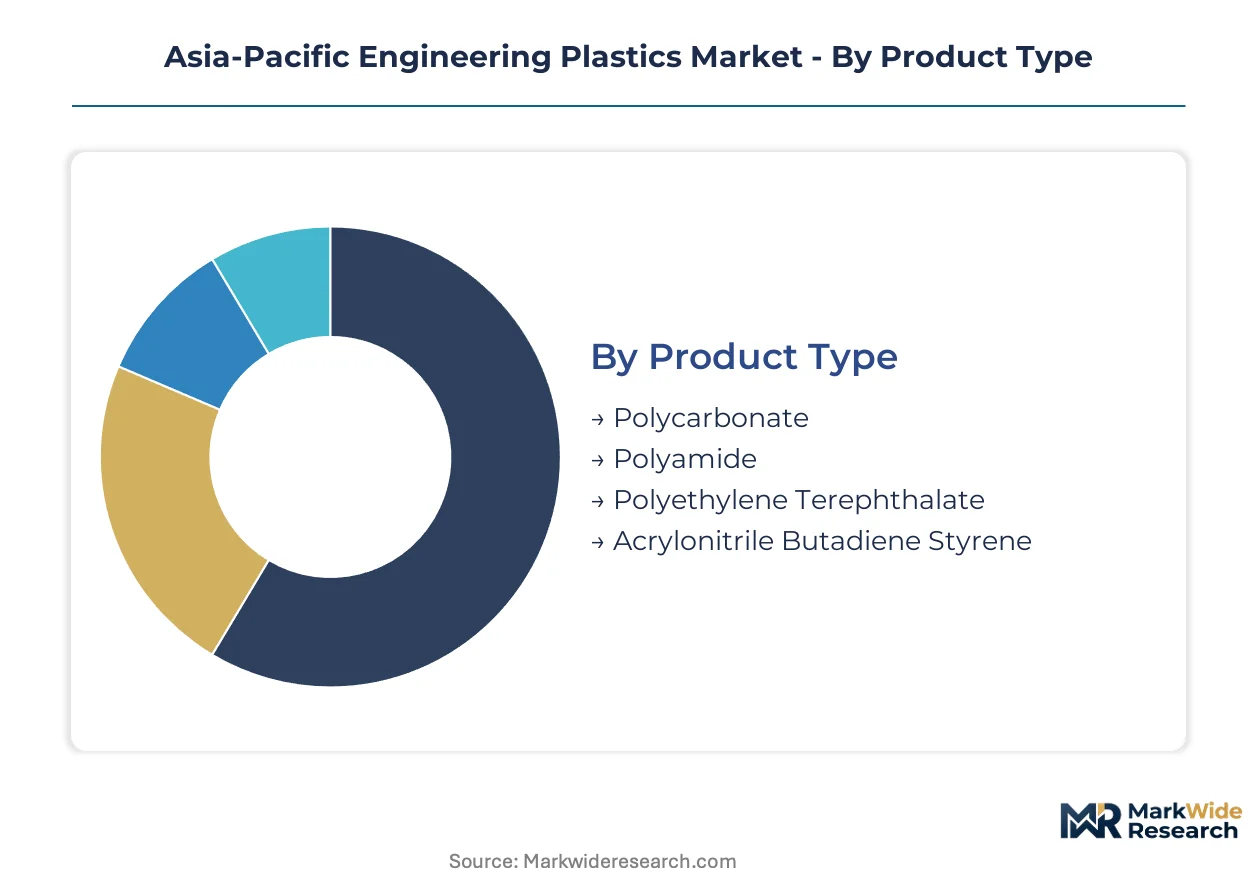
Engineering plastics selection across Asia-Pacific hinges on thermal performance thresholds, regulatory compliance burdens, and processing economics that vary sharply by end-use. Material specification decisions cascade through formulation chemistry, additive packages, and certification timelines that compounders must navigate across China's GB standards, Japan's JIS frameworks, and South Korea's MFDS requirements.
Product Type:
Thermal stability and mechanical load-bearing capacity differentiate resin selection for metal replacement applications across the region's automotive and industrial channels.
- Polycarbonate:Amorphous thermoplastic delivering optical clarity alongside flame-retardant grades rated to UL94 V-0. Demand concentrates in electrical housing applications across China's Yangtze River Delta where MIIT GB standards enforce stringent flammability documentation.
- Polyamide:Semi-crystalline polymer with continuous service temperatures exceeding 150°C in glass-reinforced grades. Automotive OEMs in Japan and South Korea specify long-fiber variants for transmission brackets and electric motor housings under METI efficiency mandates.
- Polyethylene Terephthalate:Saturated polyester with crystallization kinetics suited to precision-molded electrical connectors. PET engineering grades serve appliance manufacturers seeking cost-efficient alternatives to polyamide in non-structural applications.
- Acrylonitrile Butadiene Styrene:Terpolymer balancing impact resistance with processability in consumer goods and interior automotive trim. Northeast Asian oversupply has compressed margins for non-integrated compounders lacking captive monomer supply.
Mature deployment sits with polycarbonate in established electrical insulation channels. Newer deployment is concentrated in high-heat polyamide grades for electrified powertrain thermal management.
End User:
Customer procurement patterns diverge between specification-driven OEMs with extended qualification timelines and price-sensitive appliance manufacturers with compressed vendor selection cycles.
- Automotive OEMs:Material qualification cycles spanning 18-36 months govern resin selection for under-hood structural components. China's dual carbon goals and Japan's METI mandates are forcing reformulation of legacy flame-retardant systems across EV platforms.
- Electrical Appliances:Manufacturers prioritize UL-certified grades with documented recyclability pathways for export markets. REACH-aligned substance restrictions from European trade partners cascade into formulation requirements for wire insulation and connector housings.
- Consumer Goods:Cost-driven procurement favors ABS and commodity-engineered blends for housings and wearables. South Korea's MFDS and KOSHA frameworks add compliance layers for workplace safety and food-contact applications.
- Industrial Equipment:Fatigue-resistant polyamide grades serve precision gearing and bearing applications. METI-administered JIS standards shape product qualification for Japanese industrial equipment exports.
Procurement concentration tilts toward automotive OEMs in Japan and South Korea. Volume expansion is accelerating fastest in China's electrical appliance sector serving domestic and export markets.
Application:
Functional performance requirements dictate resin selection across load-bearing, insulating, and thermal management use cases with divergent temperature and chemical exposure profiles.
- Structural Components:Long-glass-fiber polyamide compounds achieve tensile strengths exceeding 150 MPa for metal replacement in brackets and housings. Tier-1 suppliers in Japan have accelerated qualification programs compressing traditional conversion timelines.
- Electrical Insulation:Polycarbonate and PET grades with tracking resistance and dielectric stability serve high-voltage connector and busbar applications. China's MIIT GB standards enforce material flammability documentation for domestic electrical equipment.
- Thermal Management:High-heat polyamide and specialized compounds with thermal conductivity fillers cool battery modules and power electronics. Battery pack manufacturers in the Yangtze River Delta specify continuous service temperatures above 150°C.
- Housing:Flame-retardant ABS and polycarbonate blends balance aesthetics with regulatory compliance for appliance and consumer electronics enclosures. REACH-aligned bans on legacy halogenated flame retardants force reformulation across export-oriented manufacturers.
Established volume flows through structural automotive applications. Steepest expansion trajectory is occurring in thermal management as EV battery pack specifications proliferate.
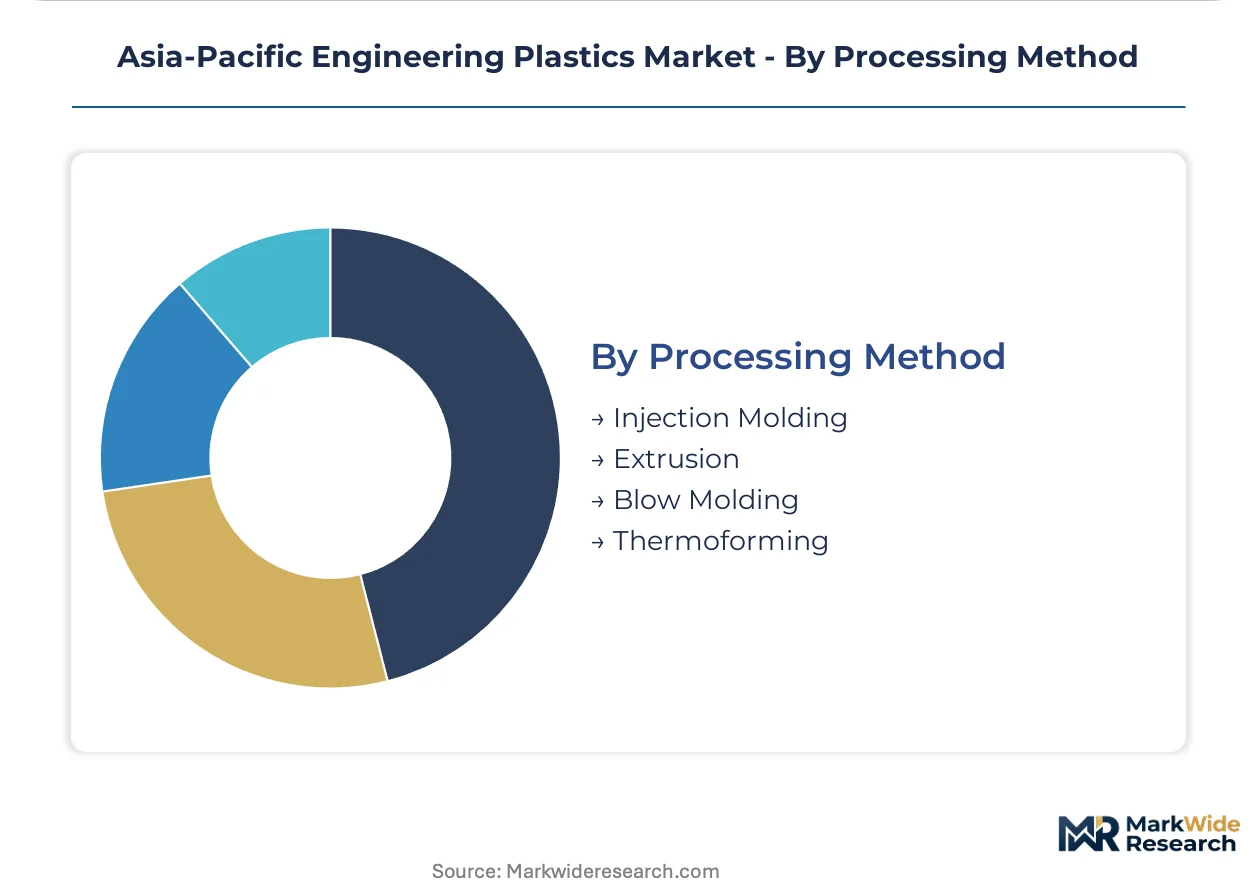
Processing Method:
Manufacturing technology selection locks in resin viscosity requirements, cycle economics, and geometric complexity capabilities that shape compounder formulation priorities.
- Injection Molding:Dominant process for precision components with complex geometries in under-hood automotive and electrical connector applications. Automation investments in Japan and South Korea are reducing cycle times for high-volume production.
- Extrusion:Sheet and film formats gain share in battery pack thermal management barriers and electrical insulation layers. Battery manufacturers specify extruded inter-cell insulation beyond traditional injection-molded housings.
- Blow Molding:Hollow-forming technology serves fluid handling reservoirs and ducting in automotive and industrial equipment. Limited penetration in engineering plastics due to viscosity and sag-resistance requirements.
- Thermoforming:Secondary shaping of extruded sheet produces large-format housings and equipment enclosures with lower tooling costs than injection molding. Applications concentrate in appliance and industrial equipment channels with moderate performance requirements.
Process maturity centers on injection molding for precision automotive and electrical components. Extrusion is gaining deployment fastest in battery thermal management film applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification and appliance manufacturing concentrate demand across Northeast Asian industrial corridors. China's dual carbon mandates and Japan's METI efficiency standards are reshaping material qualification requirements. Vietnam and Thailand are attracting Tier-1 supplier investment seeking manufacturing alternatives.
China
EV battery pack manufacturers in the Yangtze River Delta specify high-heat polyamide grades for thermal management modules. MIIT enforces GB standards governing material flammability and recyclability in automotive and electrical applications. Shanghai and Suzhou host concentrated compounding operations serving domestic OEMs and export-oriented appliance producers.
Japan
Automotive OEMs in the Chubu region accelerate qualification programs for long-glass-fiber polyamide in electric motor housings. METI administers JIS standards that shape product qualification for industrial equipment exports. Nagoya-based Tier-1 suppliers compress metal-to-plastic conversion timelines from 36 months to 18 months for new EV platforms.
South Korea
Battery manufacturers in the Seoul Capital Area procure engineered polymers with continuous service temperatures above 150°C for module housings. MFDS and KOSHA frameworks add compliance layers for consumer goods and workplace safety applications. Busan-Ulsan petrochemical complexes anchor acrylonitrile butadiene styrene supply for regional appliance and automotive channels.
Vietnam
Automotive Tier-1 suppliers establish compounding operations to serve export-oriented assembly plants. The country's national industrial regulator enforces emerging chemical safety standards aligned with ASEAN harmonization initiatives. Ho Chi Minh City and surrounding provinces attract investment seeking alternatives to China's concentration risk.
Thailand
Japanese and South Korean OEMs specify localized engineering plastics supply for regional EV production platforms. The country's automotive industry board coordinates material qualification pathways with Japanese JIS and European REACH-aligned requirements. Eastern Economic Corridor manufacturing zones concentrate injection molding capacity for under-hood components.
Asia-Pacific Engineering Plastics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with petrochemical-integrated compounders controlling cost curves in high-volume resin categories. The vendor base organizes around three strategic archetypes: feedstock-integrated majors with captive monomer supply, regional compounders serving qualification-intensive automotive channels, and specialized producers of thermal management grades for battery applications. Capacity expansion and backward integration into monomer production represent the dominant competitive moves as margin pressure intensifies on non-integrated players.
Within the feedstock-integrated tier, SABIC and LG Chem exemplify archetypes leveraging petrochemical network control to stabilize resin supply across Northeast Asian markets. Asahi Kasei Corporation occupies a position representing specialized compounders engineered for thermal management applications in electrified powertrains. These three anchors illustrate how competitive positioning diverges between scale-driven commodity resin supply and qualification-intensive performance grade development.
| Leading Market Players |
|---|
| SABIC |
| Asahi Kasei Corporation |
| Covestro AG |
| Far Eastern New Century Corporation |
| CHIMEI |
| LG Chem |
| Sumitomo Chemical Co., Ltd. |
| Solvay |
| Mitsubishi Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM procurement teams in Japan and South Korea negotiate resin supply through long-term contract structures that embed volume commitments and certification tiers. This buyer concentration enables feedstock-integrated compounders to command premium pricing for qualified grades while squeezing margins on non-integrated regional producers.
Pricing Analysis
Volume-mature polycarbonate and ABS grades trade on commodity-like curves with thin spreads, while specialized high-heat polyamide compounds for EV thermal management capture substantial margin premiums. Price differentiation rests on MIIT GB certification status and long-fiber reinforcement content rather than brand alone. Cost compression in Northeast Asian ABS supply is intensifying because of oversupply from Busan-Ulsan petrochemical complexes. Appliance manufacturers serving export markets exhibit highest price sensitivity, whereas Japanese automotive Tier-1 suppliers prioritize qualification security over unit cost.
Supply Chain Analysis
Regional distribution centers in Shanghai, Nagoya, and Busan coordinate hub-and-spoke logistics for compounded resin delivery to injection molding clusters. Manufacturing concentration spans China, Japan, and South Korea, with Vietnam and Thailand emerging as secondary compounding locations. Feedstock draws from regional refinery capacity for bisphenol A, adipic acid, and acrylonitrile monomers. Single-source vulnerability sits with specialized flame-retardant additive packages subject to REACH-aligned import restrictions. Distribution runs through direct mill-to-mold relationships for automotive OEMs, with distributor networks serving fragmented appliance and consumer goods channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over bisphenol A and adipic acid feedstocks determines margin sustainability. Players lacking backward integration into monomer supply face systematic disadvantage against petrochemical-integrated majors.
For Market Incumbents: Anticipate consolidation pressure from Northeast Asian ABS oversupply by securing captive monomer capacity or exiting commodity grades entirely. Defensive moves should prioritize MIIT GB certification pre-qualification for next-generation halogen-free flame-retardant systems. Channel control through integrated recycling services for battery pack scrap will differentiate against virgin-resin-only competitors. For New Entrants and Emerging Players: Battery pack thermal management film extrusion represents the most penetrable white-space segment, with demand accelerating faster than established supply capacity in the Yangtze River Delta. Vietnam and Thailand offer geographic entry points with lower regulatory compliance burdens than China or Japan. A go-to-market angle anchored to take-back and closed-loop recovery services aligns with domestic OEM ESG procurement requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized polyamide compounders with existing MIIT or METI qualifications in Japan and South Korea, where certification timelines create durable moats. Long-term viability over a multi-year horizon rests on exposure to EV platform content growth rather than legacy internal combustion applications. The signal to watch is qualification timeline compression for high-heat grades below 18 months, indicating commoditization risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive bisphenol A and adipic acid production insulates margin from petrochemical volatility in Northeast Asian refinery markets. |
| MIIT GB Certification Pre-Investment | Early qualification for recyclability and flammability standards secures procurement access to China's Yangtze River Delta EV battery manufacturers. |
| Integrated Recycling Service Bundling | Take-back clauses for production scrap and end-of-life modules meet domestic OEM ESG disclosure requirements ahead of regional peers. |
| Long-Fiber Polyamide Capacity Expansion | Glass-reinforced grades above 150°C continuous service temperature capture metal replacement opportunities in electric motor housings. |
| Southeast Asia Manufacturing Footprint | Vietnam and Thailand facilities reduce concentration risk exposure while serving Japanese and South Korean OEM regional production platforms. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at compounding facilities, procurement leads at automotive Tier-1 suppliers, technical R&D directors at resin producers, and distribution channel partners across Northeast Asian markets. MIIT GB standard documentation, METI JIS certification records, and REACH-aligned substance restriction notices provided regulatory validation. Bottom-up volume estimates from injection molding and extrusion capacity utilization were triangulated against top-down petrochemical feedstock consumption patterns.
Segment-level modeling operated at resin grade tier, end-use industry, processing method, and regional production hub granularity across the analysis window. CAGRs were derived from elasticity-adjusted demand projections tied to EV platform rollout schedules and appliance export volumes. Forecast inputs incorporated battery pack thermal management specification proliferation, METI efficiency mandate adoption curves, and MIIT recyclability compliance phase-in assumptions.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting bisphenol A feedstock flows, unanticipated breakthroughs in metal alloy lightweighting that reverse plastic substitution trends, and force majeure events at concentrated Northeast Asian petrochemical complexes. Forecasts reflect documented assumptions around regulatory implementation timelines and OEM platform content trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polypropylene and High-Impact Polystyrene Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Water Soluble Polymers Market