
 Asia-Pacific Opaque Polymers Market | 2026-2036
Asia-Pacific Opaque Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Opaque Polymers Market Outlook
Architectural coatings is repositioning opaque polymer consumption across Asia-Pacific as builders shift from solvent-borne to waterborne systems. BASF SE leverages its Ludwigshafen-derived technology platform to supply high-performance opacifiers across Chinese and Southeast Asian coating hubs. Dow Chemical Company anchors regional supply through integrated polyethylene and polypropylene precursor networks. Mitsui Chemicals specializes in Japan-grade polystyrene opacifiers for premium automotive and electronics applications.
Asia-Pacific opaque polymers are synthetic resin particles, typically hollow-sphere thermoplastics with controlled particle sizes between 0.3 and 0.6 microns, engineered to scatter visible light and replace titanium dioxide in formulated products. The polystyrene segment leads volume due to mature emulsion polymerization infrastructure and cost-efficient scale across Chinese coastal plants. Polypropylene opacifiers represent the fastest-expanding structural category as automotive interior specifications in Thailand and Indonesia demand lighter-weight, lower-VOC plastic components. Coatings applications command the dominant margin pool, though plastics adoption in consumer electronics housings is accelerating.
China's MEE enforces GB standards limiting VOC content in architectural coatings, directly expanding qualified opaque polymer formulations. Japan's METI promotes JIS-compliant low-emission building materials, while India's BIS develops harmonized standards for waterborne industrial coatings under its PLI scheme. Stakeholders must monitor regulatory divergence between China's mandatory carbon intensity targets and India's emerging certification timelines to align regional product portfolios.
Market Dynamics
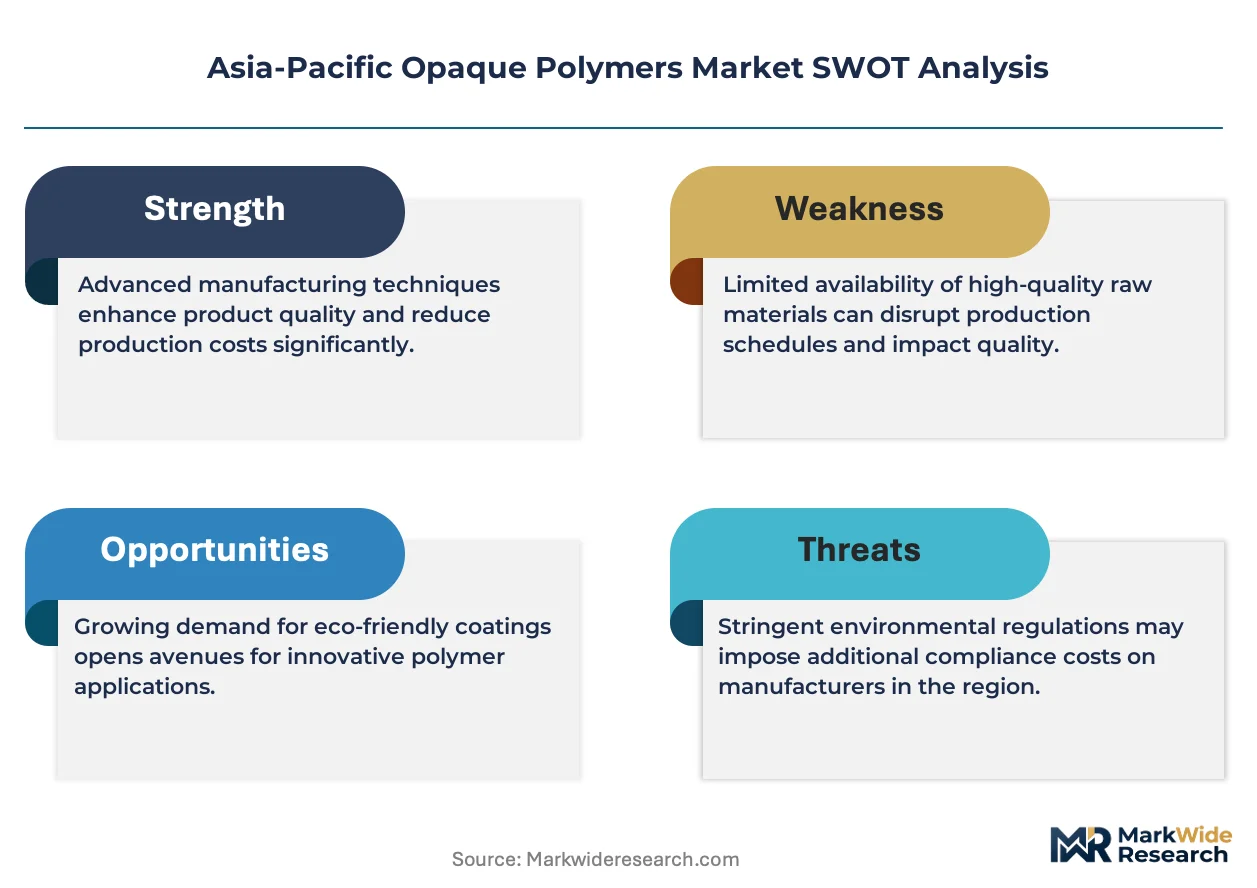
Waterborne architectural coatings are forcing a structural reformulation of opacifier supply chains across Asia-Pacific, as China's MEE tightens VOC limits and manufacturers abandon titanium dioxide-heavy solvent systems.
Growth Catalysts
- MEE dual carbon mandates:China's GB standards for architectural coatings are disqualifying high-VOC formulations and expanding qualified polymer-based opacifier procurement.
- Automotive lightweighting specifications:Thai and Indonesian OEMs are specifying hollow-sphere polypropylene opacifiers for interior plastic components to reduce vehicle weight.
- Emulsion polymerization infrastructure:Coastal Chinese plants in Jiangsu and Zhejiang provinces leverage mature polystyrene production networks to achieve cost-efficient opacifier scale.
Market Restraints
- Titanium dioxide price volatility:Feedstock cost swings for TiO2 pigment create margin compression for opacifier producers competing on replacement economics.
- Supply concentration in eastern China:Overreliance on manufacturing corridors spanning Shanghai through Zhejiang creates geographic risk exposure.
- Performance ceiling in high-sheen coatings:Hollow-sphere opacifiers exhibit scattering efficiency limitations in premium gloss architectural applications.
Strategic Opportunities
- India's PLI scheme for industrial coatings:BIS harmonization of waterborne standards under production-linked incentives opens qualified opacifier penetration.
- Consumer electronics housings:Southeast Asian electronics contract manufacturers are specifying opacified polymers for aesthetic and lightweight casing applications.
- Digital specification platforms:Coatings formulators in South Korea are adopting AI-driven raw material selection tools that rank opacifier performance metrics.
Industry Challenges
- Reformulation chemist shortage:Waterborne coatings expertise gaps in Vietnam and Indonesia delay customer technical service response times.
- Cross-border GB standard compliance:Exporters to China face inconsistent provincial enforcement of MEE carbon intensity documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Opaque Polymers Market |
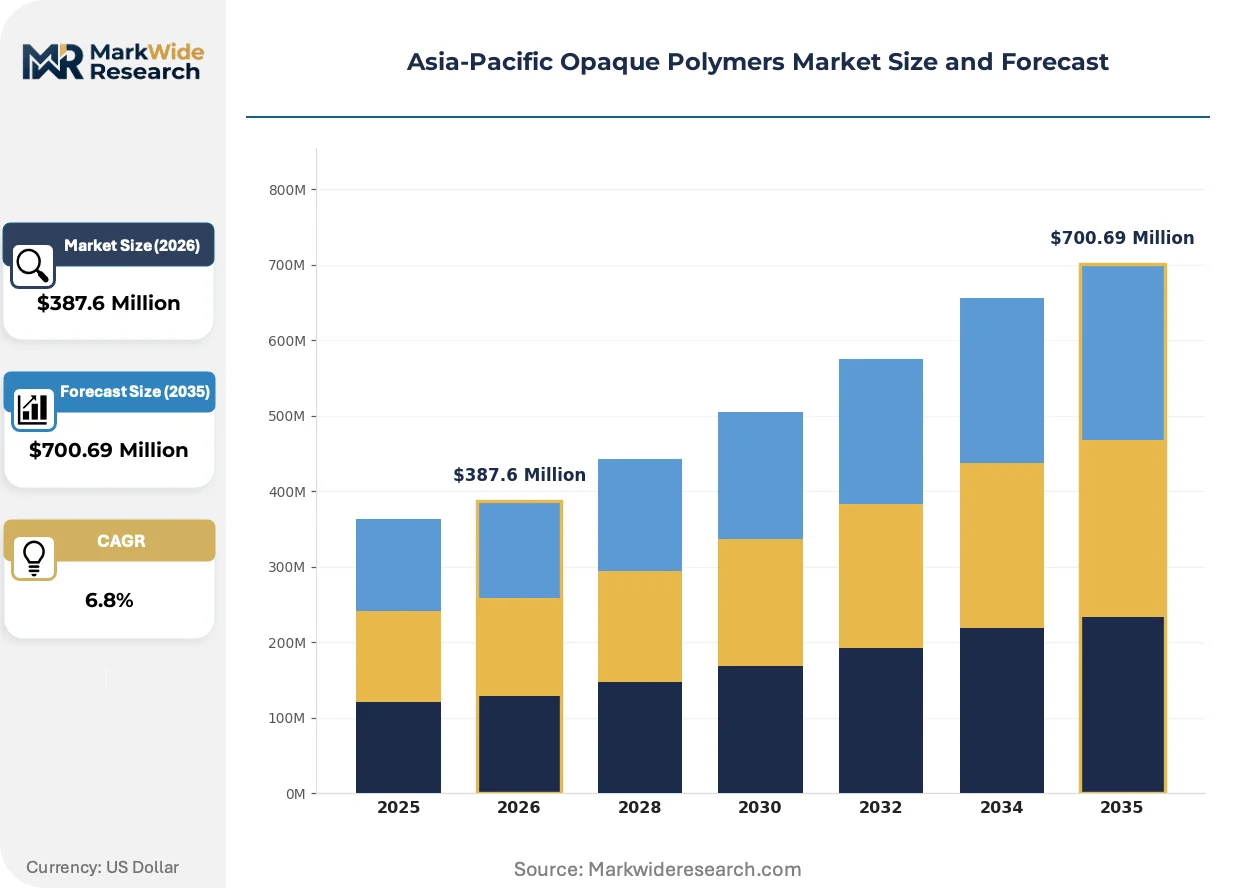
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride Application: Coatings, Adhesives, Plastics, Inks End User: Automotive, Construction, Consumer Goods, Packaging Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, Dow Chemical Company, Arkema, Solvay, Formosa Plastics Corporation, Mitsui Chemicals, INEOS, Reliance Industries, Hankuck Latices Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Opaque Polymers Market Strategic Shifts
Reformulation chemistry is accelerating across Asia-Pacific as coating manufacturers engineer opacity without titanium dioxide, triggering parallel advances in polymer particle engineering and regulatory compliance tooling.
Sub-micron hollow-sphere engineering is decentralizing opacifier performance standards across the coatings industry. Japanese automotive OEMs are adopting precision-controlled 0.3-0.4 micron polystyrene particles for Class-A interior surfaces. This particle architecture is decentralizing quality benchmarks from pigment-centric TiO2 specifications toward polymer-scattering efficiency metrics.
China's MEE is enforcing sequential tightening of GB 30982 VOC limits in architectural coatings through 2025-2030 compliance windows. Industrial consequence includes mandatory reformulation audits for imported coating systems. Waterborne exterior wall coating producers in Jiangsu province are accelerating polymer opacifier qualification timelines to maintain distribution licenses.
Specification behavior is compressing switching cycles as procurement teams consolidate raw material supplier panels. Large architectural coatings formulators in South Korea are unbundling legacy multi-source pigment procurement into single-platform opacifier contracts. This consolidation is most visible in Seoul-Incheon manufacturing clusters where coating producers prioritize JIS-compliant low-emission certification bundles.
Asia-Pacific Opaque Polymers Market Segmentation
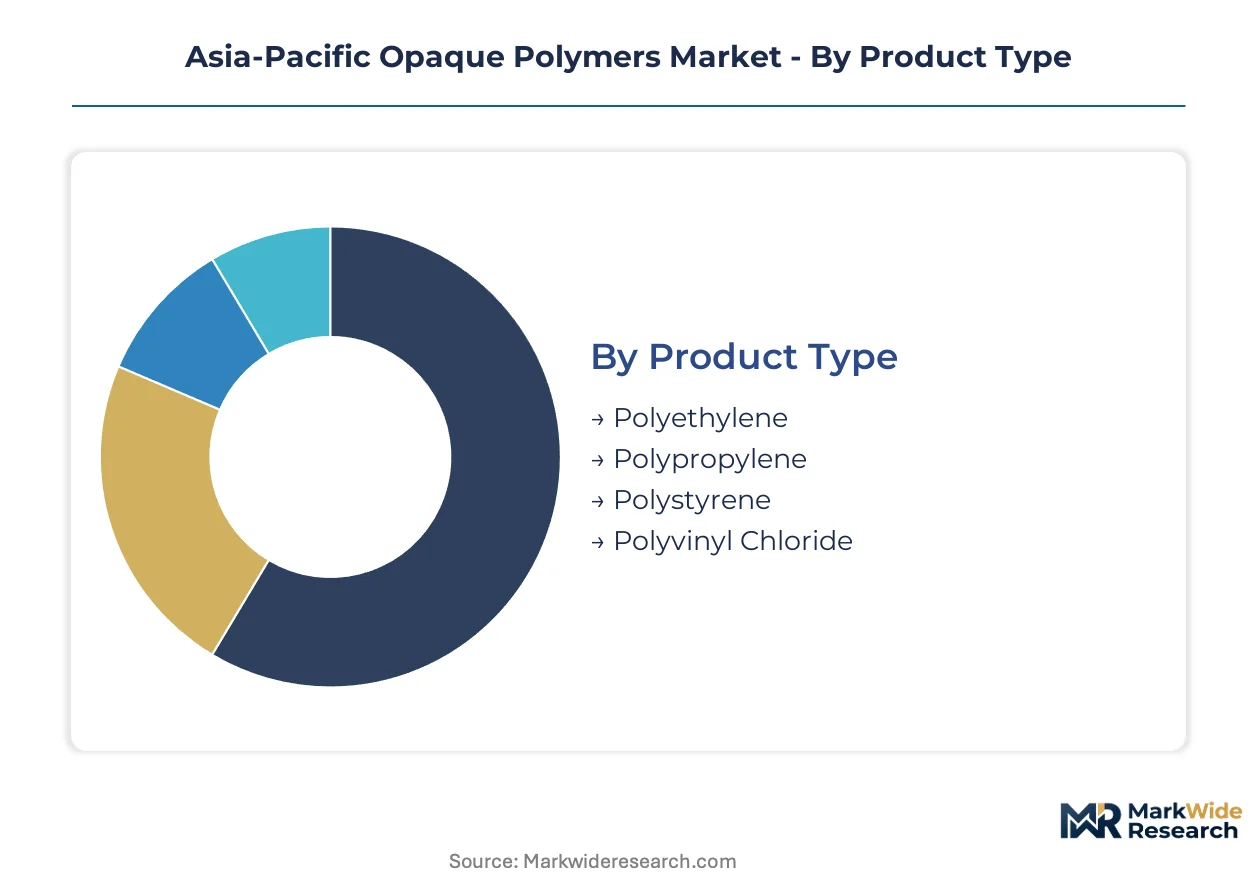
Opaque polymer procurement across Asia-Pacific follows distinct technical and commercial logics that separate commodity volume plays from specialty margin opportunities. Formulators, compounders, and end-use manufacturers each apply divergent selection criteria across resin chemistry, application performance, and supply security dimensions.
Product Type:
Buyers prioritize scattering efficiency against unit cost trade-offs when selecting resin chemistry for reformulation programs.
- Polystyrene:Hollow-sphere thermoplastic particles manufactured via emulsion polymerization deliver mature cost structures and established supply chains. Jiangsu and Zhejiang coastal plants anchor regional capacity, with MEE carbon intensity audits now conditioning qualified supplier status for architectural coatings procurement.
- Polypropylene:Lower-density hollow spheres enable automotive lightweighting specifications in Thailand and Indonesia, where Thai OEMs specify interior plastic components with reduced mass and VOC emissions. Polypropylene opacifiers are expanding most quickly as polymer-scattering efficiency metrics displace pigment-centric benchmarks in mobility applications.
- Polyethylene:Cost-competitive alternative for industrial coatings with moderate opacity requirements and high-volume contract manufacturing.
- Polyvinyl Chloride:Niche deployment in construction sealants and specialty adhesives where chemical resistance properties outweigh scattering performance.
Volume sits with polystyrene; growth tilts toward polypropylene.
Application:
Reformulation urgency varies sharply by formulated product category, with regulatory compliance windows driving divergent adoption timelines.
- Coatings:Waterborne architectural systems command the dominant margin pool as China's GB 30982 enforcement disqualifies titanium dioxide-heavy solvent formulations. Jiangsu exterior wall coating producers compress qualification timelines to maintain distribution licenses under MEE compliance schedules.
- Plastics:Consumer electronics contract manufacturers in Vietnam and Malaysia specify opacified polymers for aesthetic housings, with hollow-sphere integration reducing component weight versus filled alternatives.
- Adhesives:Pressure-sensitive and construction adhesive segments in Japan adopt JIS-compliant low-emission formulations for METI-promoted building material certification.
- Inks:Narrow-format printing applications with specialized opacity requirements and limited reformulation investment cycles.
Coatings absorb the reformulation investment; plastics are climbing the fastest on electronics outsourcing migration.
End User:
Industry-specific performance specifications and certification requirements fragment demand across construction, mobility, and consumer manufacturing verticals.
- Construction:Architectural coatings procurement concentrates in eastern China's manufacturing corridor, with project developers specifying MEE-compliant low-VOC exterior systems for green building certification eligibility.
- Automotive:Thai and Indonesian OEMs integrate hollow-sphere opacifiers into interior component specifications, balancing weight reduction against surface quality requirements for Class-A finishes.
- Consumer Goods:Electronics and appliance manufacturers source opacified polymers for aesthetic differentiation and lightweighting in premium product tiers.
- Packaging:Cost-sensitive applications with opacity requirements met through conventional filler technologies limiting polymer opacifier penetration.
Construction commands current procurement scale; automotive exhibits the steepest expansion trajectory on lightweighting mandates.
Distribution Channel:
Supply security and technical service intensity shape channel selection across customer scale and geographic concentration.
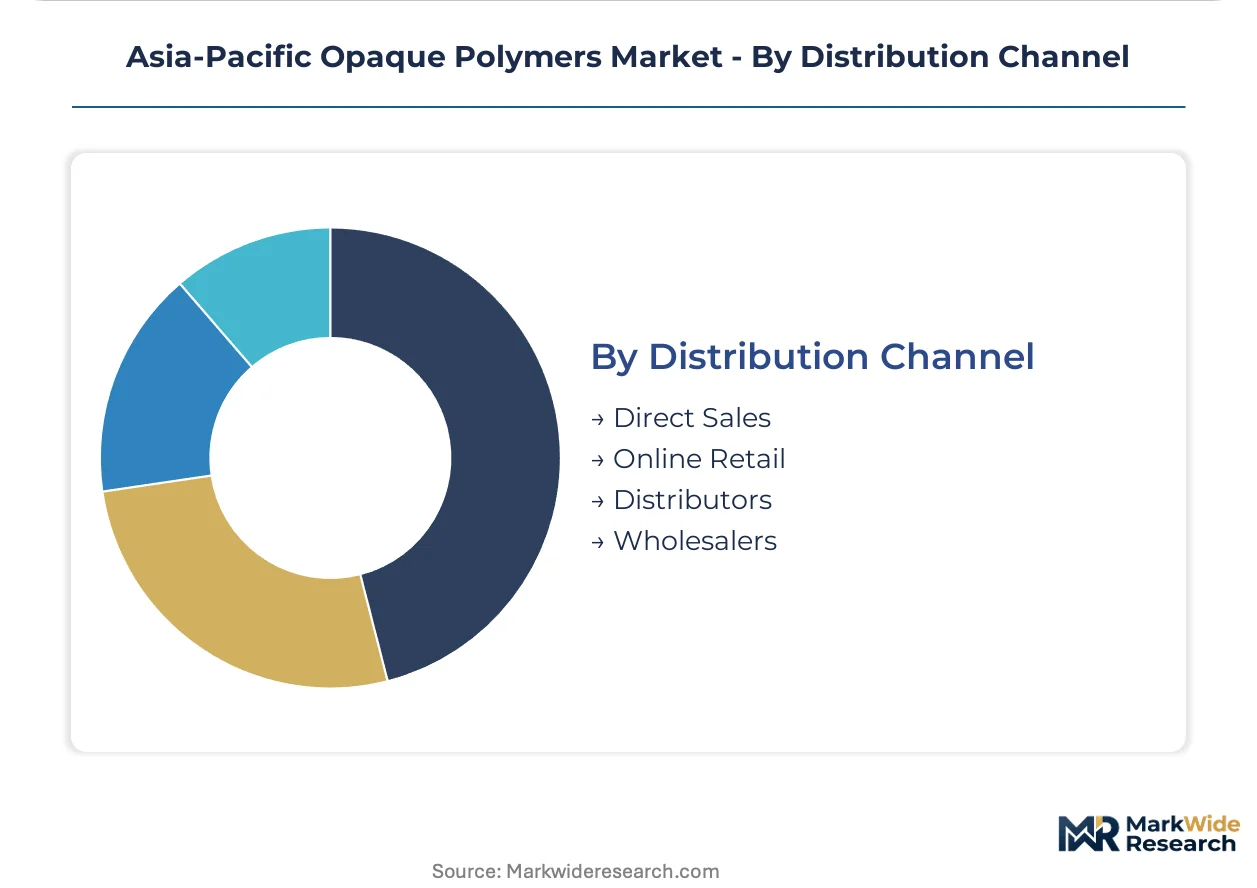
- Direct Sales:Large architectural coatings formulators in South Korea consolidate procurement through single-platform opacifier contracts, unbundling legacy multi-source pigment arrangements for JIS-compliant certification bundles.
- Distributors:Regional chemical distributors serve mid-tier compounders in Vietnam and Indonesia, though reformulation chemist shortages delay technical service response times in these markets.
- Wholesalers:Volume aggregation for standardized polystyrene grades serving cost-optimized industrial coatings segments.
- Online Retail:Emerging procurement channel for sample qualification and small-batch orders in digital-native coatings startups.
Direct sales capture premium reformulation accounts; distributors gain share fastest in Southeast Asian market development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of Asia-Pacific opaque polymer output, while consumption spreads across construction and automotive hubs throughout the region. Manufacturing corridors concentrate in eastern provinces, with demand fragmentation across regulatory jurisdictions driving divergent procurement patterns.
China
Waterborne architectural coatings procurement dominates demand as project developers specify MEE-compliant low-VOC exterior systems. GB 30982 enforcement through 2025-2030 compliance windows mandates reformulation audits for coating producers. The Jiangsu-Zhejiang-Shanghai corridor anchors manufacturing scale, with coastal plants accelerating polymer opacifier qualification timelines to maintain distribution licenses.
Japan
Automotive interior specifications and premium electronics housings drive hollow-sphere polystyrene demand for Class-A surface finishes. METI promotes JIS-compliant low-emission building materials certification for construction applications. Kansai manufacturing clusters around Osaka supply precision-controlled 0.3-0.4 micron particles for OEM quality benchmarks.
India
Industrial coatings reformulation under BIS harmonization creates procurement expansion as waterborne standards mature. The PLI scheme for manufacturing incentivizes domestic production capacity for qualified opacifier formulations. Maharashtra and Gujarat chemical corridors attract technical investment for architectural and automotive coating supply.
Thailand
Automotive lightweighting mandates from Thai OEMs specify hollow-sphere polypropylene opacifiers for interior plastic components. Board of Investment incentives support tier-1 supplier localization for regional vehicle production networks. Eastern Economic Corridor manufacturing zones integrate opacified polymers into reduced-mass, lower-VOC component specifications.
South Korea
Large architectural coatings formulators consolidate procurement through single-platform opacifier contracts for JIS-compliant certification bundles. Seoul-Incheon manufacturing clusters prioritize digital specification platforms with AI-driven raw material selection tools. MFDS-aligned quality standards influence regional export qualification requirements.
Asia-Pacific Opaque Polymers Market Competitive Environment
Top-tier vendors anchor technology licensing and integrated precursor supply, while mid-scale regional producers compete on reformulation service intensity and logistics proximity. Market structure tilts toward consolidated supply in polystyrene opacifiers alongside fragmented specialty positions in polypropylene grades. Three archetypes dominate: integrated petrochemical majors with captive resin supply, regional emulsion polymerization specialists, and coatings-dedicated technical service providers. Capacity expansion and strategic partnerships represent the dominant competitive vectors as producers secure qualified supplier status under tightening MEE carbon intensity documentation.
Within the integrated petrochemical tier, BASF SE and Dow Chemical Company exemplify multinational positioning through Ludwigshafen-derived technology platforms and polyethylene-polypropylene precursor networks respectively. Mitsui Chemicals occupies a specialist position in Japan-grade polystyrene opacifiers for premium automotive and electronics applications. These three entities represent divergent strategic anchors: European-headquartered technology licensors, American-integrated resin suppliers, and Asia-Pacific precision formulation specialists.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Arkema |
| Solvay |
| Formosa Plastics Corporation |
| Mitsui Chemicals |
| INEOS |
| Reliance Industries |
| Hankuck Latices Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Emulsion polymerization chemist concentration in Jiangsu and Zhejiang provinces drives labor-cost differentials that widen pricing-tier spreads between premium JIS-certified formulations and economy-grade industrial coatings.
Pricing Analysis
Margin tightening in standard-grade polystyrene opacifiers reflects titanium dioxide price volatility eroding replacement economics. Three-tier pricing structure across premium, standard, and economy levels separates MEE-compliant certified grades from uncertified industrial formulations. Certification level under China's GB 30982 and volume scale represent the primary price differentiation drivers. Procurement teams at large architectural coatings formulators exhibit lowest price sensitivity due to reformulation urgency, while mid-tier compounders in Vietnam and Indonesia face acute cost compression.
Supply Chain Analysis
Direct-to-formulator channels handle hyperscale demand from South Korean architectural coatings producers consolidating supplier panels. Manufacturing concentrates in China, Japan, and South Korea, with Jiangsu coastal plants anchoring polystyrene precursor supply. Raw material dependencies center on styrene monomer, polypropylene resin, and specialized emulsifiers. Single-source vulnerability in eastern China's manufacturing corridor creates geographic risk exposure. Distribution runs through technical service-intensive direct sales for premium reformulation accounts alongside regional distributors serving Southeast Asian market development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over emulsion polymerization infrastructure determines qualified supplier status under tightening MEE carbon intensity documentation.
For Market Incumbents: Cement qualified supplier positioning through captive polystyrene precursor production in Jiangsu-Zhejiang corridors. Expand technical service headcount to offset reformulation chemist shortages delaying customer response times in Vietnam and Indonesia. Defensive priority rests on securing MEE carbon intensity audit compliance ahead of competitors. For New Entrants and Emerging Players: The premium-to-economy price-point gap in India's nascent waterborne coatings market offers white-space penetration under BIS harmonization timelines. Target Maharashtra and Gujarat chemical corridors for technical investment localization. Pursue PLI-linked domestic production qualification as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with regional emulsion polymerization specialists possessing MEE-compliant documentation and Southeast Asian logistics networks given accelerating reformulation mandates. Long-term viability favors producers with backward integration into styrene monomer supply. Monitor provincial enforcement consistency of carbon intensity documentation requirements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Monomer | Captive precursor supply secures MEE carbon audit compliance and margin protection against feedstock volatility. |
| Technical Service Expansion in Southeast Asia | Dedicated reformulation chemist teams in Vietnam and Indonesia compress customer response times for qualification programs. |
| MEE Compliance Certification Investment | GB 30982 audit readiness maintains distribution licenses for Jiangsu exterior wall coating producers. |
| Joint Venture with Indian Chemical Corridors | Maharashtra and Gujarat partnerships leverage PLI incentives for domestic qualified opacifier production. |
| Digital Specification Platform Development | AI-driven raw material selection tools align with South Korean formulator procurement consolidation trends. |
Study Parameters
Document review covered customs trade data, SEC filings from petrochemical majors, MEE regulatory announcements, and BIS standard drafts, complemented by interviews with plant managers at Jiangsu-Zhejiang emulsion polymerization facilities, procurement leads at South Korean architectural coatings formulators, distribution channel partners in Vietnam and Indonesia, and technical R&D directors at Japan-grade polystyrene specialists. Bottom-up capacity and consumption estimates triangulated against top-down market sizing from trade flow analysis.
Historical volume trajectories cross-referenced against panel input from industry participants informed the analytical framework across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, application category, end-use vertical, and regional regulatory cluster. CAGRs derived from weighted average of demand driver elasticities and capacity expansion schedules. Industry-specific forecast inputs incorporated MEE compliance timeline assumptions and automotive lightweighting specification adoption curves.
Inputs from MEE provincial enforcement offices and BIS harmonization working groups were available through the study window; gaps in real-time carbon intensity audit completion data introduce uncertainty bands around China demand projections. Forecasts reflect documented assumptions regarding regulatory implementation pace and reformulation investment cycles. Periodic stress-testing of base assumptions against provincial enforcement variance and feedstock price volatility is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Polyethylene Naphthalate Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Calendering Resins Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Global Polyolefin Resins Market
Polymers & Resins
Styrenics Market
Polymers & Resins
PEKK Market
Polymers & Resins
Water-Borne Epoxy Resins Market