
 Suture Tapes Market | 2026-2036
Suture Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Suture Tapes Market Analytics
Hospital procurement departments are collapsing their vendor lists for wound closure products while ambulatory surgical centers gain purchasing influence. Arthrex Inc leverages its arthroscopy-driven product ecosystem to dominate sports-medicine suture tape applications. Ethicon Inc anchors its position through Johnson & Johnson's surgical supply chain control and proprietary mesh-tape hybrid technologies. Smith & Nephew plc differentiates via its advanced wound management portfolio that spans sutures, tapes, and negative-pressure systems.
Suture tapes are woven or non-woven fabric strips, typically measuring 0.5 to 5 cm in width, designed to reinforce soft-tissue repairs by distributing mechanical load across suture lines in cardiac and orthopedic procedures. Surgical tapes command the largest revenue pool due to their use in high-acuity operating rooms, while adhesive variants represent the fastest-expanding category as outpatient procedural volumes rise. Polyester-based tapes capture premium pricing because of their tensile strength retention, whereas polypropylene grades compete on cost in high-volume hospital contracts.
FDA 510(k) clearance requirements and the EU MDR's renewed clinical evaluation obligations force manufacturers to maintain extensive biocompatibility documentation and post-market surveillance systems. ISO 10993 biological evaluation standards govern cytotoxicity and skin irritation testing protocols that determine market access eligibility. Stakeholders must monitor how CMS reimbursement adjustments for outpatient procedures and Japan's PMDA quality management inspections reshape regional competitive dynamics.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously elevating technical performance requirements for suture tape manufacturers seeking preferred supplier status.
Growth Catalysts
- EU MDR Clinical Evidence Mandates:Stricter post-market surveillance obligations under the Medical Device Regulation are filtering out marginal competitors and concentrating procurement among established suppliers with robust quality management systems.
- Polyester Tensile Performance:Advanced woven polyester constructions retain mechanical integrity through extended rehabilitation protocols, expanding indications in rotator cuff and ACL reconstruction procedures.
- Japan:Aging demographics and sustained surgical volumes in tertiary medical centers are maintaining steady demand for high-performance wound closure technologies with established reimbursement pathways.
Market Restraints
- Raw Material Concentration:Medical-grade polyester and polypropylene fiber production concentrates among a limited set of specialized chemical suppliers, exposing converters to input cost volatility and allocation constraints.
- 510(k) Documentation Burden:FDA requirements for substantial equivalence demonstrations and biocompatibility testing under ISO 10993 extend product development timelines and elevate regulatory capital requirements.
- Suture Anchor Substitution:Knotless fixation devices and interference screws are capturing select ligament repair applications where tape reinforcement was previously standard.
Strategic Opportunities
- Germany:Outpatient surgical centers are gaining purchasing autonomy outside traditional hospital procurement hierarchies, creating direct sales channel potential for specialized tape manufacturers.
- Adhesive Tape Convergence:Pressure-sensitive adhesive formulations combined with woven reinforcement substrates are enabling single-operator application in ambulatory settings without suture expertise.
- CMS Bundled Payments:Reimbursement compression for hospital-based procedures is accelerating site-of-care migration to lower-cost settings where simplified closure technologies command preference.
Industry Challenges
- Biocompatibility Testing Bottlenecks:Cytotoxicity and sensitization studies required under ISO 10993-5 and ISO 10993-10 are extending certification timelines as contract laboratory capacity constraints accumulate.
- Legacy ERP Integration:Hospital supply chain systems require extensive data formatting for Unique Device Identification compliance, forcing manufacturers to maintain parallel inventory tracking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suture Tapes Market |
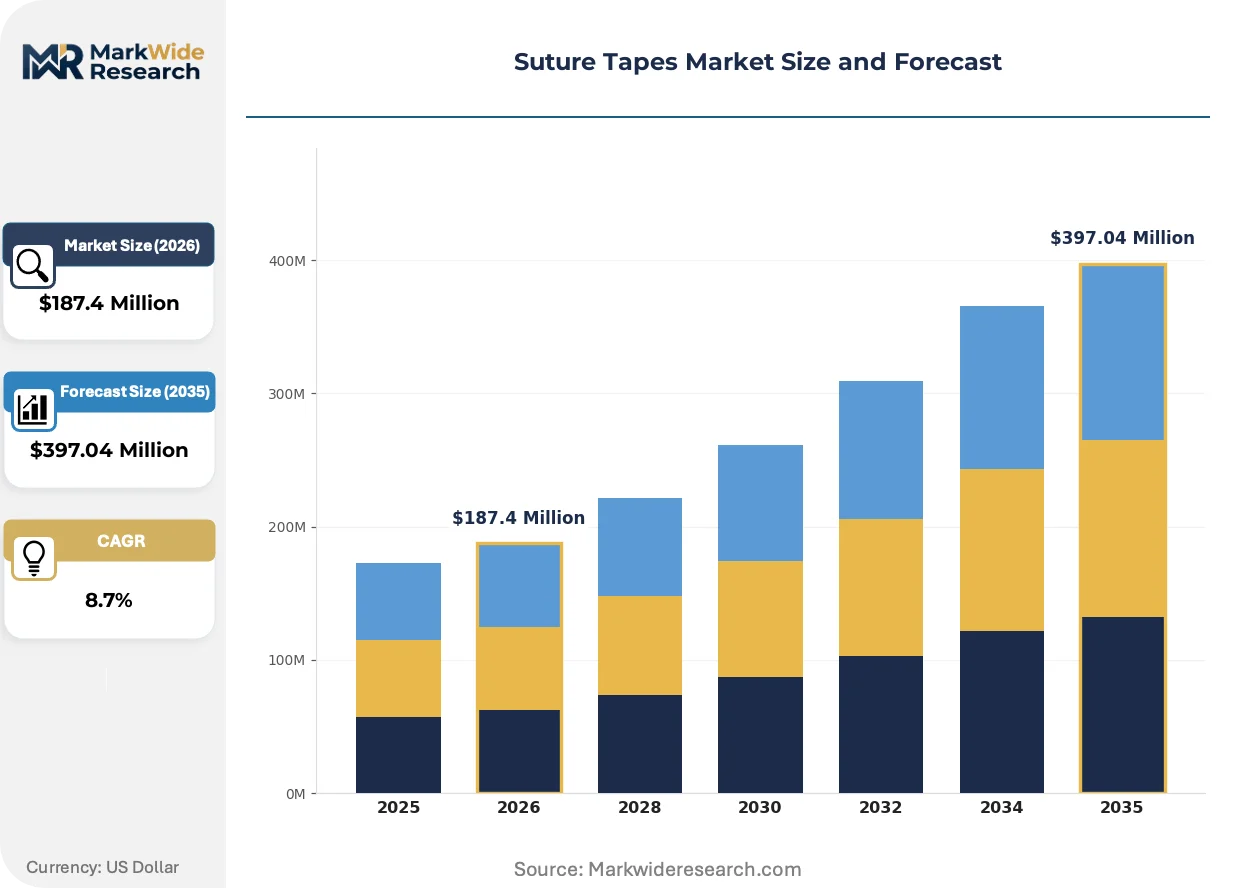
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical, Adhesive, Non-Adhesive, Paper Material: Polypropylene, Cotton, Polyester, Silicone End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Application: Cardiac Surgery, Orthopedic Surgery, Cosmetic Surgery, Dermatologic Procedures |
| Companies Covered | Arthrex Inc, ConMed Corporation, Ethicon Inc, Medtronic plc, 3M Company, Smith & Nephew plc, B. Braun Melsungen AG, Stryker, Zimmer Biomet Holdings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suture Tapes Market Evolving Landscape
Material science advances and regulatory harmonization pressures are simultaneously elevating performance thresholds and compressing commercialization timelines for next-generation closure products.
Antimicrobial-impregnated suture tapes are fragmenting the standard product landscape by addressing surgical site infection risk in high-comorbidity patient populations. Orthopedic departments in United States academic medical centers are piloting chlorhexidine-coated variants for revision procedures. This technology is fragmenting procurement decisions into infection-risk-stratified purchasing categories rather than universal product standards.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to reconstruct clinical evidence packages for legacy devices grandfathered under previous directives. Small and mid-size suppliers without predicate device libraries face disproportionate compliance costs. German notified bodies are extending review queues, delaying market access for tape products requiring renewed CE marking.
Consolidated purchasing cooperatives are displacing individual hospital contracting authority across United States health systems. Value analysis committees now mandate head-to-head mechanical testing data before adding suture tapes to formularies. This concentration is most visible in California and Texas, where multi-hospital networks leverage combined surgical volumes to extract performance guarantees and inventory management concessions.
Suture Tapes Market Segmentation
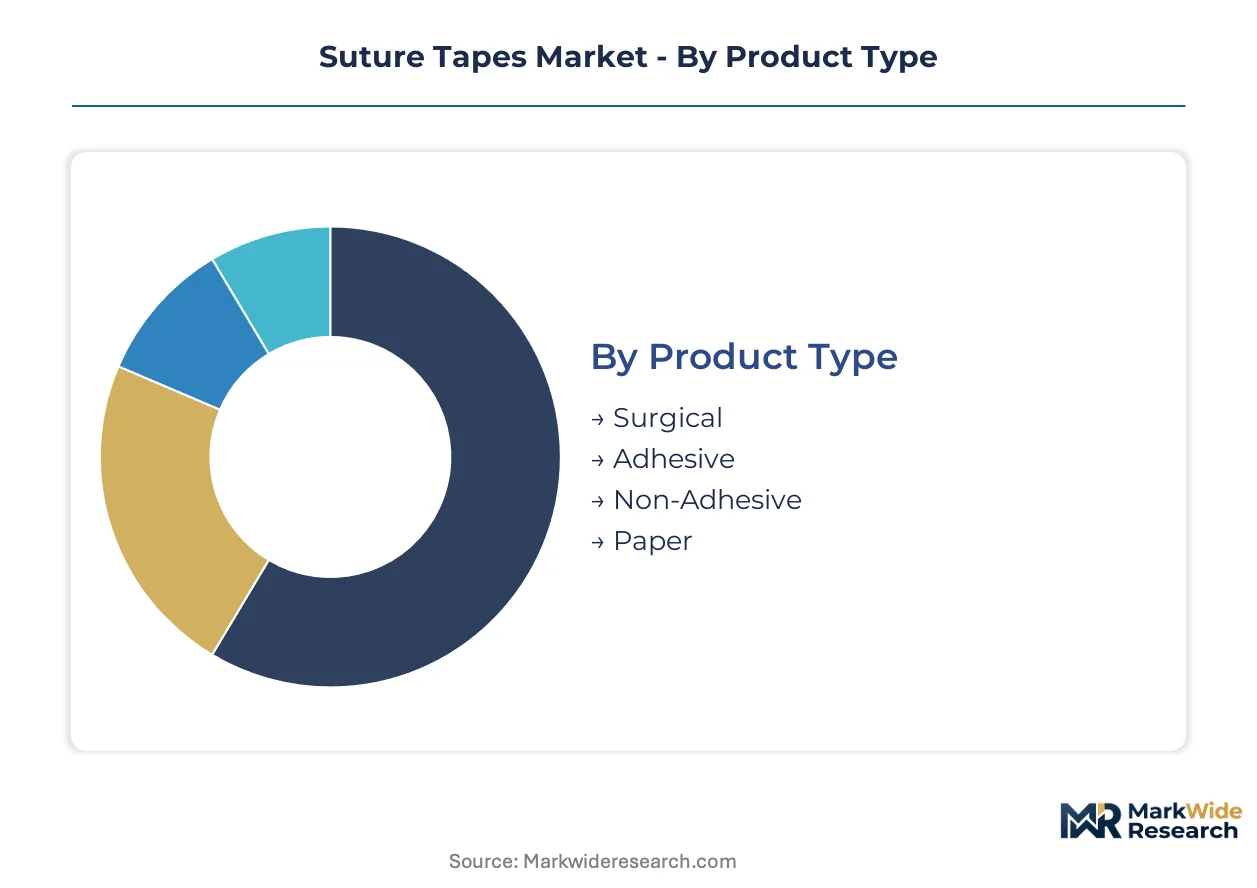
Suture tape procurement patterns diverge sharply across clinical settings and material specifications. Manufacturers align product portfolios to these fault lines to secure preferred supplier status with consolidated health systems.
Product Type:
Surgical tapes dominate domestic hospital procurement in the United States and Germany, while adhesive variants drive export-led growth into Asian ambulatory markets.
- Surgical:Woven polyester and polypropylene strips engineered for load-bearing soft-tissue reinforcement in operating rooms. United States academic medical centers specify these for rotator cuff and ACL reconstruction protocols where mechanical integrity through rehabilitation is non-negotiable.
- Adhesive:Pressure-sensitive variants combining woven substrates with medical-grade acrylic or silicone adhesives. Ambulatory surgical centers in Japan and South Korea are standardizing these for single-operator application without specialized suturing expertise, compressing procedure time and labor costs.
- Non-Adhesive:Plain woven tapes requiring mechanical fixation via sutures or staples, positioned for cost-sensitive hospital contracts where labor substitution is not the priority.
- Paper:Low-tack breathable tapes for superficial wound closure and dermatologic applications, concentrated in retail pharmacy channels and primary care settings.
Surgical tapes command the established base. The steepest expansion runs through adhesive formats.
Material:
Polyester and polypropylene grades split procurement decisions between performance-critical orthopedic applications and high-volume general surgery contracts.
- Polyester:High-tenacity woven constructions retaining tensile strength through extended rehabilitation. German and Japanese tertiary centers specify these for cardiac and orthopedic procedures where suture line failure carries catastrophic risk.
- Polypropylene:Lightweight monofilament-based tapes competing on unit cost in high-volume hospital agreements. United States integrated delivery networks leverage combined purchasing power to extract favorable pricing on standardized polypropylene specifications.
- Cotton:Breathable natural fiber tapes for superficial closure and patient populations with synthetic material sensitivities, concentrated in pediatric and dermatologic settings.
- Silicone:Soft, atraumatic variants for fragile skin and long-term wound management, gaining traction in homecare and geriatric applications.
Polyester anchors premium-tier procurement. Polypropylene captures volume-driven expansion.
End User:
Hospital purchasing departments consolidate vendor lists while ambulatory and homecare channels fragment decision authority across smaller clinical units.
- Hospitals:Centralized procurement of high-performance tapes for cardiac and orthopedic suites, with value analysis committees demanding mechanical testing data and inventory management concessions.
- Ambulatory Surgical Centers:Fastest-growing channel in United States outpatient migration, favoring simplified adhesive formats that reduce procedure complexity and staffing requirements.
- Clinics:Decentralized purchasing of mid-tier products for minor surgical procedures, with limited negotiating leverage against manufacturer list pricing.
- Homecare:Emerging demand for patient-applied closure products, particularly silicone and paper tapes for chronic wound management outside institutional settings.
Hospitals retain the core revenue base. Ambulatory surgical centers are climbing the fastest.
Application:
Orthopedic and cardiac procedures concentrate demand for high-performance reinforcement, while cosmetic and dermatologic applications expand into lower-acuity settings.
- Orthopedic Surgery:Ligament repair and tendon fixation procedures in United States and German sports medicine departments. Load-distribution requirements drive specification of woven polyester tapes with documented cyclic fatigue resistance.
- Cardiac Surgery:Sternum closure and vascular anastomosis reinforcement in tertiary centers. Japanese and United States academic hospitals maintain stringent biocompatibility and tensile performance standards.
- Cosmetic Surgery:Aesthetic closure applications where scar minimization competes with mechanical performance as the primary selection criterion.
- Dermatologic Procedures:Superficial excision and biopsy closure in office-based settings, favoring low-trauma adhesive and paper tape formats.
Orthopedic surgery anchors the established demand base. Cosmetic surgery is expanding most quickly as outpatient procedural volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export woven polyester suture tapes to United States hospital systems, while Japanese suppliers serve domestic tertiary centers with premium-grade reinforcement products.
United States
Academic medical centers in California and Texas drive specification of high-tenacity tapes for rotator cuff protocols. FDA 510(k) clearance pathways filter marginal competitors from the procurement base. The Greater Boston cluster anchors biomechanical testing infrastructure that validates cyclic fatigue resistance claims.
Germany
Tertiary centers in Bavaria and North Rhine-Westphalia specify polyester tapes for cardiac sternum closure where mechanical failure carries catastrophic risk. EU MDR Article 10 technical documentation requirements extend review queues through notified bodies in Berlin. The Stuttgart industrial corridor concentrates precision weaving capacity for medical-grade fiber conversion.
Japan
Aging demographics sustain surgical volumes in Tokyo and Osaka metropolitan tertiary centers. PMDA quality management inspections enforce biocompatibility documentation standards that parallel FDA requirements. The Kobe medical device cluster supports specialized coating capabilities for antimicrobial-impregnated variants.
South Korea
Ambulatory surgical centers in Seoul Capital Area standardize adhesive tape formats for single-operator application. MFDS device registration requirements align with international standards but compress approval timelines relative to EU processes. The Busan-Ulsan corridor supplies medical-grade polypropylene fiber to regional converters.
United Kingdom
NHS procurement consolidation favors suppliers with established CE marking and UKCA transition documentation. The Cambridge-Oxford-London triangle anchors translational research partnerships between orthopedic departments and materials science programs. Value analysis committees in London teaching hospitals demand head-to-head mechanical testing data before formulary inclusion.
Suture Tapes Market Competitive Landscape
Player mix skews toward diversified surgical supply conglomerates with orthopedics-focused divisions. Three to five entities control the majority of hospital procurement contracts through integrated delivery network relationships. Strategic archetypes separate into arthroscopy-ecosystem integrators, wound-management portfolio owners, and diversified device conglomerates. Competitive moves concentrate on procurement consolidation defense and ambulatory channel expansion.
Within the arthroscopy-ecosystem tier, Arthrex Inc and Smith & Nephew plc exemplify players leveraging sports-medicine procedural volume to anchor tape specification. Ethicon Inc occupies a position representing diversified supply chain control through Johnson & Johnson's hospital distribution infrastructure. Zimmer Biomet Holdings Inc and Stryker sit within the orthopedic-implant conglomerate archetype, using ligament repair hardware relationships to cross-sell reinforcement products.
| Leading Market Players |
|---|
| Arthrex Inc |
| ConMed Corporation |
| Ethicon Inc |
| Medtronic plc |
| 3M Company |
| Smith & Nephew plc |
| B. Braun Melsungen AG |
| Stryker |
| Zimmer Biomet Holdings Inc |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between United States integrated delivery networks and polyester fiber suppliers lock in both supply access and price visibility for high-performance suture tape grades, insulating hospital procurement from medical-grade polymer spot market volatility while compressing margins for converters without backward integration into fiber production.
Pricing Analysis
Next-generation antimicrobial-impregnated tapes command a 40-60% premium over standard woven polyester constructions, while prior-generation polypropylene grades face sustained cost compression in high-volume hospital contracts. Pricing stratifies across premium, standard, and economy tiers driven by ISO 10993 certification grade and tensile performance documentation. Cost compression in polypropylene segments is intensifying because United States GPOs leverage combined surgical volumes to extract standardized pricing. Ambulatory surgical centers exhibit the highest price sensitivity, whereas German tertiary cardiac centers prioritize mechanical integrity over unit cost.
Supply Chain Analysis
Strategic stockpiling of medical-grade polyester fiber dominates procurement behavior among Japanese and German converters, contrasting with just-in-time inventory practices at United States ambulatory distributors exposed to allocation risk. Raw material concentration centers on Germany, Japan, and the United States for precision weaving capacity, with medical-grade polypropylene fiber sourcing from South Korean petrochemical complexes. Supply chain risk hinges on single-source vulnerability for chlorhexidine coating substrates used in antimicrobial variants. Distribution runs through hospital distribution consortia and specialized surgical supply distributors serving ambulatory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The suture tapes market functions as a service-attach opportunity where biocompatibility testing documentation and post-market surveillance support contracts expand faster than hardware unit shipments, as EU MDR compliance obligations convert one-time product sales into recurring regulatory service relationships.
For Market Incumbents: Secure preferred supplier status with consolidating United States health systems by embedding inventory management services into GPO contracts, while investing in captive coating capabilities for antimicrobial variants to defend against knotless fixation device substitution in ligament repair applications. For New Entrants and Emerging Players: Lead with adhesive tape formats targeting South Korean and Japanese ambulatory surgical centers, where simplified application protocols and single-operator deployment create the most penetrable entry point outside established hospital procurement hierarchies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap converters with established predicate device libraries and EU MDR technical documentation capabilities, with long-term viability hinging on regulatory service infrastructure rather than manufacturing scale alone; watch FDA 510(k) clearance velocity for antimicrobial-impregnated variants as the inflection signal indicating which coating technologies achieve clinical adoption.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Reconstruction | Legacy device CE marking renewal filters marginal competitors from German procurement pools. |
| Antimicrobial Coating Partnership | Chlorhexidine-impregnated variants address surgical site infection risk in United States revision procedures. |
| Ambulatory Distribution Channel Expansion | Direct sales relationships with South Korean day-surgery centers bypass hospital procurement consolidation. |
| Biocompatibility Testing Infrastructure Investment | In-house ISO 10993-5 and ISO 10993-10 capabilities compress certification timelines for next-generation products. |
| Hospital System Inventory Management Integration | UDI-compliant ERP data formatting services secure preferred supplier status with United States IDNs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at medical device manufacturers, validated against secondary sources including FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, hospital procurement contract registries, and ISO 10993 biocompatibility testing records. Bottom-up unit demand estimates triangulated with top-down market sizing across material grades and clinical applications.
Across the analysis window, volume and value outputs reflect segment-level modeling across product type, material specification, end-user channel, and application procedure category, with CAGRs derived from surgical volume projections, reimbursement trend analysis, and technology substitution elasticity estimates. Forecast inputs incorporate orthopedic procedure migration patterns from inpatient to ambulatory settings and antimicrobial coating adoption curves in high-comorbidity patient populations.
Underlying assumptions cover sustained FDA 510(k) clearance pathways and stable EU MDR notified body capacity, with deviation risk concentrated in raw material allocation constraints for medical-grade polymers and accelerated knotless fixation device substitution in ligament repair protocols. Revision becomes warranted when antimicrobial coating regulatory requirements cross thresholds that extend biocompatibility testing timelines beyond current contract laboratory capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
Acid Citrate Dextrose Tubes Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Foley Trays Market