
 Plastic Bandages Market | 2026-2036
Plastic Bandages Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Bandages Market Outlook
China is reconfiguring regional supply dynamics for plastic bandages through expanded domestic manufacturing of medical-grade adhesives and non-woven substrates. Johnson & Johnson leverages its established hospital procurement networks across North America and Europe to sustain volume leadership in adhesive wound care. 3M competes through proprietary breathable film technologies that differentiate its product portfolio in surgical and sports medicine segments. Medline Industries anchors significant private-label capacity, controlling distribution economics for mid-tier pharmacy and home care channels.
Plastic bandages are disposable medical dressings comprising a perforated plastic film or strip coated with a pressure-sensitive adhesive, typically incorporating an absorbent non-stick pad for wound coverage and protection against mechanical irritation and microbial ingress. The primary commercial purpose centers on managing minor acute wounds, post-surgical incision sites, and superficial trauma across clinical and consumer settings. Adhesive bandages occupy the largest share of product type demand, reflecting universal household familiarity and pharmacy shelf presence, while hydrocolloid material variants represent the fastest-expanding segment due to superior moisture-retention properties that accelerate re-epithelialization in chronic and surgical wounds. Pediatric care applications command premium positioning within the application dimension, as guardians prioritize hypoallergenic formulations and decorative compliance features for juvenile patients.
The FDA governs plastic bandages as Class I medical devices, mandating biocompatibility testing and quality system regulation compliance that elevates barrier costs for new market entrants. In Europe, the MDR and REACH frameworks impose stringent chemical substance disclosure and clinical evaluation requirements on adhesive wound care manufacturers seeking CE marking access. Stakeholders must monitor evolving regulatory convergence between FDA and EMA standards for silicone-based adhesives, as harmonization would reshape formulation R&D priorities and cross-border product registration strategies.
Market Dynamics
Hospital procurement consolidation is compressing supplier margins and forcing adhesive wound care manufacturers to defend shelf space through differentiated material certifications and just-in-time delivery guarantees.
Growth Catalysts
- Outpatient surgical volume expansion:Ambulatory surgery centers in the United States are displacing inpatient procedures, generating sustained demand for disposable post-operative dressings with shorter wear-time requirements.
- MDR compliance deadlines:European manufacturers accelerating clinical evaluation documentation for CE marking renewal are upgrading product portfolios to premium silicone-adhesive formulations.
- Aging household demographics:Japan's expanding elderly population is driving pharmacy channel replenishment of chronic wound management supplies for home-based care.
Market Restraints
- Medical-grade adhesive supply concentration:Production of hypoallergenic acrylate formulations clusters among three specialty chemical suppliers, exposing finished goods manufacturers to input allocation risk.
- Biocompatibility testing cost escalation:FDA-mandated cytotoxicity and sensitization protocols for Class I device reclassification are extending product development timelines and elevating barrier costs for mid-tier entrants.
- Advanced wound dressing substitution:Negative pressure wound therapy systems and bioactive dressings are capturing moderate-complexity cases previously managed with standard plastic bandages.
Strategic Opportunities
- Pediatric decorative segment:Character-licensed bandage formats with hypoallergenic claims command 40-60% price premiums in United States pharmacy retail.
- Sports medicine channel expansion:Marathon and triathlon event organizers are establishing direct procurement relationships with breathable film manufacturers for participant first-aid kits.
- China domestic manufacturing incentives:NMPA streamlined registration pathways for locally produced medical-grade non-wovens are enabling import substitution strategies for multinational brand owners.
Industry Challenges
- Silicone adhesive formulation expertise scarcity:Cross-functional talent combining polymer chemistry and regulatory documentation experience commands premium compensation and extended recruitment cycles.
- Legacy sterilization infrastructure retrofitting:Ethylene oxide facility closures in the United States are forcing contract manufacturers to validate alternative terminal sterilization methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Bandages Market |
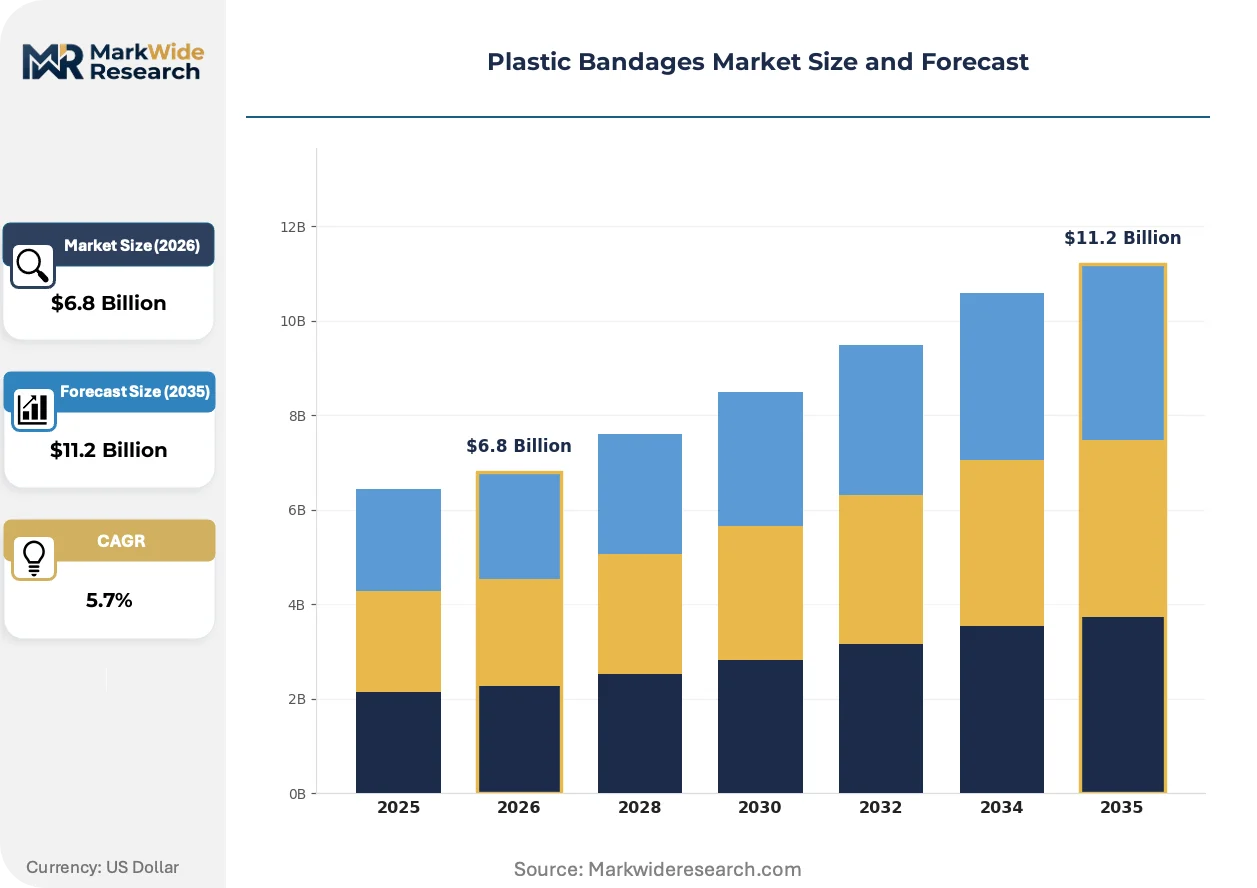
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Bandages, Elastic Bandages, Waterproof Bandages, Antiseptic Bandages Application: Wound Care, Surgical Use, Sports Injuries, Pediatric Care Material: Plastic, Fabric, Foam, Hydrocolloid End User: Hospitals, Clinics, Pharmacies, Home Care |
| Companies Covered | Johnson & Johnson, 3M, Beiersdorf, BSN Medical, Medline Industries, Smith & Nephew, ConvaTec, B. Braun, Lohmann and Rauscher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Bandages Market Strategic Shifts
Digital printing and microfluidic sensing layers are transforming plastic bandages from passive protective coverings into interactive health monitoring interfaces, compressing the innovation cycle for consumer-facing wound care brands.
Micro-perforated breathable film substrates with integrated moisture vapor transmission rate optimization are virtualizing the traditional trade-off between adhesive strength and skin-friendly removal. Hospital wound care specialists are specifying these materials for post-surgical incision coverage where maceration risk previously limited wear duration. The technology is virtualizing inventory requirements by enabling single-SKU solutions across multiple wound moisture profiles.
REACH substance restriction expansions targeting residual monomers in acrylate adhesives are forcing European manufacturers to reformulate core product lines ahead of 2025 sunset dates. The ECHA regulatory pressure is accelerating supplier qualification audits and raw material traceability investments. Wound care contract manufacturers serving EU hospital systems are consolidating supplier bases to reduce compliance documentation burden.
Home care buyers are consolidating purchase decisions through e-pharmacy subscription models that displace traditional pharmacy impulse purchases. Amazon Pharmacy and Walgreens digital platforms are capturing recurring replenishment orders for chronic wound patients. This channel migration is most visible in United States suburban markets where retail pharmacy access constraints coincide with Medicare Advantage home delivery benefits.
Plastic Bandages Market Segmentation
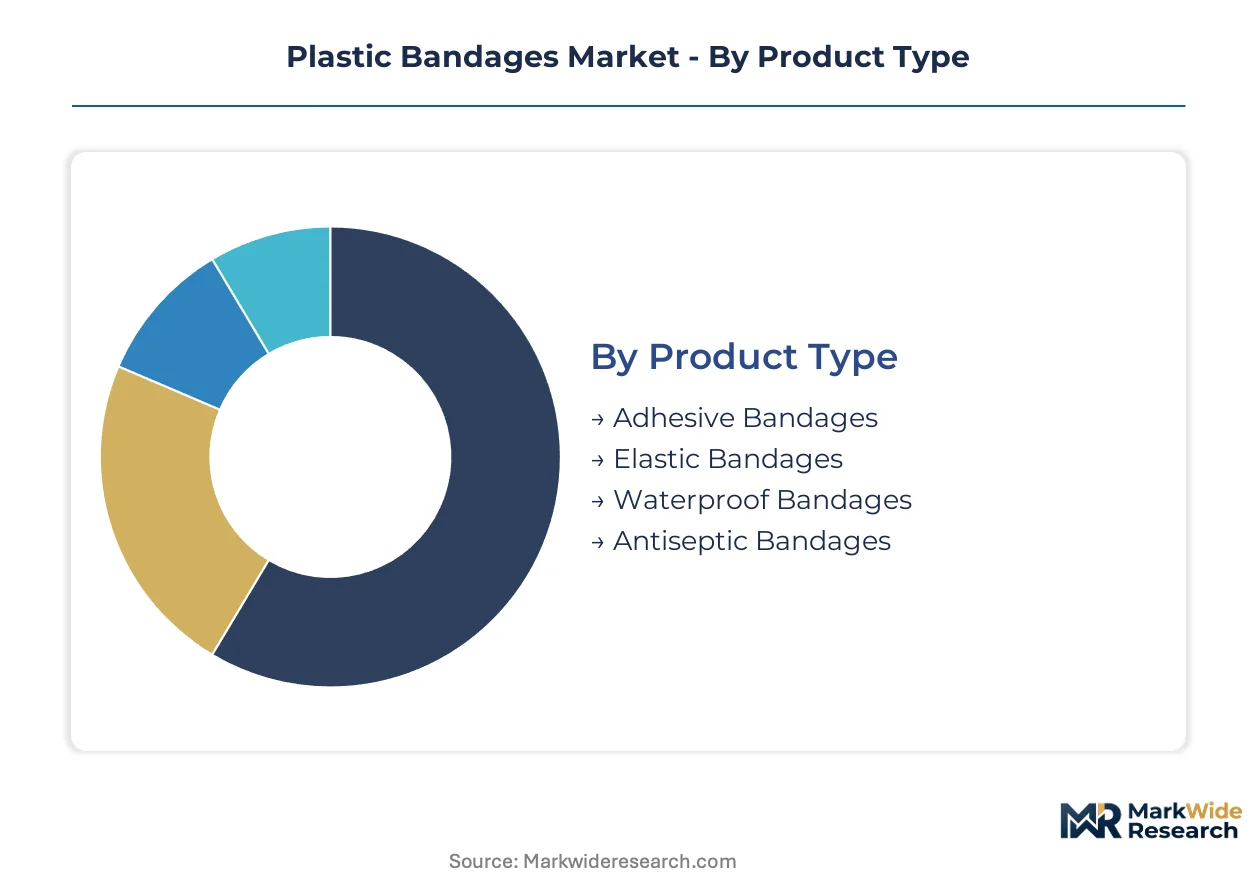
Segmentation in plastic bandages reveals divergent margin structures across material technologies and procurement channels. Hospital wound care specialists specify breathable film substrates while pharmacy retail drives volume through standardized adhesive formats.
Product Type:
Cost tier differentiation separates commodity pharmacy formats from premium clinical specifications with specialized adhesive chemistries.
- Adhesive Bandages:Perforated plastic film strips with pressure-sensitive acrylate coatings and absorbent non-stick pads dominate household and clinical procurement. United States pharmacy chains specify these for high-velocity SKU rotation in first-aid aisles, with hospital systems negotiating volume contracts for standardized post-operative coverage.
- Elastic Bandages:Woven cotton or synthetic wraps with self-adherent or clip closures provide compression therapy for sprains and venous insufficiency. Sports medicine clinics in Germany and Japan specify these for athletic injury management, with marathon event medical tents stocking co-branded formats for participant care.
- Waterproof Bandages:Occlusive polyurethane film barriers with enhanced moisture resistance for showering and aquatic activity.
- Antiseptic Bandages:Silver-ion or benzalkonium chloride-impregnated pads delivering antimicrobial protection for high-infection-risk wounds.
Adhesive Bandages holds installed capacity. Elastic Bandages is rotating up the share rankings.
Application:
Volume concentration varies sharply between acute trauma episodes and recurring chronic wound management protocols.
- Wound Care:Daily dressing changes for abrasions, lacerations, and diabetic ulcers require moisture-balanced substrates. United States home care agencies specify hydrocolloid variants for elderly patients with pressure injuries, with Medicare Advantage plans covering recurring replenishment through e-pharmacy channels.
- Surgical Use:Sterile incision coverings with specified MVTR ratings prevent maceration while maintaining barrier integrity. Ambulatory surgery centers in Texas and Florida specify breathable film technologies for same-day discharge protocols, with shorter wear-time requirements driving SKU proliferation.
- Sports Injuries:Athlete-specific formats with enhanced adhesion for perspiration resistance.
- Pediatric Care:Hypoallergenic formulations with character licensing for compliance-driven juvenile applications.
Wound Care anchors procurement volume. Surgical Use is expanding most quickly as outpatient displacement accelerates.
Material:
Margin structure stratifies across substrate technologies with distinct regulatory qualification burdens and raw material input profiles.
- Plastic:Polyethylene and polyurethane films with micro-perforation for vapor transmission constitute the baseline substrate technology. Chinese domestic manufacturers are scaling medical-grade non-woven production to reduce import dependency for multinational brand owners serving Asia-Pacific markets.
- Fabric:Woven cotton or rayon blends with superior conformability for joint and contour wound coverage.
- Foam:Polyurethane foam substrates with high absorbency for exuding wounds.
- Hydrocolloid:Carboxymethyl cellulose and gelatin matrices forming gel layers upon exudate contact. Japan's aging household demographics sustain pharmacy channel replenishment for home-based pressure ulcer management, with METI quality certifications differentiating premium import brands.
Plastic maintains manufacturing scale. Hydrocolloid is climbing the fastest as chronic wound prevalence rises.
End User:
Customer type determines packaging specifications, sterilization requirements, and procurement decision-making authority.
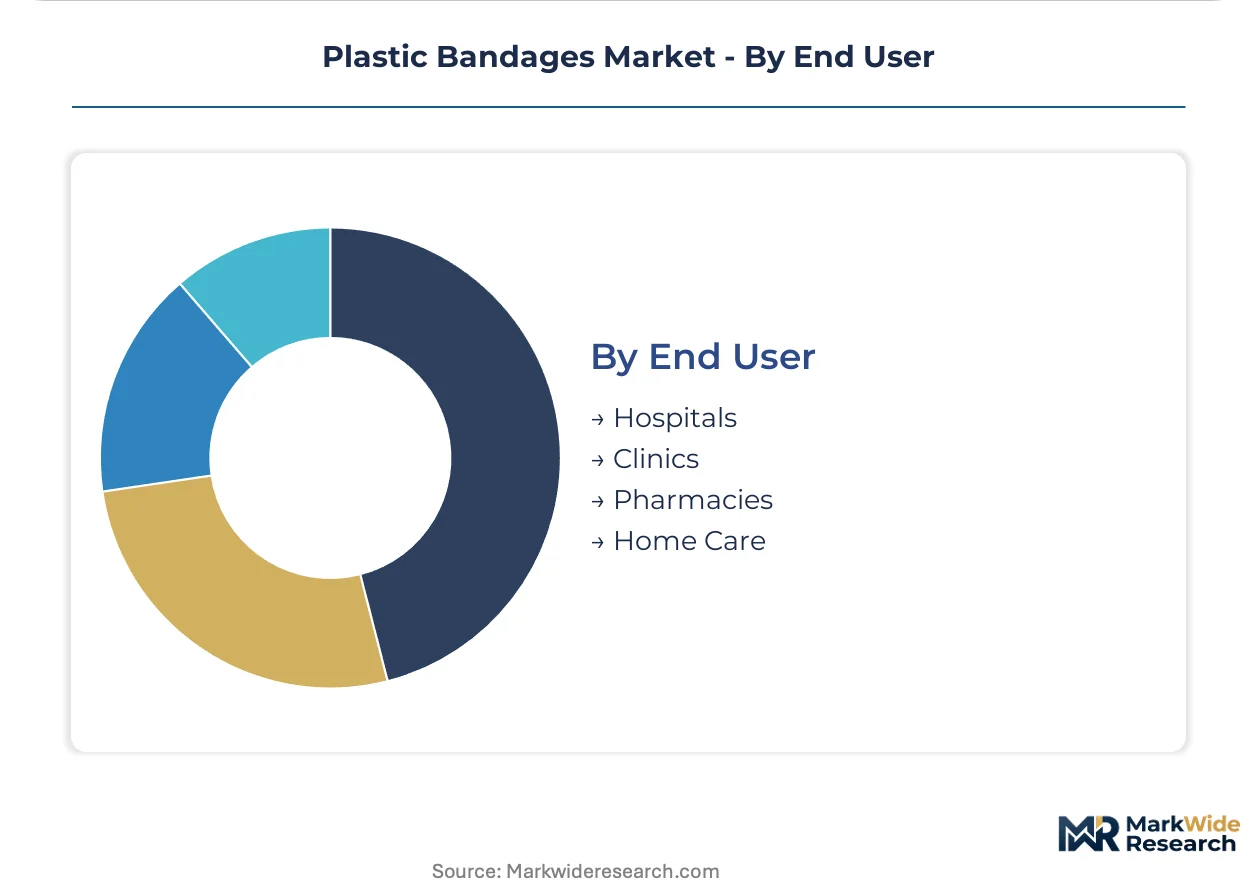
- Hospitals:Centralized purchasing departments specify material certifications and just-in-time delivery guarantees. FDA-mandated biocompatibility documentation elevates supplier qualification barriers, with consolidated health systems in California and New York compressing vendor margins through multi-year contracts.
- Clinics:Physician office laboratories and urgent care centers with intermediate volume requirements.
- Pharmacies:Retail chains and independent dispensaries with impulse-purchase and subscription replenishment models. Amazon Pharmacy and Walgreens digital platforms capture recurring orders for chronic wound patients in United States suburban markets with Medicare Advantage home delivery benefits.
- Home Care:Direct-to-patient channels for elderly and mobility-limited consumers.
Hospitals control specification authority. Pharmacies is gaining share fastest through digital channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA medical device quality standards anchor procurement specifications in the United States, the dominant geography for plastic bandage consumption. Outpatient surgical volume expansion and aging household demographics sustain demand concentration across North America, Europe, and Asia-Pacific.
United States
Ambulatory surgery centers in Texas and Florida displace inpatient procedures, generating sustained demand for disposable post-operative dressings with shorter wear-time requirements. FDA Class I device biocompatibility testing mandates elevate supplier qualification barriers for market entrants. Consolidated health systems in California and New York compress vendor margins through multi-year procurement contracts.
Germany
Sports medicine clinics specify elastic bandages for athletic injury management, with marathon event medical tents stocking co-branded formats for participant care. ECHA REACH substance restrictions targeting residual monomers in acrylate adhesives force reformulation investments ahead of regulatory deadlines. The Rhine-Ruhr industrial corridor hosts specialty chemical suppliers producing medical-grade adhesive formulations.
China
NMPA streamlined registration pathways for locally produced medical-grade non-wovens enable import substitution strategies for multinational brand owners. Domestic manufacturing incentives accelerate scaling of medical-grade adhesive and substrate production. The Yangtze River Delta region concentrates contract manufacturing capacity serving Asia-Pacific distribution networks.
Japan
Expanding elderly populations drive pharmacy channel replenishment of chronic wound management supplies for home-based care. METI quality certifications differentiate premium import brands in the domestic market. The Kanto region around Tokyo anchors distribution infrastructure for elderly care product logistics.
United Kingdom
NHS procurement consolidation shifts adhesive wound care purchasing toward standardized national contracts with volume discount structures. MHRA post-Brexit regulatory autonomy maintains alignment with MDR technical standards while streamlining UKCA marking pathways. The Midlands region concentrates medical device distribution warehousing serving national hospital networks.
Plastic Bandages Market Competitive Environment
Capability concentration sits with specialty adhesive formulators; scale advantage sits with diversified healthcare conglomerates. The market structure tiers between multinational brand owners with hospital procurement networks and mid-tier private-label manufacturers controlling pharmacy economics. Three archetypes dominate: diversified medical device conglomerates, specialty wound care pure-plays, and contract manufacturing specialists. Competitive moves center on silicone adhesive formulation R&D and just-in-time delivery infrastructure investments.
Within the diversified healthcare tier, Johnson & Johnson and 3M exemplify scale-driven positioning through established North American and European hospital networks. Medline Industries occupies a distinct private-label anchor position, controlling distribution economics for mid-tier pharmacy and home care channels. These three entities represent the structural poles around which competitive dynamics organize.
| Leading Market Players |
|---|
| Johnson & Johnson |
| 3M |
| Beiersdorf |
| BSN Medical |
| Medline Industries |
| Smith & Nephew |
| ConvaTec |
| B. Braun |
| Lohmann and Rauscher |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese medical-grade non-woven substrate production is compressing input costs while simultaneously eroding supplier bargaining power across Asia-Pacific procurement networks. This utilization imbalance forces multinational brand owners to renegotiate contract terms and compress finished goods pricing to defend pharmacy shelf space.
Pricing Analysis
Geographic price spreads between United States hospital contracts and European pharmacy retail exceed 35 percent on equivalent adhesive bandage SKUs. Three-tier pricing structure across premium silicone-adhesive, standard acrylate, and economy unbranded formats dominates procurement negotiations. Price differentiation hinges on FDA biocompatibility certification tier and volume scale commitments from consolidated health systems. Pricing pressure stems from hospital procurement consolidation in California and New York, with ambulatory surgery centers exhibiting highest price sensitivity and pediatric decorative segments showing least.
Supply Chain Analysis
Contract manufacturing concentration sits with Yangtze River Delta facilities serving multinational brand owners and domestic Chinese producers scaling medical-grade adhesive capacity. Raw material dependencies draw from South Korean silicone polymer suppliers, German specialty chemical formulators, and domestic Chinese non-woven substrate producers. Single-source vulnerability concentrates in hypoallergenic acrylate adhesive production clustered among three specialty chemical suppliers. Distribution runs through hospital GPO networks, pharmacy retail chains, and emerging e-pharmacy subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as outpatient surgical displacement creates specialized SKU demand for shorter wear-time dressings across ambulatory settings. This demand-side shift fragments procurement authority away from centralized hospital purchasing toward clinic-level specification.
For Market Incumbents: Entrench hospital procurement relationships through just-in-time delivery infrastructure investments and silicone adhesive formulation R&D capabilities. Defend against private-label encroachment by securing multi-year material certification contracts with consolidated health systems. Backward integration into medical-grade adhesive production reduces exposure to specialty chemical supplier allocation risk.
For New Entrants and Emerging Players: Pursue pediatric decorative segment white space where character-licensed formats command substantial price premiums in United States pharmacy retail. Target sports medicine channel expansion through direct procurement relationships with marathon and triathlon event organizers. E-pharmacy subscription models offer lowest customer acquisition friction for chronic wound management replenishment.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital procurement consolidation and regulatory barrier escalation favor scaled operators with established FDA documentation capabilities. Acquisition target archetype: mid-tier contract manufacturers with validated alternative terminal sterilization methods post-ethylene oxide facility closures. Signal to watch: NMPA registration pathway acceleration enabling China domestic production scale-up by multinational brand owners.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Adhesive Formulation R&D | MDR compliance deadlines in Europe accelerate premium product portfolio upgrades ahead of REACH substance restrictions. |
| Just-in-Time Delivery Infrastructure | Hospital procurement consolidation demands inventory virtualization to defend vendor margins under multi-year contracts. |
| E-Pharmacy Channel Partnership | Amazon Pharmacy and Walgreens digital platforms capture recurring replenishment orders from Medicare Advantage beneficiaries. |
| China Domestic Manufacturing Scale-Up | NMPA streamlined registration pathways enable import substitution strategies for Asia-Pacific distribution networks. |
| Pediatric Decorative SKU Development | Character-licensed formats with hypoallergenic claims penetrate pharmacy retail through guardian-driven compliance purchasing. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital wound care specialists, GPO contracts managers, pharmacy category buyers, and medical device regulatory affairs leads. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Bottom-up SKU-level volume aggregation and top-down macro demand calibration were triangulated to reconcile segment-level outputs.
Calibration against historical shipment data and disclosed capacity expansions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, material substrate technology, and end-user procurement channel. CAGRs were derived from regression analysis of correlated surgical volume and demographic drivers. Forecast inputs incorporated outpatient procedure displacement rates and chronic wound prevalence projections.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth, adhesive raw material costs, or regulatory harmonization timelines would shift the trajectory. Forecasts reflect documented assumptions regarding sterilization infrastructure transition and REACH compliance deadlines. Quarterly review of hospital procurement contract awards and NMPA registration approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Compression Socks Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
South America Syringe Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Evidence Collection Tubes Market
Medical Supplies
Elbow Splints Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Global Swab Market
Medical Supplies
Japan Hospital Supplies Market