
 Foley Trays Market | 2026-2036
Foley Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Foley Trays Market Insights
EU MDR and FDA 510(k) infection control mandates is restructuring purchasing criteria across acute care networks. Medtronic Plc leverages its integrated urology portfolio to sustain contract visibility with IDNs. B. Braun Melsungen AG anchors European hospital supply chains through localized tray sterilization services. Coloplast Corporation differentiates via silicone-dominant material platforms that compete on biocompatibility metrics.
Foley trays are pre-packaged sterile assemblies containing a Foley catheter, drainage bag, specimen container, and lubricant, typically constructed from medical-grade PVC or silicone with closed-system drainage to minimize CAUTI risk; they serve to standardize catheter insertion protocols across clinical settings. Disposable trays command volume leadership due to single-use sterility requirements, while specialty trays configured for suprapubic or three-way applications capture premium positioning. Silicone material adoption extends fastest in home care channels where extended dwell times reduce trauma incidence.
FDA enforces Class II device controls and CAUTI reduction guidelines that shape tray sterilization validation and labeling claims, while EU MDR imposes enhanced clinical evidence requirements for reusable tray reprocessing systems. The central bank of procurement strategy must monitor evolving EPA waste-stream rules for disposable plastic components and ISO 13485 quality system audits that gate supplier qualification. Stakeholders should track how CMS hospital-acquired condition penalties redirect volume toward closed-system tray designs with integrated antiseptic barriers.
Market Dynamics
FDA's CAUTI reduction mandates are compressing hospital purchasing cycles toward closed-system tray configurations with integrated antiseptic barriers, forcing suppliers to revalidate sterilization protocols and documentation workflows.
Growth Catalysts
- EU MDR clinical evidence requirements:Reusable tray reprocessing systems face heightened documentation standards that favor pre-validated disposable assemblies in acute care networks.
- Silicone material platforms:Extended dwell time applications in home care channels are accelerating biocompatibility-driven procurement decisions.
- Aging surgical volumes:United States hospital networks are expanding specialty tray configurations for complex urological procedures.
Market Restraints
- Medical-grade PVC supply concentration:Feedstock volatility from Asian petrochemical suppliers creates input cost instability for standard tray configurations.
- EPA waste-stream scrutiny:Disposable plastic component disposal faces tightening environmental compliance costs in acute care settings.
- Reusable tray reprocessing complexity:ISO 13485 quality system audits impose supplier qualification barriers that limit vendor pool expansion.
Strategic Opportunities
- Home care channel expansion:Extended catheterization patients in Medicare Advantage networks represent underpenetrated demand for silicone-dominant specialty trays.
- CMS hospital-acquired condition penalties:Financial pressure on inpatient facilities creates procurement tailwinds for closed-system designs with infection barriers.
- Antimicrobial coating convergence:Integration of silver-alloy technologies with standard tray assemblies enables premium positioning in surgical suites.
Industry Challenges
- Sterilization validation timelines:FDA 510(k) pathway requirements for novel tray configurations extend product launch cycles by 12-18 months.
- Legacy EHR integration friction:Closed-system tray data capture requires interoperability investment that strains mid-tier supplier IT resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foley Trays Market |
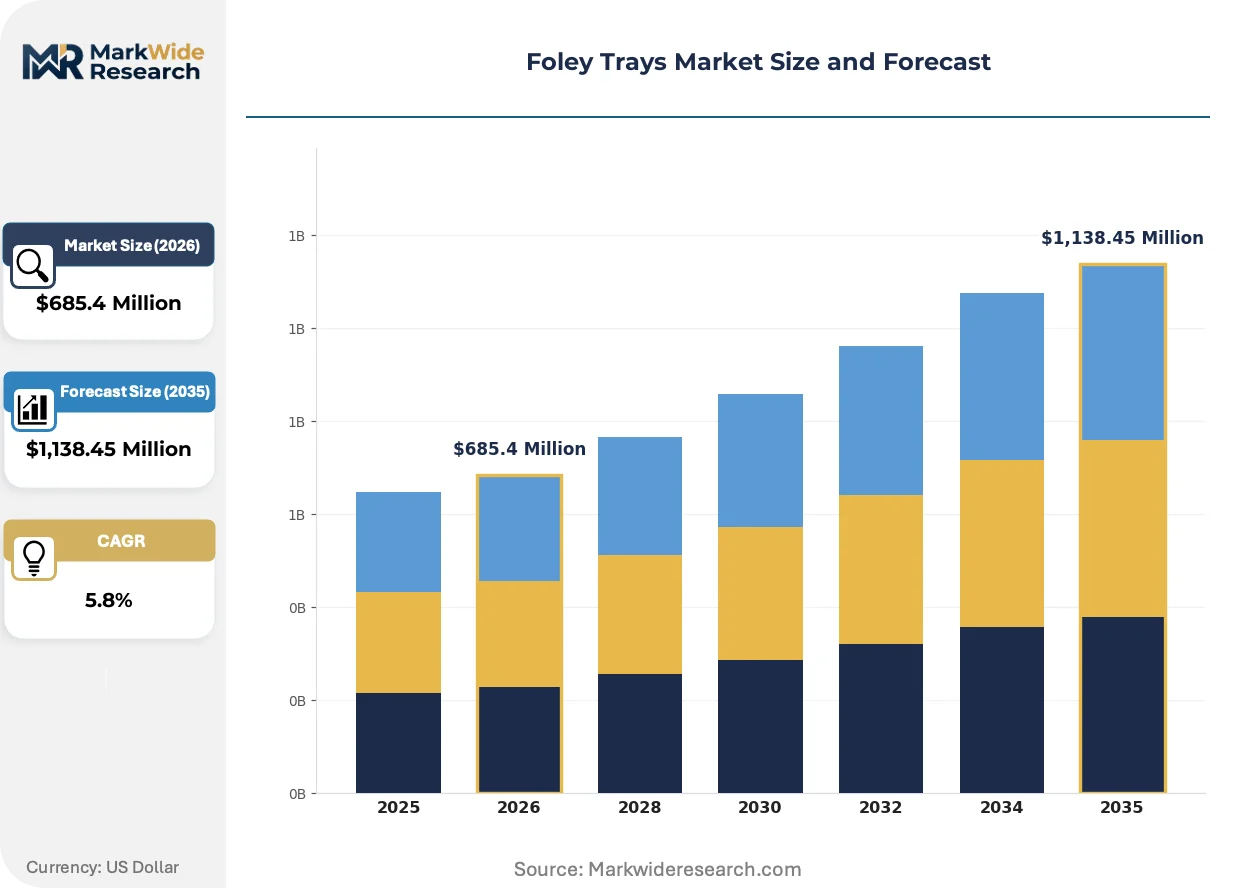
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Trays, Specialty Trays, Disposable Trays, Reusable Trays End User: Hospitals, Clinics, Home Care, Surgical Centers Material: Plastic, Stainless Steel, Silicone, Composite Application: Urological Procedures, Surgical Procedures, Patient Care, Emergency Services |
| Companies Covered | Medtronic Plc, Boston Scientific Corporation, C.R. Bard Inc., B. Braun Melsungen AG, Teleflex Inc., Hollister Inc., Coloplast Corporation, Cardinal Health Inc., Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foley Trays Market Trends and Innovations
Catheter tray design is converging with infection surveillance infrastructure, creating demand for assemblies that integrate with digital health monitoring systems rather than functioning as standalone consumables.
Closed-system drainage technology is modularizing Foley tray architecture by separating the catheter-drainage bag interface into standardized connection modules. Surgical suites at academic medical centers are adopting these configurations fastest. The shift is compressing supplier R&D cycles toward platform-based component development rather than integrated proprietary designs.
EU MDR's enhanced clinical evidence requirements for reusable devices are restructuring European hospital procurement toward single-use tray validation. Suppliers must now submit post-market surveillance data for reprocessing claims. German and French acute care networks are consolidating contracts around pre-validated disposable suppliers to avoid compliance documentation burdens.
Integrated delivery networks are consolidating catheter procurement through centralized distribution agreements that bypass traditional medical-surgical distributors. Hospital systems with 10+ facilities are negotiating direct manufacturer relationships. This pattern is most visible in United States metropolitan markets where IDN market power concentrates purchasing decisions.
Foley Trays Market Segmentation
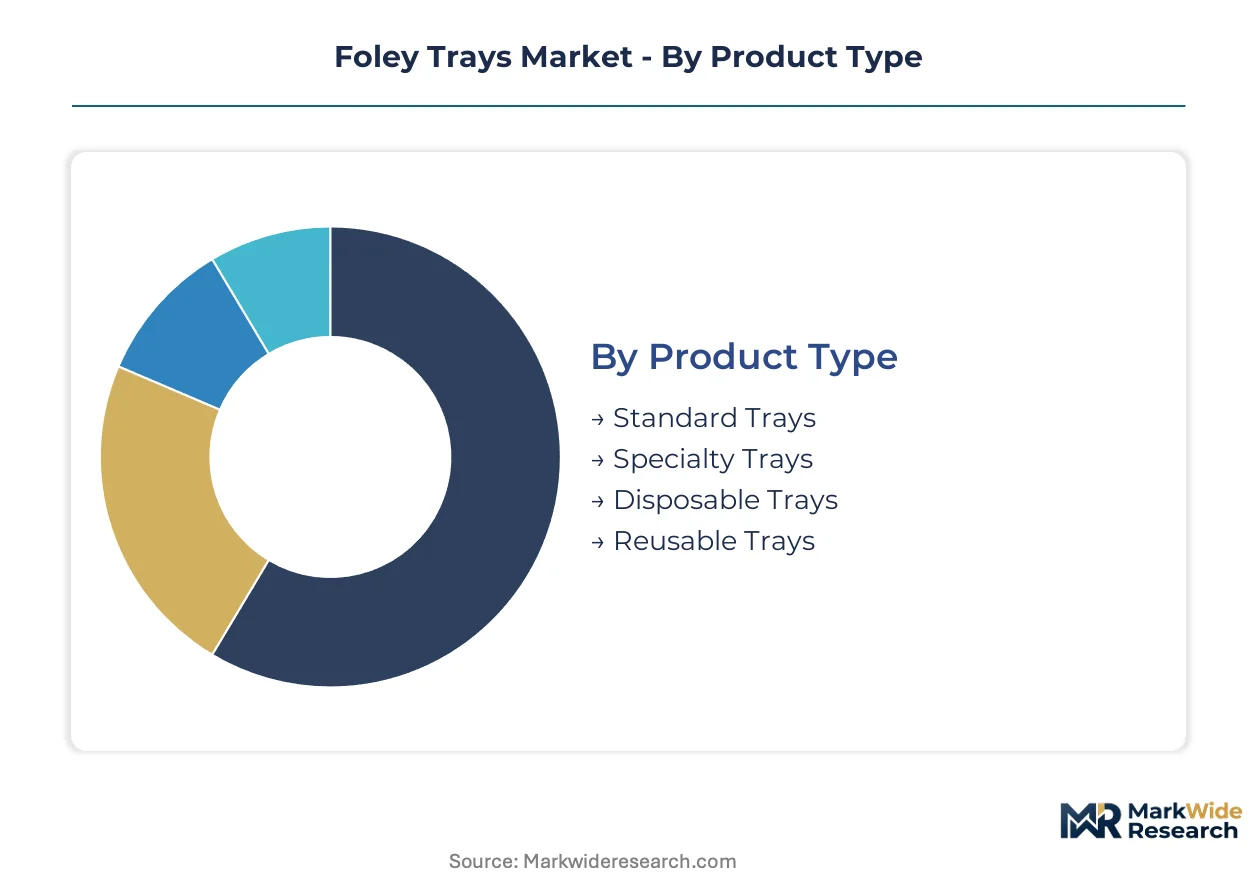
Foley tray procurement decisions fragment across four critical dimensions: product configuration, clinical setting, material platform, and procedural application. Each segmentation axis carries distinct sterilization requirements, reimbursement pathways, and supply chain configurations that determine vendor selection criteria.
Product Type:
Capital deployment intensity varies sharply across product categories, with reusable tray systems demanding the highest upfront sterilization infrastructure investment while disposable configurations shift capital burden to recurring operational expenditure.
- Standard Trays:Pre-packaged assemblies containing Foley catheter, drainage bag, specimen container, and water-soluble lubricant in medical-grade PVC construction. United States hospital networks procure these in highest volumes for routine catheterization protocols under FDA 510(k) Class II device controls.
- Specialty Trays:Configured for suprapubic catheterization, three-way irrigation, or post-TURP applications with integrated antiseptic barriers and closed-system drainage modules. Academic medical centers in the United States are consolidating procurement around these configurations to satisfy CMS hospital-acquired condition penalty avoidance strategies.
- Disposable Trays:Single-use sterile assemblies eliminate reprocessing documentation burdens under EU MDR clinical evidence requirements. German and French acute care networks favor pre-validated disposable suppliers to avoid compliance overhead.
- Reusable Trays:Stainless steel instrument sets requiring ISO 13485-validated sterilization protocols and post-market surveillance documentation. European hospital procurement is retreating from this category due to heightened MDR reprocessing evidence standards.
Most installed capacity flows through Standard Trays. Expansion is steepest in Specialty Trays.
End User:
Customer concentration patterns reveal acute care networks commanding procurement volume leadership while home care channels present the steepest adoption trajectory for silicone-dominant material platforms.
- Hospitals:Inpatient facilities with 100+ beds dominate procurement through integrated delivery network centralized contracts. United States IDNs with 10+ facilities negotiate direct manufacturer relationships, bypassing traditional medical-surgical distributors.
- Clinics:Outpatient urology and primary care settings with lower catheterization volumes favor disposable tray configurations to minimize sterilization infrastructure investment.
- Home Care:Medicare Advantage networks serving extended catheterization patients are accelerating silicone material adoption to reduce trauma incidence during dwell times exceeding 14 days.
- Surgical Centers:Ambulatory facilities concentrate demand for specialty tray configurations supporting same-day urological procedures with rapid turnover requirements.
Procurement volume concentrates in Hospitals. Patient volume is shifting fastest into Home Care.
Material:
Material selection directly determines biocompatibility certification pathways, with silicone platforms commanding premium positioning against commodity PVC alternatives.
- Plastic:Medical-grade PVC remains the dominant feedstock for standard tray configurations, though Asian petrochemical supply concentration creates input cost volatility.
- Stainless Steel:Reusable instrument construction requiring steam sterilization validation and corrosion resistance testing under ISO 17665 standards.
- Silicone:Platinum-cured elastomer platforms with superior tissue compatibility and reduced encrustation rates. United States home care channels are expanding procurement fastest for extended-dwell applications.
- Composite:Hybrid material constructions combining structural polymers with antimicrobial additive integration, typically silver-alloy or chlorhexidine coatings for surgical suite positioning.
Production volume runs heaviest through Plastic. Commercial momentum is building fastest behind Silicone.
Application:
Procedural specificity dictates tray complexity requirements, with surgical applications demanding the most sophisticated closed-system drainage integration.
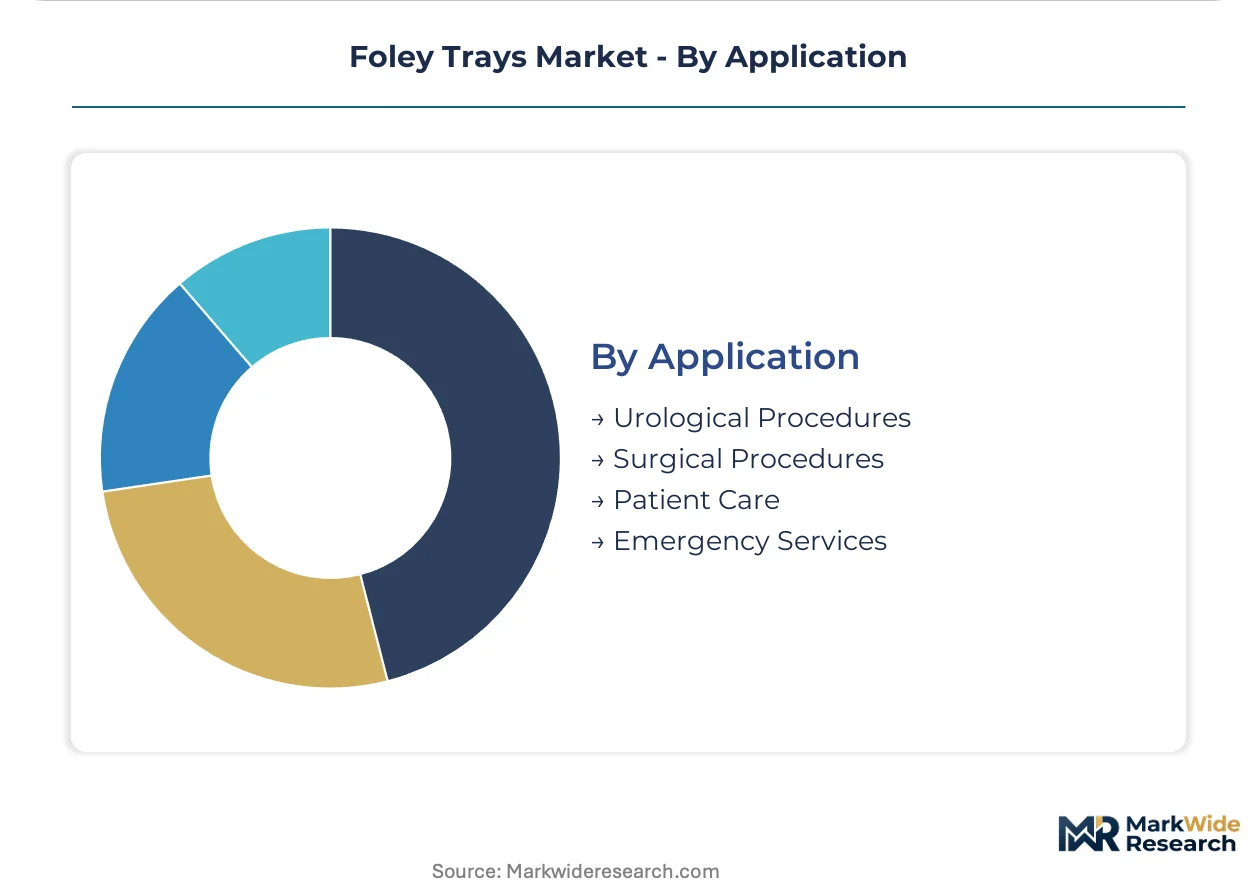
- Urological Procedures:Diagnostic catheterization, post-operative drainage, and bladder irrigation protocols in hospital and surgical center settings.
- Surgical Procedures:Perioperative catheterization in orthopedic, gynecologic, and abdominal surgery requiring sterile insertion technique compliance.
- Patient Care:Long-term indwelling catheter management in skilled nursing and home care environments with infection surveillance integration.
- Emergency Services:Rapid-deployment configurations for trauma and acute urinary retention in emergency department and pre-hospital settings.
Clinical utilization peaks in Urological Procedures. Deployment is broadening fastest across Patient Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled nursing workforce concentrations in the Upper Midwest and specialized urology clusters in the Sun Belt are anchoring demand geography for catheter tray procurement across developed markets.
United States
Aging surgical volumes and Medicare Advantage expansion for home-based catheterization are sustaining procurement growth. FDA 510(k) Class II device controls and CMS hospital-acquired condition penalties are redirecting hospital purchasing toward closed-system tray designs. The Minneapolis-St. Paul corridor concentrates manufacturing capacity for silicone-dominant specialty configurations serving extended-dwell applications.
Germany
Acute care network consolidation and EU MDR implementation timelines are compressing supplier qualification cycles. The national pharmaceutical regulator enforces enhanced clinical evidence requirements for reusable tray reprocessing systems that favor pre-validated disposable assemblies. The Rhine-Ruhr industrial cluster hosts sterilization validation facilities serving centralized procurement contracts across North Rhine-Westphalia hospital systems.
France
Public hospital procurement centralization through regional health agencies is standardizing tray specifications across university hospital networks. ANSM post-market surveillance mandates for reprocessing claims are accelerating retreat from reusable stainless steel configurations. The Lyon-Grenoble medical technology corridor concentrates distribution infrastructure for single-use silicone platforms targeting home care channels.
Japan
Super-aging demographics and long-term care insurance expansion are extending catheterization into community-based settings. PMDA quality system requirements align with ISO 13485 standards that gate supplier entry for foreign manufacturers. The Osaka-Kobe manufacturing belt anchors domestic production of medical-grade PVC feedstock for standard tray configurations serving acute care networks.
United Kingdom
NHS supply chain consolidation through regional procurement hubs is reducing vendor counts for standardized tray configurations. MHRA post-Brexit regulatory alignment with EU MDR documentation standards maintains compliance burdens for reusable device reprocessing. The West Midlands medical device cluster hosts contract sterilization services supporting NHS England centralized distribution agreements.
Foley Trays Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Foley tray market structure. Integrated medical device conglomerates with captive sterilization infrastructure dominate hospital contract negotiations, while specialized urology suppliers capture premium positioning in academic medical center channels. Three strategic archetypes define competitive positioning: diversified conglomerates with cross-category procurement leverage, silicone-focused material specialists, and regional sterilization service integrators. M&A activity concentrates on acquiring validated reprocessing documentation portfolios, while geographic expansion targets Medicare Advantage network direct contracting relationships.
Among diversified medical technology conglomerates, Medtronic Plc and Boston Scientific Corporation exemplify the procurement-leverage archetype that anchors integrated delivery network relationships. B. Braun Melsungen AG occupies a position within the European sterilization service tier, representing localized supply chain integration against disposable-centric competitors. Coloplast Corporation sits within the material-specialist segment, exemplifying biocompatibility-driven positioning for extended-dwell home care applications.
| Leading Market Players |
|---|
| Medtronic Plc |
| Boston Scientific Corporation |
| C.R. Bard Inc. |
| B. Braun Melsungen AG |
| Teleflex Inc. |
| Hollister Inc. |
| Coloplast Corporation |
| Cardinal Health Inc. |
| Cook Medical |
| Others |
Pricing and Supply Chain Analysis
Medical-grade PVC resin from Asian petrochemical corridors feeds through three pricing tiers before reaching United States hospital purchasing committees, with silicone-dominant specialty configurations commanding sustained premiums against commodity standard trays.
Pricing Analysis
Bundled sterilization services versus unbundled tray-only procurement splits the market into contract archetypes. Three-tier pricing structure across premium silicone, standard PVC, and economy configurations tracks certification grade and dwell-time performance. Cost compression in standard PVC tiers is intensifying because Asian feedstock volatility transmits directly into hospital GPO negotiations. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with CMS penalty exposure show lowest.
Supply Chain Analysis
Regional distribution centers in Minneapolis-St. Paul, Rhine-Ruhr, and Osaka-Kobe anchor hub-and-spoke patterns serving hospital networks within 48-hour replenishment windows. Manufacturing concentration rests on China, Germany, and the United States for medical-grade polymers and sterilization infrastructure. Raw material dependencies center on petroleum-derived PVC, platinum-catalyzed silicone elastomers, and antimicrobial silver-alloy coatings. Single-source vulnerability in Asian petrochemical feedstock creates exposure to logistics chokepoints through Shanghai and Busan port complexes. Distribution runs through integrated delivery network centralized contracts that bypass traditional medical-surgical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in Foley trays hinge on silicone material substitution in Medicare Advantage home care channels, where biocompatibility premiums offset input cost volatility.
For Market Incumbents: Deepen backward integration into platinum-cured silicone compounding to capture margin leakage from specialty tray premiums. Anchor hospital system partnerships through closed-system drainage platform standardization that locks out disposable-only competitors. FDA 510(k) sterilization validation documentation serves as the priority defensive moat against mid-tier challengers.
For New Entrants and Emerging Players: Enter via silicone-dominant specialty configurations targeting United States home care channels where extended-dwell applications remain underpenetrated. Home care procurement through Medicare Advantage networks offers the most penetrable entry vector against incumbent hospital-focused portfolios. Direct-to-IDN contracting bypassing GPO intermediaries provides the critical go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR documentation burdens strand reusable tray reprocessing suppliers without disposable validation portfolios. Long-term viability favors asset-light designers with captive silicone material science capabilities over capital-heavy sterilization infrastructure owners. The signal to watch is CMS hospital-acquired condition penalty rate adjustments that redirect procurement volume toward infection-barrier-integrated configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct IDN contracting with 10+ facility networks bypasses distributor markups and secures volume commitments. |
| CE Marking Pathway | EU MDR clinical evidence submission for silicone platforms opens German and French acute care procurement. |
| Software Companion Development | Digital health integration for closed-system drainage monitoring aligns with infection surveillance infrastructure spending. |
| Reimbursement Strategy | Medicare Advantage home care coding optimization captures extended-dwell catheterization episode payments. |
| FDA Submission | 510(k) clearance for antimicrobial-coated tray configurations enables premium positioning in surgical suites. |
Research Methodology
Direct dialogue with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and home care supply coordinators grounded qualitative findings in procurement workflow realities. Secondary validation drew from FDA 510(k) device listings, CMS hospital-acquired condition penalty datasets, EU MDR technical documentation repositories, and hospital procurement database extracts. Bottom-up tray shipment aggregation and top-down acute care expenditure modeling were triangulated against silicone raw material trade flow data.
Bottom-up modeling tracked unit economics across standard, specialty, disposable, and reusable tray configurations over the projection horizon. Segmentation dimensions included product type, end-user facility class, material platform, and procedural application. CAGRs were derived from weighted average of historical volume trajectories and forward-looking regulatory impact coefficients. Forecast inputs incorporated FDA CAUTI reduction mandate compliance timelines and EU MDR reusable device evidence requirement phase-in patterns.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time home care channel shipment data introduce uncertainty bands around Medicare Advantage segment projections. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and silicone feedstock price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Nipple Shield Market
Medical Supplies
Cryogenic Vials Market