
 Polypropylene Film Market | 2026-2036
Polypropylene Film Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Film Market Analytics
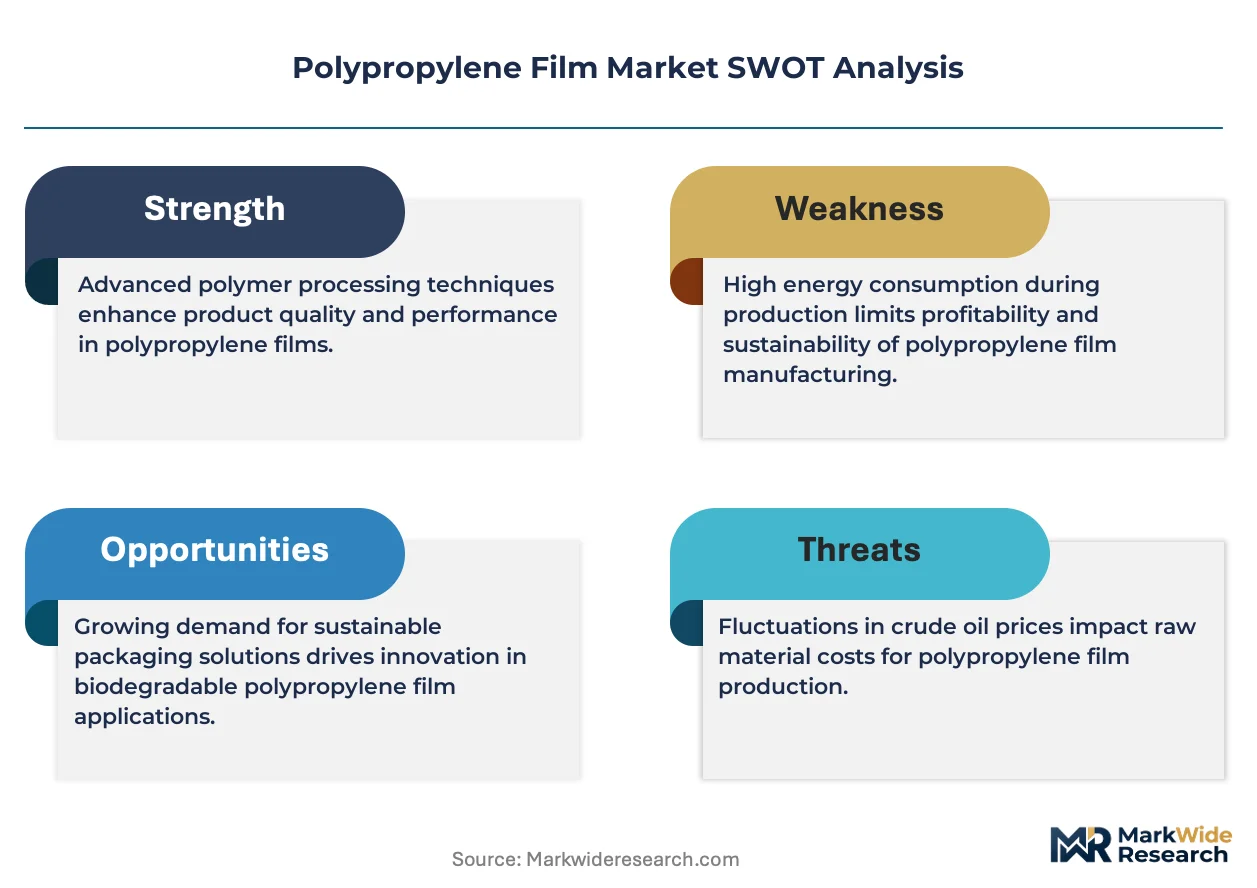
EU REACH is decoupling European supply chains from legacy plasticizer chemistries, forcing reformulation investments that smaller converters cannot absorb. Jindal Poly Films leverages captive resin integration to offset raw-material volatility. Toray Industries anchors premium optical-grade BOPP supply for display and capacitor films. Profol GmbH specializes in thin-gauge coextruded structures for medical sterilization pouches.
Polypropylene film comprises oriented and cast variants manufactured from isotactic polypropylene resin, typically extruded through tenter-frame or chill-roll processes to achieve thicknesses from 8 to 80 micrometers with controlled crystallinity for barrier, clarity, or heat-seal performance. BOPP dominates volume through its biaxial orientation yielding high tensile strength and moisture barrier for snack and confectionery wrapping. CPP commands faster expansion in retort and lidding applications where heat-seal breadth and puncture resistance justify unit-premium positioning. Medical-grade films within the thickness segment occupy concentrated margin pools as lot-traceability and biocompatibility certification create qualification barriers.
FDA food-contact notification rules and EU F-Gas Regulation constrain blowing-agent choices in foamed polypropylene structures, redirecting R&D toward physical foaming with nitrogen. China's SAMR enforces GB standards for food-packaging migration limits that exporters must certify against for market access. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
REACH compliance in Europe and FDA food-contact rule evolution are forcing converters to abandon legacy plasticizer chemistries, triggering a wave of reformulation investments that smaller players cannot finance. This regulatory decoupling is restructuring competitive tiers across flexible packaging supply chains.
Growth Catalysts
- Retort packaging expansion:CPP films capture accelerating demand from ready-meal and pet-food brands requiring puncture-resistant, high-temperature sterilization performance.
- EU F-Gas Regulation:Physical foaming with nitrogen gains commercial traction as blowing-agent constraints redirect R&D away from chemical alternatives in foamed structures.
- India:FSSAI enforcement of migration-limit standards drives domestic converters to upgrade extrusion lines for export-certification readiness.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and refinery output swings compress margin predictability for non-integrated film producers.
- China supply concentration:Capacity expansion by state-backed petrochemical complexes tilts global pricing power toward Asia-Pacific resin controllers.
- Technical thickness floor:Below 8-micrometer gauge, pinhole defects and web-handling failures prevent reliable high-speed converting without capital-intensive line upgrades.
Strategic Opportunities
- Medical sterilization pouches:Lot-traceability and biocompatibility certification create margin pools that general packaging converters cannot access without qualification investment.
- Capacitor-grade BOPP:Dielectric film specifications for electric-vehicle power electronics outpace current optical-grade supply from incumbent producers.
- China SAMR GB standards:Exporters certifying against migration-limit protocols capture shelf-space in domestic retail channels previously closed to uncertified imports.
Industry Challenges
- Multi-jurisdiction compliance synchronization:Divergent FDA notification timelines, REACH SVHC updates, and SAMR enforcement waves strain quality-assurance staffing.
- Coextrusion die refurbishment cycles:Layer-thickness uniformity requirements for barrier films demand capital outlays every 4-6 years that mid-tier converters defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Film Market |
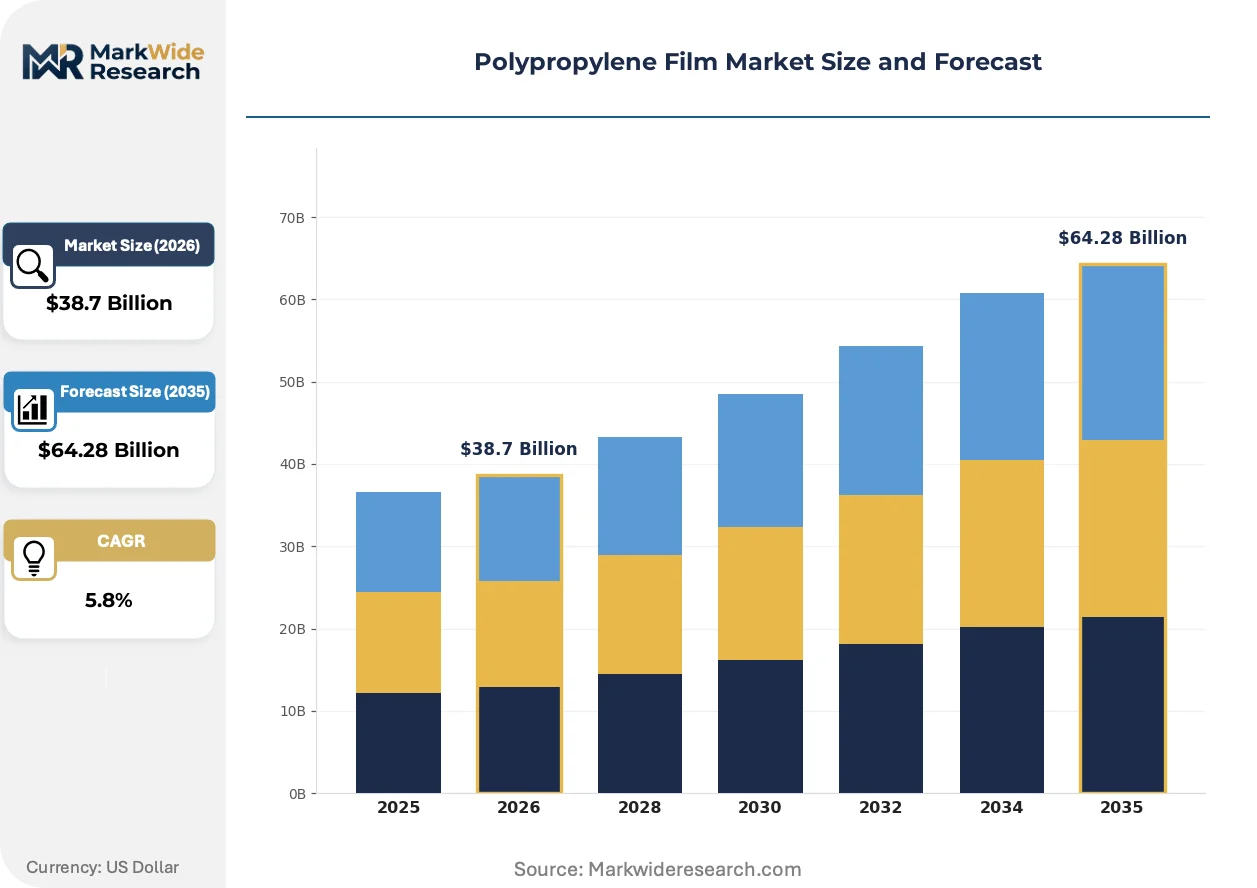
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BOPP, CPP, Cast, Others Application: Packaging, Labels, Insulation, Medical End User: Food & Beverage, Consumer Goods, Healthcare, Electronics Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | Jindal Poly Films, Taghleef Industries, Cosmo Films, UFlex, Toray Industries, Polyplex Corporation, Oben Holding Group, Innovia Films, Profol GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Film Market Evolving Landscape
Extrusion and orientation technologies are fragmenting into application-specific configurations, while regulatory chemistry constraints and downstream procurement consolidation reshape how film specifications reach end-users.
Barrier coextrusion with EVOH and polyamide tie-layers is modularizing formerly monolithic BOPP structures into stackable functional components. Snack and confectionery packagers in Germany and the United States adopt these architectures to tune oxygen transmission without full line replacement. This modularizing capability compresses product-development cycles from 18 months to under 6 for regional format launches.
EU F-Gas Regulation bans hydrofluorocarbon blowing agents in foamed polypropylene by 2030, forcing converters toward nitrogen-based physical foaming or alternative core materials. Industrial packaging producers in France and Italy face stranded equipment investments as chemical foaming lines lose compliance eligibility. The directive accelerates capital rotation toward extrusion systems with supercritical gas injection.
Brand-owner consolidation in food retail concentrates procurement leverage against film suppliers, compressing contract durations and demanding lot-level traceability. European and North American supermarket chains now mandate blockchain-verified resin origin documentation. This specification escalation excludes smaller converters lacking ERP integration with upstream polymer certification systems.
Polypropylene Film Market Segmentation
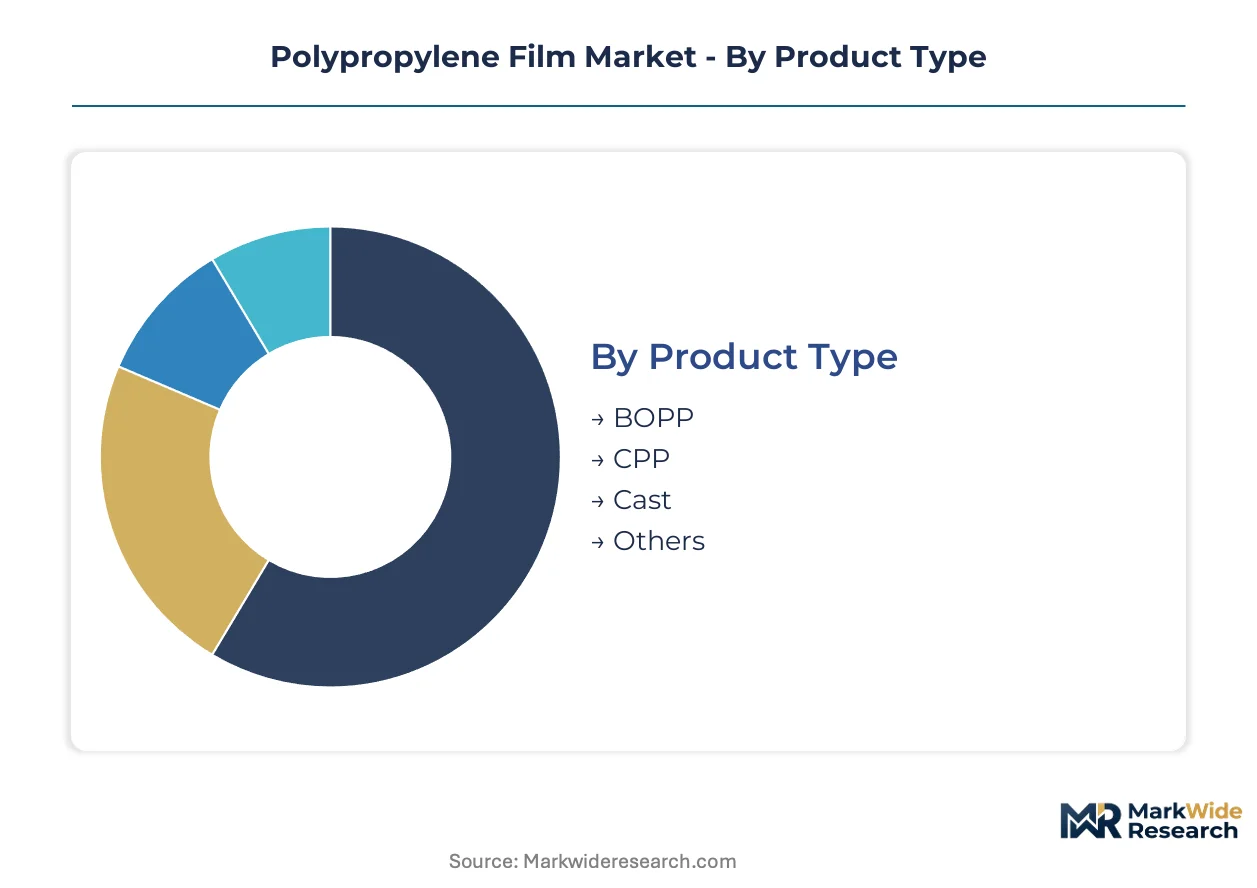
Polypropylene film specifications diverge sharply between commodity packaging volumes and certified medical or capacitor-grade premiums. Converters configure extrusion lines for either throughput efficiency or qualification-intensive niche positioning, with limited overlap in equipment and resin sourcing.
Product Type:
BOPP commands volume leadership through biaxial orientation lines running at scale, while CPP captures premium positioning in heat-seal performance tiers.
- BOPP:Biaxial orientation yields high tensile strength and moisture barrier through tenter-frame stretching. Demand concentrates in snack and confectionery wrapping across Germany and the United States, where brand-owners specify clarity and dead-fold properties for high-speed form-fill-seal lines.
- CPP:Cast film production through chill-roll extrusion delivers superior heat-seal breadth and puncture resistance. Retort pouch converters in Japan and ready-meal packagers in France drive specification escalation for sterilization-grade gauges.
- Cast:Non-oriented structures serve general-purpose lamination and adhesive tape substrates.
- Others:Metallized and coextruded variants occupy optical and capacitor dielectric niches.
Mature deployment sits with BOPP. Newer deployment is concentrated in CPP.
Application:
Packaging absorbs resin volume at commodity margins, while medical and insulation applications extract value through certification barriers and specification precision.
- Packaging:Flexible substrates for food, consumer goods, and industrial products dominate tonnage. Chinese and Indian converters expand capacity for export-certified flexible packaging substrates serving European retail channels.
- Labels:Pressure-sensitive adhesive facestocks and in-mold labels require controlled shrinkage and printability. German label converters specify matte and gloss grades for beverage and cosmetic applications.
- Insulation:Foamed and metallized structures serve building and cable applications.
- Medical:Sterilization pouches and device packaging demand lot-traceability and biocompatibility certification per ISO 10993 and US FDA requirements.
Volume concentration rests with packaging. Steepest expansion trajectory belongs to medical.
End User:
Food & Beverage procurement sets baseline specifications that other sectors modify for performance or compliance premiums.
- Food & Beverage:Migration-limit compliance under EU REACH and China's SAMR GB standards shapes resin selection and additive packages. Indian exporters upgrade extrusion lines to meet FSSAI enforcement for migration certification.
- Consumer Goods:Personal care and household product packaging emphasizes printability and stiffness for shelf presence.
- Healthcare:Sterile barrier systems and pharmaceutical blister packs require validated sealing windows and particulate control.
- Electronics:Capacitor-grade dielectric films and display optical films demand thickness uniformity below 3% variation.
Procurement scale peaks with Food & Beverage. Gaining share fastest is Electronics.
Thickness:
Thin-gauge production pushes against technical floors where pinhole defects multiply, while thick films serve structural and insulation roles.
- Thin:8-20 micrometer gauges serve overwrap and label applications. Web-handling failures accelerate below 8 micrometers without capital-intensive line upgrades.
- Medium:20-40 micrometers balances barrier and convertibility for general flexible packaging.
- Thick:40-80 micrometers provides structural rigidity for thermoformed trays and industrial bags.
- Extra Thick:Above 80 micrometers serves foam-core structures and heavy-duty applications.
Capacity deployment clusters at Medium. Investment flow targets Thin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's coastal provinces and India's western industrial corridors concentrate polypropylene film extrusion capacity, attracting resin suppliers and converters through tax holidays and duty exemptions on imported equipment.
China
Ready-meal and snack packaging brands in Shanghai and Guangzhou drive specification escalation for high-barrier CPP grades. SAMR enforces GB standards for food-contact migration limits that exporters must certify against for domestic retail access. The Yangtze River Delta hosts state-backed petrochemical complexes expanding BOPP tenter-frame capacity for capacitor-grade dielectric films.
India
FSSAI enforcement of migration-limit standards pushes domestic converters toward export-certification readiness. The western states of Maharashtra and Gujarat anchor flexible packaging substrate production, with Surat and Ahmedabad clusters upgrading chill-roll extrusion lines for retort pouch specifications.
Germany
EU REACH compliance deadlines force reformulation away from legacy plasticizer chemistries, favoring integrated producers with captive resin supply. The Rhine-Ruhr industrial region concentrates barrier coextrusion expertise, while Bavarian converters specialize in medical sterilization pouch films requiring ISO 10993 biocompatibility certification.
United States
FDA food-contact notification rules constrain additive packages for flexible packaging serving retail food brands. The Gulf Coast petrochemical corridor supplies propylene feedstock to film extruders in Texas and Louisiana, while Midwest converters near Chicago serve snack and confectionery packagers with dead-fold BOPP grades.
Japan
Retort pouch demand from convenience-store ready-meal chains drives premium CPP specifications for puncture-resistant sterilization performance. METI industrial standards guide capacitor-grade BOPP thickness uniformity below 3% variation for electric-vehicle power electronics. The Kansai region around Osaka anchors optical-grade film production for display applications.
Polypropylene Film Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered competitive strata. Market structure consolidates around integrated resin-to-film producers with captive propylene supply, while mid-tier converters face margin compression from feedstock volatility and qualification barriers in medical and capacitor segments. Three archetypes dominate: petrochemical-backward-integrated giants, regional flexible packaging substrate specialists, and niche medical-grade certification holders. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with converters securing long-term resin offtake agreements to defend margin predictability.
Among Asia-Pacific integrated producers, Jindal Poly Films exemplifies the petrochemical-backward archetype through captive resin operations. Toray Industries anchors premium optical and capacitor-grade positioning from Japanese manufacturing bases. Profol GmbH occupies the European specialist tier as a German GmbH-structured converter focused on thin-gauge medical sterilization applications.
| Leading Market Players |
|---|
| Jindal Poly Films |
| Taghleef Industries |
| Cosmo Films |
| UFlex |
| Toray Industries |
| Polyplex Corporation |
| Oben Holding Group |
| Innovia Films |
| Profol GmbH |
| Others |
Value Network & Pricing Analysis
Retort pouch converters in France and Japan demanding sterilization-grade CPP specifications are forcing extrusion lines toward qualification-intensive gauges that compress spot-market availability and elevate contract premiums for certified supply. This specification escalation tightens pricing discipline across flexible packaging tiers as uncertified volume loses shelf access.
Pricing Analysis
Short lead-time premiums dominate transactional pricing as snack packagers in Germany and the United States pay 15-25% markups for dead-fold BOPP grades delivered within four weeks versus standard eight-week contract windows. Pricing stratifies across medical certification tiers, capacitor-grade dielectric specifications, and commodity packaging volumes. Cost compression in standard BOPP is intensifying because Chinese state-backed petrochemical complexes are expanding tenter-frame capacity faster than brand-owner procurement consolidation can absorb. Food and beverage packagers exhibit highest price sensitivity, while medical sterilization pouch buyers accept premiums for lot-traceability and ISO 10993 biocompatibility certification.
Supply Chain Analysis
Container freight rates from Shanghai to Rotterdam and intra-Asia routes from Busan to Singapore directly feed into landed cost calculations for European and Southeast Asian converters sourcing resin and equipment. Supply concentrates in China, India, and Germany as state-backed petrochemical complexes, western industrial corridor clusters, and Rhine-Ruhr barrier coextrusion expertise anchor global capacity. Propylene feedstock draws from naphtha-cracking economics and refinery output swings, with additive packages constrained by REACH SVHC updates and FDA food-contact notification timelines. Single-source vulnerability sits with Asia-Pacific resin controllers tilting global pricing power. Distribution runs through converter-direct contracts with long-term offtake agreements defending margin predictability against spot volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified medical-grade and capacitor-grade capacity is structurally constrained against accelerating specification demand, propping pricing power for certified producers across the analysis window.
For Market Incumbents: Anticipate regulatory divergence between EU REACH SVHC updates, FDA notification timelines, and China SAMR GB enforcement waves by embedding multi-jurisdiction compliance staffing into quality-assurance functions. Defend position by securing captive propylene supply through backward integration or long-term resin offtake agreements with Gulf Coast and Asia-Pacific petrochemical producers, while accelerating coextrusion die refurbishment cycles to maintain layer-thickness uniformity for barrier film premiums. For New Entrants and Emerging Players: Regional flexible packaging substrate specialists in India's Maharashtra and Gujarat clusters represent the most penetrable white-space target, as FSSAI enforcement drives domestic converters toward export-certification readiness with limited indigenous qualification expertise. Medical sterilization pouch films for European healthcare procurement offer second-entry positioning given ISO 10993 biocompatibility barriers that general packaging converters defer. Partner with established resin distributors possessing ERP integration with upstream polymer certification systems to bypass blockchain-verified origin documentation mandates from supermarket chains. For Investors and Strategic Acquirers: Re-rating potential sits with niche medical-grade certification holders given lot-traceability mandates from European and North American hospital procurement consolidating sterile barrier supply. Long-term viability through the projection horizon favors converters with demonstrated biocompatibility qualification and capacitor-grade dielectric thickness uniformity below 3% variation. Watch for inflection where electric-vehicle power electronics demand outpaces current optical-grade BOPP supply from incumbent producers, signaling margin expansion for qualified entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Captive resin production insulates margin predictability against naphtha-cracking volatility for non-integrated film producers. |
| Medical-Grade Certification Investment | ISO 10993 biocompatibility qualification opens sterilization pouch margin pools inaccessible to general packaging converters. |
| Capacitor-Grade Dielectric Capacity Addition | Thickness uniformity below 3% variation addresses electric-vehicle power electronics demand outpacing optical-grade supply. |
| Multi-Jurisdiction Compliance Synchronization | Coordinated FDA, REACH, and SAMR quality-assurance staffing prevents stranded inventory in cross-border supply chains. |
| Long-Term Resin Offtake Agreements | Contracted propylene supply from Gulf Coast and Asia-Pacific petrochemical producers defends pricing power against spot volatility. |
Research Methodology
Independent corroboration across extrusion line operators, resin procurement leads at integrated producers, downstream flexible packaging converters, and medical device packaging engineers underwrites the qualitative findings in this study. Primary interviews with plant managers, technical R&D directors, and distribution channel partners combined with secondary validation from customs and trade data, SEC 10-K filings, and industry association reports. Bottom-up capacity assessments and top-down demand modeling triangulate volume and value estimates.
Rate-of-change decomposition across the analysis window isolates volume growth from price/mix effects in BOPP, CPP, and medical-grade film segments. The forecast framework models product type, application, end user, and thickness tier dimensions alongside regional production hub clustering. CAGRs derive from extrusion line deployment schedules, brand-owner procurement consolidation patterns, and regulatory compliance investment cycles. Key inputs include tenter-frame and chill-roll capacity expansion announcements, REACH SVHC update timelines, and FSSAI enforcement intensity indicators.
Caveats apply where propylene feedstock volatility, tariff exposure on Chinese equipment imports, or accelerated EU F-Gas Regulation enforcement could materially shift the outlook. Forecasts reflect assumptions about specification escalation trajectories and qualification barrier persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
PVC Film for Medical Market
Poly film
Soft Touch Lamination Film Market
Poly film
Metallized Film Market
Poly film
North America Plastic Film Packaging Market
Poly film
Poly Tubing Market
Poly film
Polyimide Films and Tapes Market
Poly film
Colourless Polyimide Films Market
Poly film
Vietnam Plastic Packaging Films Market
Poly film
Thermoforming Films Market
Poly film
Light Reflective Film Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Global Specialty Films Polymer Market
Poly film
Laminated Packaging Films Market
Poly film
Twist Wrap Film Market
Poly film
EVOH Encapsulation Film Market
Poly film
Cleanroom Film and Bags Market