
 Centrifugal Pump Market | 2026-2036
Centrifugal Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifugal Pump Market Intelligence
Buyer concentration in municipal water utilities is expanding as regional authorities merge procurement budgets across multiple jurisdictions. Grundfos Holding A/S leverages its digital pump portfolio to secure long-term service contracts with these consolidated buyers. Xylem Inc. anchors its position through advanced monitoring systems that reduce lifecycle operating costs for large-scale water infrastructure operators.
A centrifugal pump converts rotational kinetic energy into hydrodynamic energy to move fluids through a pressure differential, typically operating at speeds from 1,750 to 3,600 RPM with impeller diameters determining flow capacity and head pressure. Single-stage configurations dominate volume sales in agriculture irrigation and light commercial applications where moderate pressure requirements prevail, while multi-stage designs command premium positioning in oil extraction and high-pressure chemical processing where sequential impeller arrangements generate substantially greater discharge pressures. Sealless magnetic drive technology is displacing conventional sealed designs in chemical processing as leak-proof containment becomes mandatory for hazardous fluid handling.
The US Department of Energy enforces pump efficiency standards under the Energy Policy and Conservation Act, while the EU Ecodesign Directive mandates minimum efficiency index thresholds for clean water pumps sold across member states. China's MIIT implements GB energy efficiency grades that restrict market access for non-compliant equipment in industrial procurement. Stakeholders must monitor evolving efficiency benchmarks and carbon border adjustments that will reshape supplier qualification criteria and retrofit investment priorities.
Market Dynamics
Stringent efficiency mandates from regulators across multiple jurisdictions are forcing manufacturers to redesign core hydraulic architectures and abandon legacy low-efficiency product lines, compressing margins while accelerating R&D cycles.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency index thresholds for clean water pumps are phasing out substandard equipment across member states, creating replacement demand in municipal water infrastructure.
- Water treatment utilities:Consolidated procurement by regional authorities is scaling orders for high-efficiency multi-stage units in desalination and wastewater reclamation facilities.
- Sealless magnetic drive technology:Leak-proof containment capabilities are becoming mandatory specifications in chemical processing, displacing conventional sealed designs in hazardous fluid applications.
Market Restraints
- Raw material volatility:Stainless steel and rare earth magnet price swings compress margin predictability for manufacturers serving price-sensitive agricultural irrigation segments.
- Supply concentration:Permanent magnet production clusters in China create vulnerability for magnetic drive pump assemblers dependent on neodymium supply chains.
- Technical ceiling:Cavitation limits at high suction lift conditions constrain single-stage centrifugal pump applicability in deep-well extraction scenarios.
Strategic Opportunities
- India industrial corridor expansion:Dedicated freight corridors and smart city infrastructure are generating demand for intelligent pumping systems with integrated condition monitoring.
- Carbon border adjustment mechanisms:EU CBAM implementation is creating competitive advantage for manufacturers with verified lifecycle carbon footprints in pump production.
- Digital twin convergence:Physics-based simulation platforms combined with IoT sensor networks are enabling predictive maintenance service models in oil and gas downstream operations.
Industry Challenges
- Computational fluid dynamics expertise:Scarcity of simulation engineers capable of optimizing impeller geometries for efficiency compliance is extending product development timelines.
- Legacy system integration:Retrofitting variable frequency drives into existing fixed-speed pump installations requires custom control architecture engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifugal Pump Market |
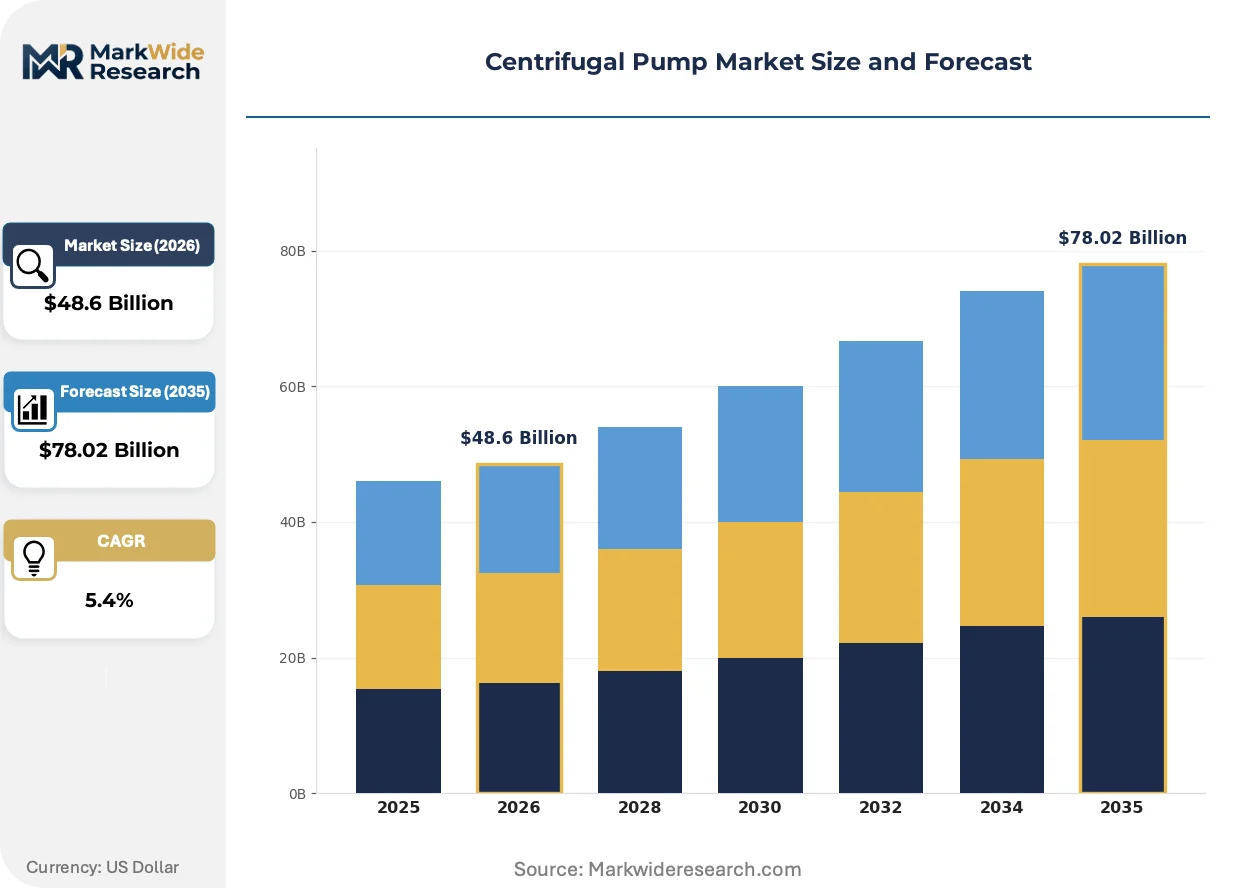
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $78.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage, Multi-Stage, Vertical, Horizontal, Magnetic Drive Technology: API, Magnetic Coupling, Sealless, Regenerative, End Suction Application: Water Treatment, Oil Extraction, Chemical Processing, Agriculture Irrigation, Fire Protection End User: Municipalities, Refineries, Chemical Factories, Farming Cooperatives, Fire Departments |
| Companies Covered | KSB SE & Co. KGaA, ITT Inc., Grundfos Holding A/S, Wilo SE, Ebara Corporation, Flowserve Corporation, Sulzer Ltd., Weir Group PLC, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifugal Pump Market Strategic Shifts & Innovations
Digitalization of pump assets is redefing value capture mechanisms, shifting revenue from hardware transactions toward performance-guaranteed service arrangements anchored by real-time operational data.
Variable frequency drive technology is integrating with advanced motor control algorithms to enable demand-responsive flow modulation. Municipal water utilities in Germany and Australia are deploying these systems to reduce energy consumption during off-peak distribution periods. The technology is integrating pump operation with grid signaling protocols, compressing payback periods for efficiency retrofits.
The EU Ecodesign Directive is tightening enforcement mechanisms for pump efficiency verification through market surveillance protocols. Non-compliant equipment faces mandatory withdrawal from member state markets, reshaping supplier qualification criteria for public procurement frameworks. Industrial process operators in chemical manufacturing are responding by pre-qualifying only IE4-premium efficiency motors for new installations.
Lifecycle cost contracting is displacing capital expenditure-based procurement in large-scale water infrastructure. Municipal authorities in China and India are unbundling equipment purchase from 10-year service agreements, transferring operational risk to OEM service providers. This pattern is most visible in desalination projects where energy guarantees dominate vendor selection criteria.
Centrifugal Pump Market Segmentation
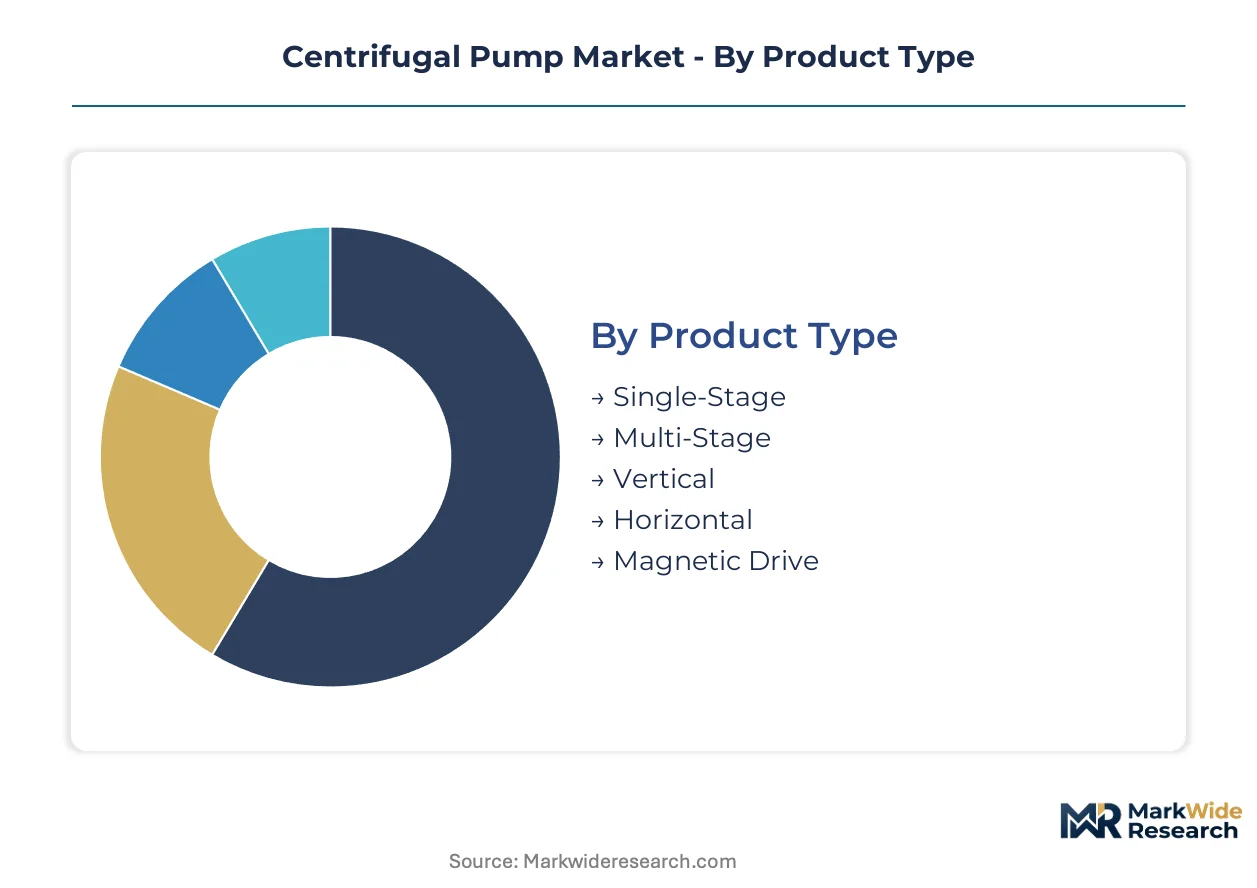
Pump specification varies sharply across end-use contexts, with pressure requirements, fluid corrosivity, and duty cycles dictating architectural choices. Procurement budgets in municipal water infrastructure diverge fundamentally from chemical processing specifications, creating distinct competitive arenas within the same product category.
Product Type:
Buyers in this category differentiate primarily by pressure head requirements and installation footprint constraints.
- Single-Stage:One impeller generates moderate discharge pressure up to 150 meters head. Agricultural irrigation districts in India and Australia specify these units for surface water distribution where suction lift remains shallow and capital budgets constrain upfront investment.
- Multi-Stage:Sequential impeller arrangements stack pressure contributions to achieve heads exceeding 800 meters. Oil extraction operators in the Permian Basin and North Sea deploy these configurations for reservoir pressure maintenance and produced water reinjection.
- Vertical:Motor-mounted-above designs minimize floor space in compact pump stations. Urban water utilities in Singapore and Tokyo specify vertical configurations for submerged intake applications.
- Horizontal:Split-case architectures simplify maintenance access for large-flow applications. Cooling water circuits in thermal power plants across China and Germany favor horizontal split-case units.
- Magnetic Drive:Sealless containment eliminates shaft penetration through the pressure boundary. Chemical processing facilities handling chlorinated solvents and acids in the US Gulf Coast and Antwerp-Rotterdam cluster mandate magnetic drive specifications.
Single-stage units lead volumes today; magnetic drive configurations are gaining share fastest.
Technology:
Specification engineers select architectures based on API compliance requirements and hazardous area classifications.
- API:Heavy-duty designs meeting American Petroleum Institute standards for refinery and upstream service. Operators in the Middle East and US shale plays require API 610 compliance for hydrocarbon transfer and injection duties.
- Magnetic Coupling:Synchronous torque transmission through containment shells eliminates mechanical seals. Pharmaceutical manufacturers in Switzerland and Ireland specify magnetic coupling for sterile process integrity.
- Sealless:Canned motor and magnetic drive variants eliminate emission pathways. The EU Ecodesign Directive and EPA leak detection regulations are accelerating sealless adoption in volatile organic compound service.
- Regenerative:Peripheral impeller designs generate high heads at low flow rates. Boiler feed applications in industrial steam systems specify regenerative turbines for pressure ratios exceeding centrifugal limits.
- End Suction:Single-inlet volute designs dominate general industrial service. Water treatment plants in Brazil and South Africa specify end-suction units for raw water intake and clarified water transfer.
End suction architectures dominate installed base; sealless technologies are climbing the fastest.
Application:
Fluid characteristics and regulatory exposure determine pump selection across use cases.
- Water Treatment:Clean water and wastewater handling with efficiency mandates driving specification. Desalination plants in Saudi Arabia and Israel specify energy-recovery turbine integration with high-pressure feed pumps.
- Oil Extraction:Multiphase flow handling and artificial lift applications. Enhanced oil recovery projects in Canada and Kazakhstan require corrosion-resistant alloys for sour service conditions.
- Chemical Processing:Aggressive fluid containment with zero-leak tolerance. Chlor-alkali producers in Louisiana and Germany specify nickel alloys and fluoropolymer linings for brine and chlorine duty.
- Agriculture Irrigation:Seasonal operation with price-sensitive procurement. Center-pivot systems in the US Great Plains and Australian Murray-Darling basin favor dry-pit submersible configurations.
- Fire Protection:Standby reliability with UL/FM listing requirements. High-rise developments in Dubai and Mumbai specify vertical turbine fire pumps for sprinkler system pressure maintenance.
Water treatment commands the largest installed base; oil extraction applications are expanding most quickly.
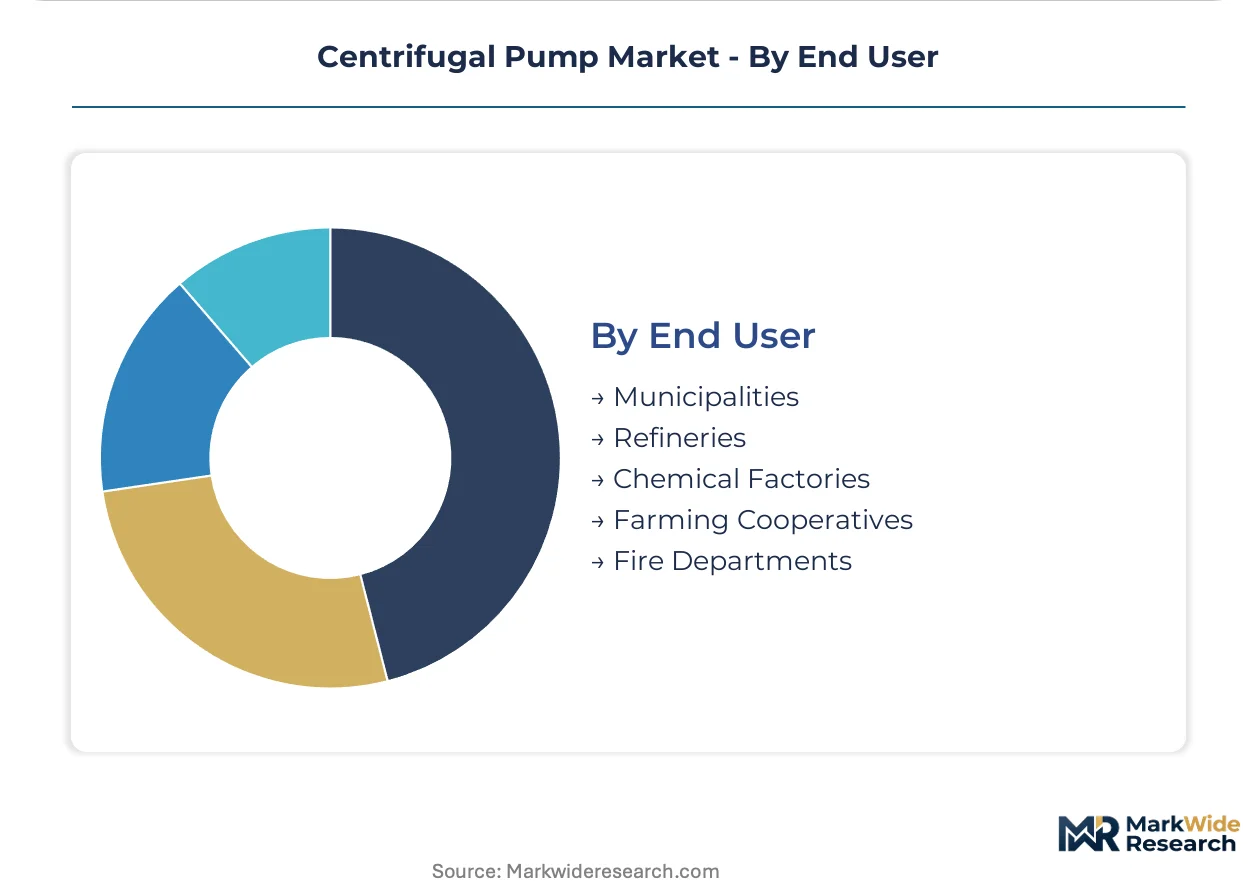
End User:
Procurement sophistication and lifecycle cost horizons separate buyer segments.
- Municipalities:Consolidated regional authorities with 20-year asset planning horizons. German and Australian water utilities are unbundling equipment purchase from long-term energy performance contracts.
- Refineries:Reliability-centered maintenance with API specification rigor. Complexes along the US Gulf Coast and in Rotterdam are retrofitting variable frequency drives to existing pump populations.
- Chemical Factories:Process safety management with sealless technology preferences. Specialty chemical producers in Switzerland and Japan specify redundant pump configurations for critical batch operations.
- Farming Cooperatives:Capital-constrained buyers prioritizing first cost over efficiency. Irrigation districts in India and Brazil are aggregating demand through regional procurement pools.
- Fire Departments:Code-compliance procurement with standby reliability emphasis. Urban fire protection authorities in Singapore and London specify diesel-driven backup configurations for grid-independent operation.
Municipalities lead aggregate demand; chemical factories are shifting specification fastest toward premium efficiency tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in fluid dynamics and precision manufacturing anchor centrifugal pump demand across distinct industrial geographies. Regional procurement patterns diverge sharply between efficiency-mandated replacement cycles and greenfield infrastructure expansion.
China
MIIT enforces GB energy efficiency grades that restrict market access for non-compliant industrial equipment. Provincial procurement pools in Jiangsu and Zhejiang aggregate demand for desalination and wastewater reclamation pumps. The Yangtze River Delta hosts dense clusters of pump assemblers serving chemical processing and power generation sectors.
Germany
The EU Ecodesign Directive mandates minimum efficiency index thresholds that phase out substandard clean water pumps across member states. Municipal utilities in North Rhine-Westphalia and Bavaria unbundle equipment purchase from decade-long energy performance contracts. Stuttgart and Frankfurt industrial corridors specify IE4-premium efficiency motors for new process installations.
United States
The Department of Energy enforces pump efficiency standards under the Energy Policy and Conservation Act. EPA leak detection regulations accelerate sealless adoption in volatile organic compound service across Gulf Coast chemical clusters. Permian Basin operators deploy multi-stage configurations for reservoir pressure maintenance and produced water reinjection.
India
Dedicated freight corridors and smart city infrastructure generate demand for intelligent pumping systems with integrated condition monitoring. BIS certification requirements tighten quality benchmarks for agricultural irrigation equipment entering procurement pools. Gujarat and Maharashtra industrial zones specify variable frequency drive integration for municipal water distribution retrofits.
Australia
MEPS standards establish minimum efficiency requirements that filter substandard equipment from municipal procurement frameworks. Murray-Darling basin irrigation districts favor dry-pit submersible configurations for center-pivot systems. Sydney and Melbourne water utilities deploy demand-responsive flow modulation systems to reduce energy consumption during off-peak distribution periods.
Centrifugal Pump Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: full-line hydraulic specialists with integrated digital portfolios, regional fabrication houses serving price-sensitive agricultural segments, and engineered-to-order contractors for API-specified hydrocarbon service. Dominant competitive moves include backward integration into permanent magnet supply chains and technology licensing arrangements for sealless magnetic drive architectures.
Within the full-line specialist tier, Grundfos Holding A/S and KSB SE & Co. KGaA exemplify integrated service models that unbundle hardware from long-term performance contracts. Xylem Inc. anchors the digital monitoring vector, occupying a position where real-time operational data shifts revenue toward outcome-based arrangements. Ebara Corporation and Flowserve Corporation sit within the engineered-to-order segment, representing archetypes where project-specific customization dominates procurement qualification. Wilo SE and ITT Inc. exemplify regional-market depth strategies, while Sulzer Ltd. and Weir Group PLC occupy positions in abrasive-service and slurry-handling specializations.
| Leading Market Players |
|---|
| KSB SE & Co. KGaA |
| ITT Inc. |
| Grundfos Holding A/S |
| Wilo SE |
| Ebara Corporation |
| Flowserve Corporation |
| Sulzer Ltd. |
| Weir Group PLC |
| Xylem Inc. |
| Others |
Cost & Logistics Intelligence
Precision machinist concentrations in Stuttgart and Milan anchor labor-cost differentials that widen pricing-tier spreads between European premium manufacturers and Asian fabrication houses serving agricultural irrigation segments.
Pricing Analysis
The bundled-vs-unbundled service split separates capital-expenditure procurement from lifecycle performance contracting. Pricing stratifies across premium, standard, and economy tiers based on efficiency certification grade and after-sales service bundling. Cost compression in economy-tier agricultural pumps intensifies because stainless steel price volatility feeds through to bill-of-materials. Farming cooperatives in India and Brazil exhibit highest price sensitivity; municipal utilities in Germany and Australia show lowest sensitivity due to 20-year total-cost-of-ownership horizons.
Supply Chain Analysis
Reverse-logistics flows for remanufactured impellers and refurbished magnetic drive assemblies create secondary supply channels that compete with new equipment in price-sensitive segments. Permanent magnet production clusters in China, precision casting foundries in Germany, and stainless steel forging operations in India feed component dependencies for neodymium, duplex alloys, and CNC-machined housings. Single-source vulnerability concentrates in rare earth magnet supply chains. Distribution runs through OEM-direct municipal procurement pools, regional distributor networks for agricultural segments, and engineered-to-order contractors for API-specified hydrocarbon service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The centrifugal pump market functions as a stable compounder where efficiency mandate compliance drives steady replacement demand across municipal water infrastructure.
For Market Incumbents: Anchor market position through backward integration into permanent magnet supply chains and captive production of IE4-premium efficiency motors. Sealless technology specialists threaten incumbents with conventional sealed architectures. Certification investment in EU Ecodesign Directive compliance represents the critical defensive lever. For New Entrants and Emerging Players: Engineering procurement contractors in India's smart city infrastructure present the most penetrable channel partner type for intelligent pumping systems with integrated condition monitoring. White-space targets include variable frequency drive retrofits for existing fixed-speed installations and predictive maintenance service models for oil and gas downstream operators. Go-to-market execution should emphasize outcome-based energy performance guarantees rather than equipment transactions. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabrication houses serving price-sensitive agricultural segments that lack digital service capabilities. Long-term viability centers on manufacturers with verified lifecycle carbon footprints positioned for EU carbon border adjustment mechanism advantage. Monitor BIS certification enforcement in Indian agricultural procurement pools as inflection indicator for quality-tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnets | Captive neodymium supply secures magnetic drive pump assemblers against China supply concentration risk. |
| IE4-Premium Efficiency Motor Certification | EU Ecodesign Directive compliance qualifies manufacturers for German municipal unbundled procurement contracts. |
| Digital Twin Platform Development | Physics-based simulation enables predictive maintenance service models for Permian Basin oil extraction operators. |
| Remanufacturing Network Expansion | Refurbished impeller flows compete in agricultural segments while supporting circular economy mandates. |
| Regional Procurement Pool Aggregation | Consolidated demand in Jiangsu and Zhejiang provinces captures scale economies for desalination pump assemblers. |
Research Approach
Direct dialogue with plant engineers, municipal procurement directors, aftermarket service heads, and OEM technical sales specialists grounded qualitative findings in operational realities. Secondary validation drew from customs trade databases, SEC 10-K filings of listed pump manufacturers, EU Ecodesign Directive market surveillance reports, and MIIT GB standard enforcement disclosures. Bottom-up unit shipment estimates triangulated against top-down industrial capital expenditure flows across water treatment, oil extraction, and chemical processing sectors.
Segment-level value outputs across the projection horizon reflect modeled interactions between product type, technology architecture, application severity, and end-user procurement sophistication. CAGRs derived from regression analysis of historical replacement cycles against regulatory phase-in schedules. Industry-specific forecast inputs included desalination project pipelines in Saudi Arabia and Israel, Permian Basin produced water reinjection volumes, and EU carbon border adjustment mechanism implementation timelines.
Revisions become necessary when rare earth export restrictions materialize, efficiency mandate enforcement accelerates, or municipal procurement unbundling spreads beyond German and Australian utilities. Forecasts reflect documented assumptions about regulatory compliance timelines and industrial capital expenditure continuity. Practitioners should monitor BIS certification expansion in Indian agricultural equipment, EPA leak detection rulemaking for volatile organic compound service, and MIIT GB grade enforcement intensity for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Canned Motor Pumps Market
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Dispensing Pump Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Industrial Aerators Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market