
 Single-Stage Centrifugal Pumps Market | 2026-2036
Single-Stage Centrifugal Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Stage Centrifugal Pumps Market Analytics
Composite and polymer-based impeller materials are decoupling single-stage centrifugal pumps from traditional cast iron cost structures. Sulzer Ltd. leverages its Swiss engineering heritage to dominate high-specification chemical process applications. Grundfos Holding AS anchors its position through in-house production of energy-efficient motor-drive systems. Xylem Inc. competes aggressively in the North American municipal water sector with digitally integrated pump monitoring platforms.
A single-stage centrifugal pump converts rotational kinetic energy into hydrodynamic energy through a single impeller stage, typically achieving flow rates from 5 to 5,000 cubic meters per hour at heads up to 150 meters depending on impeller diameter and rotational speed. Its primary industrial purpose is to transfer clean or lightly contaminated fluids across water distribution, chemical processing, and thermal management systems. Horizontal pumps occupy the largest installed base in heavy industrial process settings where maintenance access and bearing longevity determine total cost of ownership. Submersible pumps represent the fastest-expanding category as borewell irrigation and deep-well municipal extraction projects multiply across water-stressed regions. Stainless steel material grades command premium positioning in chemical industry and potable water segments where corrosion resistance extends service intervals and satisfies sanitary regulations.
The US EPA Safe Drinking Water Act and EU Ecodesign Directive jointly enforce minimum efficiency standards that disqualify older pump architectures from public procurement tenders. India's BIS IS 8034 and IS 14220 standards mandate performance testing protocols that shape import eligibility and domestic manufacturing compliance. China's MIIT GB 19762 efficiency grades create tiered market access where premium motor-pump combinations qualify for state-backed infrastructure rebates. Stakeholders must monitor evolving carbon-border adjustment mechanisms and regional efficiency label harmonization to align product portfolios with shifting compliance thresholds.
Market Dynamics
Stainless steel procurement mandates from water utilities are compressing traditional cast iron supply chains while accelerating material certification timelines across municipal tender processes.
Growth Catalysts
- MIIT GB 19762 Efficiency Grades:China's tiered motor-pump efficiency standards unlock state-backed infrastructure rebates for premium equipment configurations.
- Agricultural Irrigation Modernization:India's government-sponsored replacement cycles in water-stressed heartland states drive borewell pump volume concentration.
- Potable Water Corrosion Standards:Stricter stainless steel requirements from US EPA Safe Drinking Water Act procurement clauses extend service intervals for compliant suppliers.
Market Restraints
- Alloy Price Volatility:Nickel and chromium input cost swings compress margin stability for stainless steel variant producers.
- Foundry Capacity Concentration:Heavy cast iron impeller production clusters in select industrial zones create geographic supply vulnerability.
- Submersible Motor Seal Failure Rates:Technical limitations in deep-well thermal management restrict operational depth specifications.
Strategic Opportunities
- Digital Pump Monitoring Convergence:Integration of vibration sensors with cloud-based predictive maintenance platforms creates service revenue attachment.
- Rural Water Infrastructure Gaps:India's underserved district-level distribution networks offer white space for packaged pump-motor systems.
- EU Ecodesign Directive Expansion:Anticipated scope broadening to smaller horsepower ratings will disqualify legacy architectures from public tenders.
Industry Challenges
- Hydraulic Design Talent Scarcity:Specialized computational fluid dynamics expertise required for impeller optimization faces limited pipeline from engineering programs.
- Multi-Standard Certification Overlap:Simultaneous BIS IS 8034, IS 14220, and EU CE marking compliance creates testing timeline bottlenecks for export-oriented manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Stage Centrifugal Pumps Market |
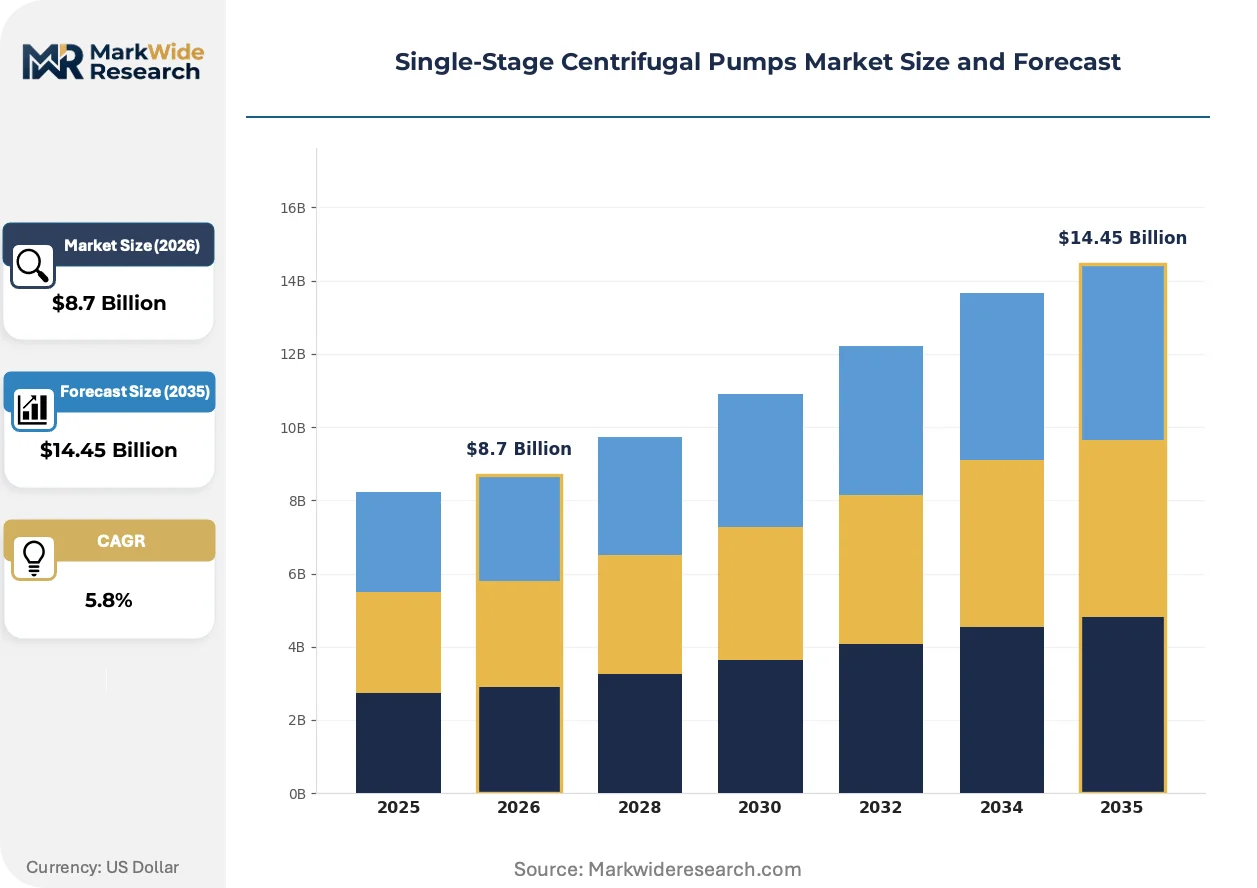
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Pumps, Vertical Pumps, Submersible Pumps, End Suction Pumps End User: Agriculture, Water Supply, Chemical Industry, HVAC Application: Irrigation, Industrial Process, Fire Suppression, Wastewater Treatment Material: Cast Iron, Stainless Steel, Bronze, PVC |
| Companies Covered | Sulzer Ltd., KSB Company, Grundfos Holding AS, Xylem Inc., Flowserve Corporation, Wilo Group, Baker Hughes Company, Weir Group PLC, Andritz AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Stage Centrifugal Pumps Market Evolving Landscape
Polymer composite impeller fabrication is decoupling performance specifications from traditional metallurgical constraints while enabling modular manufacturing footprints closer to demand clusters.
Computational fluid dynamics-optimized polymer impellers are unifying corrosion resistance with weight reduction in chemical process applications. Specialty chemical processors in Germany and the Netherlands are qualifying these components for intermittent duty cycles previously reserved for alloy castings. The technology is unifying spare parts logistics with on-demand additive manufacturing capabilities, compressing regional inventory requirements.
REACH Annex XVII restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent passivation or laser surface texturing for stainless steel wetted components. Pump OEMs serving EU municipal water tenders must redesign finishing lines to maintain CE marking eligibility. The regulation is reshaping supplier qualification protocols, with coating subcontractors facing accelerated audit frequencies.
Lifecycle cost contracting is displacing unit-price procurement in Scandinavian district heating networks. Energy service companies now guarantee kilowatt-hour consumption thresholds across fifteen-year service agreements, absorbing efficiency risk. Denmark and Sweden anchor this model, with Dutch water boards piloting similar performance guarantees for sewage lift stations.
Single-Stage Centrifugal Pumps Market Segmentation
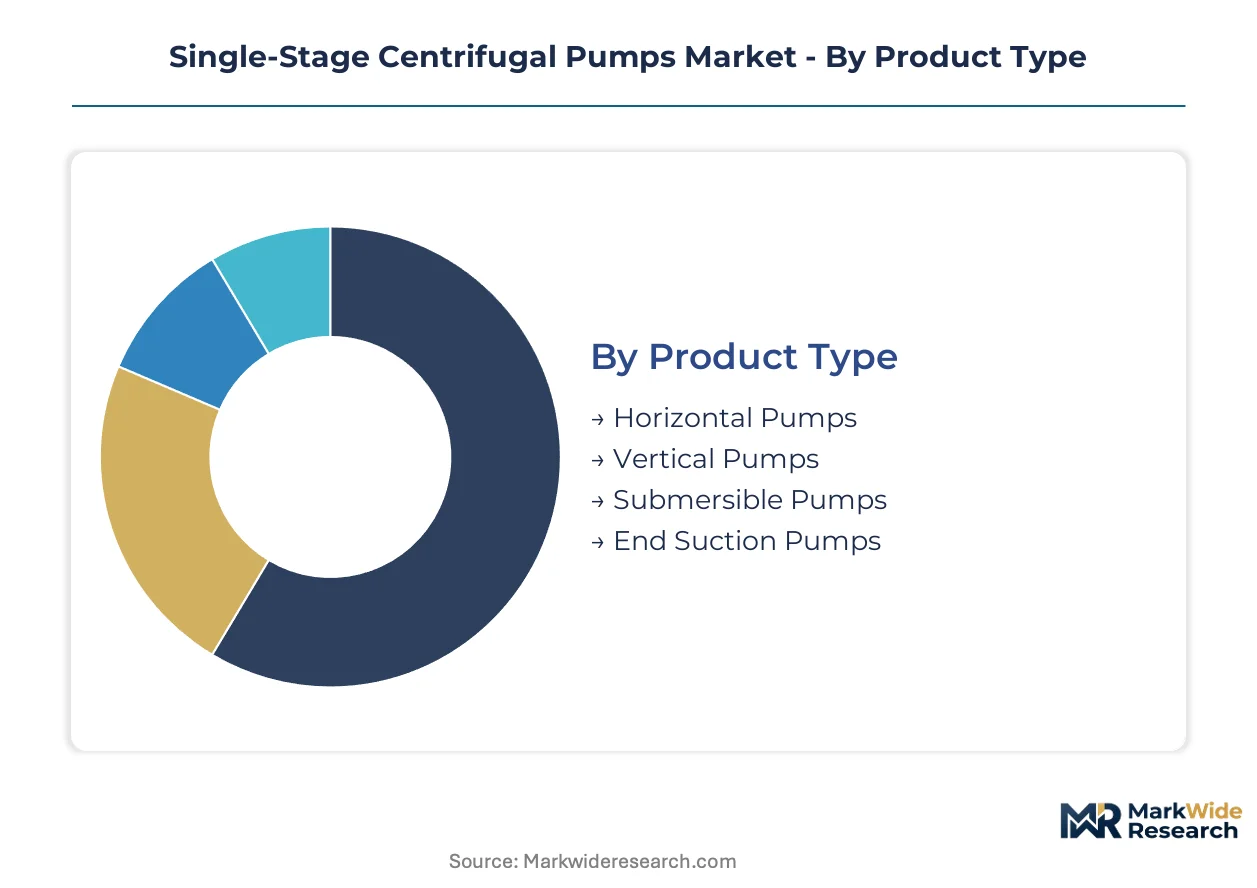
Segmentation in single-stage centrifugal pumps determines procurement specifications across replacement cycles. Material grades and mounting configurations dictate compliance eligibility for tender processes. End-use concentration in water-stressed geographies reshapes product mix priorities for manufacturers.
Product Type:
Upgrade cycles favor configurations that reduce lifetime operating costs and extend maintenance intervals in continuous-duty installations.
- Horizontal Pumps:Split-case or end-suction designs with bearing housings accessible at floor level dominate heavy industrial process settings. Water supply utilities in Germany and the United States specify these for baseload distribution stations where bearing longevity determines total cost of ownership.
- Submersible Pumps:Motor-impeller integrated units operate fully immersed in borewell and deep-well extraction applications. India's agricultural heartland states—Maharashtra, Gujarat, and Tamil Nadu—drive procurement volume through government-sponsored irrigation modernization schemes replacing surface-mounted installations.
- Vertical Pumps:Space-saving inline configurations suit HVAC riser installations and compact plant rooms where footprint constraints override maintenance access preferences.
- End Suction Pumps:Single-entry impeller designs with overhung shafts serve light industrial and commercial building services where capital cost sensitivity exceeds efficiency optimization priorities.
Horizontal pumps sit at the top of the volume ranking, with submersible pumps climbing the fastest.
End User:
Cost tier differentiation separates specification-intensive process industries from price-sensitive bulk procurement segments.
- Water Supply:Municipal utilities and private water operators mandate stainless steel wetted components under EPA Safe Drinking Water Act and EU Drinking Water Directive corrosion standards. Procurement clauses in California, Texas, and the Netherlands explicitly disqualify cast iron for potable contact surfaces.
- Agriculture:Borewell irrigation and surface water lift schemes concentrate demand in India's Cauvery and Narmada basins, China's North China Plain, and California's Central Valley. Submersible motor-pump sets dominate where groundwater depth exceeds fifteen meters.
- Chemical Industry:Specialty processors in Germany's Rhine-Ruhr cluster and the Netherlands' Rotterdam port complex specify alloy grades and mechanical seal configurations for intermittent duty with aggressive media.
- HVAC:District heating networks in Denmark and Sweden specify premium efficiency grades under lifecycle cost contracting models, while commercial building services prioritize compact vertical inline units.
Water supply commands the premium pricing tier, while agriculture generates the highest unit volumes.
Application:
Volume concentration follows infrastructure investment cycles in water-stressed regions and industrial capacity expansion.
- Irrigation:Surface and pressurized distribution systems in India's PM-KUSUM scheme and China's high-standard farmland construction program drive replacement demand for electrically powered surface and submersible units.
- Industrial Process:Chemical transfer, cooling water circulation, and boiler feed applications in Texas Gulf Coast petrochemical complexes and Germany's BASF-Ludwigshafen cluster specify horizontal split-case and multistage derivatives.
- Wastewater Treatment:Municipal sewage lift stations in the Netherlands and Florida favor submersible grinder pumps with vortex impellers for solids handling.
- Fire Suppression:NFPA 20 compliance mandates dedicated fire pump installations in high-rise construction across Dubai, Singapore, and New York City.
Irrigation absorbs the largest share of annual installations, with wastewater treatment gaining share fastest.
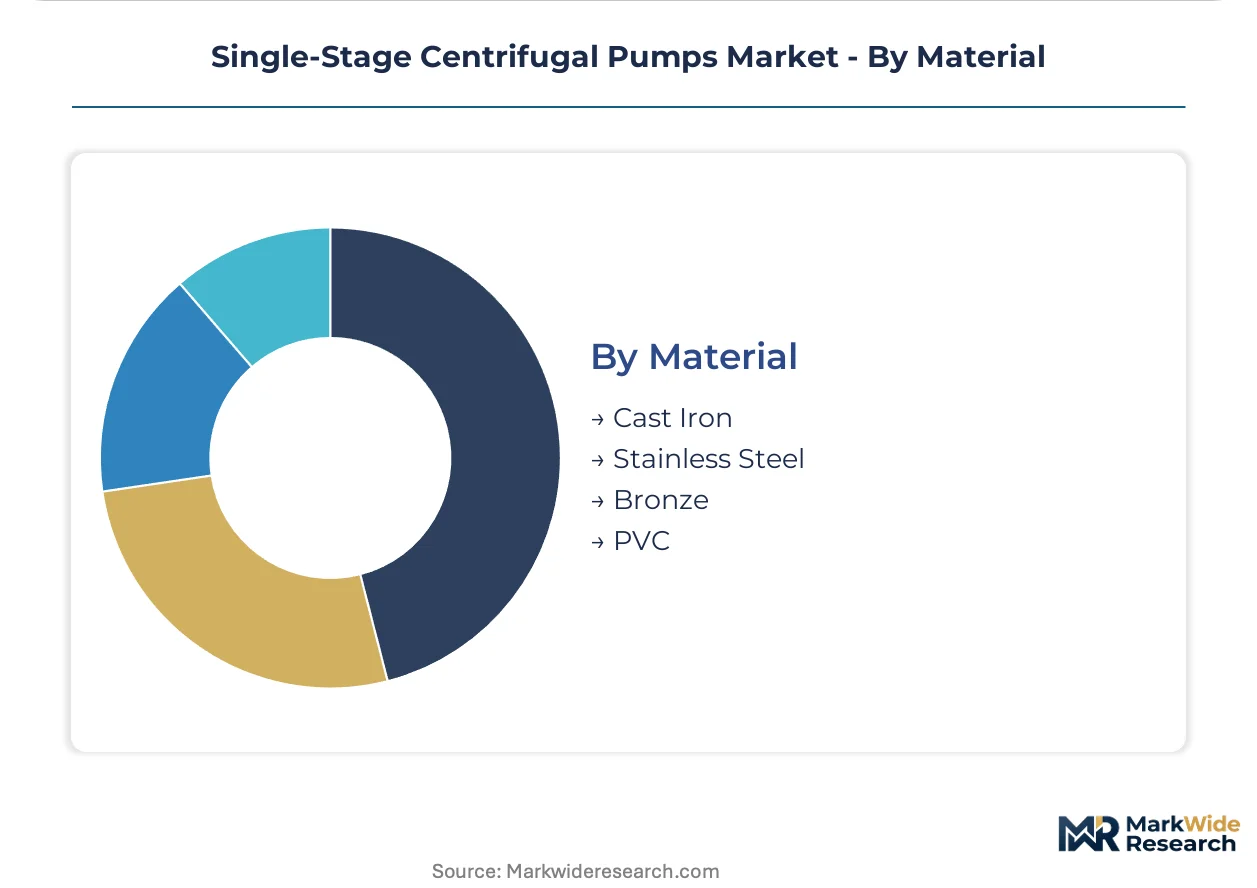
Material:
Margin structure stratifies around corrosion resistance certification and alloy input cost volatility.
- Stainless Steel:AISI 316 and duplex grades satisfy potable water and chemical process specifications where service interval extension justifies material premium. REACH Annex XVII hexavalent chromium restrictions force conversion to trivalent passivation or laser surface texturing for CE marking eligibility.
- Cast Iron:Gray and ductile iron impeller and volute castings retain cost advantage in irrigation and wastewater segments where corrosion tolerance permits shorter replacement cycles. Foundry capacity concentrates in China's Hebei province and India's Coimbatore cluster.
- Bronze:Naval brass and aluminum bronze variants serve marine applications and select chemical services where galvanic compatibility and biofouling resistance matter.
- PVC:Thermoplastic pump housings and impellers handle corrosive effluents and ultrapure water in semiconductor fabrication and pharmaceutical processing.
Cast iron retains volume leadership, while stainless steel captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr industrial corridor anchors European demand for process-grade single-stage centrifugal pumps, with municipal utilities across North America and Asia-Pacific accelerating procurement cycles to meet tightening efficiency mandates.
United States
Municipal water utilities in California and Texas drive stainless steel procurement for potable distribution networks. EPA Safe Drinking Water Act corrosion standards disqualify cast iron from surface water contact applications. The Permian Basin petrochemical cluster specifies horizontal split-case pumps for cooling water circulation at BASF-TotalEnergies and Dow facilities.
China
North China Plain irrigation modernization and Yangtze River Delta chemical processing expansion concentrate demand for submersible and horizontal configurations. MIIT GB 19762 efficiency grades tier state-backed infrastructure rebates toward premium motor-pump combinations. Shandong Province foundry clusters supply gray iron impellers for domestic agricultural replacement cycles.
India
Maharashtra, Gujarat, and Tamil Nadu agricultural heartland states absorb submersible pump volumes through PM-KUSUM irrigation scheme disbursements. BIS IS 8034 and IS 14220 performance testing protocols shape import eligibility and domestic manufacturing compliance. Coimbatore's pump manufacturing cluster specializes in cast iron borewell motor-pump sets for groundwater extraction beyond fifteen meters.
Germany
Rhine-Ruhr specialty chemical processors and Netherlands Rotterdam port complex operators specify alloy-grade pumps for intermittent duty with aggressive media. REACH Annex XVII hexavalent chromium restrictions force conversion to trivalent passivation for CE marking eligibility. Bavarian pump OEMs redesign finishing lines to maintain municipal water tender eligibility across EU member states.
Netherlands
Dutch water boards pilot lifecycle cost contracting for sewage lift stations, displacing unit-price procurement with fifteen-year energy performance guarantees. EU Ecodesign Directive minimum efficiency standards shape public tender specifications for distribution infrastructure. Rotterdam's chemical processing hub qualifies polymer composite impellers for duty cycles previously reserved for stainless steel castings.
Single-Stage Centrifugal Pumps Market Competitive Landscape
Portfolio diversification dominates the current landscape as established players extend from core pump manufacturing into integrated monitoring systems and energy service contracting. The vendor base stratifies across three tiers: multinational engineering conglomerates with captive motor-drive production, mid-cap specialists in corrosion-resistant materials, and regional fabricators serving price-sensitive agricultural procurement. Two archetypes anchor competitive positioning: vertically integrated system houses controlling upstream motor manufacturing, and material science specialists qualifying polymer composites for chemical process applications. Geographic expansion into India's district-level distribution networks and technology licensing for digital predictive maintenance platforms represent the dominant competitive moves.
Within the integrated system house tier, Grundfos Holding AS and Xylem Inc. occupy positions defined by in-house energy-efficient motor production and cloud-based pump monitoring capabilities respectively. Sulzer Ltd. exemplifies the high-specification chemical process specialist archetype, leveraging Swiss engineering heritage in corrosion-resistant alloy applications. These three companies represent contrasting strategic vectors: captive vertical integration, digital service platform convergence, and premium material qualification for regulated process industries.
| Leading Market Players |
|---|
| Sulzer Ltd. |
| KSB Company |
| Grundfos Holding AS |
| Xylem Inc. |
| Flowserve Corporation |
| Wilo Group |
| Baker Hughes Company |
| Weir Group PLC |
| Andritz AG |
| Others |
Value Network & Pricing Analysis
EU REACH Annex XVII hexavalent chromium restrictions gate qualified supply for CE-marked municipal tenders while segmenting manufacturers into premium-certified and standard-grade pricing tiers. Stainless steel passivation compliance costs compress margins for non-specialist foundries and disqualify legacy finishing lines from Dutch and German water utility procurement.
Pricing Analysis
Input-cost pass-through from nickel and chromium alloy volatility compresses margin stability for stainless steel variant producers serving chemical process and potable water segments. Three-tier pricing structure across premium-certified, standard-grade, and economy-cast tiers separates Grundfos and Sulzer configurations from regional Indian fabricators. Pricing pressure stems from Shandong Province gray iron oversupply flooding agricultural replacement cycles. Agricultural borewell pump buyers exhibit highest price sensitivity while Rhine-Ruhr specialty chemical processors accept material premiums for duplex-grade corrosion resistance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale municipal utility demand in California, Texas, and the Netherlands while distributor networks serve India's district-level agricultural procurement. Foundry capacity concentrates in China's Hebei province, India's Coimbatore cluster, and Germany's Bavarian industrial corridor. Raw material dependencies draw from Indonesian nickel ore, South African chromium, and scrap steel feedstocks. Single-source vulnerability in deep-well submersible motor seal manufacturing restricts operational depth specifications. Distribution runs through authorized service partners for aftermarket spare parts and predictive maintenance platform subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through successive regulatory tightening, with EU Ecodesign Directive scope expansion to sub-10kW ratings representing the next demand inflection.
For Market Incumbents: Hedge alloy price exposure through long-term nickel and chromium supply agreements with Indonesian and South African mining consortia. Accelerate polymer composite impeller qualification to decouple from foundry capacity constraints. Capture digital service revenue by embedding vibration sensors and cloud-based predictive maintenance platforms in municipal tender offerings. Defend against mid-cap material specialists by locking exclusive distribution through Dutch and German water board lifecycle cost contracting pilots. For New Entrants and Emerging Players: The premium-economy price-point gap in India's PM-KUSUM agricultural irrigation scheme creates white-space for packaged pump-motor systems with BIS IS 8034 certification. Target Maharashtra and Gujarat district-level distribution networks where incumbent coverage remains sparse. Pursue technology licensing partnerships with Bavarian OEMs for trivalent passivation finishing lines to shortcut CE marking eligibility. Qualify polymer composite impellers for intermittent chemical process duty in Rotterdam's specialty processing hub. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap corrosion-resistant material specialists with captive foundry capacity and BIS certification infrastructure. Five-to-ten year viability favors targets with demonstrated EU Ecodesign Directive compliance and installed base expansion into Scandinavian lifecycle cost contracting markets. Monitor MIIT GB 19762 efficiency grade tier movements as the signal for state-backed infrastructure rebate eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor-Drive Manufacturing | Captive energy-efficient motor production secures MIIT rebate eligibility for Chinese infrastructure tenders. |
| Polymer Composite Impeller Qualification | Rotterdam chemical processors validate additive-manufactured components for aggressive media intermittent duty. |
| Digital Predictive Maintenance Platform Deployment | Vibration sensor integration creates fifteen-year service revenue attachment in Dutch water board contracts. |
| BIS Certification Infrastructure Investment | IS 8034 and IS 14220 testing capability unlocks PM-KUSUM scheme eligibility for agricultural pump volumes. |
| Trivalent Passivation Finishing Line Conversion | REACH Annex XVII compliance maintains CE marking access for German and Dutch municipal water tenders. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's pump manufacturing clusters and municipal utility procurement offices. The research combines structured interviews with maintenance directors at German chemical processors, OEM procurement teams in Texas petrochemical facilities, and aftermarket service heads at Indian agricultural distributors with secondary validation from SEC 10-K filings, customs trade data, and BIS certification registries. Bottom-up installation volume estimates triangulate against top-down market value reconstruction across material grade and mounting configuration segments.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models product type, end user, application, and material grade dimensions alongside regional regulatory cluster alignment. CAGRs derive from segment-level growth rate reconciliation with macro infrastructure investment cycles. Forecast inputs incorporate MIIT efficiency grade tier movements, PM-KUSUM scheme disbursement trajectories, and EU Ecodesign Directive scope expansion timelines.
Caveats apply where nickel-chromium alloy price spikes, foundry capacity disruptions, or submersible motor seal thermal management breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure rebate continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Global Solar Water Pump Systems Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Fire Pump Test Meters Market