
 Europe Water Pump Market | 2026-2036
Europe Water Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Water Pump Market Insights
CE marking under the Ecodesign Directive is rotating the competitive landscape toward higher-efficiency pump architectures. Grundfos leverages its Danish R&D base to dominate variable-speed circulator technology. Wilo anchors its position through deep vertical integration in electronic controls and system integration for building services.
A water pump converts mechanical energy into hydraulic energy to move fluids through piping networks, typically achieving flow rates from liters per minute to thousands of cubic meters per hour depending on impeller geometry and motor configuration. Centrifugal pumps occupy the bulk of industrial and municipal installations due to their scalability and tolerance for abrasive media. Positive displacement technology sustains premium margins in high-pressure process applications where precise volumetric delivery matters. Electric drive systems lead the technology dimension while solar-powered units gain traction in remote agricultural zones across Southern Europe.
The EU Ecodesign Directive and F-Gas Regulation shape product development cycles by mandating efficiency thresholds and restricting refrigerants in cooling circuits. Germany's KBA and France's ANSM enforce national transpositions that delay market entry for non-compliant equipment. Stakeholders must monitor the EU's evolving taxonomy for sustainable water infrastructure as financing rules redirect capital toward certified efficient systems.
Market Dynamics
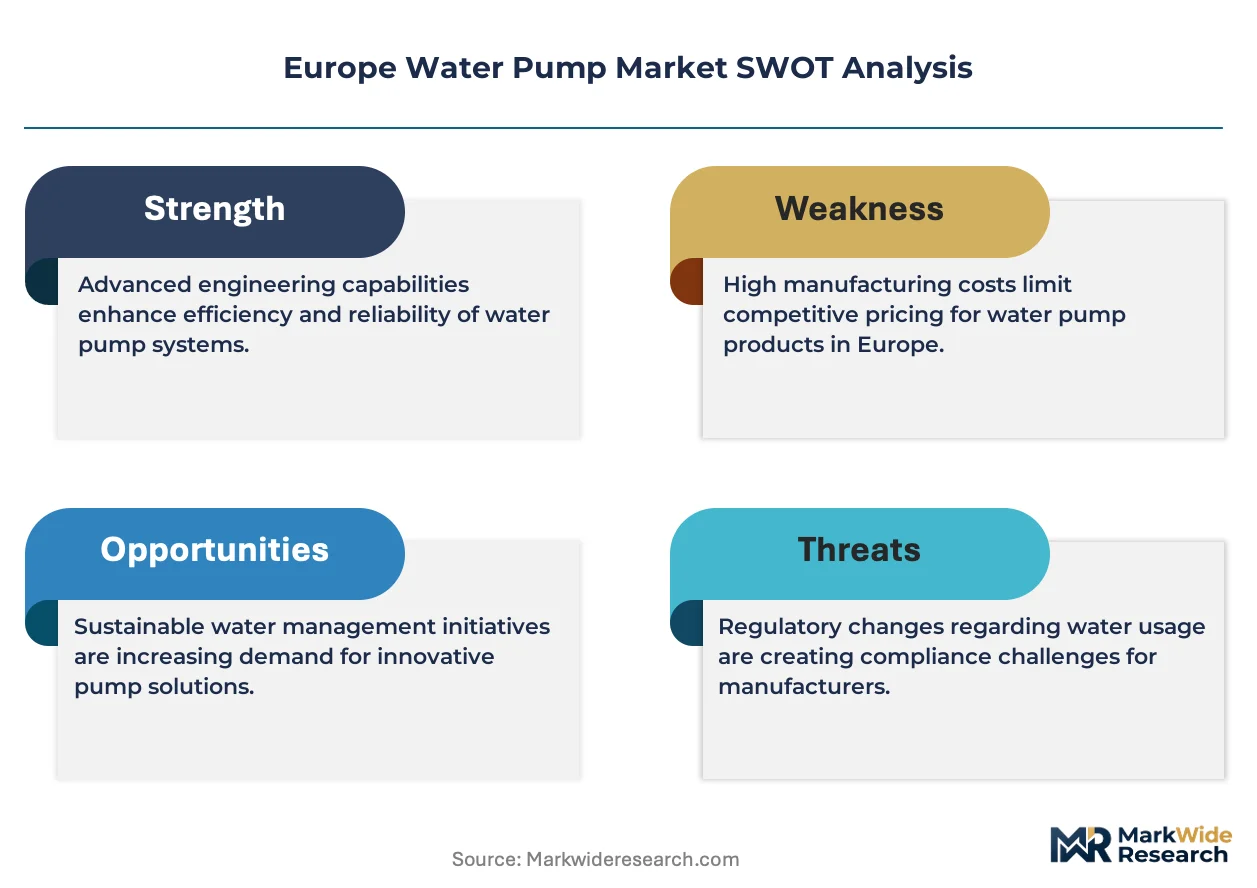
The EU Ecodesign Directive is compressing product lifecycles across the European water pump landscape, forcing manufacturers to redesign hydraulic architectures around minimum efficiency index thresholds before non-compliant stock becomes unsellable.
Growth Catalysts
- Wastewater Infrastructure Modernization:Municipal utilities in Germany and France are expanding tertiary treatment capacity to meet Urban Waste Water Treatment Directive standards, creating sustained demand for submersible and dry-pit pump configurations.
- Variable-Speed Drive Adoption:Electronic commutation and permanent magnet motors are penetrating building services and district heating networks, cutting energy consumption by enabling pressure-controlled operation rather than throttling.
- Agricultural Water Stress:Northern Italy's Po Valley irrigation cooperatives are replacing fixed-speed borehole pumps with solar-hybrid systems to reduce diesel dependency and secure water abstraction licenses under tightening river basin management plans.
Market Restraints
- Copper and Rare Earth Price Volatility:Permanent magnet motor production depends on neodymium supply chains concentrated in Chinese processing facilities, exposing European assemblers to input cost swings and potential export restriction risks.
- Foundry Capacity Concentration:Ductile iron casting for pump housings clusters in Eastern European supplier parks, creating single-source vulnerabilities for mid-tier manufacturers without captive metallurgical capabilities.
- CE Marking Compliance Burden:The Machinery Directive's harmonized standards require third-party notified body intervention for pumps above certain power thresholds, extending time-to-market by four to eight months for non-EU origin equipment.
Strategic Opportunities
- Digital Pump Twins:Cloud-connected vibration and temperature sensors combined with machine learning algorithms enable predictive maintenance contracts, shifting revenue from hardware sales to recurring service streams in industrial process applications.
- Hydrogen Electrolyzer Integration:PEM and alkaline electrolysis plants require high-pressure circulation loops for thermal management, opening a nascent specification channel for magnetically coupled canned motor pumps in the Netherlands and German hydrogen clusters.
- EU Taxonomy Alignment:Sustainable finance disclosure requirements are redirecting institutional capital toward water infrastructure projects that specify Ecodesign-compliant equipment, creating preferential procurement pathways for certified suppliers.
Industry Challenges
- Electronics-Hydraulics Integration:Power electronics and sensor calibration expertise sits outside traditional pump engineering departments, forcing recruitment competition with automotive and renewable energy sectors for embedded systems talent.
- Legacy System Interoperability:Building automation retrofits in Germany's municipal stock require protocol translation between proprietary pump controls and open BACnet standards, complicating specification and commissioning workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Water Pump Market |
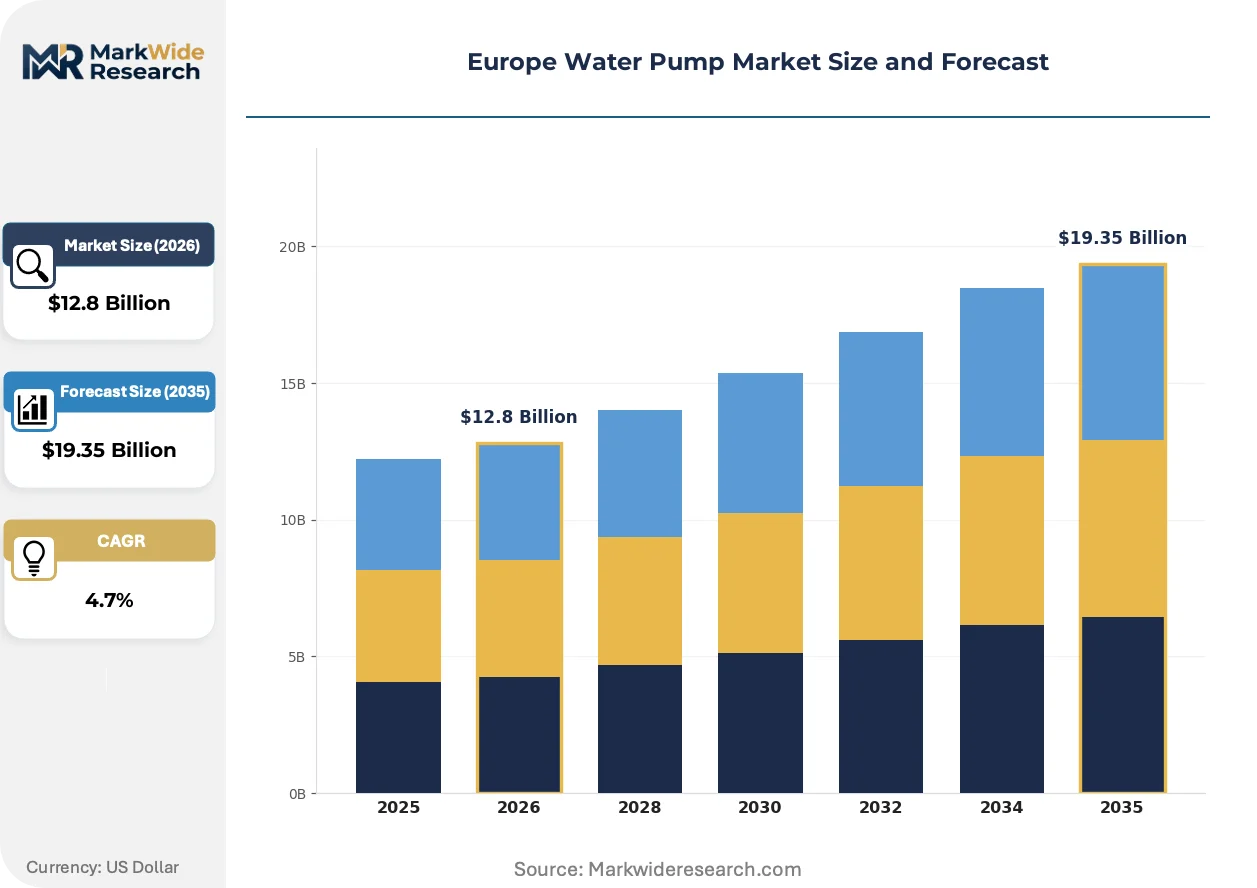
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Positive Displacement, Diaphragm, Submersible Application: Agriculture, Industrial, Municipal, Commercial End User: Construction, Manufacturing, Irrigation, Utilities Technology: Electric, Diesel, Solar, Hydraulic |
| Companies Covered | Wilo, Flowserve, Grundfos, Andritz AG, Ebara Corporation, KSB, Xylem, Caprari, Sulzer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Water Pump Market Trends and Innovations
Electrification and intelligence are converging to redefine pump system architecture, with efficiency mandates accelerating the retirement of fixed-speed mechanical designs in favor of adaptive, sensor-rich hydraulic platforms.
Permanent magnet synchronous motors paired with variable frequency drives are displacing asynchronous induction motors in circulator and booster applications. German HVAC contractors are specifying these configurations as default for new build and deep retrofit projects. The shift is compressing margins for manufacturers lacking in-house power electronics capabilities while rewarding integrated system suppliers.
The EU F-Gas Regulation's phase-down schedules are forcing refrigerant pump manufacturers to redesign hermetic compressor systems for lower-GWP alternatives. Industrial refrigeration OEMs in Denmark and Sweden are accelerating qualification programs for CO2 transcritical booster pumps. Cold chain logistics operators in the Netherlands are demanding equipment pre-certified for R744 compatibility to avoid stranded asset risk.
Performance contracting is displacing traditional capital purchase models in municipal water sectors. French and British water utilities are tendering energy performance guarantees that transfer operational risk to pump OEMs. This restructures vendor-client relationships around verified savings rather than upfront equipment cost, concentrating contract awards among suppliers with established service networks and baseline energy audit capabilities.
Europe Water Pump Market Segmentation
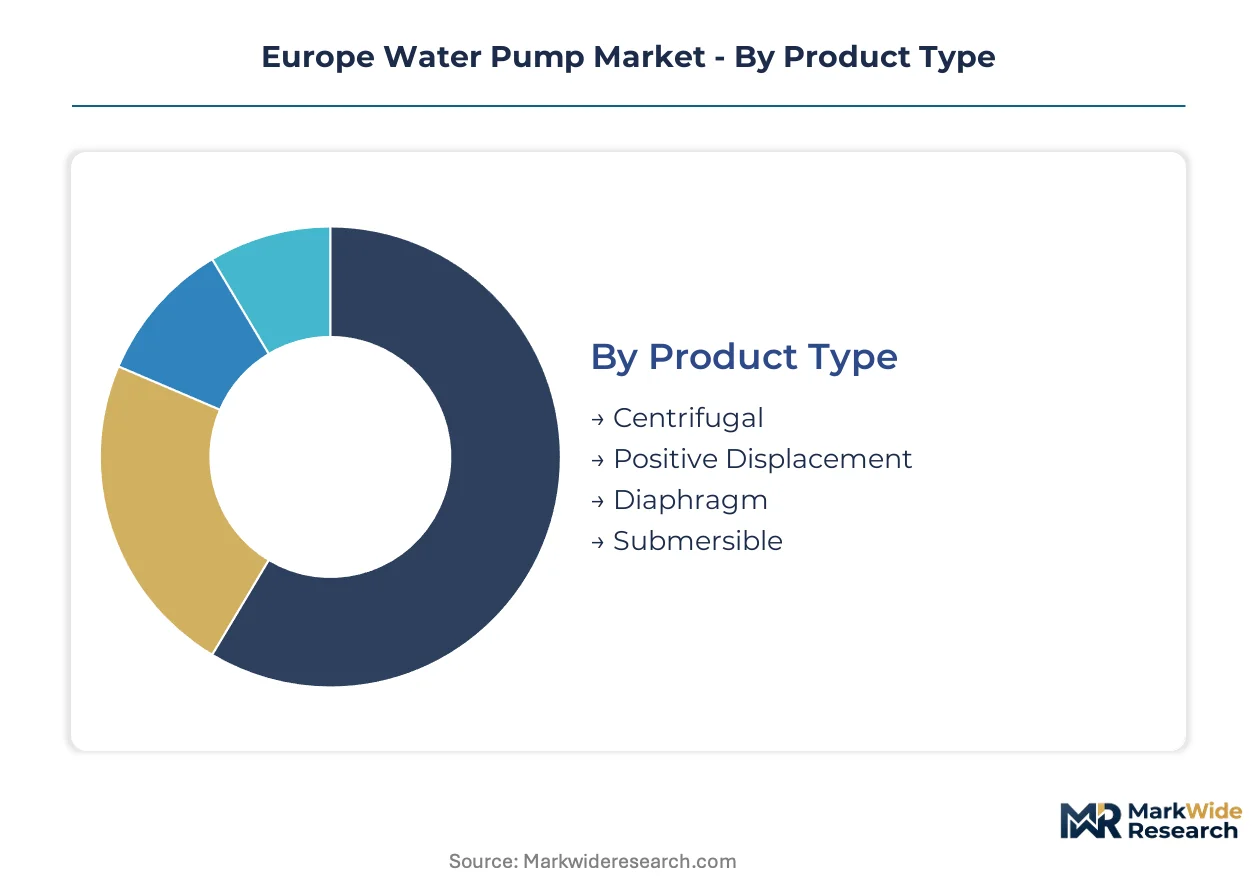
Water pump procurement channels diverge sharply across Europe, with municipal tenders favoring certified efficiency tiers while agricultural buyers prioritize total cost of ownership. Understanding segment-channel alignment reveals where specification power concentrates and which technology transitions will reshape vendor relationships.
Product Type:
Centrifugal units move through distributor networks serving industrial and municipal accounts, while positive displacement and specialized configurations often sell direct to OEM integrators and process engineering firms.
- Centrifugal:Impeller-based hydraulic architectures dominate volume installations across wastewater treatment and building services. German municipal utilities specify these for tertiary treatment expansion under Urban Waste Water Treatment Directive compliance timelines.
- Positive Displacement:Rotating or reciprocating mechanisms deliver precise volumetric flow for high-pressure process loops. Northern Italian food processing and chemical manufacturers specify these where shear-sensitive fluid handling matters.
- Diaphragm:Seal-less designs handle abrasive slurries and corrosive media in mining tailings and chemical transfer. Eastern European extractive industries drive replacement cycles.
- Submersible:Motor-hydraulic integration for borehole and wet-pit installation serves agricultural abstraction and drainage networks across the Po Valley and French cereal plains.
Centrifugal pumps dominate installed base. Positive displacement is where expansion concentrates in premium process applications.
Application:
Cost tier segmentation separates specification-intensive municipal tenders from price-sensitive agricultural procurement, with industrial and commercial applications occupying intermediate positions on engineering intensity.
- Agriculture:Irrigation abstraction and drainage systems span open-field and greenhouse operations. Italian and Spanish water stress regulations are accelerating solar-hybrid retrofits in river basin districts with tightening abstraction licenses.
- Industrial:Process cooling, boiler feed, and chemical transfer require continuous-duty reliability. German automotive and chemical clusters specify magnetically coupled designs for leak-free operation.
- Municipal:Drinking water distribution and wastewater collection networks operate under EU Ecodesign efficiency mandates. French and British utilities are tendering energy performance guarantees that transfer operational risk to OEMs.
- Commercial:Building services circulation and pressure boosting follow HVAC specification channels. Danish and Swedish district heating networks are adopting variable-speed circulators as default.
Municipal applications anchor revenue stability. Agricultural solar-hybrid retrofits are climbing the fastest among specification channels.
End User:
Customer type determines service attachment rates, with utilities and manufacturing operations generating recurring maintenance revenue while construction and irrigation segments favor transactional procurement.
- Construction:Temporary dewatering and site drainage equipment moves through rental channels. German residential building permits influence short-term demand volatility.
- Manufacturing:Process-integrated pump systems require predictive maintenance contracts. Dutch and Belgian chemical processors are specifying digital pump twins for vibration monitoring.
- Irrigation:Cooperative and individual farm purchases concentrate in Northern Italy and France's Grand Est region. River basin management plans are restricting diesel-powered abstraction.
- Utilities:Municipal water and wastewater operators specify through framework agreements. CE marking and Ecodesign compliance filter vendor eligibility.
Utilities dominate long-term contract value. Manufacturing digitalization is where service revenue expansion concentrates.
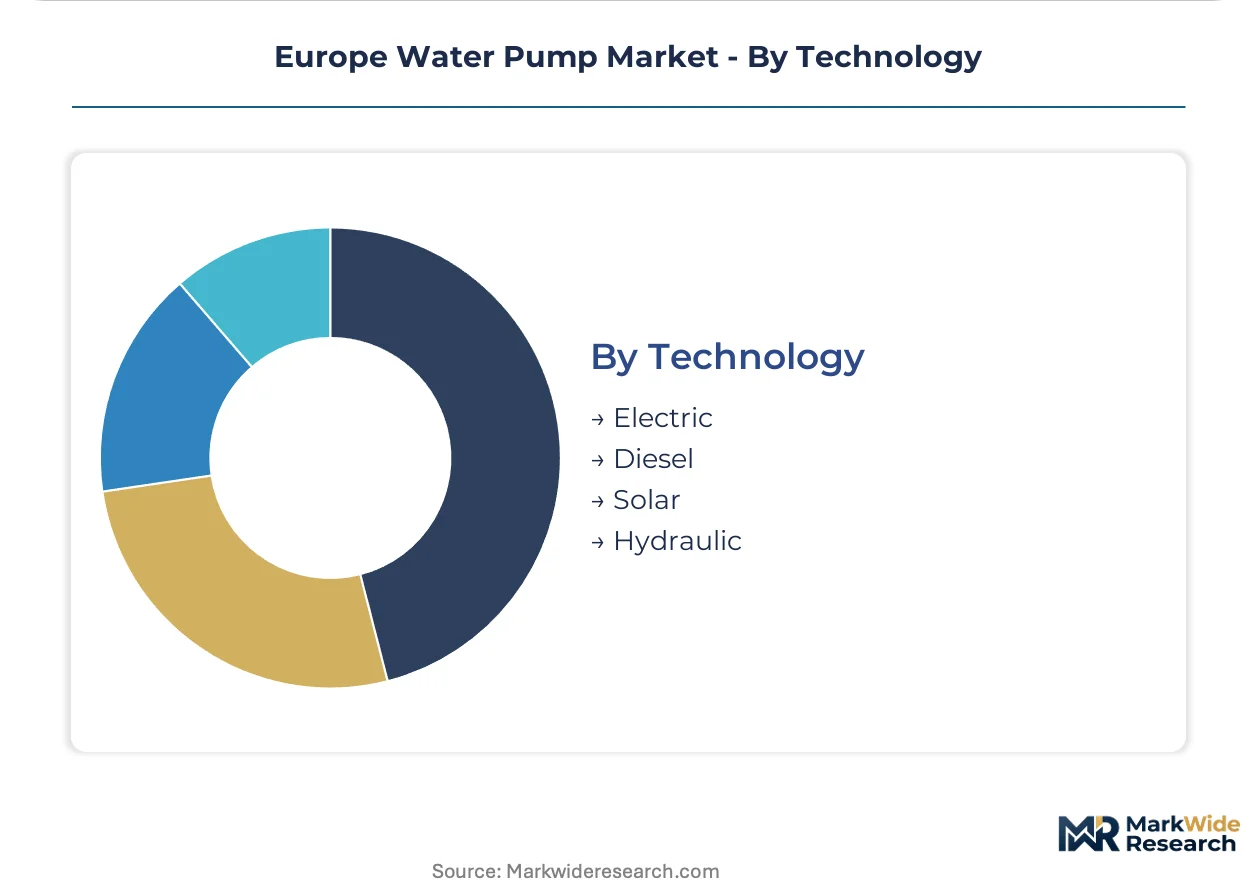
Technology:
Supply concentration for permanent magnet motors and power electronics is reshaping technology cost structures, with electric configurations consolidating share as diesel faces regulatory pressure.
- Electric:Grid-connected and battery-backed motor drives serve continuous-duty municipal and industrial applications. German KBA efficiency transpositions favor permanent magnet synchronous configurations.
- Diesel:Mobile and backup power for remote construction and emergency dewatering. French and Italian emissions zones are restricting non-road mobile machinery.
- Solar:Photovoltaic-powered DC pumps for off-grid agricultural abstraction. Southern European irradiance patterns and subsidy structures determine payback economics.
- Hydraulic:Fluid power transmission for explosion-risk environments and mobile equipment. Specialist applications in mining and marine sectors.
Electric technology dominates new specification. Solar configurations are gaining share fastest in Mediterranean agricultural zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's efficiency mandates and national transpositions of the Ecodesign Directive are redirecting procurement budgets toward certified pump architectures across member states. Municipal tenders now weight lifecycle energy consumption above upfront capital cost. Industrial clusters in Germany, France, Italy, the Netherlands, and Poland are absorbing the bulk of technology transition investment.
Germany
German municipal utilities are expanding tertiary wastewater treatment capacity under Urban Waste Water Treatment Directive deadlines. The KBA enforces national Ecodesign transpositions that filter non-compliant equipment from public tenders. The Ruhr industrial corridor and Bavarian chemical clusters specify magnetically coupled pumps for leak-free process cooling.
France
French water utilities are tendering energy performance guarantees that transfer operational risk to OEMs under ANSM oversight of infrastructure procurement standards. The Grand Est cereal plains and Paris Basin irrigation cooperatives are replacing diesel abstraction pumps with solar-hybrid configurations to secure river basin licenses.
Italy
Northern Italy's Po Valley irrigation cooperatives face tightening water abstraction permits under river basin management plans. Regional authorities in Lombardy and Emilia-Romagna subsidize solar-powered borehole retrofits to reduce diesel dependency. Food processing manufacturers in Parma and Modena specify positive displacement pumps for shear-sensitive fluid handling.
Netherlands
Dutch hydrogen electrolyzer clusters in the Port of Rotterdam and Eemshaven are creating specification channels for high-pressure canned motor pumps in PEM and alkaline thermal management loops. Cold chain logistics operators demand R744-compatible equipment pre-certified under F-Gas Regulation phase-down schedules.
Poland
Polish foundry parks in Silesia and Lower Silesia supply ductile iron castings for pump housings to mid-tier European assemblers. German OEMs are qualifying secondary metallurgical sources to reduce single-source vulnerability. Municipal utilities in Warsaw and Kraków are modernizing district heating circulation networks with variable-speed drives.
Europe Water Pump Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth, creating a tiered structure where scale-driven multinationals face focused engineering houses. The vendor base clusters around three strategic archetypes: integrated system suppliers controlling power electronics and hydraulics, component specialists selling through distributor networks, and regional fabricators serving price-sensitive replacement markets. Dominant competitive moves include backward integration into permanent magnet motor production and strategic partnerships with hydrogen electrolyzer OEMs.
Among Denmark-based integrated suppliers, Grundfos and Wilo exemplify the system-level archetype combining hydraulic design with captive electronic control production. Flowserve represents the multinational project-engineering tier serving process industry accounts through direct specification relationships. These anchors illustrate how competitive positioning increasingly depends on in-house capabilities across the electromechanical boundary rather than pure hydraulic engineering.
| Leading Market Players |
|---|
| Wilo |
| Flowserve |
| Grundfos |
| Andritz AG |
| Ebara Corporation |
| KSB |
| Xylem |
| Caprari |
| Sulzer |
| Others |
Pricing and Supply Chain Analysis
Foundry capacity utilization rates above 85 percent in Polish and Czech metallurgical parks compress margin structures for ductile iron castings while simultaneously elevating price floors for pump housings sourced by mid-tier European assemblers lacking captive metallurgical capabilities.
Pricing Analysis
Certification level under the EU Ecodesign Directive and Machinery Directive CE marking creates the primary spread between premium and commodity tiers, with notified body intervention adding four to eight months to compliance timelines that filter non-EU origin equipment from public tenders. Three-tier pricing structure across premium Ecodesign-compliant, standard efficiency, and economy fixed-speed configurations stratifies procurement channels, with municipal utilities least price-sensitive due to lifecycle energy accounting and agricultural cooperatives most sensitive to upfront capital outlay. Pricing pressure stems from permanent magnet motor cost volatility as neodymium processing concentration in Chinese facilities exposes European assemblers to input cost swings.
Supply Chain Analysis
Strait of Hormuz transit risk for petrochemical feedstocks and Chinese rare earth export licensing chokepoints expose permanent magnet motor production to geopolitical disruption. Supply concentration clusters in Poland and Czechia for ductile iron castings, Germany for precision-machined pump components, and China for neodymium magnet processing. Raw material dependencies rest on copper winding stock, rare earth permanent magnets, and specialized bearing alloys. Single-source vulnerability in Eastern European foundry parks threatens mid-tier manufacturers without qualified secondary metallurgical sources. Distribution runs through industrial distributor networks serving municipal and industrial accounts, with direct specification relationships dominating OEM integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in digital service layers and hydrogen electrolyzer specification channels as efficiency mandates and emerging energy infrastructure create niches outside incumbent integrated system suppliers.
For Market Incumbents: Fortify captive power electronics capabilities against recruitment competition from automotive and renewable energy sectors for embedded systems talent. Deepen backward integration into permanent magnet motor production to insulate margin structures from Chinese neodymium processing volatility. Prioritize framework agreement renewals with French and British water utilities tendering energy performance guarantees. For New Entrants and Emerging Players: CE marking fast-track services for non-EU origin equipment create immediate service revenue potential before hardware market entry. Target solar-hybrid agricultural retrofits in Northern Italy's Po Valley where river basin management plans restrict diesel abstraction and subsidy structures compress payback periods. Lead with predictive maintenance software partnerships rather than capital equipment sales to bypass incumbent distributor lock-in. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with power electronics calibration expertise and established hydrogen electrolyzer OEM relationships. Long-term viability hinges on digital twin platform deployment and recurring service revenue attachment rates rather than transactional hardware margins. Watch F-Gas Regulation phase-down acceleration as signal for R744-compatible equipment qualification urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Insulates European assemblers from Chinese neodymium export restriction risks. |
| Digital Pump Twin Platform Launch | Shifts revenue from hardware sales to predictive maintenance contracts with industrial processors. |
| Hydrogen Electrolyzer OEM Partnership | Opens specification channels for high-pressure canned motor pumps in Dutch and German clusters. |
| CE Marking Fast-Track Service Development | Captures service revenue from non-EU manufacturers facing Machinery Directive compliance delays. |
| Solar-Hybrid Agricultural System Certification | Qualifies equipment for Italian and French subsidy programs restricting diesel abstraction. |
Research Methodology
A standing panel of municipal utility procurement directors, industrial maintenance managers, OEM specification engineers, and aftermarket service heads provided ongoing calibration against primary field interviews conducted across German, French, Italian, and Dutch pump installations. Secondary validation drew from EU Ecodesign Directive transposition documents, KBA and ANSM enforcement notices, F-Gas Regulation phase-down schedules, and customs trade data for ductile iron and rare earth magnet flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, application, end user, and technology segmentation dimensions. CAGRs were derived from installed base retirement curves and replacement demand modeling under efficiency mandate compliance timelines. Forecast inputs incorporated hydrogen electrolyzer capacity buildout trajectories in the Netherlands and German clusters, plus river basin management plan enforcement intensity in Italian agricultural districts.
Decision-makers should treat outputs as directional under assumptions of stable EU regulatory enforcement and continued Chinese rare earth export availability; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation phase-down schedules and hydrogen infrastructure subsidy allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Industrial Aerators Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Global Reciprocating Pumps Market
Pumps and Control Devices
Multistage Pump Market
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Global Hydrocyclone Market