
 Plate Heat Exchanger Market | 2026-2036
Plate Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Plate Heat Exchanger Market Outlook
Aftermarket service revenue is tilting toward gasket replacement and plate refurbishment as installed bases mature across Western Europe. ALFA LAVAL leverages its extensive service network to capture recurring maintenance spend. Danfoss anchors its position through backward integration into refrigerant system controls. Kelvion Holding specializes in hygienic designs that command premium positioning within dairy and brewery applications.
A plate heat exchanger consists of a series of corrugated metal plates sealed by gaskets or brazing, with fluids flowing in alternating channels to achieve thermal transfer coefficients significantly higher than shell-and-tube alternatives. The corrugation pattern, typically chevron or herringbone geometry, creates turbulent flow at low Reynolds numbers, enabling compact footprints for duties in pasteurization, district heating, and chemical reaction temperature control. Gasketed configurations retain the largest installed base due to serviceability, though welded and semi-welded variants are gaining traction in aggressive process streams where elastomer degradation poses operational risk. Brazed plate heat exchangers dominate residential and light commercial HVAC segments where first cost sensitivity and hermetic integrity outweigh maintenance access requirements.
ASME Boiler and Pressure Vessel Code, PED 2014/68/EU, and ISO 15547 standards govern design, fabrication, and inspection protocols, with compliance serving as a non-negotiable market access filter for suppliers targeting regulated industries. EPA refrigerant management rules and the EU F-Gas Regulation are indirectly stimulating demand by accelerating HVAC system replacements that bundle higher-efficiency heat exchangers. Stakeholders must monitor evolving material specifications for hydrogen-compatible nickel alloys as energy transition projects advance thermal management requirements.
Market Dynamics
The EU F-Gas Regulation and ASME Boiler and Pressure Vessel Code are compressing replacement cycles for legacy thermal equipment while tightening compliance filters on new installations.
Growth Catalysts
- HVAC Retrofit Mandates:The EU Green Deal's efficiency targets are forcing commercial building operators across Germany and France to replace shell-and-tube units with compact plate configurations.
- Process Modernization:Dairy and brewery applications in Denmark and the Netherlands are specifying hygienic plate designs that reduce pasteurization energy intensity.
- Hydrogen Infrastructure:Nickel alloy specifications for thermal management in electrolyzer and fuel cell systems are creating specification pull from energy transition project developers.
Market Restraints
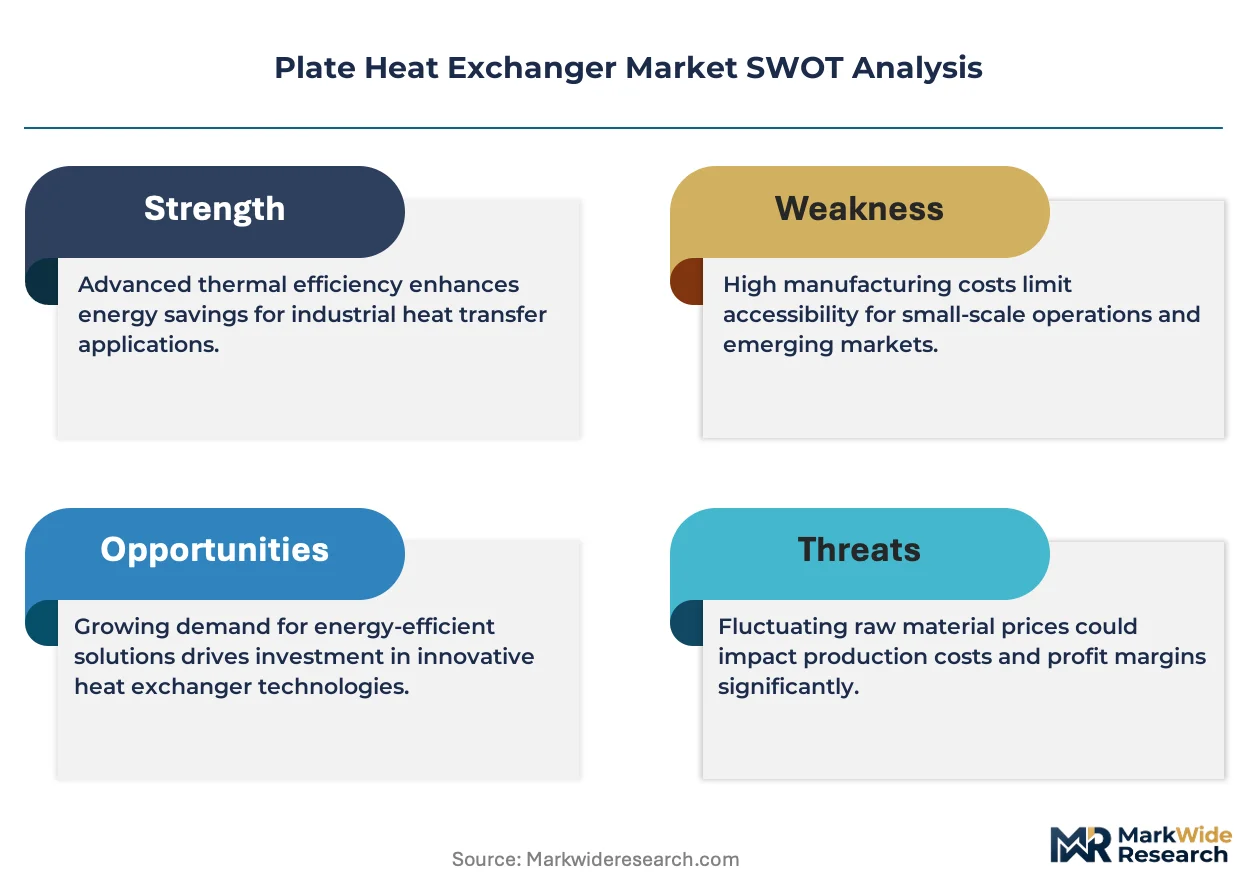
- Stainless Steel Volatility:Plate fabrication costs fluctuate with nickel and molybdenum commodity pricing, compressing margin predictability for OEMs.
- Elastomer Supply Concentration:Specialized gasket polymers for aggressive chemical streams depend on a limited supplier base concentrated in Western Europe.
- Welded Unit Limitations:Permanent brazed and welded configurations cannot accommodate future capacity expansion, constraining adoption in scaling process plants.
Strategic Opportunities
- Aftermarket Service Expansion:Gasket replacement and plate refurbishment contracts for mature installed bases in Sweden and Belgium generate recurring revenue streams.
- Semi-Welded Hybrids:Configurations combining serviceable gaskets with welded process-side seals address aggressive fluids in chemical processing applications.
- Digital Thermal Monitoring:Integration of IoT sensors with heat exchanger fleets enables predictive maintenance contracts in district heating networks.
Industry Challenges
- Certification Timeline Compression:PED 2014/68/EU and ASME code compliance documentation requirements extend project approval cycles, straining engineering resources.
- Legacy System Integration:Retrofit projects in older industrial facilities face piping configuration mismatches that demand custom engineering for plate heat exchanger installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plate Heat Exchanger Market |
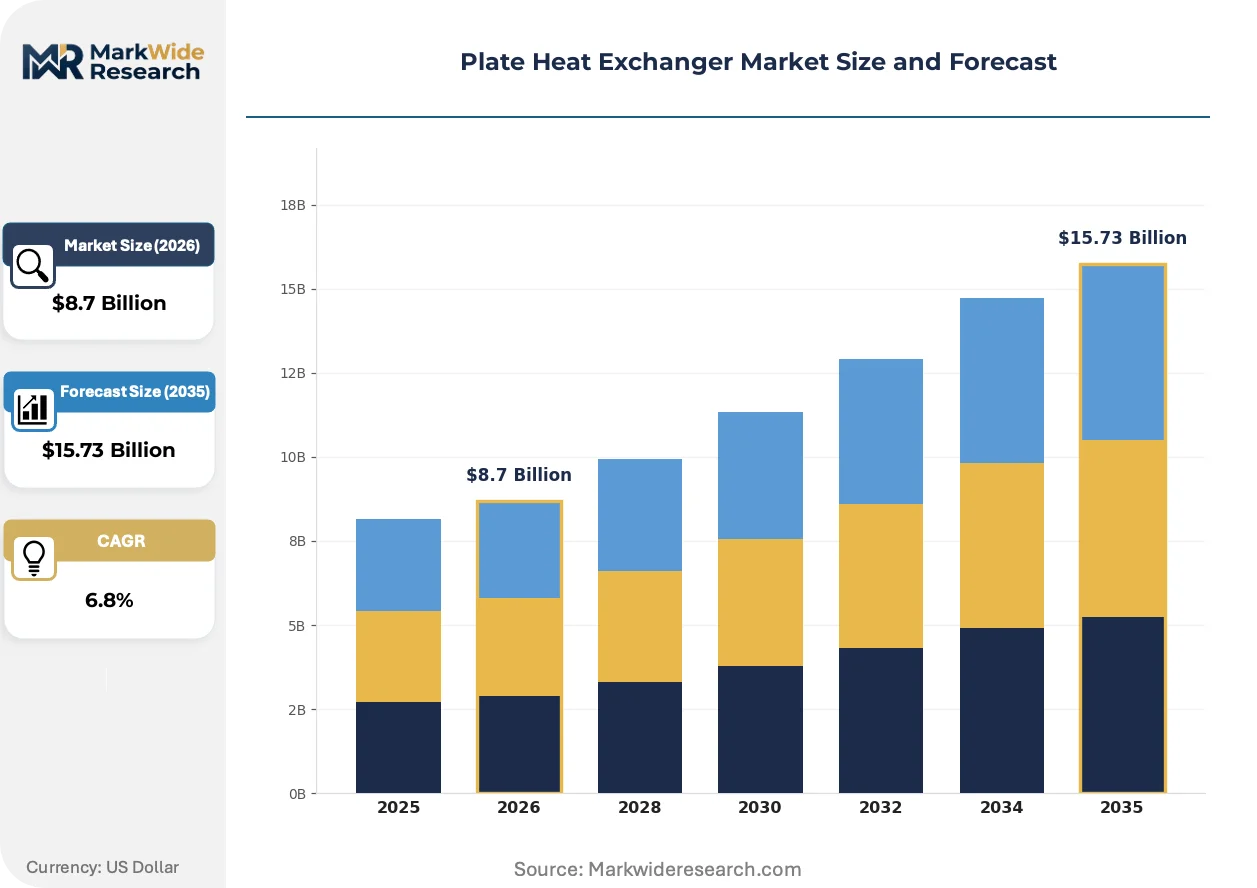
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasketed, Welded, Brazed, Semi-Welded Application: Food & Beverage, HVAC, Chemical Processing, Pharmaceutical End User: Manufacturing, Oil & Gas, Energy, Marine Material: Stainless Steel, Titanium, Nickel Alloy, Carbon Steel |
| Companies Covered | ALFA LAVAL, Danfoss, Kelvion Holding, Xylem, HISAKA WORKS, SPX FLOW, API Heat Transfer, SWEP International, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plate Heat Exchanger Market Strategic Shifts
Corrugation geometry optimization, material science advances, and service model unbundling are restructuring how thermal transfer equipment is specified, procured, and maintained across process industries.
Additive manufacturing of complex channel geometries is rendering obsolete traditional stamping limitations on plate surface area density. Chemical processors in the Netherlands are piloting topology-optimized plates that achieve turbulent flow at 40% lower pressure drop. This manufacturing freedom is compressing the performance gap between compact plate units and larger shell-and-tube alternatives in high-duty applications.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbon refrigerants is accelerating HVAC system replacements that bundle higher-efficiency heat exchangers. Equipment specifiers in Germany now face compliance deadlines that favor plate configurations with lower refrigerant charge requirements. Residential and light commercial segments are responding by specifying hermetic brazed units that minimize leakage risk.
Service unbundling is separating hardware procurement from long-term maintenance obligations in municipal district heating contracts. Finnish and Danish utilities now negotiate plate refurbishment and gasket replacement as standalone performance agreements rather than bundled capital purchases. This shift concentrates aftermarket revenue with OEMs possessing established service networks across Nordic urban heating infrastructure.
Plate Heat Exchanger Market Segmentation
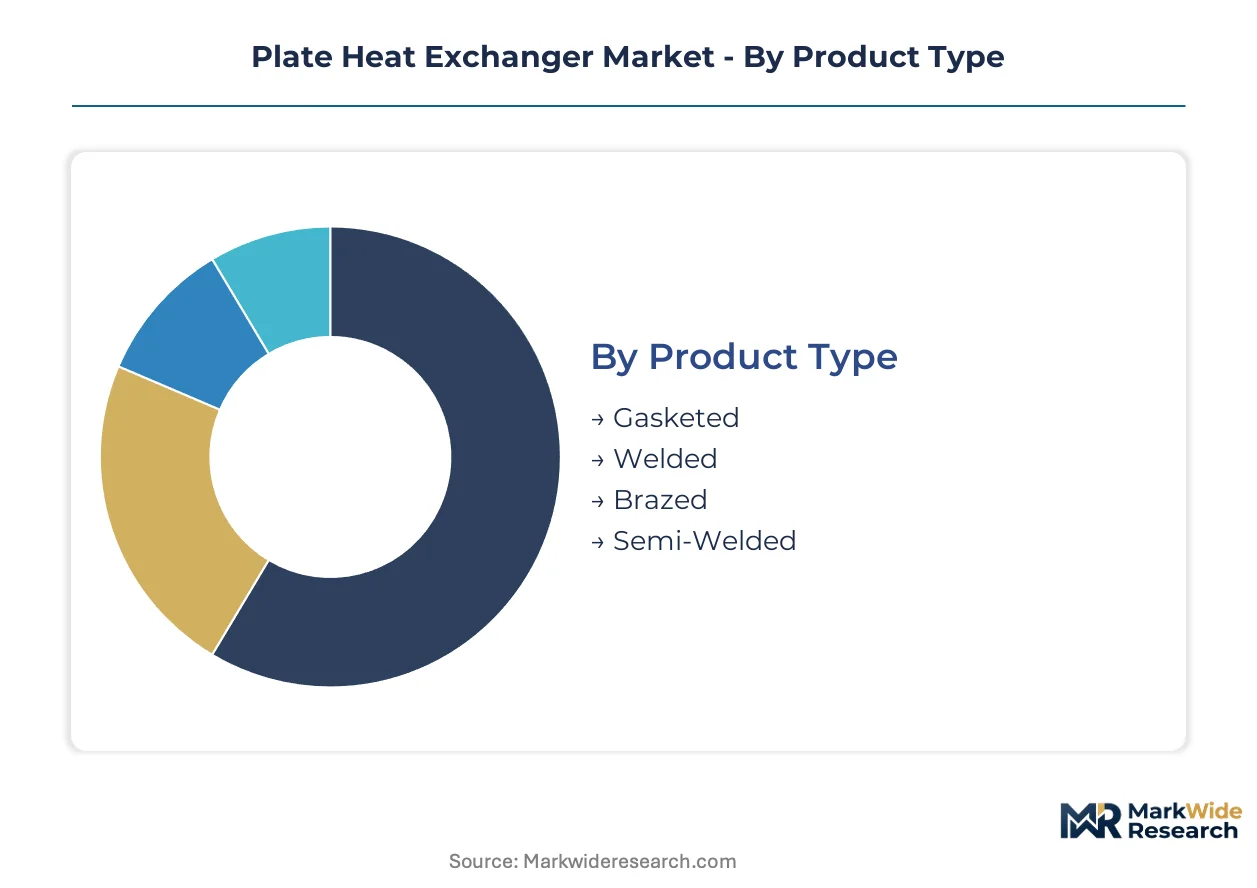
Plate heat exchanger procurement patterns diverge sharply across technical configurations and end-use environments. Specification engineers weight serviceability against hermetic integrity depending on process criticality and fluid aggressiveness.
Product Type:
Gasketed units cycle through refurbishment every 3-5 years while brazed configurations operate 15-20 years without maintenance access. Replacement velocity therefore concentrates in mechanically sealed designs.
- Gasketed:Corrugated plates clamped between frames with elastomer seals permit individual plate replacement and chemical cleaning. Dairy processors across Denmark and the Netherlands specify these for pasteurization duties where hygiene protocols demand frequent disassembly.
- Brazed:Copper- or nickel-brazed plate stacks create hermetic assemblies with no gasket degradation risk. Residential heat pump installers in Germany favor these for compact footprints and minimal refrigerant charge requirements under EU F-Gas Regulation limits.
- Welded:Laser-welded plate pairs eliminate elastomer exposure in aggressive chemical streams. Petrochemical operators specify these for sulfuric acid cooling where gasket materials would fail.
- Semi-Welded:Hybrid designs weld the process fluid side while retaining gasketed service access on the utility side. Chemical processors in Belgium deploy these for chlorine-handling duties requiring both corrosion resistance and maintenance flexibility.
Gasketed configurations dominate installed base. Brazed designs are where expansion concentrates.
Application:
Cost tiers separate standardized HVAC specifications from validated pharmaceutical installations demanding extensive documentation packages.
- HVAC:District heating networks and commercial building climate systems prioritize thermal efficiency per unit volume. Swedish municipal utilities specify compact plate units for urban heat distribution where space constraints exclude shell-and-tube alternatives.
- Food & Beverage:Hygienic plate designs with polished surfaces and crevice-free channels meet 3-A Sanitary Standards for dairy pasteurization. Brewery operators across the Czech Republic and Poland specify these for wort cooling and fermentation temperature control.
- Chemical Processing:Aggressive media handling requires material upgrades and specialized gasket polymers. Chlor-alkali producers in Germany specify nickel alloy plates for brine heating circuits.
- Pharmaceutical:ASME-BPE compliance and full material traceability drive specification requirements. Injectable drug manufacturers in Switzerland specify validated plate heat exchangers for WFI generation and SIP cycles.
HVAC commands volume leadership. Pharmaceutical applications carry the steepest margin expansion trajectory.
End User:
Customer procurement sophistication ranges from standardized catalog selection in manufacturing to engineered-to-order specifications in offshore marine.
- Manufacturing:Process plants across automotive painting and metal finishing specify plate heat exchangers for closed-loop cooling tower circuits. Paint booth operators in Spain prioritize compact footprints for integration into existing facility layouts.
- Oil & Gas:Upstream separation and downstream refining applications demand high-pressure ratings and sour service compatibility. North Sea platform operators specify welded configurations for produced water heating.
- Energy:Combined cycle power plants and nuclear facilities require seismic qualification and ASME Section III compliance. French EPR reactor projects specify titanium-plated designs for auxiliary cooling systems.
- Marine:Space-weight constraints and classification society rules govern specification. Cruise ship builders in Italy specify brazed units for freshwater generator and HVAC duties where machinery room volume is severely constrained.
Manufacturing absorbs the highest unit volume. Marine specifications are climbing fastest on newbuild activity.
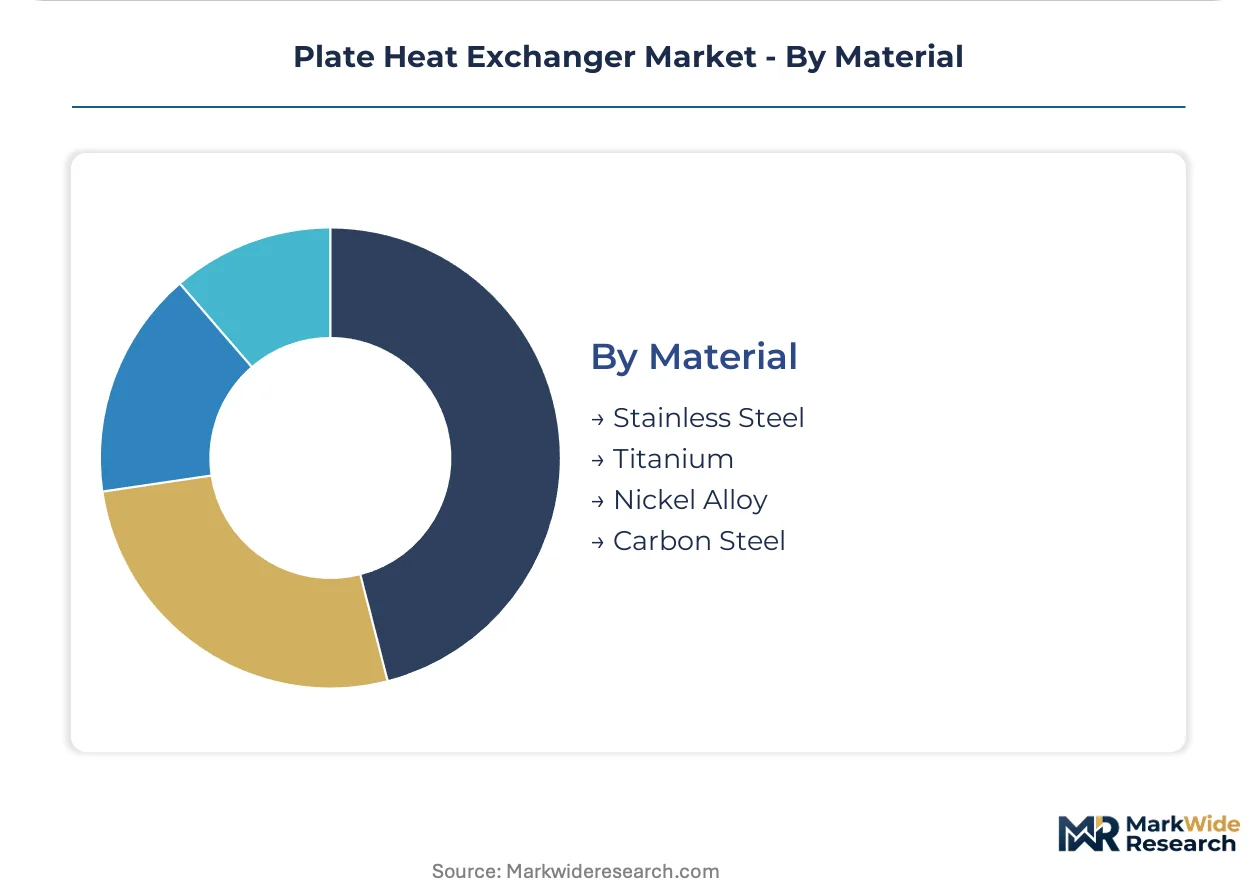
Material:
Supply concentration for specialty alloys creates procurement risk that stainless steel specifications avoid.
- Stainless Steel:Austenitic grades 304 and 316 dominate general service applications where chloride exposure remains moderate. Brewery and dairy specifications across Austria and Germany standardize on 316L for food contact surfaces.
- Titanium:Seawater resistance and immunity to chloride stress corrosion cracking justify premium pricing. Desalination plant operators in the Middle East specify titanium-plated units for brine heating and condenser duties.
- Nickel Alloy:C-276 and Alloy 625 specifications handle sulfuric acid and hydrofluoric acid streams in chemical processing. Hydrogen electrolyzer projects in the Netherlands specify these for high-temperature thermal management in alkaline and PEM cell stacks.
- Carbon Steel:Cost-sensitive HVAC and utility water applications where corrosion allowance permits reduced material specification. Polish district heating networks deploy carbon steel plates for secondary return circuits with chemical treatment programs.
Stainless steel dominates installed base. Nickel alloy specifications are where technology transition concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plate heat exchanger fabrication clusters in Germany's industrial corridor, with component supply chains radiating through the Netherlands and Belgium. Demand patterns diverge between mature European retrofit markets and emerging Asian manufacturing bases.
Germany
The EU F-Gas Regulation's refrigerant phase-down deadlines are compressing HVAC replacement cycles across commercial building stock. Industrial process operators in North Rhine-Westphalia specify semi-welded configurations for chemical handling duties. The Ruhr Valley's district heating utilities are modernizing thermal substations with compact plate units.
United States
EPA refrigerant management rules are accelerating bundled heat exchanger replacements in supermarket refrigeration systems. ASME Boiler and Pressure Vessel Code compliance filters govern specification for regulated industries. Gulf Coast petrochemical clusters in Texas deploy welded plate designs for sour service cooling circuits.
China
Dual carbon goals under MIIT industrial efficiency mandates are stimulating demand in steel and cement process heat recovery. GB standards for pressure equipment govern local fabrication quality tiers. Yangtze River Delta HVAC manufacturers are scaling brazed plate production for residential heat pump exports.
Japan
METI energy efficiency benchmarks for commercial buildings are tightening thermal performance requirements. JIS standards certification creates non-negotiable procurement filters for domestic projects. Osaka-Kobe industrial corridor process plants specify titanium-plated units for seawater cooling applications.
India
CEA thermal efficiency mandates for power plants are driving auxiliary cooling system upgrades. BIS pressure vessel standards are gradually harmonizing with ISO protocols for import substitution. Gujarat's chemical processing belt is specifying nickel alloy plates for aggressive acid handling duties.
Plate Heat Exchanger Market Competitive Environment
Full-line thermal equipment multinationals and specialized compact heat exchanger fabricators split the market across distinct specification tiers. Consolidation pressure concentrates among mid-scale European suppliers facing raw material volatility. Three archetypes dominate: integrated thermal system houses with refrigerant controls portfolios, standalone plate heat exchanger specialists with deep aftermarket networks, and diversified process equipment conglomerates with cross-selling capabilities. Competitive moves center on backward integration into specialty alloy supply and geographic expansion through local fabrication licensing.
Among Nordic-origin specialists, ALFA LAVAL and SWEP International occupy positions emphasizing service network density and hermetic brazed configurations respectively. Danfoss anchors the integrated system house archetype through captive controls technology. These three exemplify divergent strategic postures: pure-play heat transfer focus versus thermal ecosystem bundling versus refrigerant circuit integration.
| Leading Market Players |
|---|
| ALFA LAVAL |
| Danfoss |
| Kelvion Holding |
| Xylem |
| HISAKA WORKS |
| SPX FLOW |
| API Heat Transfer |
| SWEP International |
| GEA Group |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's brazed plate fabrication sector is compressing export pricing while forcing European OEMs toward service revenue models that buffer margin erosion. German and Italian producers respond by anchoring premium positioning to PED 2014/68/EU certification tiers and aftermarket bundling rather than hardware margins alone.
Pricing Analysis
Aftermarket service contracts for gasket replacement and plate refurbishment generate lifetime value multiples exceeding original equipment sales. Pricing stratifies across premium, standard, and economy tiers where ASME-certified pharmaceutical units command substantial premiums over carbon steel HVAC specifications. Cost compression in brazed residential heat pumps is intensifying because Yangtze River Delta manufacturers are scaling export volume. Manufacturing plant engineers exhibit highest price sensitivity while pharmaceutical validation teams prioritize compliance documentation over unit cost.
Supply Chain Analysis
Export control restrictions on nickel alloy metallurgy and advanced welding equipment limit technology transfer to emerging fabrication hubs. Plate stamping and brazing operations concentrate in Germany, China, and Japan while specialty gasket polymers draw from a limited Western European supplier base. Single-source vulnerability for C-276 and Alloy 625 nickel alloys creates procurement risk for hydrogen electrolyzer projects. Distribution runs through OEM direct sales for large process installations and specialized HVAC wholesalers for standardized brazed units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as energy transition projects splinter demand across hydrogen-compatible nickel alloys, district heating retrofits, and pharmaceutical validation tiers that resist commoditization.
For Market Incumbents: Harden aftermarket network density in Nordic district heating corridors where municipal utilities are unbundling service contracts from capital purchases. Deepen backward integration into specialty alloy supply chains to offset nickel and molybdenum volatility compressing fabrication margins. Capture recurring revenue through predictive maintenance platforms integrating IoT thermal monitoring. For New Entrants and Emerging Players: Build out semi-welded hybrid configurations for Belgian and Dutch chemical processors handling chlorine and sulfuric acid streams where incumbent welded designs lack service flexibility. Target India's Gujarat chemical belt where CEA efficiency mandates are accelerating auxiliary cooling upgrades ahead of local fabrication capacity. Establish specification relationships through engineering consultancy partnerships rather than direct OEM competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across brazed plate residential HVAC as Chinese manufacturers achieve scale economies that compress Western asset turns. Acquire European mid-scale specialists possessing PED-certified fabrication assets and established pharmaceutical validation documentation libraries. Monitor nickel alloy spot price spreads as inflection indicator for margin compression timing in process equipment tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Supply | Captive sourcing of C-276 and Alloy 625 insulates margins from commodity volatility in hydrogen electrolyzer specifications. |
| Aftermarket Service Network Expansion | Gasket refurbishment contracts in Swedish district heating generate recurring revenue streams detached from capital cycle timing. |
| Semi-Welded Product Line Development | Hybrid configurations address Belgian chemical processors demanding both corrosion resistance and maintenance access. |
| Digital Thermal Monitoring Integration | IoT sensor deployment enables predictive maintenance contracts with Finnish municipal heating utilities. |
| Pharmaceutical Validation Documentation Investment | ASME-BPE compliance packages differentiate premium positioning for Swiss injectable drug manufacturers. |
Study Parameters
A spread of perspectives from plant maintenance directors, OEM procurement teams, aftermarket service heads, and HVAC specification engineers converged on the working assumptions driving this analysis. Primary fieldwork across Germany's industrial corridor, the Netherlands' chemical processing belt, and Nordic district heating utilities combined with secondary validation from SEC filings of listed thermal equipment manufacturers, PED 2014/68/EU notified body registers, and MIIT industrial efficiency disclosure databases. Bottom-up unit economics triangulated against top-down sector spend estimates anchored the projection framework.
Demand-supply balance modeling across the projection horizon incorporated capacity utilization signals from German and Chinese fabrication clusters, segmented by gasketed, brazed, welded, and semi-welded product configurations alongside material tiers from carbon steel through nickel alloy. CAGRs derived from replacement cycle compression under EU F-Gas Regulation deadlines and hydrogen infrastructure capital deployment curves. Industry-specific forecast inputs included district heating network modernization pipelines and pharmaceutical capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese brazed plate exporters or nickel alloy mining consortiums would shift outcomes. Material shifts in EU F-Gas Regulation enforcement timelines or hydrogen electrolyzer deployment scale would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Single-Stage Centrifugal Pumps Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
Seawater Pump Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Electric Oil Pump Market