

Cooling Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Pump Market Insights
Market Context
The capital-intensity divergence between integrated pump manufacturers and assembly-dependent competitors is collapsing as energy-efficiency mandates and smart-monitoring requirements raise minimum viable scale. Grundfos leverages its in-house electronics division to bundle variable-speed drives with centrifugal units, commanding premium positioning in data center contracts. Xylem sustains geographic dominance through decentralized service networks that reduce downtime liability for power generation clients. KSB differentiates via foundry-to-finish vertical integration that insulates margin pools from raw material volatility.
Technical Definition and Segments
A cooling pump is a fluid-handling device engineered to circulate coolants—water, glycol solutions, or synthetic refrigerants—through heat exchangers, chillers, or process loops at specified flow rates and head pressures, typically constructed from cast iron, stainless steel, or polymer composites to resist corrosion and thermal cycling. Centrifugal pumps occupy the largest volume share due to their suitability for high-flow, moderate-head HVAC and power generation applications, while magnetic drive technology captures expanding share in chemical processing and pharmaceutical production where seal leakage poses contamination risk. Positive displacement configurations anchor margin pools in semiconductor manufacturing, where precision flow control protects wafer yield during etching and deposition thermal management.
Regulatory Outlook
The EU F-Gas Regulation and REACH chemical restrictions are reshaping material specifications and refrigerant compatibility requirements for pumps sold into European HVAC and industrial cooling systems. The US Department of Energy pump efficiency standards and China's GB energy-labeling program are converging to penalize fixed-speed, single-stage designs while rewarding integrated variable-frequency drive architectures. Stakeholders must monitor how regional efficiency certification timelines and carbon-border adjustment mechanisms reshape sourcing decisions for multinational facility operators.
Market Dynamics
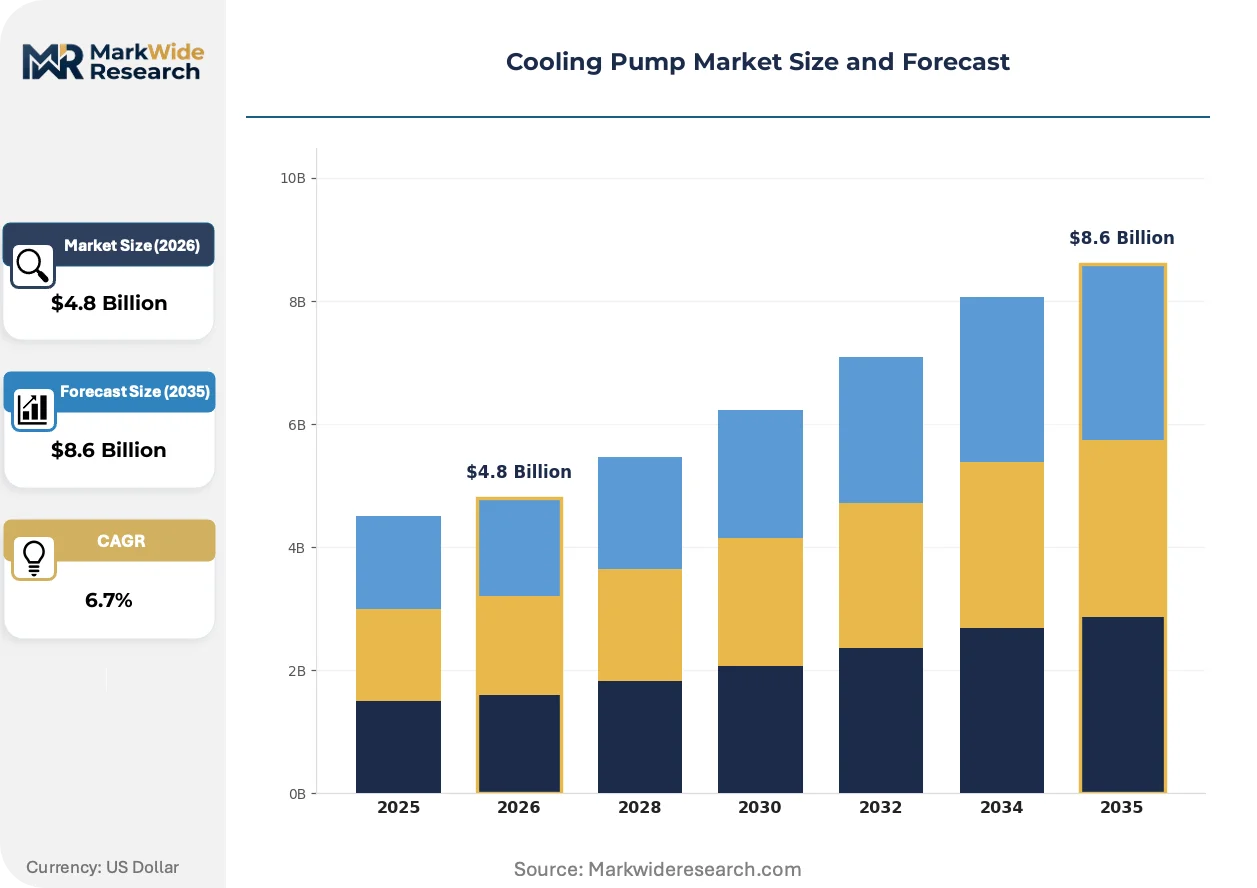
AI-driven thermal loads in hyperscale data centers are compressing procurement cycles for high-pressure liquid cooling pumps, forcing manufacturers to abandon standardized catalog offerings in favor of application-engineered systems with embedded IoT diagnostics.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants under the EU F-Gas Regulation is compelling HVAC contractors to replace legacy pump-refrigerant pairings with compatible low-GWP alternatives, expanding retrofit volumes.
- Hyperscale data center construction:Facility operators in China are specifying magnetic-drive centrifugal pumps for direct-to-chip cooling loops, creating concentrated demand for corrosion-resistant stainless steel configurations.
- Semiconductor etching thermal management:Precision positive-displacement pumps are becoming essential for wafer yield protection in advanced node manufacturing, locking in long-term supply agreements with foundry operators.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and samarium-cobalt sourcing dependence on Chinese processing facilities exposes magnetic-drive pump manufacturers to export quota volatility and price spikes.
- Stainless steel alloy cost inflation:Nickel and molybdenum price swings in commodity markets compress margin pools for foundry-integrated producers serving chemical processing end-uses.
- Seal material incompatibility:Existing elastomer formulations face premature degradation with synthetic refrigerants like R-1234yf, forcing costly qualification cycles for alternative fluoropolymer compounds.
Strategic Opportunities
- India industrial cooling upgrades:The Bureau of Energy Efficiency's Perform Achieve Trade scheme is creating compliance-driven demand for variable-frequency drive pumps in steel and cement plants.
- Pharmaceutical aseptic processing:Magnetic-drive technology convergence with single-use bioreactor systems is opening white space in biologics manufacturing thermal control applications.
- Digital twin integration:Predictive maintenance algorithms bundled with pump hardware are enabling subscription-based service revenue streams that decouple growth from unit shipment volumes.
Industry Challenges
- Electronics-embedded systems integration:Variable-speed drive programming and IoT sensor calibration require software engineering competencies that traditional mechanical pump manufacturers lack in-house.
- Multi-jurisdictional efficiency certification:Concurrent compliance with US DOE pump standards, China's GB labeling, and EU ecodesign directives stretches engineering resources and delays product launches.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Pump Market Trends and Innovations
Electrification of thermal management architectures is collapsing the boundary between mechanical pumping hardware and power electronics, forcing component suppliers to reorganize around integrated system competencies rather than discrete product lines.
Magnetic levitation bearing technology is miniaturizing. The elimination of mechanical contact surfaces enables maintenance-free operation across 50,000+ hour lifecycles. Data center operators in Singapore and the Netherlands are specifying mag-lev pumps for mission-critical cooling loops where downtime costs exceed hardware replacement values. This technology is miniaturizing footprint requirements for high-head applications, enabling rack-mounted configurations that displace centralized chiller plants.
China's GB energy efficiency labeling program is tightening minimum performance coefficients for centrifugal pumps sold into commercial building HVAC systems. The regulation's tiered rating structure is penalizing fixed-speed designs while accelerating variable-frequency drive penetration. Domestic manufacturers are responding by integrating in-house electronics capabilities that foreign competitors must source through third-party partnerships.
Power generation utilities are unbundling aftermarket service contracts from initial equipment procurement, treating pump maintenance as a distinct spend category with separate vendor qualification. Independent service providers are capturing lubrication system overhaul and impeller refurbishment work that OEMs previously monopolized. This disintermediation is most pronounced in combined-cycle gas turbine installations across the US Gulf Coast and Middle East desalination complexes.
Cooling Pump Market Segmentation
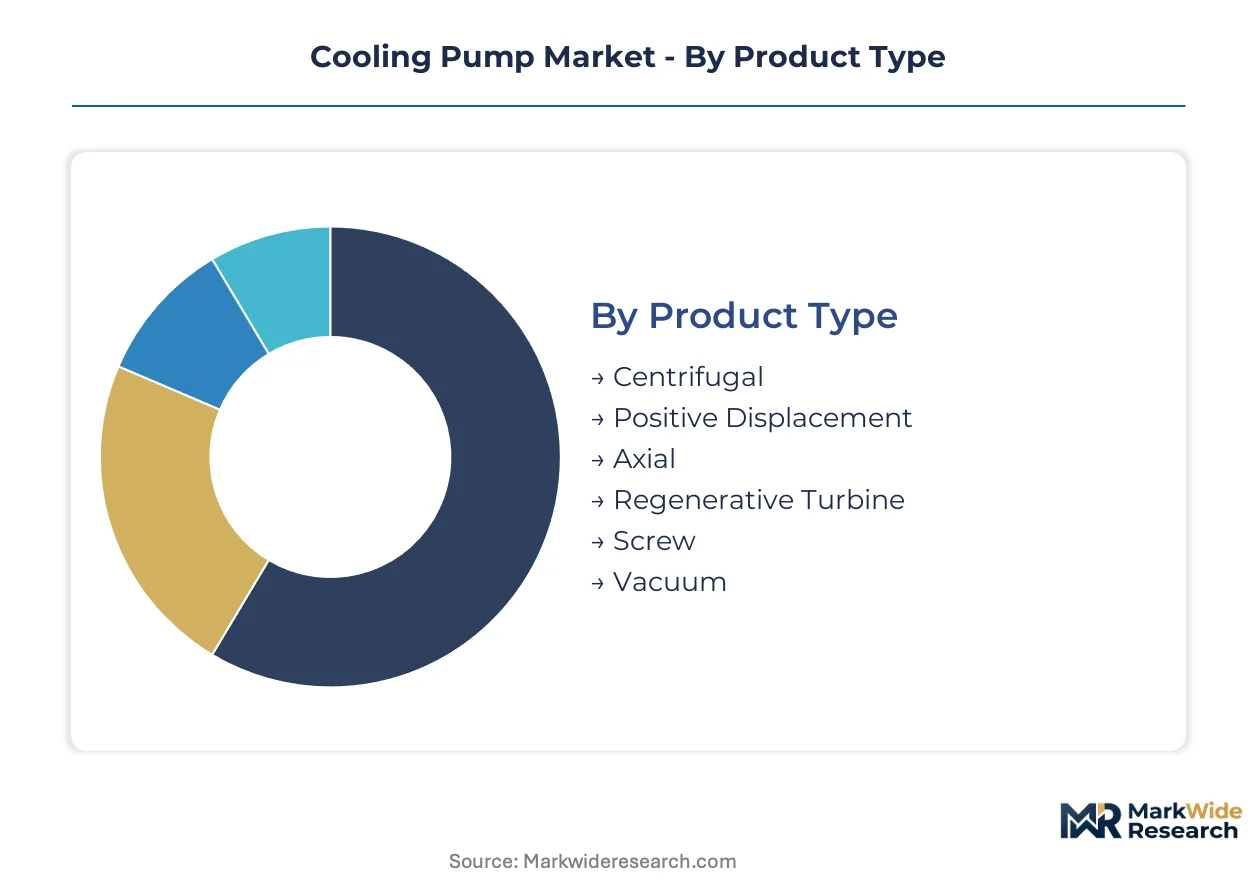
Segmentation in the cooling pump market reveals where procurement power concentrates and which technical specifications command premium pricing. Manufacturers configure product portfolios around these divisions to defend margin pools against commoditization pressures.
Product Type:
Margin pools concentrate in configurations that integrate variable-speed electronics and corrosion-resistant alloys, with foundry-integrated producers capturing value that assembly-dependent competitors cannot replicate.
- Centrifugal:These pumps dominate high-flow, moderate-head applications through radial impeller designs cast in stainless steel or bronze alloys. Demand clusters in hyperscale data centers across China and the US, where facility operators specify magnetic-drive variants to eliminate seal leakage risks in direct-to-chip cooling loops.
- Positive Displacement:Precision metering capabilities protect wafer yields in semiconductor etching and deposition thermal management. Foundry operators in Taiwan and South Korea lock in long-term supply agreements for these units, accepting extended lead times in exchange for flow control tolerances measured in microliters.
- Axial:Propeller-style impellers generate high flow at low head pressures for cooling tower circulation and large-scale HVAC distribution networks.
- Regenerative Turbine:Peripheral flow paths deliver high pressure ratios in compact footprints, suiting boiler feed and pressure-boosting skids where space constraints dominate specification criteria.
- Screw:Intermeshing rotors handle viscous coolants and oil-glycol mixtures in industrial process cooling with minimal pulsation.
- Vacuum:Specialized configurations evacuate and charge refrigeration circuits during HVAC installation and maintenance service calls.
The dominant share belongs to Centrifugal, while Positive Displacement is closing the gap fastest.
Technology:
Procurement patterns split between mission-critical applications demanding hermetic integrity and cost-optimized installations where mechanical simplicity overrides leakage risk tolerance.
- Magnetic Drive:Rare earth magnet couplings transmit torque through containment shells, eliminating shaft seals entirely. Pharmaceutical producers in Switzerland and Germany specify these for aseptic bioprocessing, where single-particle contamination triggers batch discard costs exceeding pump replacement values by orders of magnitude.
- Mechanical Seal:Elastomer-faced rotating seals remain standard for water-glycol HVAC circulation, though refrigerant compatibility testing consumes engineering resources as synthetic alternatives displace legacy hydrofluorocarbons.
- Electric Motor:Integrated permanent magnet synchronous motors with variable-frequency drives now constitute the baseline specification for commercial building codes in China and the European Union.
- Hydraulic:Fluid power actuation persists in explosion-rated chemical processing environments where electrical spark ignition risks mandate intrinsic safety architectures.
- Diaphragm:Reciprocating elastomer membranes isolate pumped fluid from mechanical components, serving abrasive slurry cooling in mining and mineral processing operations.
Magnetic Drive holds the installed base majority, though Electric Motor configurations are expanding most quickly as efficiency mandates penetrate mid-market segments.
Application:
Specification intensity varies sharply across cooling loads, with thermal density per square meter determining whether standardized catalog offerings suffice or application-engineered systems become mandatory.
- HVAC Systems:Chilled water and condenser water circulation accounts for the largest unit volume, with China's GB energy labeling program and the EU Ecodesign Directive jointly penalizing fixed-speed designs. Domestic Chinese manufacturers integrate in-house electronics capabilities that foreign competitors must source through third-party partnerships.
- Data Center Cooling:AI workload thermal densities have compressed procurement cycles from 18 months to 90 days in some hyperscale contracts. Operators in Singapore and the Netherlands specify mag-lev bearing pumps for mission-critical loops where downtime costs exceed hardware replacement values.
- Power Generation:Combined-cycle gas turbine installations across the US Gulf Coast and Middle East desalination complexes drive demand for high-pressure boiler feed and condensate extraction services.
- Chemical Processing:Aggressive coolant chemistries and elevated temperatures mandate alloy selection and seal material qualification cycles that extend lead times.
- Metal Fabrication:Quenching and cutting fluid recirculation pumps face abrasive contamination and thermal shock cycling that accelerates wear component replacement.
- Food Processing:Sanitary design requirements including 3-A certification and FDA-compliant elastomers constrain supplier qualification to specialists with hygienic design competencies.
HVAC Systems maintains volume leadership, though Data Center Cooling exhibits the steepest expansion trajectory as liquid infrastructure displaces air cooling.
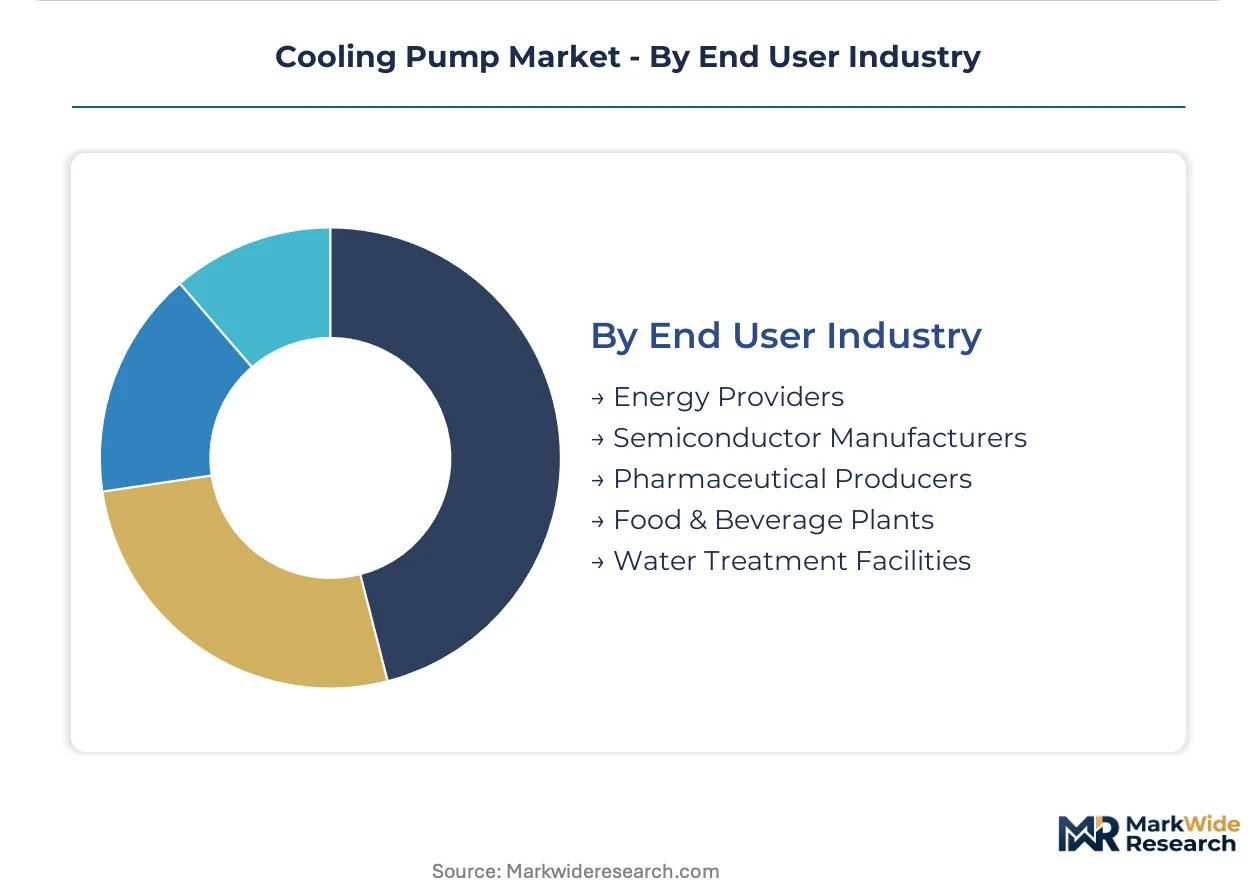
End User Industry:
Customer concentration and technical sophistication determine contract structures, with semiconductor and pharmaceutical sectors demanding embedded diagnostics and predictive maintenance integration that commodity buyers reject.
- Energy Providers:Utility procurement unbundles aftermarket service from initial equipment supply, treating pump maintenance as a distinct spend category with separate vendor qualification protocols.
- Semiconductor Manufacturers:Advanced node foundries in Taiwan, South Korea, and Arizona impose sub-micron particle contamination limits that only magnetic-drive positive displacement configurations satisfy.
- Pharmaceutical Producers:Single-use bioreactor convergence with magnetic-drive technology opens white space in biologics manufacturing thermal control, with Swiss and German facilities leading specification intensity.
- Food & Beverage Plants:Clean-in-place protocols and allergen segregation requirements drive demand for quick-disconnect configurations and electropolished wetted surfaces.
- Water Treatment Facilities:Municipal and industrial desalination operators in Saudi Arabia and the UAE specify corrosion-resistant materials for seawater intake and brine discharge services.
Energy Providers represent the largest installed base, while Semiconductor Manufacturers are gaining share fastest as thermal management intensity climbs with each process node shrink.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in cooling pumps tilt toward surplus production in Germany, Denmark, and Japan against deficit absorption in China, India, and the UAE. Manufacturing scale advantages in precision casting and permanent magnet processing concentrate supply capability, while infrastructure buildouts and data center construction in import-dependent markets sustain demand asymmetry.
China
Hyperscale facility construction in Beijing, Shanghai, and the Yangtze River Delta consumes magnetic-drive centrifugal units for direct-to-chip cooling loops. The GB energy efficiency labeling program tightens minimum performance coefficients, penalizing fixed-speed designs and accelerating domestic variable-frequency drive integration. Facility operators in Shenzhen and Hangzhou specify corrosion-resistant stainless steel configurations for AI workload thermal management.
United States
Combined-cycle gas turbine installations across Texas and Louisiana drive demand for high-pressure boiler feed services, while hyperscale data centers in Northern Virginia and Phoenix compress procurement cycles to 90-day windows. The Department of Energy pump efficiency standards penalize single-stage fixed-speed architectures, rewarding integrated VFD systems. Independent service providers capture lubrication overhaul work that OEMs previously monopolized in Gulf Coast power generation clusters.
Germany
Pharmaceutical producers in Basel-adjacent Baden-Württemberg and Swiss-border regions specify magnetic-drive pumps for aseptic bioprocessing, where single-particle contamination triggers batch discard costs exceeding hardware replacement values. The EU F-Gas Regulation compels HVAC contractors to replace legacy pump-refrigerant pairings with low-GWP compatible alternatives. Foundry-integrated manufacturers in North Rhine-Westphalia leverage captive stainless steel casting to insulate margins from nickel price volatility.
India
Steel and cement plants in Maharashtra, Gujarat, and Karnataka face compliance pressure under the Bureau of Energy Efficiency's Perform Achieve Trade scheme, creating retrofit demand for variable-frequency drive pumps. The country's national energy regulator enforces consumption benchmarks that penalize fixed-speed installations in designated industrial sectors. Cooling system upgrades concentrate in the Mumbai-Pune industrial corridor and the Delhi-Mumbai Industrial Corridor nodes.
Singapore
Data center operators specify mag-lev bearing pumps for mission-critical cooling loops where downtime costs exceed hardware replacement values, driven by tropical thermal loads and land-constrained facility designs. The national environmental agency enforces stringent efficiency standards for commercial building HVAC systems that accelerate premium pump specification. Digital infrastructure investment clusters in Changi and Tuas anchor demand for maintenance-free 50,000-hour lifecycle configurations.
Cooling Pump Market Competitive Landscape
Concentration sits with foundry-integrated European and Japanese manufacturers that control upstream casting and magnet processing capabilities. Three tiers structure procurement: premium application-engineered systems for semiconductor and pharmaceutical thermal management; mid-market configurable platforms for data center and power generation contracts; and price-optimized catalog units for commercial HVAC replacement cycles. Dominant competitive moves include backward integration into permanent magnet sourcing and electronics-embedded system bundling that captures service contract attachment.
Among Danish and German pump specialists, Grundfos, Xylem, and KSB occupy positions exemplifying the foundry-to-finish integration archetype. Grundfos leverages in-house electronics division capabilities to bundle variable-speed drives with centrifugal units. Xylem sustains geographic coverage through decentralized service networks that reduce downtime liability. KSB anchors margin pools via captive stainless steel foundry operations that buffer raw material price swings. These manufacturers represent the premium tier where application engineering and predictive maintenance integration command contract structures unavailable to assembly-dependent competitors.
| Leading Market Players |
|---|
| Grundfos |
| Xylem |
| Sulzer |
| Flowserve |
| KSB |
| Wilo |
| EBARA |
| Kirloskar Brothers |
| Torishima Pump |
| Others |
Pricing and Supply Chain Analysis
Twenty-six-week lead times for rare earth magnet procurement concentrate pricing power among foundry-integrated manufacturers in Germany and Denmark, while assembly-dependent competitors absorb margin compression from nickel and molybdenum volatility. This inventory-to-pricing dynamic rewards backward integration into permanent magnet sourcing and captive stainless steel casting.
Pricing Analysis
Configured-to-order pricing for application-engineered magnetic-drive systems commands spreads exceeding standard catalog centrifugal units by factors tied to corrosion-resistant alloy grades and embedded IoT diagnostics. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier—CE-marked efficiency grades versus baseline fixed-speed architectures—and by after-sales service bundling. Cost compression in mid-market HVAC segments intensifies because Chinese domestic manufacturers integrate in-house variable-frequency drive electronics that foreign competitors source externally. Data center operators exhibit least price sensitivity, accepting extended lead times for mag-lev bearing configurations where downtime costs dominate total cost of ownership calculations.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for magnetic-drive pump components sourced from Chinese rare earth processing facilities. Supply concentrates in Germany, Denmark, and Japan for precision casting and permanent magnet fabrication, while China dominates neodymium and samarium-cobalt refining. Raw material dependencies rest on nickel-molybdenum stainless steel alloys, fluoropolymer seal compounds, and rare earth magnet powders. Single-source vulnerability in Chinese magnet processing exposes manufacturers to export quota volatility. Distribution runs through OEM-direct channels for large power generation and semiconductor contracts, with independent service providers capturing aftermarket refurbishment in unbundled utility procurement structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions and digital twin integration represent the fastest-expanding revenue layer in this market, outpacing hardware shipment growth as data center operators prioritize uptime guarantees over capital expenditure optimization.
For Market Incumbents: Fortify captive foundry positions in North Rhine-Westphalia and Baden-Württemberg against margin erosion from Chinese electronics-integrated competitors by accelerating proprietary variable-frequency drive firmware development and securing long-term rare earth magnet offtake agreements with Japanese processors. Certification investment in EU F-Gas Regulation compatibility and REACH-compliant elastomer qualifications defends premium positioning against emerging assembly-dependent challengers. For New Entrants and Emerging Players: Lead with magnetic-drive technology convergence for single-use bioreactor systems in Swiss and German pharmaceutical clusters, where aseptic processing requirements and batch discard cost sensitivity create penetrable white space absent incumbent service infrastructure. Target India's Bureau of Energy Efficiency Perform Achieve Trade compliance retrofit cycle through localized variable-frequency drive assembly partnerships with Maharashtra and Gujarat industrial distributors. For Investors and Strategic Acquirers: Long-term, this sits as a service-attach infrastructure play because unbundled aftermarket contracts in US Gulf Coast power generation and Middle East desalination complexes disintermediate OEM service monopolies, creating recurring revenue platforms independent of unit shipment cyclicality. Acquisition target archetype: mid-cap specialists with embedded IoT diagnostics capabilities and established predictive maintenance algorithm libraries. Monitor hyperscale data center procurement cycle compression as inflection indicator—contracts below ninety-day windows signal tipping point toward application-engineered system preference over catalog offerings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Sourcing | Insulates margin pools from Chinese export quota volatility and price spikes. |
| Digital Twin Integration with Pump Hardware | Enables subscription-based predictive maintenance revenue decoupled from unit volumes. |
| EU F-Gas Regulation Compatibility Certification | Qualifies low-GWP refrigerant pump pairings for European HVAC retrofit demand. |
| Magnetic-Drive Technology Miniaturization | Supports rack-mounted direct-to-chip cooling configurations displacing centralized plants. |
| Localized Electronics Integration Partnerships | Addresses China's GB energy labeling requirements without third-party dependency. |
Research Methodology
The analysis maps centrifugal, positive displacement, and magnetic-drive pump sub-sectors, each validated through maintenance directors at hyperscale data centers, plant engineers in steel and cement facilities, aftermarket service heads at power generation utilities, and procurement teams at semiconductor foundries. Primary interview insights triangulate against customs trade data, SEC filings from listed pump manufacturers, EU F-Gas Regulation implementation reports, and China's GB energy labeling program documentation. Bottom-up unit shipment estimates and top-down addressable market sizing reconcile through iterative stakeholder feedback loops.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, technology architecture, application intensity, and end-user industry sophistication as core segmentation dimensions. CAGRs derive from installed base turnover rates, efficiency regulation compliance deadlines, and AI workload thermal density trajectories. Forecast inputs incorporate rare earth magnet price indices, nickel alloy commodity movements, and data center construction permit pipelines.
Forecasts assume regulatory continuity in EU F-Gas phasedown schedules, US DOE pump efficiency standards, and China's GB labeling tier progression; material policy shifts would require re-modeling. Semiconductor fabrication node advancement pace and hyperscale facility construction financing availability represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.