
 Global Piston Pumps Market | 2026-2036
Global Piston Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Piston Pumps Market Foresight
OEM-direct procurement channels is rewriting how piston pump manufacturers reach end users in heavy machinery markets. Bosch Rexroth AG leverages its captive hydraulics portfolio to anchor long-term supply agreements with European construction equipment builders. Moog Inc. specializes in precision motion control applications where axial piston pumps serve aerospace and defense platforms with exacting performance thresholds.
A piston pump converts rotational mechanical energy into hydraulic fluid displacement through reciprocating piston motion within a cylindrical bore block, typically achieving pressures exceeding 400 bar in industrial configurations. Its primary purpose is to generate controlled fluid power for heavy-duty actuation systems in mobile and stationary machinery. Axial piston pumps dominate high-pressure hydraulic applications where swashplate angle modulation enables variable displacement control, while plunger pumps retain strong positions in water treatment and oilfield injection services where abrasive fluid handling demands rugged liner and packing designs. Radial piston pumps occupy niche roles in high-torque, low-speed drives where eccentric shaft geometry delivers superior starting efficiency.
The EPA enforces emissions standards that push mobile equipment OEMs toward electrified hydraulic architectures, directly influencing pump-matching specifications for electric motor drives. ISO 4406 cleanliness codes and the EU Machinery Directive impose fluid contamination limits and safety integration requirements that filter down to component-level design obligations. Stakeholders must monitor how China's MIIT efficiency mandates and the EU Green Deal's embodied carbon tracking reshape sourcing decisions for cast iron housings and hardened steel valve plates.
Market Dynamics
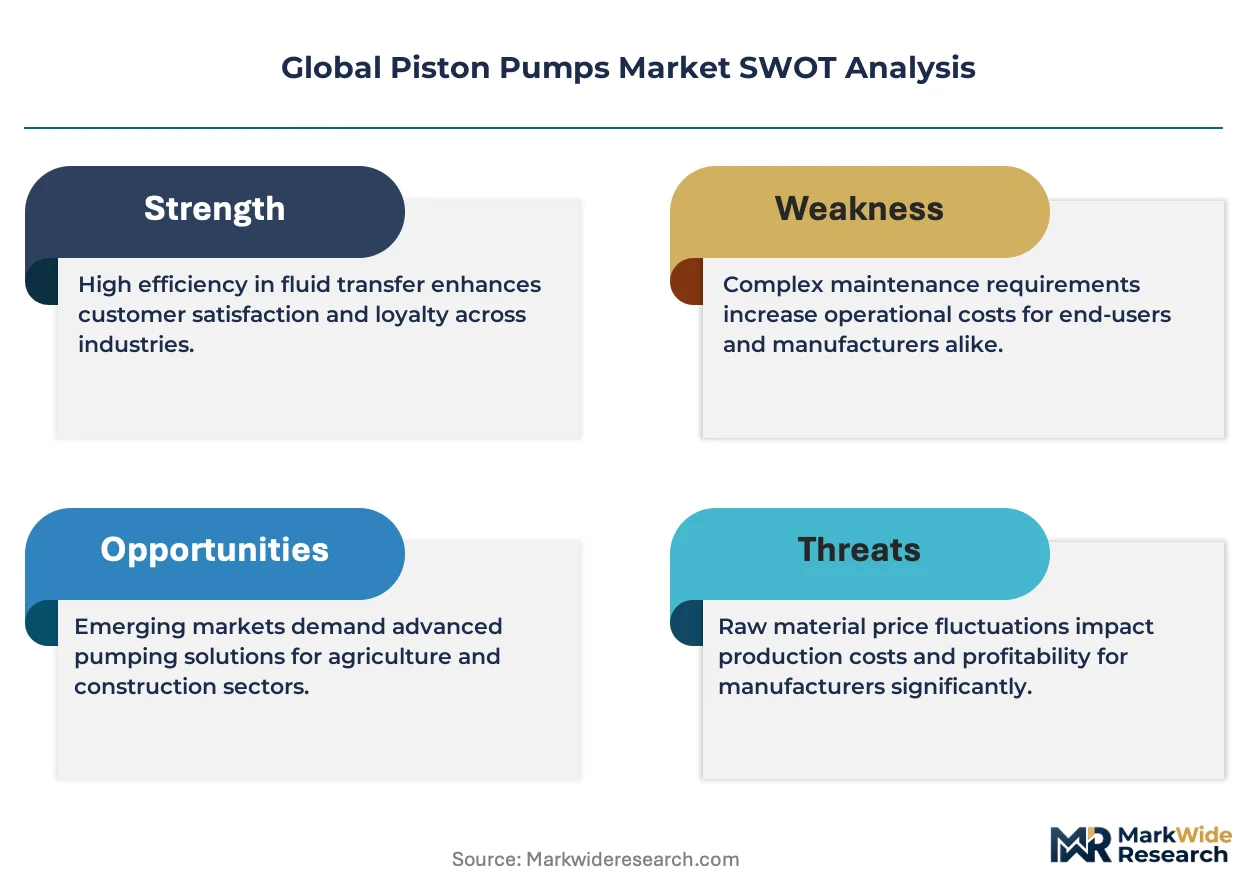
Electrification of mobile hydraulic systems is fragmenting traditional pump-matching specifications as OEMs redesign architectures around electric motor drives rather than internal combustion power take-offs.
Growth Catalysts
- Shale basin fleet modernization:North American hydraulic fracturing operators are replacing legacy pump units with higher-pressure configurations to access deeper unconventional reserves.
- EU Green Deal embodied carbon tracking:The regulation is forcing foundries to document emissions from cast iron housing production, favoring suppliers with verified low-carbon metallurgy.
- Axial piston variable displacement:Swashplate angle modulation technology enables precise flow control for precision engineering applications in Germany's industrial corridor.
Market Restraints
- Hardened steel valve plate supply concentration:Specialty alloy production clusters in select European and East Asian metallurgical centers create vulnerability to input bottlenecks.
- EPA emissions compliance costs:Mobile equipment electrification mandates require extensive pump redesign cycles that compress R&D amortization periods.
- Gear pump substitution in mid-pressure ranges:Fixed-displacement alternatives capture cost-sensitive applications below 250 bar where precision control offers marginal value.
Strategic Opportunities
- India's PLI scheme for construction machinery:Domestic production incentives attract pump manufacturers to establish local assembly for earthmoving equipment OEMs.
- Water treatment plunger pump retrofit demand:Abrasive fluid handling specifications in tertiary oil recovery and desalination plants favor rugged liner designs over axial alternatives.
- Condition monitoring convergence:Integration of vibration sensors with IoT telemetry enables predictive maintenance contracts that capture lifetime value from installed bases.
Industry Challenges
- ISO 4406 cleanliness code compliance:Fluid contamination thresholds require filtration system redesigns that extend qualification timelines for new pump architectures.
- Electrified hydraulic integration complexity:Matching pump response characteristics to electric motor torque curves demands control software competencies outside traditional mechanical engineering skill bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Piston Pumps Market |
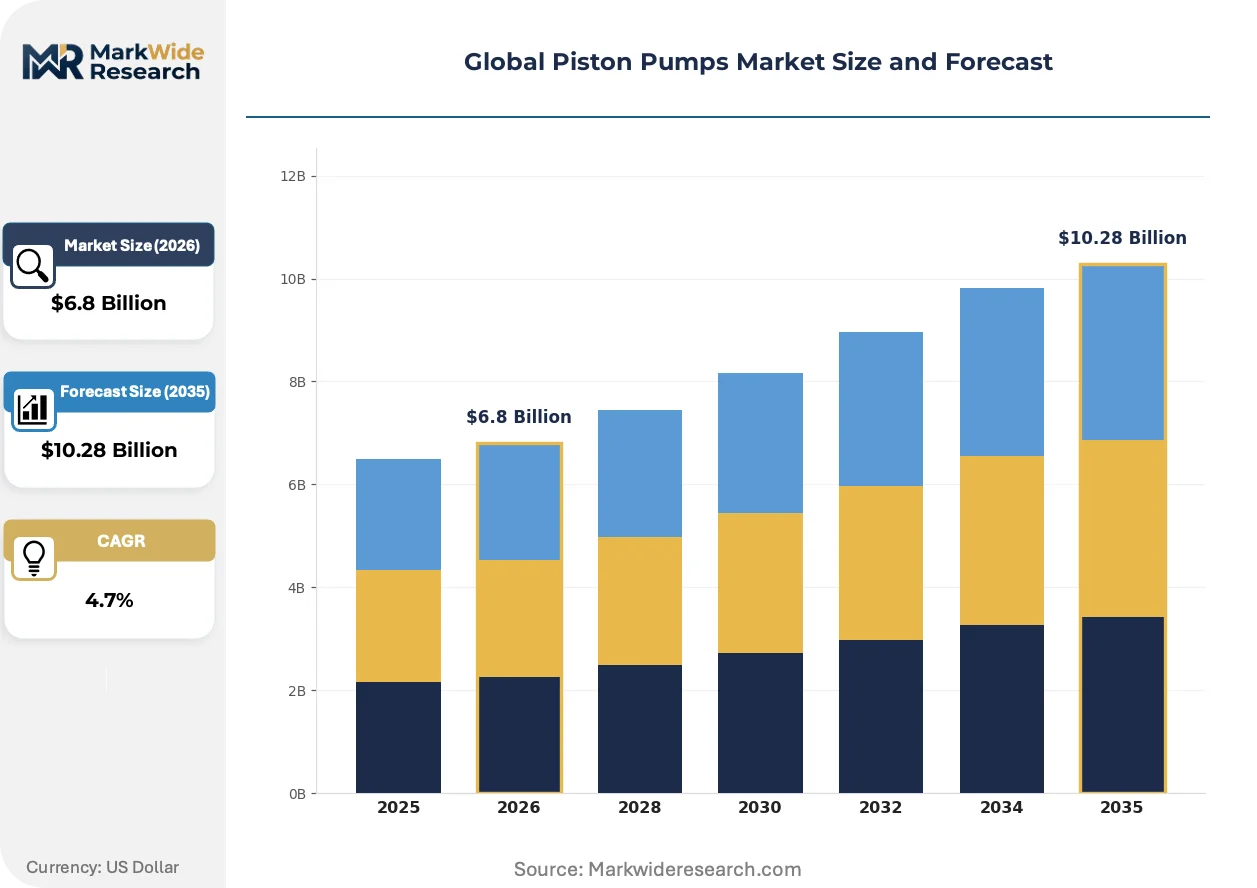
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Piston Pumps, Radial Piston Pumps, Plunger Pumps, Triplex Pumps, Duplex Pumps Application: Agriculture Equipment, Construction Machinery, Marine Systems, Hydraulic Presses, Mining Equipment Drive Type: Electric Motor, Diesel Engine, Gasoline Engine, Hydraulic Motor, Pneumatic Motor End User Industry: Oilfield Services, Aerospace Manufacture, Food Processing, Water Treatment, Chemical Production |
| Companies Covered | Bosch Rexroth AG, Moog Inc., Daikin Industries, Ltd., Alfa Laval, Danfoss, Parker Hannifin Corp, Interpump Group, Yuken Kogyo Co., Ltd., Nachi-Fujikoshi Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Piston Pumps Market Shifts & Advancements
Digital fluid power architectures are redefining how piston pumps interface with system-level controls, shifting value capture from hardware displacement toward software-defined performance envelopes.
Electro-hydraulic actuation is hybridizing conventional piston pump hardware with servo-electric positioning, enabling stroke-by-stroke flow modulation without mechanical swashplate linkages. Construction equipment OEMs in Germany and Japan are piloting these configurations for excavator boom control. The technology is hybridizing supplier relationships as motion control specialists enter territory historically held by pure-play hydraulics manufacturers.
China's MIIT efficiency mandates for hydraulic machinery are tightening minimum performance coefficients for volumetric and mechanical efficiency. Domestic pump producers must redesign port plate geometries and piston coatings to maintain market access. Imported product lines face parallel compliance obligations, compressing the premium positioning historically enjoyed by European axial piston suppliers.
After-sales service unbundling is accelerating as fleet operators separate maintenance contracts from original equipment purchases. Rental companies in North American shale plays now source replacement pumps through independent distributors rather than captive OEM channels. Brazil's ANVISA-equivalent industrial safety frameworks are reinforcing this pattern by mandating third-party certification for remanufactured hydraulic components.
Global Piston Pumps Market Segmentation
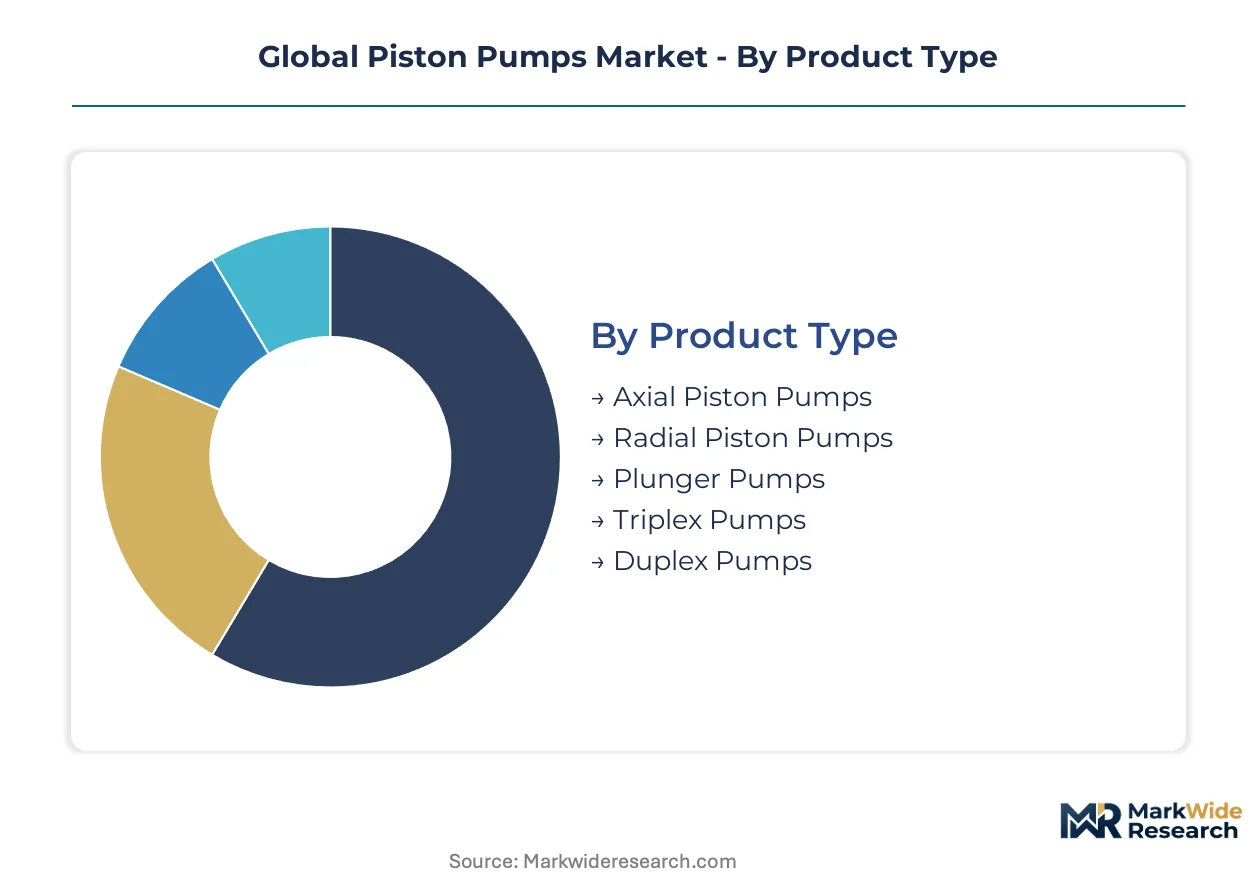
Piston pump architectures fragment across pressure ratings, fluid compatibility, and power transmission interfaces. Each segmentation dimension carries distinct margin profiles and qualification barriers that shape supplier positioning.
Product Type:
Cost tier differentiation separates precision-engineered variable displacement units from fixed-displacement alternatives serving abrasive fluid handling.
- Axial Piston Pumps:Swashplate angle modulation enables continuous displacement adjustment from zero to maximum flow. Demand concentrates in Germany's industrial manufacturing corridor where precision engineering applications require exact pressure control.
- Radial Piston Pumps:Eccentric shaft geometry drives pistons arranged radially around a central drive, delivering superior starting torque at low rotational speeds. High-torque, low-speed drives in mining winch systems favor this configuration for stall-resistant operation.
- Plunger Pumps:Rugged liner and packing designs handle abrasive fluids in water treatment and oilfield injection services where axial alternatives suffer premature wear.
- Triplex Pumps:Three-plunger inline configurations deliver pulsation-dampened flow for high-pressure cleaning and hydrostatic testing applications.
- Duplex Pumps:Two-plunger designs balance cost and output stability in mid-pressure industrial process lines.
Axial configurations hold installed capacity. Plunger designs are rotating up the share rankings.
Application:
Application segmentation tracks equipment duty cycles and hydraulic power density requirements across mobile and stationary machinery.
- Construction Machinery:Excavator boom circuits and loader lift systems demand variable displacement pumps matched to electric motor torque curves under EPA electrification mandates. OEMs in Germany and Japan pilot electro-hydraulic actuation for stroke-by-stroke flow modulation.
- Oilfield Services:Hydraulic fracturing fleets in US shale basins deploy high-pressure triplex configurations for proppant slurry injection. Fleet operators now source replacement pumps through independent distributors rather than captive OEM channels.
- Agriculture Equipment:Tractor hydraulic systems favor cost-optimized fixed-displacement units for implement lift and steering circuits.
- Marine Systems:Corrosion-resistant coatings and duplex stainless steel construction address seawater exposure in deck machinery and stabilizer systems.
- Hydraulic Presses:Metal forming applications require rapid pressure buildup and precise holding characteristics.
Construction applications command premium positioning. Oilfield services are climbing the fastest.
Drive Type:
Power source selection determines pump speed range, torque ripple tolerance, and control system architecture.
- Electric Motor:Servo-driven pumps enable software-defined performance envelopes with precise speed control. Mobile equipment OEMs redesign architectures around electric motor drives rather than internal combustion power take-offs under emissions regulations.
- Diesel Engine:Traditional power take-off configurations persist in remote mining and construction sites lacking grid infrastructure.
- Gasoline Engine:Portable power units serve emergency repair and temporary dewatering applications.
- Hydraulic Motor:Secondary power transmission in complex multi-circuit machinery.
- Pneumatic Motor:Explosion-proof operation in chemical production environments.
Electric motor drives hold installed capacity. Diesel alternatives are rotating up the share rankings.
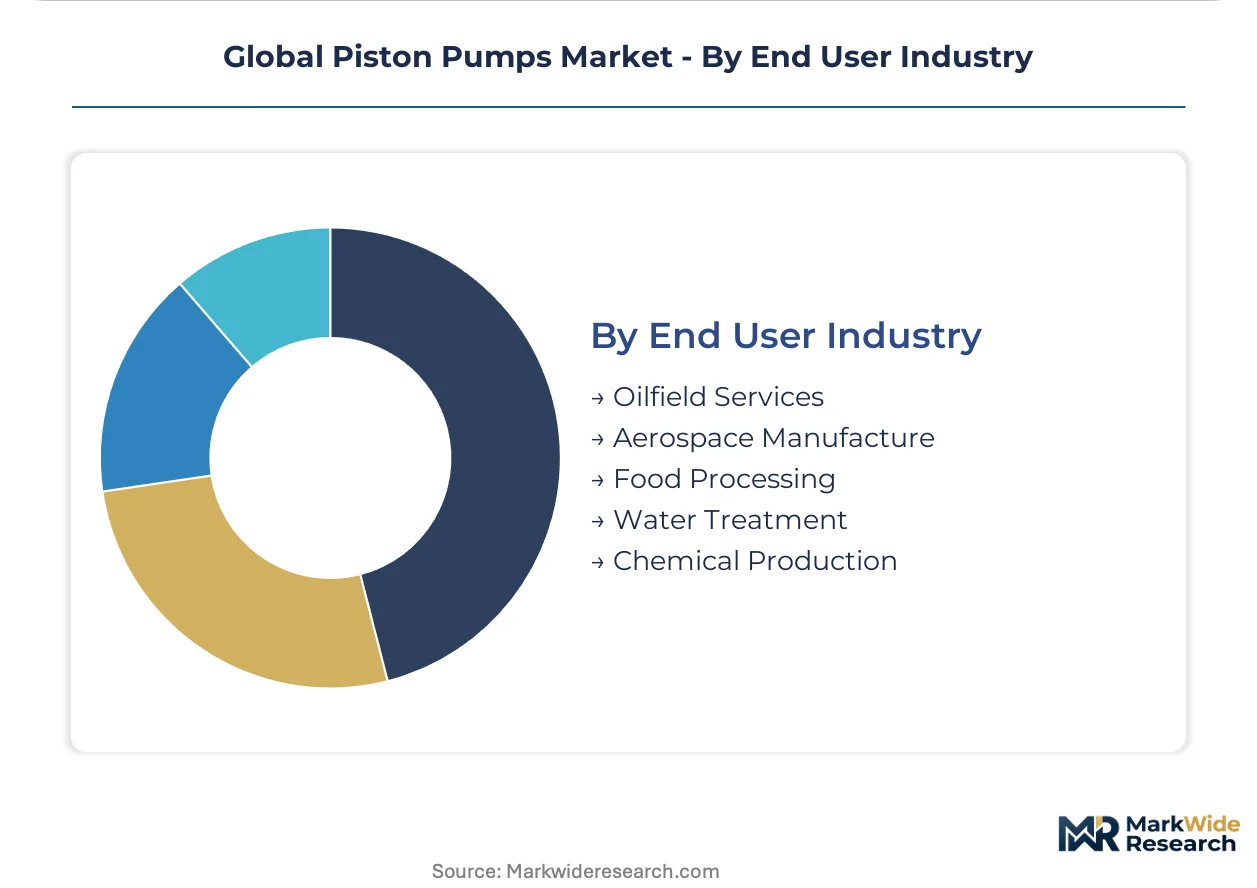
End User Industry:
Industry verticals impose distinct fluid cleanliness codes, material compatibility requirements, and certification standards.
- Oilfield Services:Abrasive fluid handling specifications in tertiary oil recovery favor rugged plunger pump designs. China's MIIT efficiency mandates tighten minimum performance coefficients for volumetric and mechanical efficiency across imported and domestic product lines.
- Water Treatment:Desalination plants and wastewater facilities specify hardened valve plates and ceramic-coated plungers for chlorine and particulate exposure.
- Aerospace Manufacture:Precision motion control platforms demand exacting performance thresholds with zero-failure tolerances.
- Food Processing:Stainless steel construction and FDA-compliant seals address sanitary washdown requirements.
- Chemical Production:Corrosion-resistant alloys and double mechanical seals prevent hazardous fluid release.
Oilfield services hold installed capacity. Water treatment is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network underwrites US primacy in high-pressure hydraulic fracturing pump demand. Germany's Rhine-Ruhr industrial corridor channels precision engineering requirements through its dense machine tool ecosystem. China's coastal manufacturing belt absorbs efficiency-mandated design upgrades.
United States
Hydraulic fracturing fleet operators in the Permian and Bakken formations are replacing legacy pump units with higher-pressure configurations. EPA emissions standards push mobile equipment OEMs toward electrified hydraulic architectures that reshape pump-matching specifications. Houston anchors oilfield services procurement, while Detroit-area construction equipment builders pilot electric motor drive integrations.
Germany
Precision engineering applications in metal forming and machine tool automation demand exact pressure control through variable displacement axial units. EU Green Deal embodied carbon tracking forces foundries to document emissions from cast iron housing production. Stuttgart and Munich host clusters where motion control specialists and pure-play hydraulics manufacturers compete for construction equipment OEM contracts.
China
MIIT efficiency mandates for hydraulic machinery tighten minimum performance coefficients for volumetric and mechanical efficiency. GB standards force design upgrades across imported and domestic product lines alike. Shanghai and Suzhou manufacturing zones concentrate pump assembly operations serving construction machinery OEMs responding to domestic production incentives.
Japan
Construction equipment OEMs in Tokyo and Osaka pilot electro-hydraulic actuation configurations for excavator boom control. METI industrial efficiency frameworks pressure suppliers to improve port plate geometries and piston coatings. Nagoya's automotive-adjacent hydraulics cluster supplies precision motion control platforms for aerospace manufacture and factory automation.
India
The PLI scheme for construction machinery attracts pump manufacturers to establish local assembly for earthmoving equipment OEMs. BIS certification requirements for hydraulic machinery create qualification barriers for imported product lines. Pune and Chennai industrial corridors concentrate domestic fabrication capacity serving infrastructure build-out programs.
Global Piston Pumps Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The supplier base stratifies between diversified motion control conglomerates and focused hydraulics fabricators. Three archetypes dominate: captive hydraulics divisions of construction equipment OEMs, independent precision component specialists, and diversified industrial technology groups with fluid power portfolios. Competitive moves concentrate on strategic partnerships for electric motor drive integration and capacity expansion in low-carbon metallurgy supply.
Among diversified industrial technology groups, Bosch Rexroth AG and Parker Hannifin Corp occupy positions spanning component supply through system integration. Moog Inc. exemplifies the precision motion control specialist archetype, sitting within aerospace and defense platform supply chains where exacting performance thresholds apply. Daikin Industries, Ltd. represents the Asia-Pacific industrial conglomerate model with captive hydraulics capabilities.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Moog Inc. |
| Daikin Industries, Ltd. |
| Alfa Laval |
| Danfoss |
| Parker Hannifin Corp |
| Interpump Group |
| Yuken Kogyo Co., Ltd. |
| Nachi-Fujikoshi Corp. |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container cost dynamics expose how supply concentration in European and East Asian metallurgical centers amplifies downstream price differentiation between premium axial configurations and standard fixed-displacement units. Hardened steel valve plate bottlenecks translate into tiered availability premiums that OEM procurement teams must navigate when sourcing for electrified hydraulic architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates precision-engineered variable displacement units with ISO 4406 certification compliance from fixed-displacement alternatives serving abrasive fluid handling. Price differentiation rests on volumetric efficiency ratings and after-sales service bundling rather than raw material costs alone. Cost compression in the economy tier is intensifying because gear pump substitution captures mid-pressure applications below 250 bar. Fleet operators in North American shale basins exhibit the highest price sensitivity due to unbundled procurement through independent distributors, while aerospace and defense platforms tolerate premium positioning for zero-failure tolerances.
Supply Chain Analysis
Specialty alloy feedstock for hardened steel valve plates draws from concentrated production clusters in Germany, Japan, and China, with secondary refining capacity tethered to electric arc furnace operations in South Korea. Raw material dependencies span high-grade chromium-molybdenum steel billets, ceramic piston coatings, and corrosion-resistant duplex stainless steel for marine applications. Single-source vulnerability in European foundry capacity for cast iron housings intensifies under EU Green Deal embodied carbon tracking requirements. Distribution runs through OEM-direct channels for construction equipment builders and independent aftermarket networks serving oilfield services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification of mobile hydraulic systems constitutes a high-growth disruption as EPA emissions mandates force pump-matching specification redesigns around electric motor torque curves. This technological inflection fragments traditional supplier relationships while opening white-space for motion control specialists.
For Market Incumbents: Harden supply security through backward integration into low-carbon metallurgy supply or captive foundry partnerships in Germany and Japan to defend against input bottlenecks. Anchor long-term agreements with construction equipment OEMs piloting electro-hydraulic actuation before motion control specialists capture system-tier value. Prioritize certification investment for China's MIIT efficiency mandates to maintain premium positioning against domestic producers.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized construction machinery assembly corridor where BIS certification creates qualification barriers for legacy importers. Target water treatment plunger pump retrofit demand where abrasive fluid handling specifications favor rugged liner designs over entrenched axial alternatives. Pursue predictive maintenance software partnerships with IoT telemetry providers to capture lifetime value from installed bases.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision component specialists with embedded aerospace and defense platform relationships over diversified industrial conglomerates exposed to commodity cycle volatility. Long-term viability hinges on electric motor drive integration competencies and software-defined performance envelope capabilities. Monitor EPA enforcement patterns and EU Green Deal carbon border adjustment mechanisms as inflection indicators for foundry sourcing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Metallurgy | EU Green Deal tracking requirements favor suppliers with verified emissions documentation from German foundries. |
| Electro-Hydraulic Actuation Partnerships | Construction equipment OEMs in Stuttgart and Tokyo seek stroke-by-stroke flow modulation without mechanical linkages. |
| Predictive Maintenance Platform Development | Vibration sensor integration with IoT telemetry enables lifetime value capture from North American shale fleet operators. |
| Local Assembly Expansion under India's PLI Scheme | Domestic production incentives attract pump manufacturers to Pune and Chennai corridors for earthmoving equipment OEMs. |
| MIIT Efficiency Compliance Certification | China's tightening performance coefficients for volumetric and mechanical efficiency compress European premium positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from diversified industrial technology groups, and MIIT regulatory bulletins. Interviews with maintenance directors at hydraulic fracturing fleet operators, OEM procurement teams in Germany's industrial corridor, and aftermarket service heads at independent distributors provided operational validation. Bottom-up unit deployment estimates from shale basin operators were triangulated against top-down market value reconstruction from component manufacturer revenue disclosures.
Forecast inputs include pressure rating segmentation, drive type migration patterns from diesel to electric motor configurations, and end-user industry demand trajectories across oilfield services and water treatment applications. CAGRs were derived from weighted scenario analysis across electrification adoption curves and efficiency mandate implementation timelines. The modeling period incorporates port plate geometry redesign cycles, ceramic coating adoption rates, and condition monitoring convergence timelines as industry-specific variables.
Stress conditions across specialty alloy price volatility, EPA enforcement intensity, and China domestic production incentive scaling were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet replacement cycles and electrification architecture penetration. Cross-checking against IEA industrial efficiency tracking and ACC hydraulic machinery shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
Double Diaphragm Pump Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
United States Positive Displacement Pumps Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Water Pump Market