
 Grease Pump Market | 2026-2036
Grease Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Grease Pump Market Foresight
Industrial manufacturing buyers are collapsing legacy procurement cycles for manual grease pumps while fleet operators and mining contractors accelerate investment in automatic systems. Graco Inc. dominates portable electric pump lines for construction sites through direct distribution. SKF Group anchors stationary automatic installations in European automotive workshops with integrated condition monitoring. Lincoln Industrial specializes in high-pressure pneumatic units for underground mining fleets.
A grease pump is a positive-displacement device engineered to deliver lubricating grease at controlled pressures, typically ranging from 3,000 to 10,000 psi, through fixed or flexible lines to bearing surfaces, bushings, and friction points in heavy machinery. Its primary industrial purpose is to eliminate manual lubrication labor, ensure consistent film thickness, and extend component life in equipment operating under load, contamination, or temperature stress. Electric grease pumps now lead the product type landscape in revenue terms due to their programmability and compatibility with Industry 4.0 control architectures, while pneumatic variants retain share in explosive atmospheres where electrical ignition risks are regulated. The end-user split shows mining and construction outpacing automotive workshops in growth velocity, driven by remote-site reliability requirements and total-cost-of-ownership contracting models that penalize unplanned downtime.
OSHA lockout-tagout standards and EPA spill prevention rules shape grease pump specification in United States industrial settings, forcing suppliers to engineer sealed reservoir designs and quick-connect fittings that minimize environmental release. The EU Machinery Directive and REACH chemical compliance frameworks in Europe restrict certain base-grease formulations and mandate CE-marked pump assemblies with documented pressure safety margins. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving lubricant toxicity classifications will redirect material selection and aftermarket service economics before the next equipment replacement cycle.
Market Dynamics
Precision greasing infrastructure is fragmenting traditional maintenance economics as fleet operators abandon calendar-based schedules for condition-triggered lubrication cycles tied to telematics and vibration sensors.
Growth Catalysts
- EPA emission standards for off-road diesel equipment:United States operators face compliance pressure to reduce friction losses through automated greasing systems that optimize film thickness and cut parasitic drag.
- Underground mining fleet automation:Australian mining contractors are retrofitting autonomous haul trucks with centralized lubrication to eliminate manual greasing in hazardous pit environments.
- Automotive OEM assembly line retrofits:Germany's industrial corridor is deploying centralized grease distribution networks to synchronize lubrication cycles with takt-time manufacturing rhythms.
Market Restraints
- Lithium complex grease price volatility:Base thickener costs fluctuate with lithium carbonate mining output from Chilean and Australian deposits, squeezing pump reservoir fill economics.
- High-pressure seal supply concentration:Precision urethane and PTFE seal manufacturing clusters in southern Germany and Japan's Kansai region, creating single-source vulnerability for pump rebuild kits.
- REACH chemical compliance friction:ECHA substance restrictions on certain extreme-pressure additives force formulation reformulation cycles that delay new pump lubricant compatibility certification.
Strategic Opportunities
- Wind turbine drivetrain maintenance:Offshore installations in the North Sea and Baltic coasts require remote-access automatic greasing systems for nacelle bearings inaccessible during weather windows.
- EU Machinery Directive pressure safety mandates:CE-marked pump assemblies with documented burst margins open replacement demand across aging European metalworking and paper mill infrastructure.
- IoT-enabled predictive lubrication:Convergence of vibration monitoring and cloud analytics allows pump OEMs to sell lubrication-as-a-service rather than capital equipment.
Industry Challenges
- Mechatronics technician scarcity:Maintenance organizations struggle to staff field service roles combining hydraulic troubleshooting with PLC programming and sensor calibration.
- Legacy system integration complexity:Brownfield manufacturing sites run decades-old centralized lubrication headers that resist retrofit with Industry 4.0 control architectures without full line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grease Pump Market |
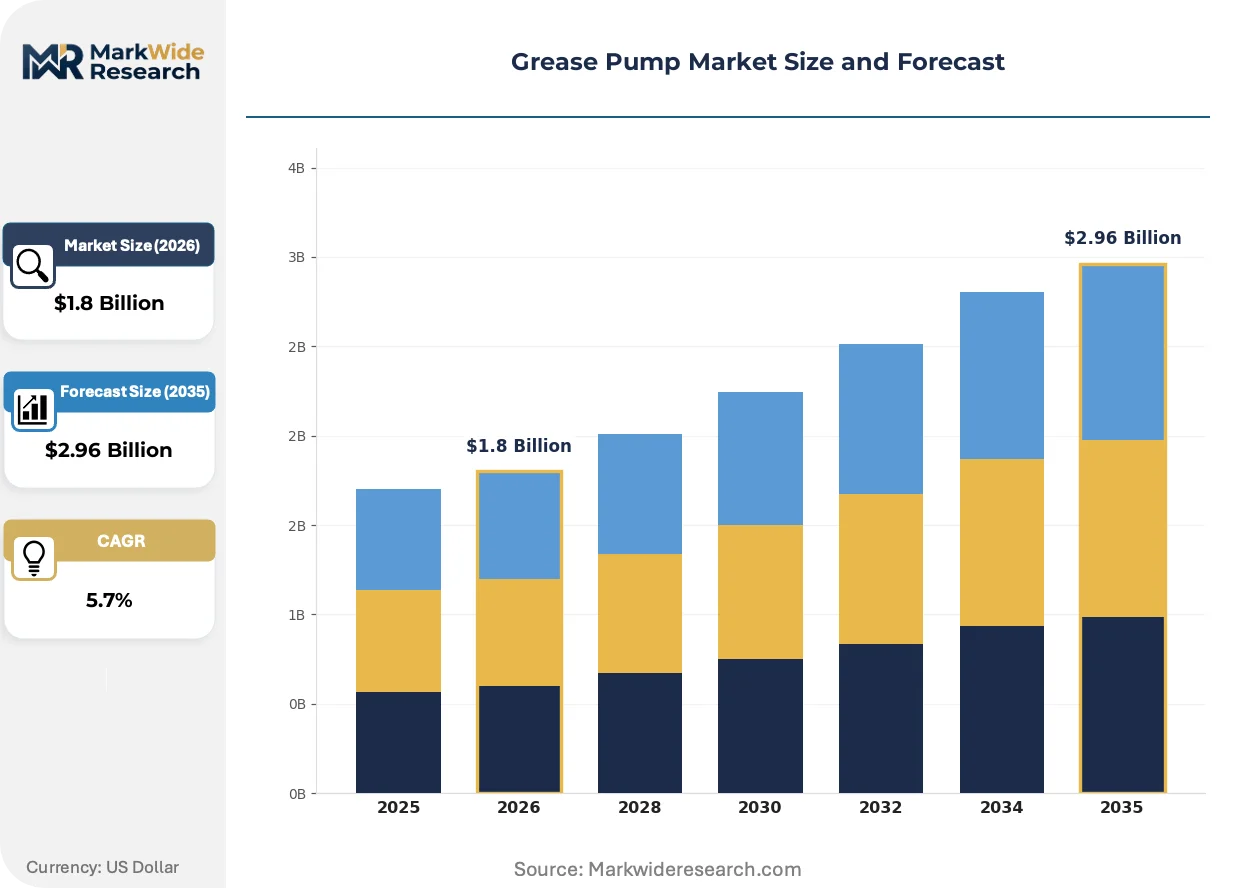
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Grease Pumps, Electric Grease Pumps, Pneumatic Grease Pumps, Automatic Grease Pumps End User: Automotive Workshops, Industrial Manufacturing, Construction, Mining Installation Type: Portable, Stationary, Mobile, Fixed Distribution Channel: Online Retailers, Distributors, Direct Sales, Dealers |
| Companies Covered | Graco Inc., SKF Group, Lincoln Industrial, Ingersoll Rand, TriRotor Inc, Pressol Schmiergerate GmbH, TAKADA CORPORATION, LUBE Corporation, Flexbimec International srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grease Pump Market Shifts & Advancements
Electrification and digitalization are converging to reengineer how lubricant reaches friction points, compressing the gap between pump hardware and maintenance software.
Brushless DC motor technology is fragmenting the electric grease pump landscape into modular, field-replaceable drive units. Mining contractors in Western Australia are specifying these motors for their variable-speed programmability and reduced spark risk compared to brushed alternatives. The shift is fragmenting supplier relationships as end-users mix motor, pump head, and controller components from different vendors rather than buying integrated systems.
OSHA lockout-tagout enforcement is tightening reservoir design standards in United States industrial plants. Sealed quick-fill ports and pressure-vented caps now dominate specification sheets to prevent accidental release during maintenance. Food processing and pharmaceutical packaging lines are most affected, driving demand for stainless-steel pump housings with sanitary clamp fittings.
Total-cost-of-ownership contracting is compressing procurement cycles for automatic systems. Fleet managers at construction and aggregate operations now specify uptime guarantees and penalty clauses for unplanned downtime rather than accepting capital equipment bids. This behavioral shift is most visible in North American mining and heavy civil construction, where lubrication service providers are assuming operational risk for component life extension.
Grease Pump Market Segmentation
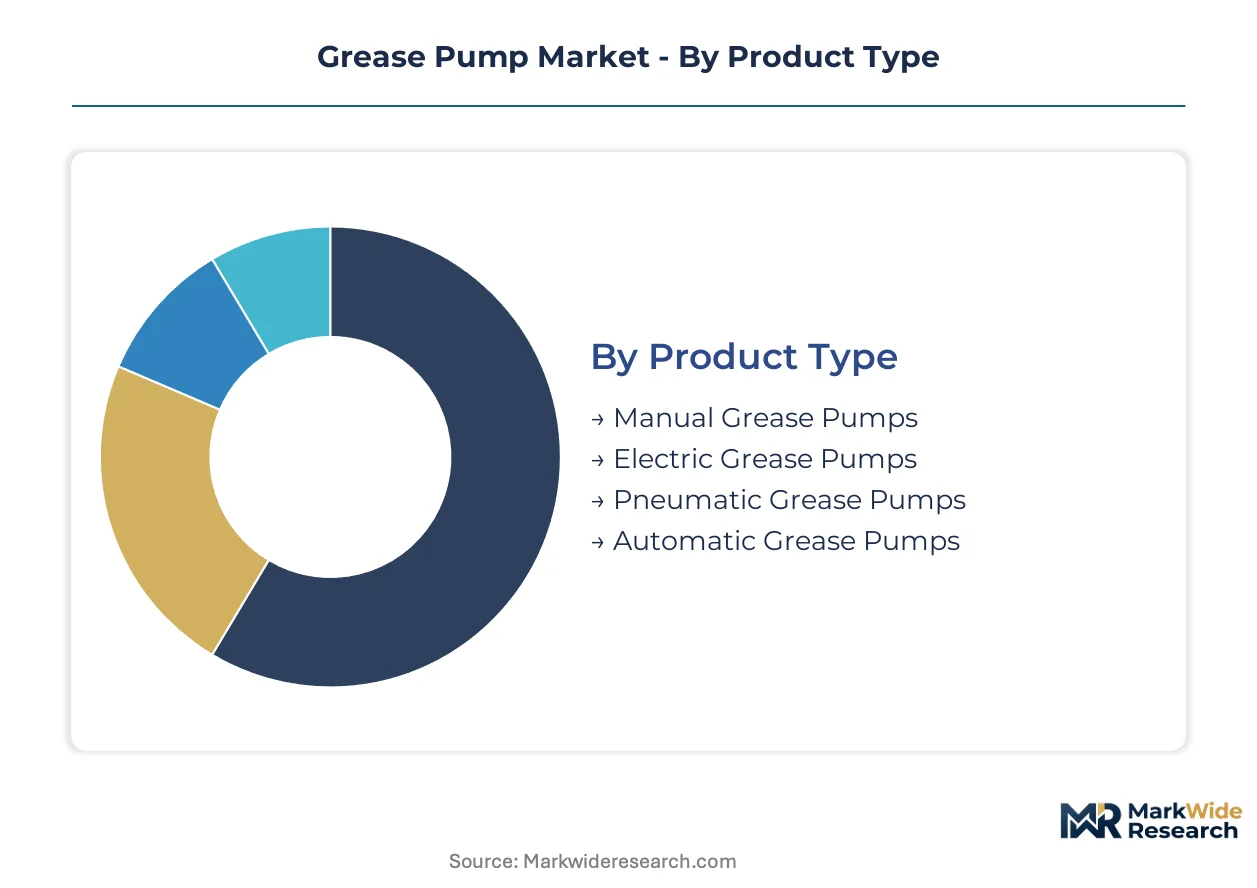
Segmentation in the grease pump market reveals how lubrication infrastructure fragments across power sources, mobility requirements, and procurement channels. Buyers in mining and automotive sectors deploy sharply different specifications, forcing suppliers to maintain parallel product architectures rather than unified platforms.
Product Type:
Electric grease pumps face substitution pressure from pneumatic alternatives in explosive atmospheres, while manual pumps confront displacement by automatic systems in fleet maintenance contracts.
- Electric Grease Pumps:Brushless DC motor variants deliver programmable pressure curves from 3,000 to 10,000 psi through Industry 4.0 control interfaces. Demand concentrates in German automotive OEM assembly lines where synchronized lubrication cycles match takt-time production rhythms.
- Automatic Grease Pumps:Centralized distribution systems with multi-point injection headers eliminate manual labor in remote mining operations. Australian underground contractors specify these for autonomous haul truck fleets where pit access restrictions prevent hand-greasing during production windows.
- Pneumatic Grease Pumps:Compressed-air-driven units operate without electrical ignition risk in confined underground headings.
- Manual Grease Pumps:Lever-actuated portable units persist in small-scale construction and agricultural maintenance where capital constraints resist automation.
Electric grease pumps anchor the volume base while automatic grease pumps gain share at the steepest rate.
End User:
Cost tier stratification separates premium automatic system buyers from economy manual pump purchasers across maintenance-intensive industries.
- Mining:Total-cost-of-ownership contracting models penalize unplanned downtime, driving specification of centralized automatic systems with remote monitoring. Western Australian iron ore operations lead retrofit intensity as fleet automation eliminates manual greasing in hazardous pit environments.
- Industrial Manufacturing:Brownfield metalworking and paper mill infrastructure in Europe requires CE-marked pump replacements under Machinery Directive pressure safety mandates.
- Construction:Portable electric and pneumatic units dominate equipment rental fleets and contractor job sites.
- Automotive Workshops:Stationary installations with integrated condition monitoring serve high-volume service bays.
Mining commands the steepest investment trajectory while industrial manufacturing provides the installed base for replacement cycles.
Installation Type:
Application mobility requirements split demand between field-service portability and permanent infrastructure integration.
- Portable:Battery-powered and pneumatic handheld units serve construction equipment operators requiring lubrication at dispersed work faces. OSHA lockout-tagout enforcement in United States industrial plants drives specification of sealed reservoir designs with quick-connect fittings.
- Stationary:Fixed-header centralized systems anchor automotive assembly lines and process manufacturing facilities where lubrication timing synchronizes with production sequences.
- Mobile:Skid-mounted pump carts serve maintenance crews rotating across mining fleet parking areas.
- Fixed:Hard-piped distribution networks with metered injection points serve permanent industrial infrastructure.
Stationary installations dominate capital expenditure value while portable units move the highest unit volumes.
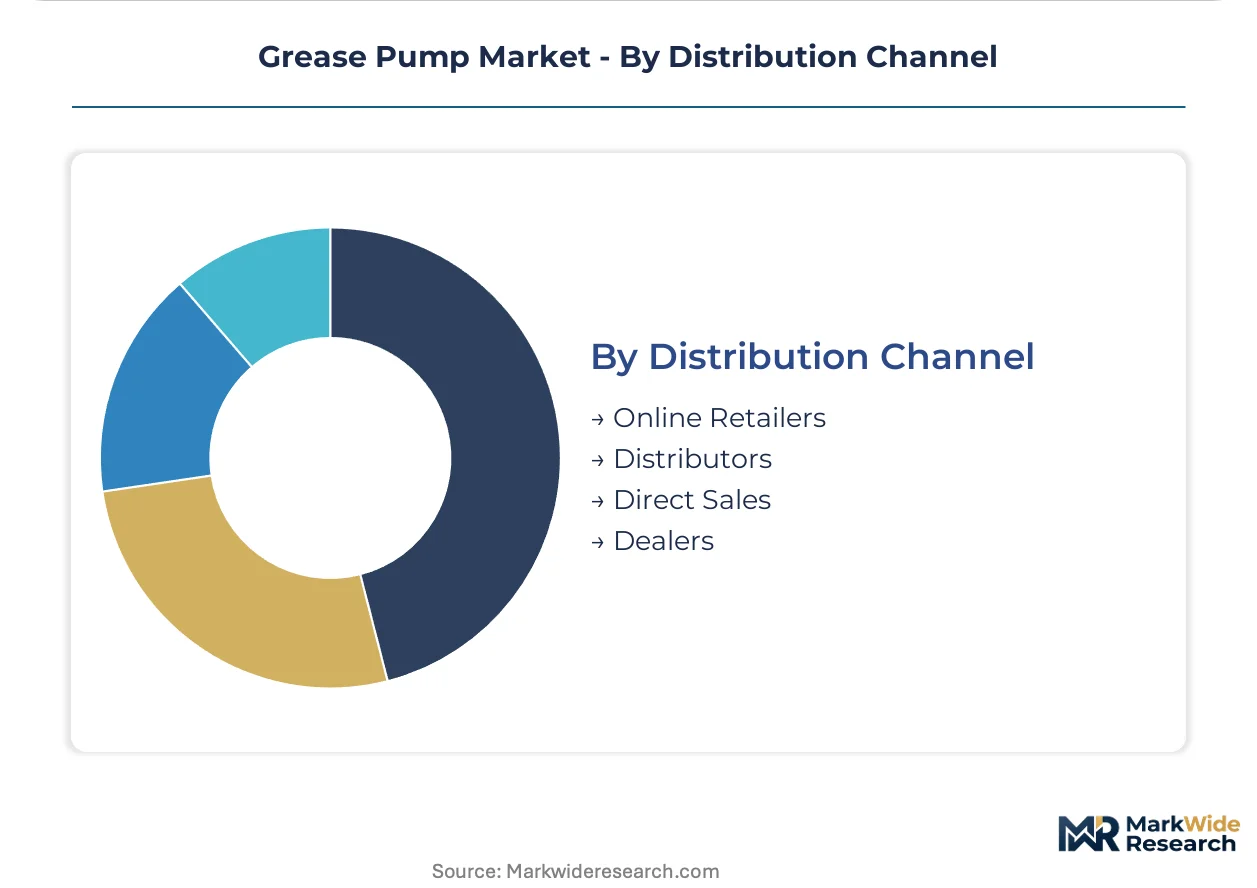
Distribution Channel:
Customer type and order scale determine channel selection, with enterprise fleet operators bypassing intermediaries while small contractors rely on dealer networks.
- Direct Sales:Pump OEMs maintain field engineering teams for mining contractors and automotive OEMs specifying uptime guarantees and penalty clauses. Graco Inc. deploys direct distribution for portable electric pump lines to North American construction sites.
- Distributors:Industrial supply houses stock replacement pump heads, motors, and seal kits for maintenance organizations.
- Dealers:Local equipment dealers serve agricultural and small construction operators with manual pump offerings.
- Online Retailers:E-commerce platforms capture standard component sales for in-house maintenance teams.
Direct sales capture the highest-value contracts while distributors handle the broadest SKU breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara heavy-haul rail network underwrites Australia's dominance in mining-sector grease pump deployment. Germany's Rhine-Main industrial corridor anchors European precision manufacturing demand. The US Gulf Coast petrochemical complex supports lubricant formulation infrastructure that shapes pump specification standards.
Australia
Western Australian iron ore operations drive automatic system retrofits for autonomous haul truck fleets. EPA-equivalent state environmental regulators enforce spill prevention standards in Pilbara pit environments. Perth-based maintenance contractors supply centralized lubrication infrastructure to remote mine sites where manual greasing is operationally prohibitive.
Germany
Automotive OEM assembly lines in Stuttgart and Munich deploy synchronized grease distribution networks matching takt-time production rhythms. EU Machinery Directive pressure safety mandates force CE-marked pump replacements across aging metalworking infrastructure. Baden-Württemberg's industrial cluster concentrates precision seal manufacturing for high-pressure pump assemblies.
United States
Construction equipment rental fleets in Texas and the Mountain West specify portable electric pumps for dispersed job sites. OSHA lockout-tagout enforcement tightens reservoir design standards in food processing and pharmaceutical packaging lines. EPA emission standards for off-road diesel equipment push operators toward precision greasing systems that cut friction losses and parasitic drag.
Japan
Kansai-region precision component manufacturers supply high-pressure urethane and PTFE seals for pump rebuild kits. METI industrial efficiency programs encourage condition-monitoring integration in automotive workshop installations. Osaka-based fabrication clusters specialize in compact pump heads for space-constrained manufacturing environments.
China
Shanxi and Inner Mongolia coal mining operations accelerate fleet automation requiring centralized lubrication systems. GB standards and MIIT equipment safety regulations shape domestic pump certification requirements. Yangtze River Delta manufacturing hubs produce cost-optimized electric pump motors for export and domestic construction markets.
Grease Pump Market Competitive Landscape
Concentration sits with diversified industrial conglomerates controlling distribution infrastructure and specialized lubrication system houses with deep mining-sector relationships. The vendor base spans three tiers: global fluid handling conglomerates with direct field engineering capabilities, regional pump specialists serving automotive workshop networks, and component fabricators supplying seal kits and replacement heads. M&A activity targets condition-monitoring software assets, while capacity expansion concentrates in brushless DC motor and high-pressure seal manufacturing.
Among diversified industrial conglomerates, Graco Inc. and SKF Group exemplify contrasting strategic positions. Graco anchors portable electric pump lines through North American direct distribution networks. SKF occupies a position in stationary automatic installations with integrated monitoring capabilities. Lincoln Industrial represents the mining-specialist archetype, with company nomenclature indicating industrial lubrication heritage.
| Leading Market Players |
|---|
| Graco Inc. |
| SKF Group |
| Lincoln Industrial |
| Ingersoll Rand |
| TriRotor Inc |
| Pressol Schmiergerate GmbH |
| TAKADA CORPORATION |
| LUBE Corporation |
| Flexbimec International srl |
| Others |
Supply & Pricing Matrix
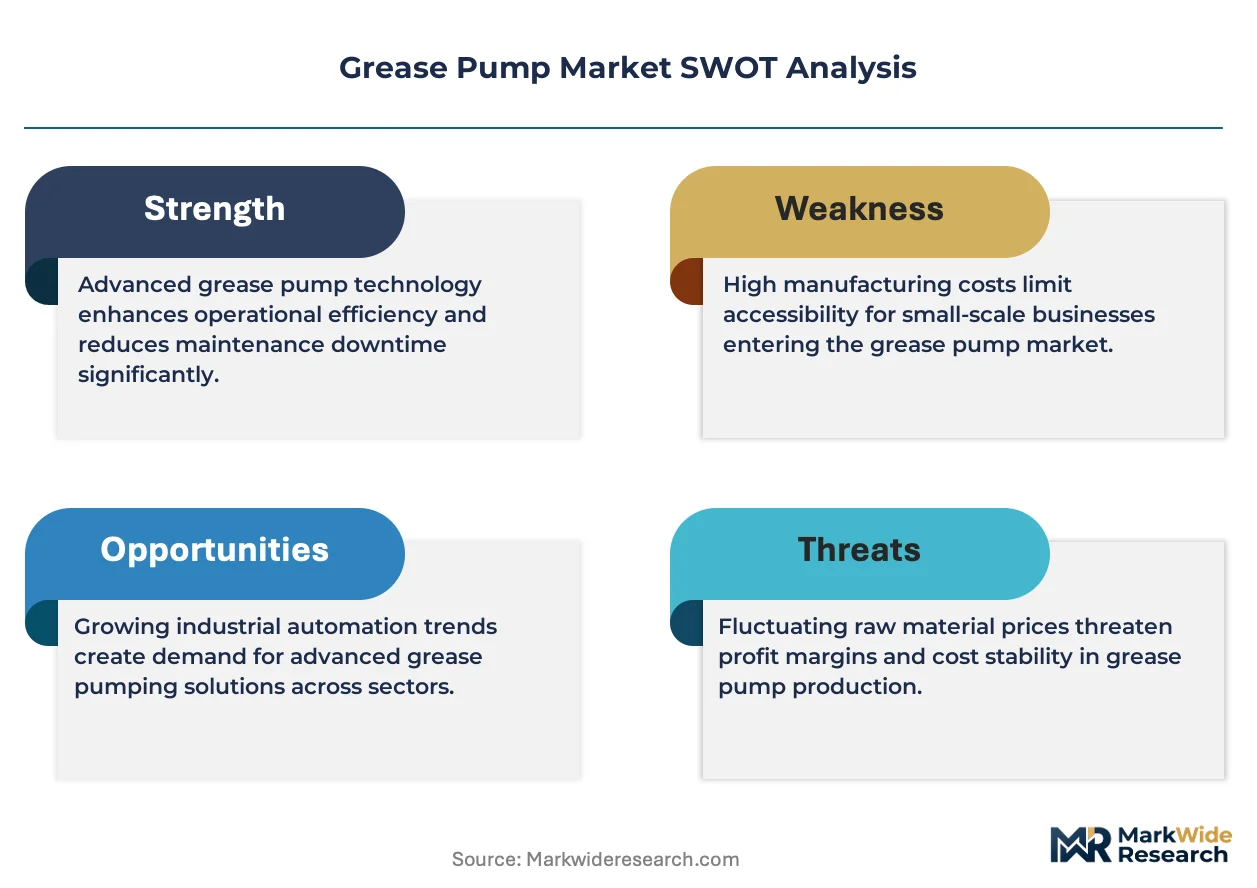
Long-term total-cost-of-ownership contracts with uptime guarantee clauses lock in supply access for mining contractors while anchoring price visibility across multi-year fleet lubrication programs. These agreements bundle automatic pump hardware, preventive maintenance labor, and consumable grease into single-line-item budgets that resist spot-market volatility.
Pricing Analysis
Volume-discount tiering separates enterprise fleet operators purchasing centralized systems from small contractors buying portable units. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Pricing pressure stems from lithium complex grease cost volatility squeezing reservoir fill economics. Small agricultural operators exhibit highest price sensitivity, while Australian mining contractors prioritize reliability guarantees over unit cost.
Supply Chain Analysis
Germany and Japan anchor precision seal manufacturing for high-pressure pump assemblies, with Baden-Württemberg and Kansai-region fabricators supplying urethane and PTFE components. Brushless DC motors draw from Yangtze River Delta production hubs. Single-source vulnerability concentrates in southern German seal manufacturing clusters. Distribution runs through direct field engineering teams for enterprise accounts and industrial supply houses for replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grease pump infrastructure sits at an early-cycle expansion story driven by fleet automation eliminating manual greasing in hazardous mining environments. Penetration remains below saturation across brownfield manufacturing sites resisting Industry 4.0 retrofit.
For Market Incumbents: Fortify backward integration into brushless DC motor production to offset supply concentration in Chinese manufacturing hubs. Deepen captive supply of high-pressure seal kits by acquiring precision fabrication assets in Germany's industrial corridor. This defends margin position against emerging entrants offering modular component mixing.
For New Entrants and Emerging Players: Predictive lubrication software layers represent a service gap where incumbents under-serve mid-tier construction fleets lacking in-house IoT expertise. Target North American equipment rental companies with subscription-based pump monitoring. Deploy mobile-first diagnostics platforms as the go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors condition-monitoring software specialists over hardware fabricators. Long-term viability hinges on lubrication-as-a-service business model maturation. Watch for autonomous haul truck fleet deployment rates as the inflection signal indicating automatic system replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Manufacturing | Captive supply of PTFE components reduces rebuild kit vulnerability from Kansai-region concentration. |
| IoT-Enabled Predictive Lubrication Launch | Cloud analytics convergence allows OEMs to sell subscription monitoring rather than capital hardware. |
| CE-Marked Pump Assembly Certification | EU Machinery Directive compliance opens replacement demand across aging European metalworking infrastructure. |
| Long-Term Service Contract Expansion | Uptime guarantee clauses align vendor economics with mining contractor total-cost-of-ownership priorities. |
| Brushless DC Motor Capacity Buildout | Variable-speed programmability meets Western Australian autonomous fleet specification requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors, fleet operations managers, OEM procurement teams, and aftermarket service heads; and secondary validation through customs trade records, SEC equipment manufacturer filings, EPA emission compliance databases, and EU Machinery Directive certification registries. Bottom-up unit demand modeling triangulated against top-down industrial capex surveys.
Across the projection horizon, the analytical framework segmented volume and value outputs by power source, mobility requirement, end-user industry, and procurement channel. CAGRs derived from equipment replacement cycle analysis and fleet automation penetration curves. Industry-specific forecast inputs incorporated lithium carbonate price indices and autonomous mining vehicle deployment tracking.
Underlying assumptions cover regulatory enforcement continuity for OSHA lockout-tagout and EPA spill prevention standards, with deviation risk concentrated in REACH chemical compliance friction delaying lubricant compatibility certification. Recalibration cycles align with material shifts in fleet automation adoption and carbon-border adjustment mechanism implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Drum Pump Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Solar Fountain Pumps Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Seawater Pump Market