
 Spin-On Hydraulic Filter Market | 2026-2036
Spin-On Hydraulic Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Spin-On Hydraulic Filter Market Analysis
Aftermarket fleet operators is rotating toward higher-efficiency spin-on hydraulic filters as OEM service intervals compress and total cost of ownership calculations gain weight in procurement decisions. Parker Hannifin Corporation leverages its distributed service network to capture recurring replacement volumes across industrial equipment fleets. Donaldson Company, Inc. anchors its position through specialized contamination control solutions that extend hydraulic system life in severe-duty environments. Eaton Corporation Plc competes on integrated hydraulic system design where filtration modules embed directly into power unit architectures.
A spin-on hydraulic filter comprises a cylindrical canister element threaded for quick replacement onto a fixed filter head, typically incorporating pleated cellulose, microglass, or synthetic composite media rated for beta efficiency thresholds and differential pressure collapse ratings. Metal canister construction dominates severe-duty applications where thermal cycling and mechanical shock exceed plastic housing tolerances, while composite material variants gain traction in weight-sensitive transportation equipment seeking corrosion resistance. Microglass filtration media leads technical differentiation as hydraulic systems operate at finer cleanliness codes demanded by precision servo valves and high-pressure piston pumps.
ISO 4406 cleanliness standards and NFPA recommended practices shape baseline filtration specifications across industrial equipment and transportation applications, with EPA non-road emission regulations indirectly tightening hydraulic system reliability requirements that cascade into filter replacement frequency. China's GB standards for hydraulic fluid cleanliness and the EU Machinery Directive's safety integrity specifications further fragment compliance obligations for multinational filter suppliers. Stakeholders must monitor how regional certification divergence affects platform standardization strategies and inventory pooling economics across distributed manufacturing networks.
Market Dynamics
ISO 4406 cleanliness code tightening across industrial hydraulic systems is forcing fleet operators into more frequent filter replacement cycles and higher-efficiency media specifications, compressing service intervals and elevating total cost-of-ownership calculations in procurement decisions.
Growth Catalysts
- EPA Non-Road Emission Regulations:Tier 4 and Stage V compliance mandates for off-highway equipment cascade into hydraulic system reliability requirements that accelerate filter replacement frequency in construction and agricultural machinery.
- China's Industrial Corridor Localization:Domestic OEMs in Shandong and Jiangsu provinces are consolidating hydraulic component sourcing, creating captive demand for standardized spin-on filter platforms across excavator and loader production lines.
- Microglass Media Technology:Beta-rated synthetic microglass filtration is penetrating precision servo valve applications where cellulose media cannot achieve required cleanliness codes for high-pressure piston pump protection.
Market Restraints
- Steel Canister Input Volatility:Cold-rolled steel price fluctuations directly impact metal housing production costs for severe-duty thermal cycling applications where composite alternatives lack mechanical shock tolerance.
- Filter Head Standardization Lock-In:Legacy equipment fleets with proprietary thread specifications and port geometries create switching friction that protects incumbent suppliers and fragments replacement demand.
- Extended-Life Hydraulic Fluids:Synthetic fluid formulations with enhanced oxidation stability are stretching drain intervals, indirectly compressing filter change frequency in cost-sensitive maintenance programs.
Strategic Opportunities
- India's Infrastructure Build-Out:National highway and railway expansion projects are mobilizing earthmoving equipment fleets that lack established aftermarket service networks, opening channel development for filter suppliers.
- Predictive Maintenance Integration:Differential pressure sensors and IoT-enabled filter heads are converging with fleet telematics platforms to enable condition-based replacement scheduling rather than calendar-driven changes.
- EU Green Deal Circular Economy Requirements:Extended producer responsibility frameworks for industrial components are incentivizing recyclable canister designs and remanufactured element programs.
Industry Challenges
- Contamination Control Specialist Scarcity:ISO 4406 cleanliness auditing and hydraulic system diagnostics require certified technicians that OEM dealer networks struggle to retain against industrial fluid power consulting firms.
- Multi-Standard Certification Burden:Simultaneous compliance with GB standards for China-bound equipment, NFPA recommended practices for North American sales, and EU Machinery Directive safety specifications fragments testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spin-On Hydraulic Filter Market |
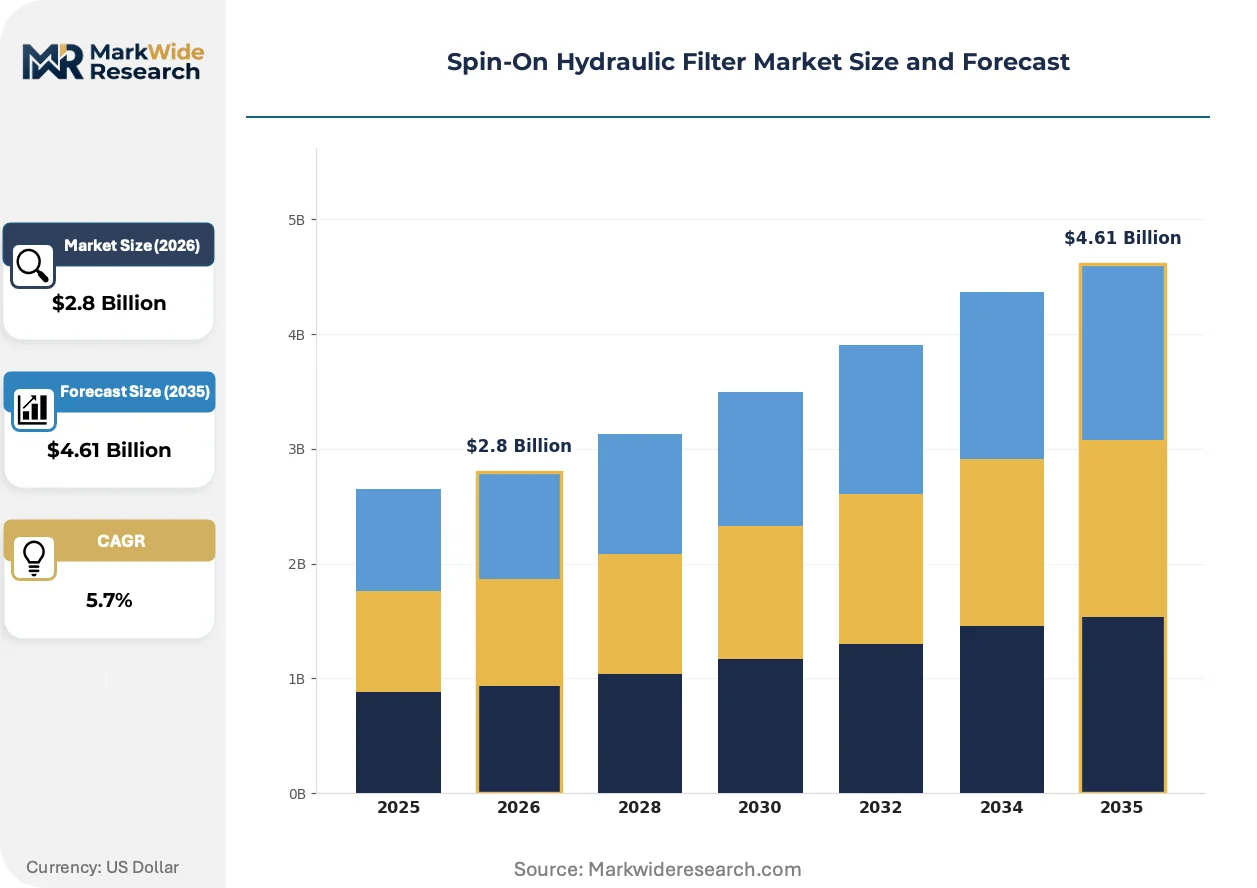
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Canister, Plastic Canister, Composite Material, Engine Oil End User: Automotive OEMs, Heavy Machinery, Agricultural Equipment, Marine Applications Technology: Filtration Media, Spin-On Design, Hydraulic Systems, Microglass Application: Industrial Equipment, Transportation, Construction, Power Generation |
| Companies Covered | Parker Hannifin Corporation, Eaton Corporation Plc, Donaldson Company, Inc., Bosch Rexroth AG, Mahle GmbH, Hydac International GmbH, Schroeder Industries, LLC, Yamashin Filter Corp., Baldwin Filters, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spin-On Hydraulic Filter Market Emerging Trajectories
Hydraulic filtration technology is bifurcating between severe-duty metal construction and lightweight composite alternatives, while regulatory pressure and fleet digitization reshape how replacement demand is triggered and fulfilled.
Microglass composite media is supplanting traditional cellulose in high-pressure applications. Mining equipment operators in Western Australia and Chilean copper districts specify beta-rated synthetic elements for piston pump protection. This transition compresses the addressable market for commodity cellulose suppliers while elevating technical barriers to filter manufacturing.
China's GB standards for hydraulic fluid cleanliness are tightening enforcement through MIIT equipment certification audits. Domestic excavator OEMs must now document ISO 4406 compliance to receive production licenses. This regulatory pressure is accelerating localization of filter supply chains within China's industrial corridor and excluding non-compliant import brands.
Fleet operators are unbundling filter procurement from OEM captive service agreements. Independent aftermarket distributors in Germany's Ruhr industrial region and Texas shale plays now stock multi-brand filter lines. This channel fragmentation pressures manufacturer-direct pricing structures and elevates inventory carrying costs for distributors managing multiple thread specifications.
Spin-On Hydraulic Filter Market Segmentation
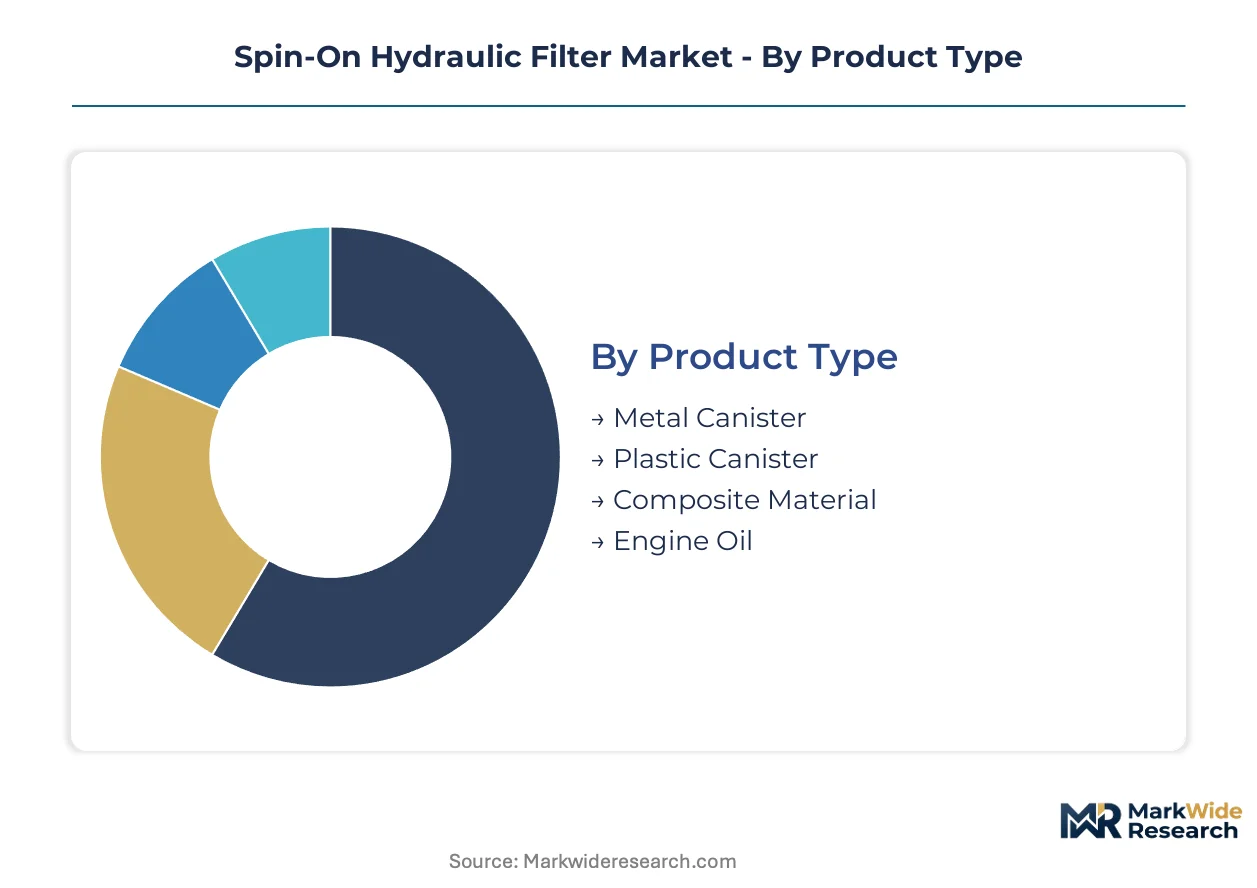
Spin-on hydraulic filter procurement channels diverge sharply by segment. Fleet operators source through independent distributors while OEMs negotiate direct supply agreements. Understanding these channel dynamics exposes margin concentration and inventory pooling economics.
Product Type:
Channel mix varies by housing material durability requirements. Metal canisters flow through severe-duty equipment dealers. Plastic and composite variants concentrate in transportation aftermarket channels.
- Metal Canister:Cold-rolled steel construction withstands thermal cycling and mechanical shock in mining and construction environments. Demand concentrates in Western Australia's iron ore districts and Chilean copper belts where equipment operates continuously under load. EPA Tier 4 reliability mandates accelerate replacement frequency in these severe-duty fleets.
- Plastic Canister:Glass-reinforced nylon housings reduce weight in mobile hydraulic applications. Agricultural OEMs in Iowa and Mato Grosso specify these for tractor implement circuits where corrosion resistance outweighs impact tolerance.
- Composite Material:Carbon-fiber reinforced polymers target aerospace and rail hydraulics requiring electromagnetic neutrality.
- Engine Oil:Cross-application spin-on units serve dual hydraulic and lubrication systems in compact equipment.
By volume, Metal Canister leads. By growth pace, Composite Material is ahead.
End User:
Cost tier stratification separates premium OEM specifications from price-sensitive aftermarket procurement. Each tier demands different certification documentation and technical support intensity.
- Automotive OEMs:Just-in-time delivery contracts require ISO 14001 environmental certification and PPAP documentation. Tier 1 suppliers in Stuttgart and Detroit specify beta-rated microglass media for transmission and power steering circuits.
- Heavy Machinery:Construction and mining fleets prioritize total cost-of-ownership calculations over unit price. Komatsu and Caterpillar dealer networks in Alberta oil sands and Kalgoorlie goldfields stock high-collapse-rated elements for 5000+ psi excavator circuits.
- Agricultural Equipment:Seasonal demand spikes challenge inventory planning. Deere and CNH service channels dominate North American replacement volumes.
- Marine Applications:Salt corrosion resistance drives specification toward specialized coatings and stainless hardware.
Heavy Machinery commands the largest revenue pool. Automotive OEMs show the steepest expansion trajectory.
Technology:
Application maturity determines margin structure. Established spin-on designs compete on logistics efficiency while emerging media technologies capture premium pricing.
- Filtration Media:Pleated cellulose remains the volume standard for general industrial hydraulics. Synthetic microglass penetration accelerates in precision servo valve protection where ISO 4406 codes below 18/16/13 are mandatory.
- Spin-On Design:Thread standardization efforts by NFPA and ISO reduce switching friction between suppliers. Fleet operators in Texas Permian Basin shale plays stock cross-referenced filter lines to minimize downtime risk.
- Hydraulic Systems:Integrated filter-head designs embed directly into power unit architectures.
- Microglass:Beta 1000+ rated synthetic elements achieve sub-3-micron absolute filtration for high-pressure piston pump protection.
Filtration Media generates the highest unit volumes. Microglass is climbing the fastest.
Application:
Customer type fragmentation shapes service intensity. Industrial maintenance contracts demand predictive analytics integration while construction procurement focuses on availability.
- Industrial Equipment:Manufacturing plants in Germany's Ruhr region and China's Yangtze River Delta specify condition-based monitoring with differential pressure sensors. IoT-enabled filter heads transmit clogging data to centralized maintenance platforms.
- Transportation:Fleet operators unbundle filter procurement from OEM service agreements. Independent distributors in Chicago and Rotterdam now stock multi-brand lines supporting mixed fleet compositions.
- Construction:Project-based demand creates irregular replacement patterns. Rental fleet operators in Dubai and Singapore prioritize fast-turn inventory over technical consultation.
- Power Generation:Wind turbine hydraulic pitch systems require extended-life elements with 12+ month change intervals.
Industrial Equipment anchors replacement volume. Transportation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel's petrochemical corridor underwrites North American hydraulic component demand through interconnected refinery and offshore equipment maintenance networks.
United States
EPA Tier 4 Final emission mandates accelerate filter replacement cycles in Permian Basin fracking fleets and Great Plains agricultural machinery. OSHA hydraulic safety directives tighten maintenance documentation requirements for industrial plants. Houston's energy equipment service cluster concentrates aftermarket distribution capacity for Gulf Coast offshore platforms.
Germany
Ruhr industrial region manufacturing plants specify condition-monitored filtration for precision machine tool hydraulics. EU Machinery Directive safety integrity specifications mandate documented contamination control protocols. Stuttgart's automotive tier-one supplier corridor integrates beta-rated microglass elements into transmission and power steering production lines.
China
MIIT equipment certification audits enforce GB standards compliance for excavator OEMs in Shandong and Jiangsu provinces. Dual carbon goals pressure industrial facilities toward predictive maintenance systems that optimize filter change intervals. Yangtze River Delta manufacturing clusters localize hydraulic component sourcing to reduce import dependency.
India
National highway and railway expansion projects mobilize earthmoving equipment fleets lacking established aftermarket networks. BIS certification requirements for hydraulic fluid cleanliness create compliance barriers for unverified import brands. Maharashtra's Pune-Nashik industrial belt attracts filter distributors establishing regional warehousing for construction equipment service.
Australia
Western Australia's Pilbara iron ore districts specify severe-duty metal canister filters for continuous-load mining hydraulics. State-level mine safety regulations mandate documented hydraulic system reliability programs. Kalgoorlie's goldfield equipment service cluster stocks high-collapse-rated elements for 5000+ psi excavator circuits operating in remote desert conditions.
Spin-On Hydraulic Filter Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized contamination control firms. The market structure reflects a tiered competitive field where global fluid power suppliers coexist with regional filtration specialists. Three archetypes dominate: integrated hydraulic system designers, distributed service network operators, and severe-duty application specialists. Capacity expansion and strategic partnerships represent the primary competitive moves as suppliers secure captive demand through OEM embedded designs.
Among diversified industrial conglomerates, Parker Hannifin Corporation and Eaton Corporation Plc exemplify the integrated-systems archetype, anchoring positions through embedded filtration modules within power unit architectures. Donaldson Company, Inc. occupies a position among contamination control specialists focused on severe-duty environments. These three represent distinct strategic postures: service network leverage, system integration depth, and application-specific technical differentiation.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Eaton Corporation Plc |
| Donaldson Company, Inc. |
| Bosch Rexroth AG |
| Mahle GmbH |
| Hydac International GmbH |
| Schroeder Industries, LLC |
| Yamashin Filter Corp. |
| Baldwin Filters, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-day cold-rolled steel inventory cycles at severe-duty filter manufacturers concentrate pricing power among metal canister specialists serving Western Australian mining fleets and Alberta oil sands operators. This lead-time exposure ties unit economics directly to commodity input volatility while compressing margins for distributors managing multi-brand cellulose and microglass inventories.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates beta-rated microglass elements for precision servo valve protection from commodity cellulose filters and private-label alternatives. OEM direct contracts command certification-grade premiums anchored in ISO 14001 environmental documentation and PPAP submission requirements. Cost compression in economy-tier aftermarket channels is intensifying because independent distributors in Texas shale plays and Germany's Ruhr region unbundle procurement from captive service agreements. Fleet operators exhibit highest price sensitivity, while automotive Tier 1 suppliers in Stuttgart and Detroit demonstrate lowest elasticity due to just-in-time reliability mandates.
Supply Chain Analysis
China and Germany anchor global production of hydraulic filtration media and precision-machined filter heads, with domestic OEMs in Shandong and Jiangsu provinces localizing component sourcing under MIIT certification pressure. Cold-rolled steel canister housings, microglass filtration media, and glass-reinforced nylon polymers constitute critical input dependencies. Single-source vulnerability concentrates in beta-rated synthetic element supply where technical barriers limit qualified manufacturers. Distribution runs through OEM captive service networks, independent aftermarket distributors, and rental fleet operators prioritizing fast-turn availability over technical consultation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spin-on hydraulic filter market is recovering from cyclical compression in construction equipment procurement, with fleet replacement demand accelerating as EPA Tier 4 reliability mandates cascade through North American and European installed bases.
For Market Incumbents: Consolidate position through backward integration into microglass media manufacturing and captive supply of high-collapse-rated elements for 5000+ psi excavator circuits. Deepen channel control by embedding IoT-enabled filter heads with differential pressure sensors into fleet telematics platforms, neutralizing the threat of independent distributors unbundling procurement from OEM service agreements. For New Entrants and Emerging Players: Lead with white-space targeting of India's national highway and railway expansion projects, where earthmoving equipment fleets lack established aftermarket service networks and BIS certification requirements create compliance barriers for unverified import brands. Penetrate through technical training partnerships with Maharashtra's Pune-Nashik industrial belt distributors, positioning microglass expertise against commodity cellulose incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core filtration divisions amid portfolio rationalization pressures. Long-term viability hinges on predictive maintenance integration and circular economy compliance under EU Green Deal extended producer responsibility frameworks. Monitor MIIT enforcement intensity in China's industrial corridor as the inflection indicator for localization-driven consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Microglass Media Manufacturing Scale-Up | Captures premium pricing in precision servo valve applications where ISO 4406 codes below 18/16/13 are mandatory. |
| IoT-Enabled Filter Head Development | Embeds differential pressure sensors into power unit architectures, enabling condition-based replacement scheduling for fleet operators. |
| India Channel Infrastructure Build-Out | Establishes regional warehousing and technical training capacity ahead of infrastructure project mobilization in Maharashtra. |
| EU Circular Economy Certification Program | Positions recyclable canister designs and remanufactured element programs under extended producer responsibility frameworks. |
| Backward Integration into Cold-Rolled Steel Supply | Insulates severe-duty metal canister production from commodity price volatility affecting Western Australian mining fleet suppliers. |
Methodological Framework
Operator-level perspectives from maintenance directors at mining and construction fleets, OEM procurement teams at excavator manufacturers, aftermarket service heads at dealer networks, and plant engineers at industrial hydraulics facilities anchored the qualitative base. Primary fieldwork combined with secondary validation from SEC 10-K filings of diversified industrial conglomerates, customs and trade data on cold-rolled steel and filtration media imports, and ISO 4406 cleanliness standard documentation. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, end user, technology, and application segmentation dimensions.
Sensitivity analysis tested forecast robustness across steel price volatility scenarios, regulatory enforcement intensity variations, and fleet digitization adoption curves throughout the projection horizon. Segmentation modeling incorporated housing material durability requirements, cost tier stratification between OEM and aftermarket procurement, media technology maturity, and customer type fragmentation shaping service intensity. CAGRs derived from equipment fleet replacement cycles, ISO cleanliness code tightening trajectories, and regional infrastructure investment pipelines without assuming discrete technology disruption events.
Forecasts assume regulatory continuity in EPA Tier 4 Final emission mandates, EU Machinery Directive safety integrity specifications, and China's GB standards enforcement through MIIT equipment certification audits; material policy shifts would require re-modeling replacement frequency assumptions and localization-driven supply chain configurations. Recalibration cycles align with material shifts in steel input costs, fleet telematics penetration rates, and circular economy framework implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
End Suction Pump Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
Electric Submersible Pump (ESP) in Oil and Gas Market
Pumps and Control Devices
Split Casing Pump Market