
 Chocolate Liqueur Market | 2026-2036
Chocolate Liqueur Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Liqueur Market Outlook
Clean-label formulation is narrowing the gap between artisanal and mass-market chocolate liqueur production. Barry Callebaut leverages its cocoa processing scale to secure consistent bean supply for liqueur applications. Godiva Chocolatier, Inc. anchors its positioning through luxury retail channels and gifting occasions. Mozart Distillerie GmbH specializes in Austrian heritage recipes that command premium shelf placement in European duty-free shops.
Chocolate liqueur denotes an alcoholic beverage produced by blending cocoa extract or chocolate infusion with a distilled spirit base, typically achieving alcohol content between 15% and 25% ABV through maceration or percolation methods. Cream Liqueur dominates volume due to its dessert pairing versatility and lower alcohol threshold appealing to casual consumers. Dark Liqueur captures the fastest growth trajectory as mixologists incorporate bitter cocoa profiles into craft cocktail programs. Online Retail is expanding fastest among distribution channels, though Supermarkets still control the largest revenue pool through impulse and seasonal displays.
FDA oversees alcohol beverage labeling and allergen disclosure in the United States, while EMA and national regulators across Europe enforce EU Spirit Drinks Regulation standards for geographic indication and minimum alcohol content. These frameworks shape formulation choices, import eligibility, and marketing claims for chocolate liqueur producers operating across multiple jurisdictions. Stakeholders must monitor evolving sugar taxation and low-alcohol thresholds as these policy levers increasingly influence product architecture and market access decisions.
Market Dynamics
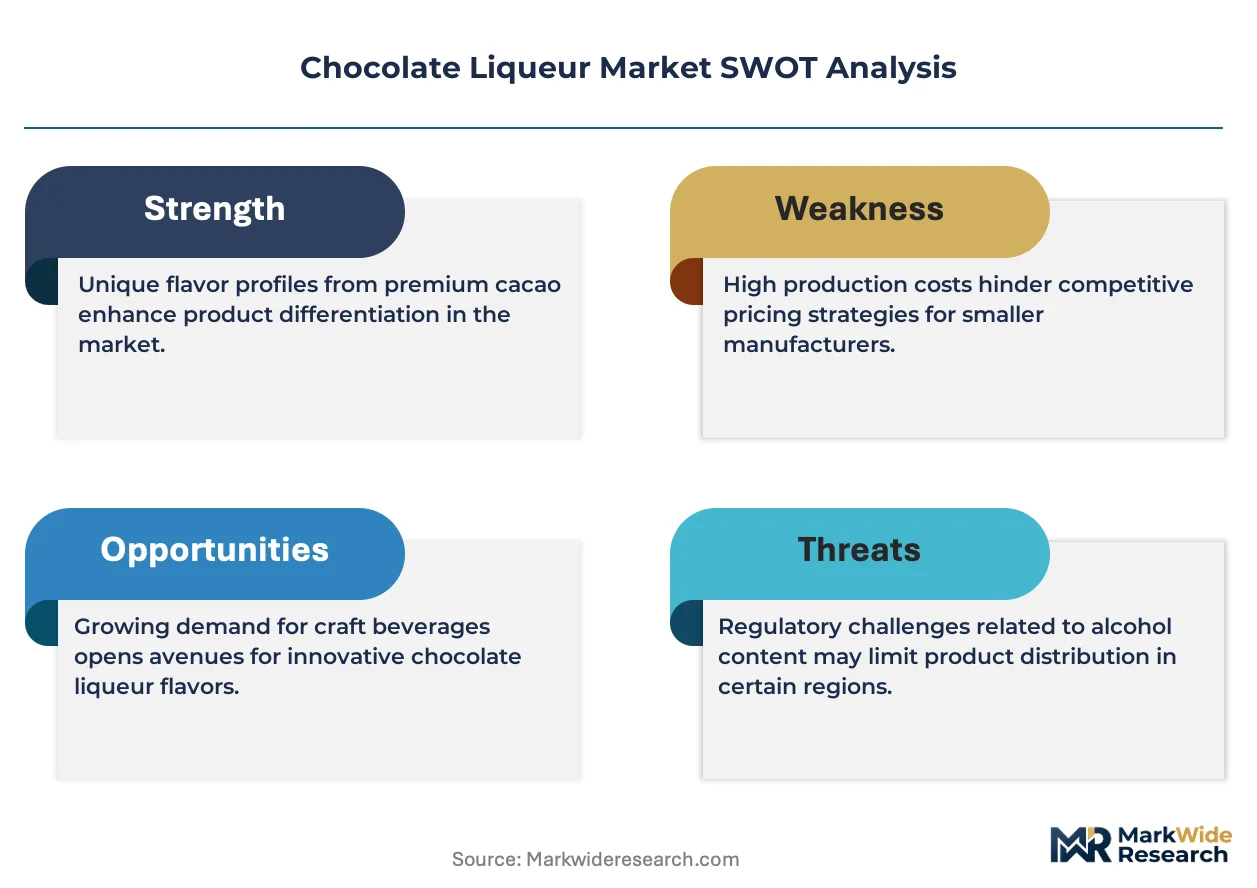
Clean-label formulation pressure is compressing margins for mass-market producers while rewarding heritage distillers with transparent supply chains. The EU Spirit Drinks Regulation's geographic indication enforcement and evolving FDA allergen disclosure rules are forcing reformulation investments across the value chain.
Growth Catalysts
- Premium Cocktail Culture:Upscale bars in New York, London, and Berlin are incorporating dark chocolate liqueur into craft cocktail programs, expanding the addressable occasion set beyond dessert pairing.
- EU Spirit Drinks Regulation:Geographic indication protections for Austrian and German heritage recipes create defensible market positions for traditional producers in duty-free and gifting channels.
- Cocoa Processing Scale:Industrial chocolate manufacturers backward integrating into liqueur ingredient supply are securing consistent bean quality and reducing input volatility for contracted distillers.
Market Restraints
- Cocoa Price Volatility:West African supply concentration and weather-driven crop variability create persistent margin pressure for producers without long-term bean contracts.
- Sugar Taxation Thresholds:United Kingdom and South Africa sugar levies are compressing formulation flexibility and forcing ABV or sweetness trade-offs in export-bound products.
- Wine and Craft Beer Substitution:Lower-alcohol dessert wines and flavored craft beers are capturing casual occasion drinkers who previously selected cream liqueurs.
Strategic Opportunities
- Online Retail Channel Expansion:Direct-to-consumer platforms in Germany and the United States are bypassing traditional three-tier distribution, enabling margin capture and customer data ownership.
- Low-Alcohol Formulation:Sub-15% ABV products align with evolving WHO consumption guidelines and open placement in grocery retail channels with restricted liquor licenses.
- Bean-to-Bottle Provenance:Single-origin cocoa sourcing with blockchain traceability is commanding premium shelf placement in Swiss and Japanese specialty retailers.
Industry Challenges
- Master Distiller Talent Scarcity:Converged expertise in cocoa chemistry and spirit maturation is concentrated among aging specialists in Austria and Belgium, constraining production scale-up.
- Multi-Jurisdiction Label Compliance:Divergent FDA, EMA, and national regulator disclosure timelines are extending product launch cycles and inflating regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Liqueur Market |
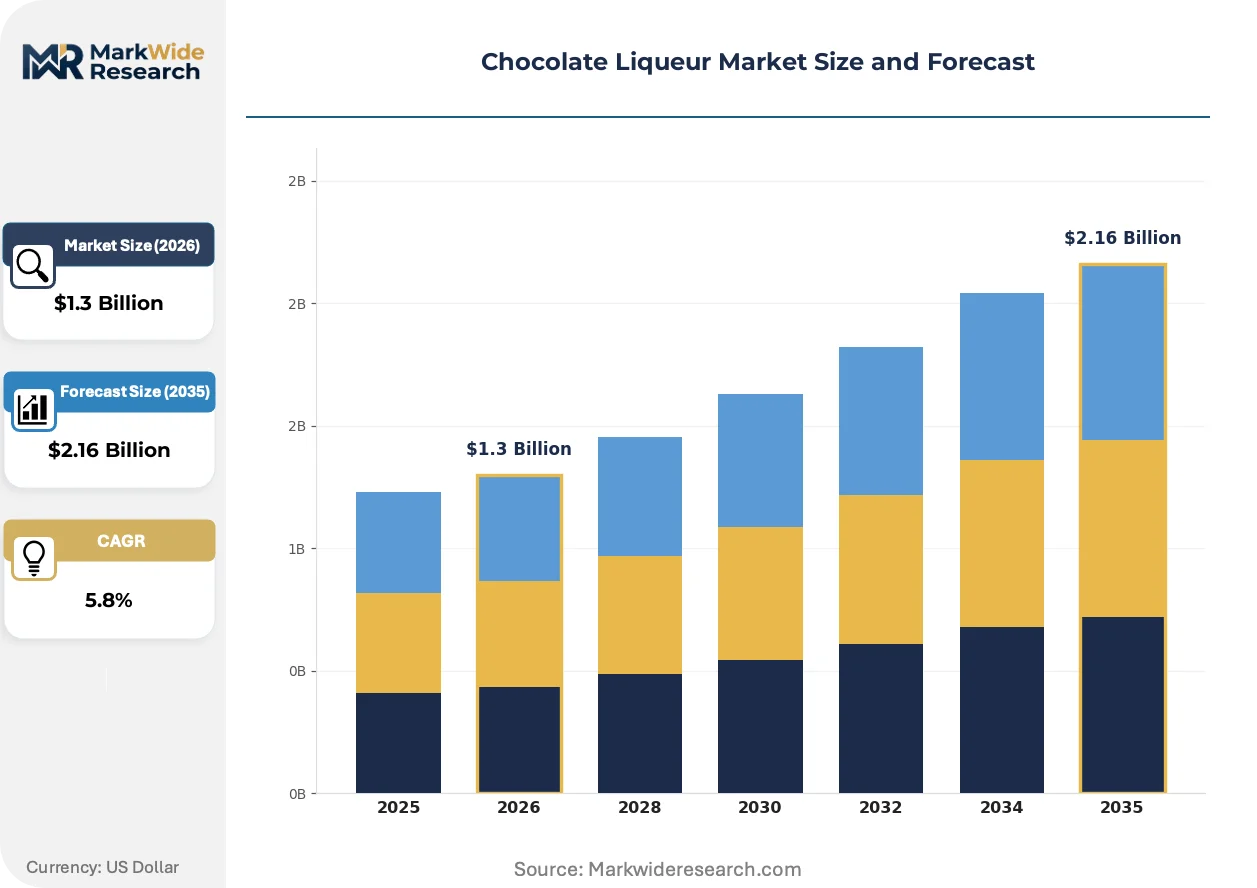
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.16 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Liqueur, Dark Liqueur, White Liqueur, Spiced Liqueur Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Duty-Free Shops Packaging Type: Glass Bottles, Plastic Bottles, Tetra Packs, Jar Packaging Customer Type: Individuals, Bars, Restaurants, Retailers |
| Companies Covered | Mondelez International Inc., Mars Incorporated, Ferrero International S.A., Barry Callebaut, Nestlé S.A., The Hershey Company, Cargill, Incorporated, Godiva Chocolatier, Inc., Mozart Distillerie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Liqueur Market Strategic Shifts
Digital traceability infrastructure is converging with heritage production methods, creating tension between artisanal authenticity claims and industrial scale requirements. Three developments are actively restructuring competitive positioning.
Blockchain-enabled provenance tracking is digitizing supply chain transparency for cocoa sourcing. Premium distillers in Switzerland and Belgium are adopting distributed ledger verification to substantiate single-origin claims. This technology is digitizing the documentation burden that previously favored mass-market producers with established quality control departments.
The EU Green Deal's Farm-to-Fork Strategy is tightening sustainability disclosure requirements for agricultural inputs. Chocolate liqueur producers must now document deforestation-free cocoa sourcing back to plantation level. German and Austrian heritage brands with established direct farmer relationships are adapting faster than competitors reliant on commodity bean markets.
Mixology education platforms are compressing the knowledge gap between professional bartenders and home enthusiasts. Online certification programs from the United States and United Kingdom are democratizing technique access, expanding the skilled consumer base capable of appreciating bitter cocoa profiles. Japan's craft cocktail bars are responding fastest, incorporating dark liqueur into tasting-menu pairings previously reserved for wine or sake.
Chocolate Liqueur Market Segmentation
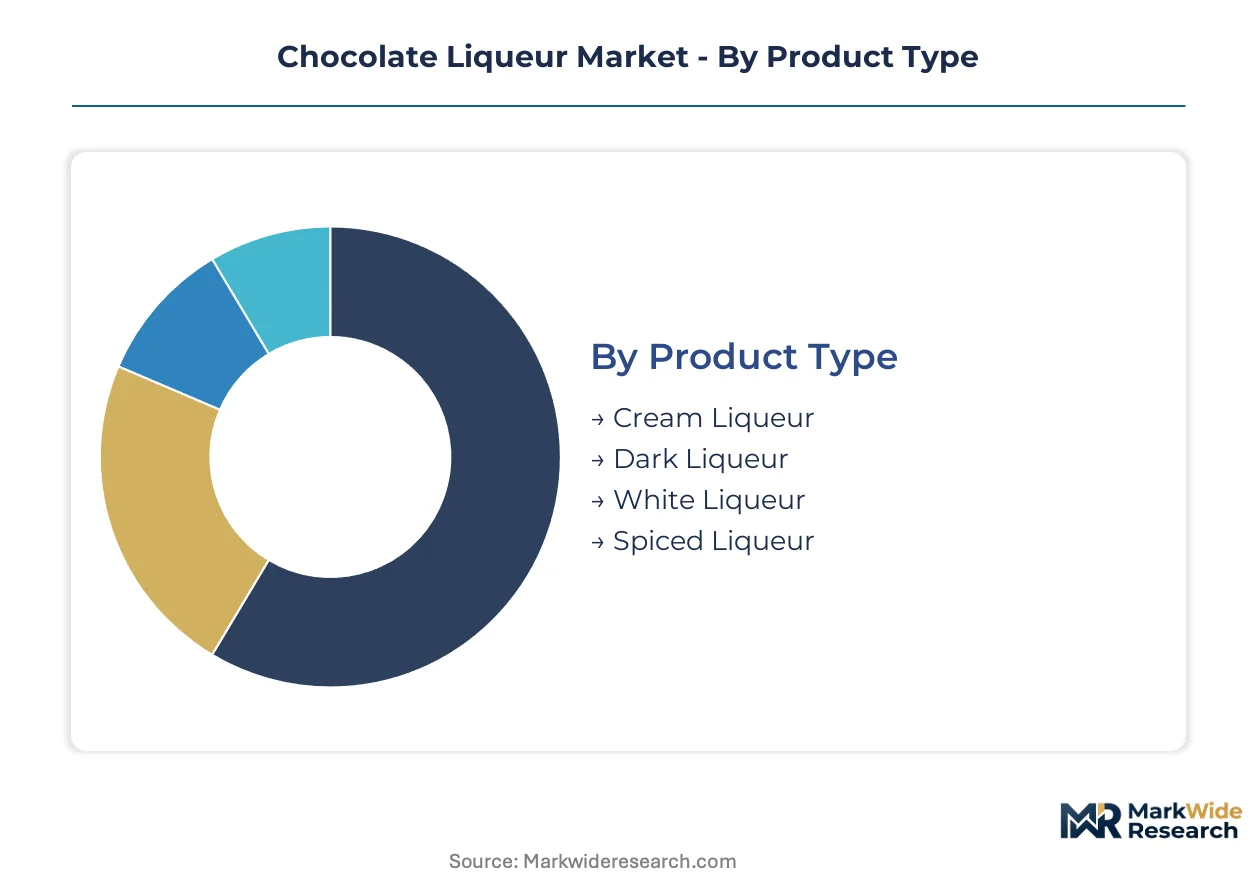
Chocolate liqueur producers navigate divergent occasion sets and channel economics through precise segment targeting. Product architecture and packaging choices directly determine placement eligibility across regulated alcohol retail environments.
Product Type:
Mature dessert-pairing formats coexist with emerging cocktail-forward profiles across the maturity spectrum.
- Cream Liqueur:Dairy-infused formulations achieve 15-17% ABV through emulsified cocoa cream bases. German and Austrian heritage producers anchor volume through duty-free gifting channels where viscosity and sweetness signal quality to casual consumers.
- Dark Liqueur:Bitter cocoa extractions without dairy emulsification permit higher alcohol integration and cleaner cocktail integration. Brooklyn, Berlin, and Tokyo mixology programs are driving placement in craft bar backbars where bartenders prize controlled dilution properties.
- White Liqueur:Cocoa butter-forward profiles with muted chocolate intensity target confectionery crossover drinkers seeking dessert-adjacent experiences without dark cocoa bitterness.
- Spiced Liqueur:Cinnamon, chili, or cardamom infusions layered over chocolate bases create seasonal limited-release opportunities in North American holiday retail.
Cream Liqueur handles the majority of throughput; Dark Liqueur is expanding most quickly on share.
Distribution Channel:
Channel economics stratify sharply between impulse-driven physical retail and data-rich direct commerce.
- Supermarkets:Seasonal display placement and checkout-adjacent positioning capture unplanned purchases during holiday periods. German and US retailers with restricted liquor licenses favor lower-ABV cream formats that qualify for grocery aisle placement.
- Online Retail:Direct-to-consumer platforms bypass three-tier distribution markups in jurisdictions with permissive shipping laws. Producers in California and Bavaria are building first-party customer databases through subscription gifting programs.
- Specialty Stores:Curated independent retailers in Switzerland and Belgium provide education-intensive environments for single-origin and bean-to-bottle provenance storytelling.
- Duty-Free Shops:Travel retail exclusives with augmented packaging command premium price multiples in Frankfurt, Heathrow, and Dubai airport corridors.
Supermarkets retain the largest revenue pool; Online Retail is climbing the fastest on channel share.
Packaging Type:
Material selection trades barrier properties against sustainability positioning and shipping economics.
- Glass Bottles:Inert barrier protection preserves volatile aromatic compounds across multi-year shelf life requirements. Premium positioning in Japanese and Swiss specialty retail demands heavyweight molded glass with embossed heritage markings.
- Plastic Bottles:PET and HDPE formats reduce freight cost per unit for mass-market cream liqueurs distributed through high-volume supermarket chains in the United Kingdom and South Africa.
- Tetra Packs:Aseptic carton technology enables ambient-stable formulations with reduced refrigeration burden in emerging market retail with inconsistent cold chain infrastructure.
- Jar Packaging:Wide-mouth containers support spoonable dessert applications and confectionery hybrid positioning in artisanal European markets.
Glass Bottles dominate premium placement; Plastic Bottles are gaining share fastest in volume-focused channels.
Customer Type:
End-user sophistication spans unplanned individual consumption through programmed hospitality procurement.
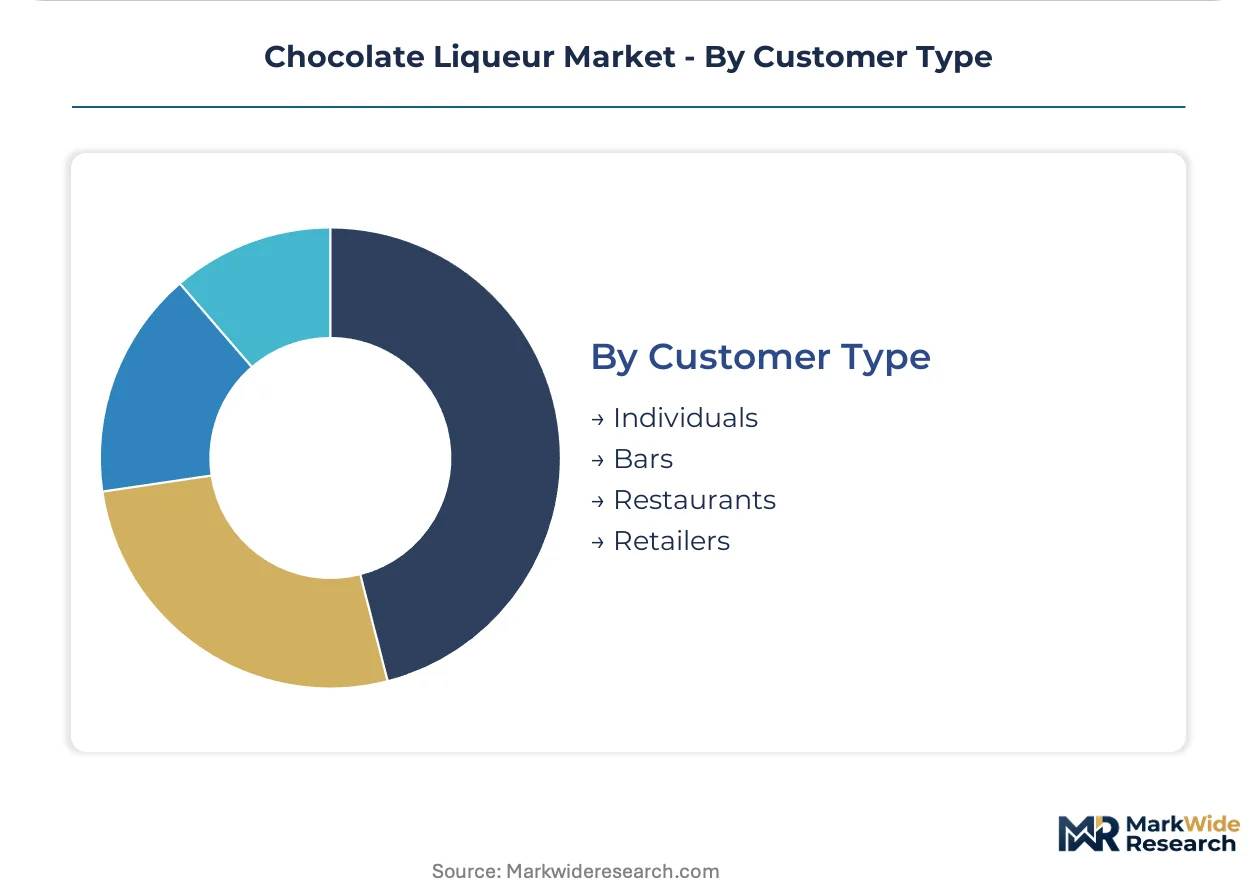
- Individuals:Gifting occasions and home mixology experimentation drive purchase frequency among affluent urban consumers in London, New York, and Singapore.
- Bars:Backbar placement decisions hinge on bottle aesthetics and pour cost efficiency for cocktail program integration in craft-focused establishments.
- Restaurants:Dessert menu pairing and tasting menu sequencing create demand for controlled-pour formats in Michelin-tier kitchens across France and Japan.
- Retailers:Curated assortment decisions by independent merchants and chain buyers determine brand discoverability in fragmented specialty alcohol markets.
Individuals generate the highest transaction frequency; Bars are the fastest-expanding customer type on volume contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chocolate liqueur exports flow primarily into duty-free corridors at Frankfurt and Munich airports, with secondary demand clusters forming in Swiss and Austrian alpine retail.
Germany
Heritage distillers in Bavaria and Baden-Württemberg anchor European volume through Easter and Christmas gifting seasons. The EU Spirit Drinks Regulation enforces geographic indication protections for traditional recipes. Frankfurt Airport duty-free exclusives command premium multiples through augmented packaging formats targeting Asian transit passengers.
United States
Craft cocktail adoption in Brooklyn, Manhattan, and Los Angeles expands dark liqueur placement beyond dessert occasions. FDA allergen disclosure rules and state-level three-tier distribution laws shape formulation and channel access. California direct-to-consumer platforms bypass traditional wholesale markups through subscription gifting programs.
Switzerland
Single-origin cocoa sourcing commands premium positioning in Zurich and Geneva specialty retail. Swissmedic and federal food safety frameworks mandate traceability documentation for deforestation-free supply chains. Bean-to-bottle producers in the Lake Geneva region leverage blockchain verification for Japanese export markets.
Japan
Mixology-forward consumption in Tokyo and Osaka integrates dark liqueur into tasting-menu pairings. METI guidelines on sustainable sourcing align with EU Green Deal disclosure requirements for imported spirits. Craft cocktail bars in Roppongi and Ginza anchor demand for controlled-pour formats in Michelin-tier venues.
United Kingdom
Sugar taxation thresholds compress formulation flexibility for cream liqueurs bound for supermarket chains. HM Revenue and Customs excise classifications determine ABV breakpoints for grocery aisle placement. London independent retailers sustain education-intensive environments for provenance-focused Austrian and German imports.
Chocolate Liqueur Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tiering. The vendor base clusters around three strategic archetypes: industrial chocolate manufacturers backward integrating into ingredient supply, heritage distillers leveraging geographic indication protections, and luxury confectionery brands extending into spirits. Dominant competitive moves include portfolio diversification into low-ABV formats and direct-to-consumer platform development bypassing three-tier distribution.
Among industrial-scale cocoa processors, Barry Callebaut exemplifies upstream integration into liqueur ingredient supply. Heritage specialists occupy the premium tier, with Mozart Distillerie GmbH representing Austrian geographic indication positioning in European duty-free channels. Godiva Chocolatier, Inc. anchors luxury retail extension strategies through gifting-occasion packaging.
| Leading Market Players |
|---|
| Mondelez International Inc. |
| Mars Incorporated |
| Ferrero International S.A. |
| Barry Callebaut |
| Nestlé S.A. |
| The Hershey Company |
| Cargill, Incorporated |
| Godiva Chocolatier, Inc. |
| Mozart Distillerie GmbH |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in West African cocoa processing is tightening bean availability for European distillers and amplifying spot-price volatility in chocolate liqueur ingredient markets. This utilization squeeze forces producers to choose between long-term contract premiums and exposure to commodity swings, reshaping both cost structures and supplier relationships across the value chain.
Pricing Analysis
Heritage-recipe pricing gaps separate Austrian geographic indication products from mass-market cream formulations and emerging bean-to-bottle premium tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by cocoa origin certification and vertical integration depth. Cost compression in mass-market cream liqueurs is intensifying because sugar taxation in the United Kingdom and South Africa forces ABV or sweetness trade-offs. Casual dessert-pairing consumers show highest price sensitivity, while Japanese mixology venues and Swiss specialty retailers absorb premium markups for provenance-verified dark liqueurs.
Supply Chain Analysis
EU deforestation-free sourcing regulations function as export-control regime equivalents, restricting cocoa flows from non-compliant West African plantations and forcing supply chain reconfiguration. Côte d'Ivoire, Ghana, and Ecuador anchor raw material supply, with German and Austrian distillers drawing from established direct-farmer relationships. Single-source vulnerability concentrates in West African bean supply exposed to weather-driven crop variability. Distribution runs through three-tier wholesale networks in the United States, direct-to-consumer platforms in Germany, and duty-free travel retail corridors at Frankfurt and Dubai airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chocolate liqueur markets are approaching a platform-economics inflection where direct-to-consumer data ownership and mixology education platforms reshape competitive moats. Interoperability between blockchain traceability systems and EU Green Deal disclosure requirements is creating new ecosystem entry barriers.
For Market Incumbents: Entrench geographic indication protections through accelerated EU Spirit Drinks Regulation compliance investments in Bavaria and Baden-Württemberg. Deepen backward integration into cocoa processing to secure bean supply against West African volatility. Lock in duty-free channel exclusives with augmented packaging formats before travel retail recovery saturates premium placement.
For New Entrants and Emerging Players: Low-alcohol sub-15% ABV formulations for United States grocery retail with restricted liquor licenses represent the most penetrable entry point. Japanese craft cocktail bars seeking tasting-menu liqueur pairings offer white-space demand for controlled-pour dark liqueur formats. California direct-to-consumer subscription gifting programs provide a go-to-market angle bypassing three-tier distribution markups.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bean-to-bottle provenance infrastructure as blockchain verification and deforestation-free documentation requirements multiply fixed costs. Heritage distillers with established direct-farmer networks in Austria and Germany present acquisition profiles with defensible margin structures. Monitor EU sugar taxation expansion and WHO consumption guideline revisions as inflection indicators for low-alcohol formulation viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | California and Bavaria subscription programs bypass three-tier markups and capture first-party customer data. |
| Bean-to-Bottle Provenance Investment | Swiss and Japanese specialty retailers command premium shelf placement for blockchain-verified single-origin sourcing. |
| Low-Alcohol Formulation Development | Sub-15% ABV products unlock United Kingdom and South Africa grocery aisle placement under sugar taxation thresholds. |
| Geographic Indication Certification | EU Spirit Drinks Regulation enforcement creates defensible positioning in Frankfurt and Heathrow duty-free corridors. |
| Mixology Education Partnership | Brooklyn and Tokyo craft cocktail programs expand dark liqueur occasion sets beyond dessert pairing. |
Study Parameters
Cross-validation between primary interviews with master distillers, cocoa procurement leads, and specialty retail buyers anchors the qualitative findings against secondary validation from EU Spirit Drinks Regulation filings, FDA allergen disclosure guidance, and customs trade data. Bottom-up volume modeling triangulates with top-down value estimates across product type, distribution channel, and regional regulatory cluster dimensions.
Calibration against historical volume trajectories and elasticity assumptions shapes the analytical framework over the projection horizon. Segmentation dimensions include cream versus dark versus white liqueur formats, supermarket versus online retail versus duty-free channel economics, and geographic indication-protected versus mass-market positioning. CAGRs derive from iterative reconciliation of input cost scenarios, regulatory timeline assumptions, and occasion-set expansion rates in craft cocktail adoption clusters.
Practitioners should monitor cocoa price volatility spikes, EU deforestation-free sourcing enforcement timelines, and sugar taxation threshold adjustments for early signals of forecast divergence. Material shifts in West African supply concentration or WHO low-alcohol consumption guideline adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Glass Chillers Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Sparkling Red Wine Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market