
 White Spirits Market | 2026-2036
White Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
White Spirits Market Analysis
The capital-intensity divergence between integrated refiners and specialty solvent blenders is unwinding competitive dynamics across the white spirits value chain. ExxonMobil Corporation leverages its integrated refining footprint to sustain cost-advantaged feedstock access for high-purity aliphatic production. Shell plc anchors its position through controlled distribution networks spanning industrial chemical channels. Hindustan Petroleum Corporation Limited competes on geographic proximity to South Asian manufacturing demand.
White spirits comprise refined petroleum distillates with a boiling range typically spanning 150°C to 220°C, consisting primarily of C7-C12 aliphatic hydrocarbons used as solvents in paints, varnishes, and industrial cleaning applications. The product type dimension shows vodka commanding established volume while gin extracts premium positioning through craft distillation positioning. Glass bottles dominate packaging structures due to chemical compatibility and brand aesthetics, though PET bottles are gaining traction in cost-sensitive retail channels where logistics efficiency shapes procurement decisions.
EPA regulations in the United States enforce volatile organic compound emission limits that constrain conventional white spirits formulations in architectural coatings. REACH compliance requirements in Europe mandate full substance registration and hazard communication, elevating compliance costs for imported solvent volumes. India's BIS certification standards govern solvent purity specifications for domestic industrial applications. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate product portfolios and manufacturing location strategies.
Market Dynamics
REACH compliance deadlines and EPA volatile organic compound limits are forcing simultaneous reformulation of solvent-grade white spirits across European and North American coatings manufacturing, compressing margins for conventional aliphatic producers while opening premium positioning for low-aromatic alternatives.
Growth Catalysts
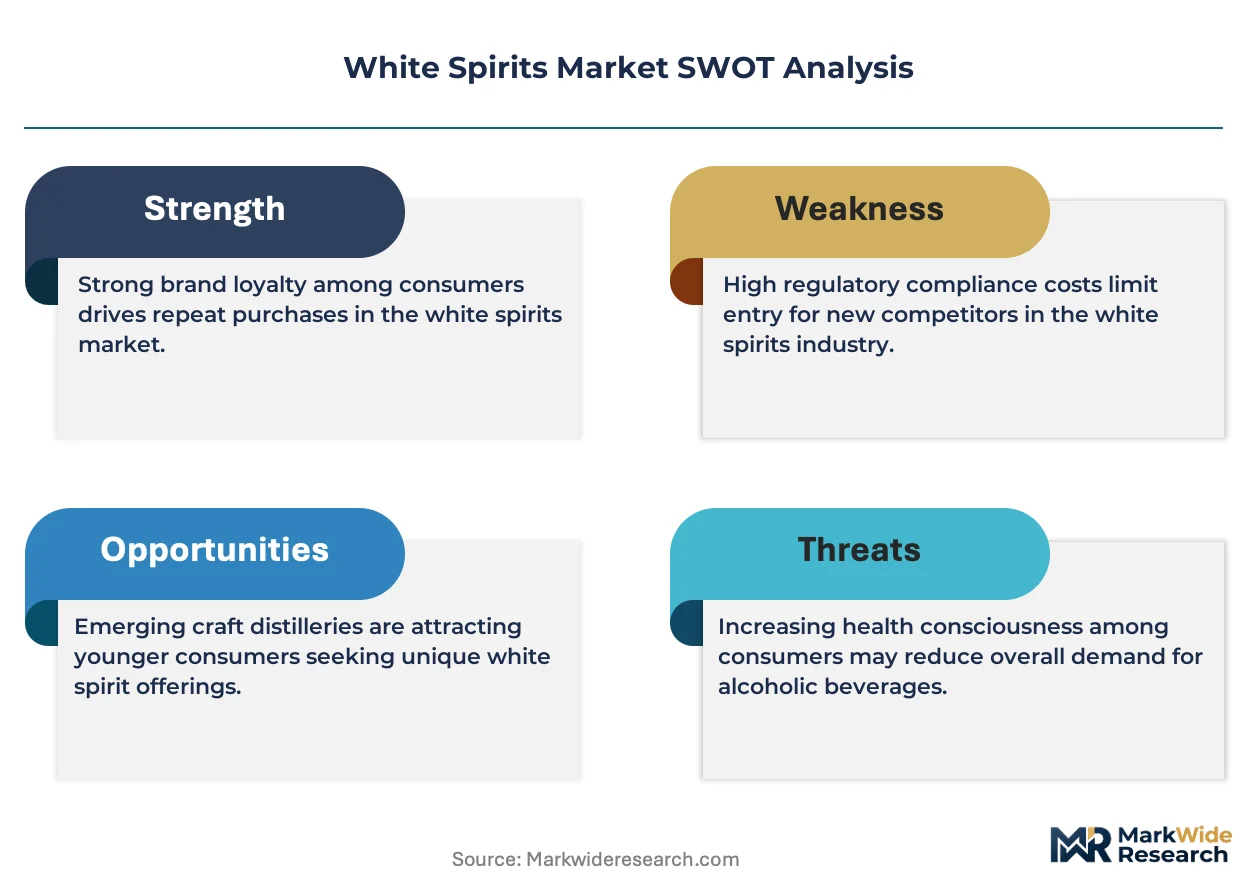
- Construction coatings demand in India:Industrial cluster expansion around Mumbai and Gujarat is accelerating solvent consumption for architectural and protective coatings applications.
- REACH registration completion:Full substance registration under ECHA guidelines has clarified compliance pathways, reducing import friction for certified European suppliers.
- Low-aromatic solvent technology:Advanced hydrodesulfurization processes are enabling premium-grade production that meets tightening occupational exposure limits in manufacturing settings.
Market Restraints
- Naphtha feedstock volatility:Crude-linked input costs for C7-C12 aliphatic fractions create margin unpredictability for non-integrated blenders.
- Waterborne coating substitution:Latex and acrylic emulsion technologies are capturing share in interior architectural applications previously served by solvent-borne systems.
- Import dependency concentration:Specialty solvent supply for European manufacturers concentrates through Rotterdam-Antwerp refining corridors, creating geographic vulnerability.
Strategic Opportunities
- Southeast Asian manufacturing migration:Vietnam and Indonesia industrial zones present underpenetrated demand for metal finishing and automotive refinish solvents.
- Recycled solvent recovery services:Closed-loop distillation and reclamation offerings create recurring revenue attachment to virgin solvent sales.
- EU Green Deal alignment:Bio-based hydrocarbon feedstock certification opens public procurement channels and sustainability-premium positioning.
Industry Challenges
- Reformulation technical capacity:Shortage of solvent chemists capable of balancing volatility, solvency power, and regulatory compliance in coating system redesign.
- Multi-jurisdiction certification lag:Sequential BIS, REACH, and EPA registration timelines delay product launches by 18-24 months for new solvent grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Spirits Market |
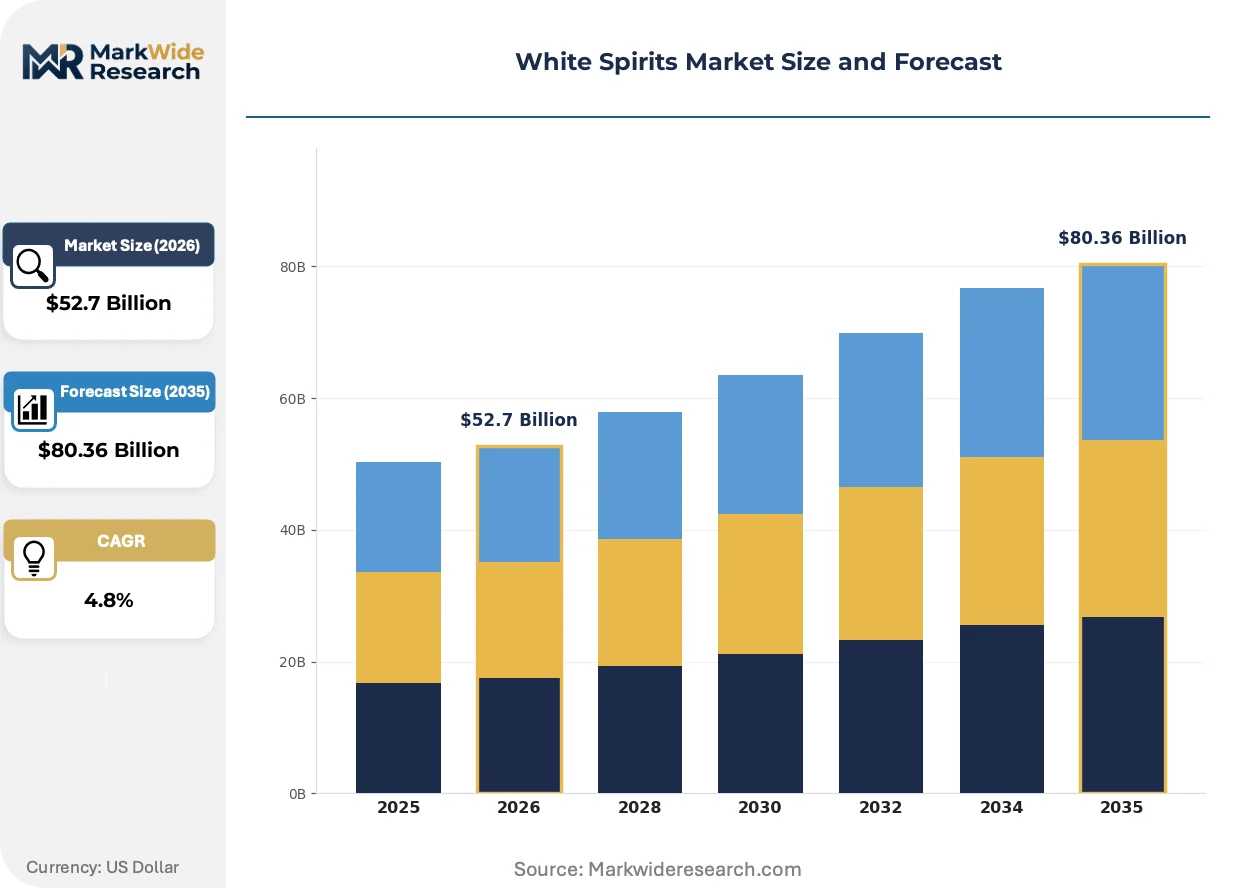
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vodka, Gin, Grappa, Absinthe End User: Bars, Restaurants, Retailers, Online Stores Packaging Type: Glass Bottles, Cans, Tetra Packs, PET Bottles Distribution Channel: Wholesale, Direct Sales, E-commerce, Supermarkets |
| Companies Covered | CEPSA, BP p.l.c., ExxonMobil Corporation, JX Nippon Oil & Energy Corporation, Hindustan Petroleum Corporation Limited, Shell plc, Neste Oyj, DHC Solvent Chemie GmbH, TotalEnergies SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Spirits Market Emerging Trajectories
Formulation science is pivoting toward reduced-aromatic and bio-derived alternatives as occupational health standards tighten and industrial buyers consolidate solvent procurement around certified suppliers with documented sustainability credentials.
Membrane separation and advanced adsorption technologies for solvent purification are supplanting conventional acid-wash and clay-treatment finishing processes. Coatings manufacturers in Germany and the Netherlands are adopting these methods to achieve sub-0.1% aromatic specifications required for workplace exposure compliance. The shift is compressing demand for traditional solvent grades while rewarding producers with integrated advanced finishing capabilities.
EPA enforcement of volatile organic compound limits under the Clean Air Act is constraining conventional white spirits in architectural coatings. Manufacturers are responding by accelerating waterborne system development and qualifying low-VOC exempt solvents for remaining solvent-borne applications. The pressure concentrates most intensely on small-to-mid-scale coating formulators lacking dedicated regulatory affairs capacity.
Industrial buyers are consolidating solvent procurement through qualified supplier programs that bundle technical service, inventory management, and waste handling. Direct distribution relationships are displacing traditional chemical distributor intermediaries in North American manufacturing corridors. The restructuring is most visible in automotive OEM and metal fabrication sectors where just-in-time solvent delivery has become a procurement requirement.
White Spirits Market Segmentation
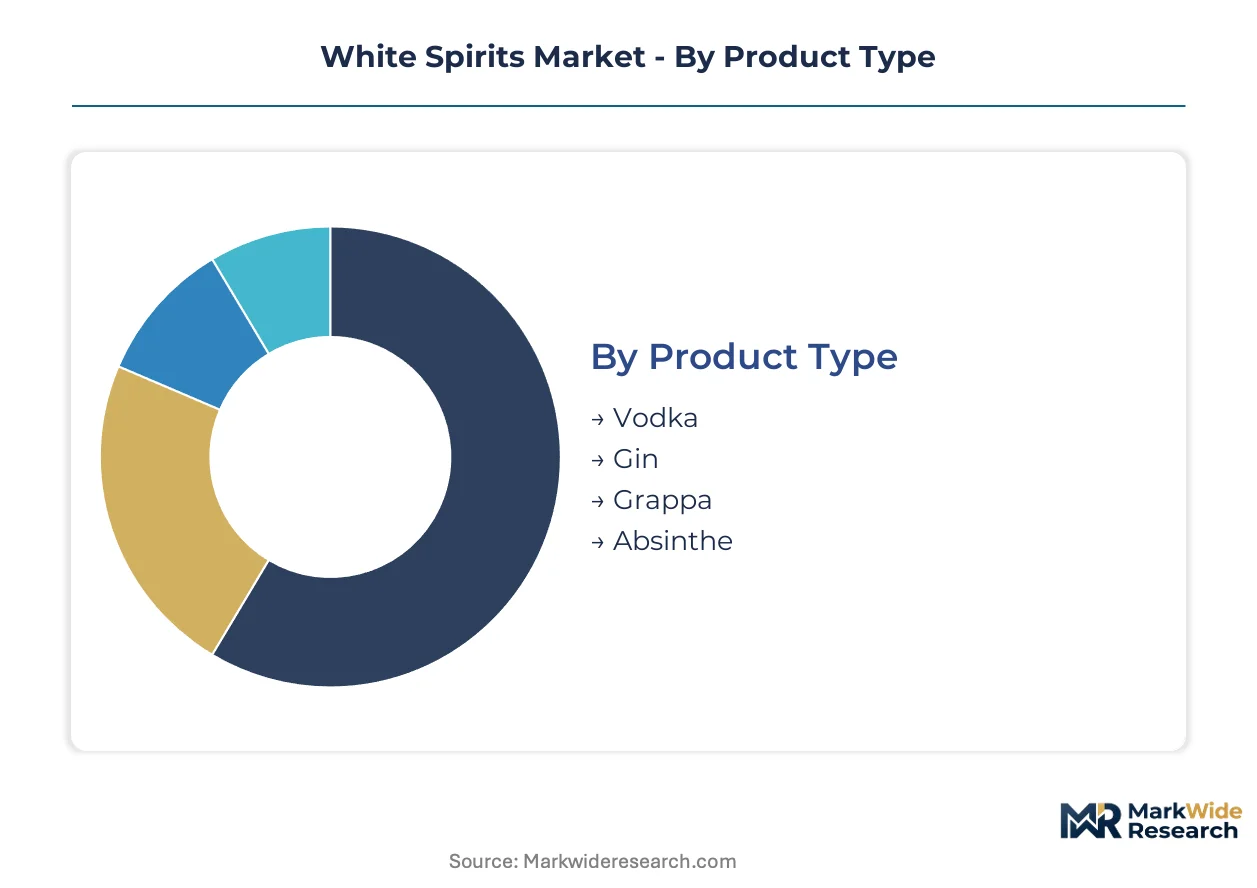
White spirits segmentation reveals divergent vulnerability profiles across consumption channels and packaging formats. Substitution pressures from craft beer, ready-to-drink cocktails, and non-alcoholic alternatives concentrate unevenly across these dimensions, reshaping investment priorities for distillers and distributors.
Product Type:
Vodka faces the most intense substitute threat from flavor-neutral ready-to-drink offerings and premium bottled water positioning, while gin's botanical complexity creates defensive moats against direct replacement.
- Vodka:Neutral grain or potato distillate typically filtered through activated carbon or charcoal to achieve clarity and smoothness. Demand concentrates in Eastern European markets and North American nightclub channels where mixability drives volume procurement. Waterborne coating substitution in industrial applications has no parallel here, but vodka's commodity positioning leaves it exposed to private-label erosion.
- Gin:Juniper-forward spirit with secondary botanical infusions ranging from citrus peel to exotic spices. Craft distillation in England, Spain, and the United States commands premium pricing through provenance storytelling and small-batch scarcity. Regulatory divergence on juniper content minimums between EU spirits regulations and US TTB standards complicates cross-border formulation.
- Grappa:Pomace brandy distilled from pressed grape skins in Italian viticulture regions. Aging regulations under EU spirits framework constrain production geography.
- Absinthe:Anise-flavored spirit with historical thujone content restrictions now relaxed in most jurisdictions. Niche consumption centers in France, Switzerland, and Czech Republic.
Vodka anchors the volume base while gin gains share at the steepest rate.
End User:
Margin tiering separates on-premise consumption with service attachment from off-premise retail where logistics efficiency and shelf placement determine profitability.
- Bars:High-velocity consumption environments where pour cost management and back-bar visibility drive brand selection. Premium vodka and gin placements concentrate in metropolitan cocktail destinations.
- Restaurants:Food-pairing occasions and wine-list integration shape spirits procurement, with Italian restaurants anchoring grappa volume.
- Retailers:Licensed liquor stores and independent merchants controlling allocated releases and store-pick single barrels. Geographic concentration in control states versus open markets fragments distribution strategy.
- Online Stores:Direct-to-consumer shipping legality varies by US state and EU member nation, constraining addressable market. Three-tier system compliance in the United States creates structural barriers absent in European markets.
Bars and restaurants capture the highest per-liter margin while online channels climb fastest where regulatory permits.
Packaging Type:
Material science and supply chain configuration directly determine cost structure and brand positioning latitude across container formats.
- Glass Bottles:Chemically inert silica-based containers with superior oxygen barrier properties and premium aesthetic associations. Weight and fragility elevate logistics costs, concentrating procurement near production facilities.
- Cans:Aluminum roll-stock forming with internal epoxy linings preventing metallic taint. RTD cocktail proliferation has normalized canned spirits in outdoor and festival consumption occasions.
- Tetra Packs:Laminated paperboard with aluminum foil layers enabling ambient distribution. Cost-sensitive emerging markets in Africa and Southeast Asia drive adoption for bulk vodka.
- PET Bottles:Lightweight polyethylene terephthalate with oxygen scavenger additives for shelf stability. Travel retail and airline duty-free channels favor PET for weight restrictions.
Glass bottles dominate value capture while cans expand most quickly in ready-to-serve formats.
Distribution Channel:
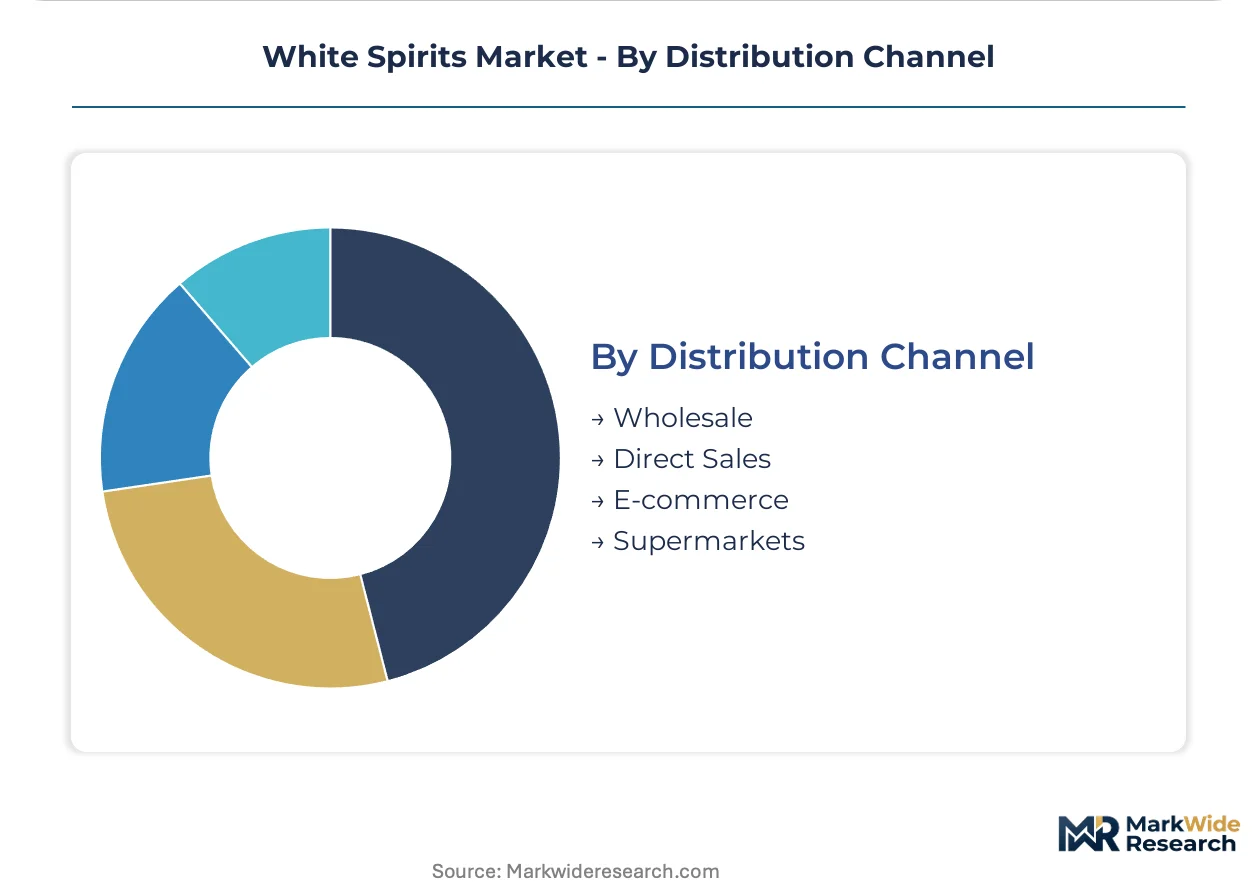
Channel power asymmetries between consolidated retail buyers and fragmented wholesale intermediaries reshape margin distribution across the value chain.
- Wholesale:Licensed distributors holding state or regional exclusivities under US three-tier architecture. Inventory carrying requirements and payment terms strain smaller craft distillers.
- Direct Sales:Distillery tasting rooms and brand homes capturing full retail margin. Regulatory constraints on volume limits and interstate shipping fragment operational scalability.
- E-commerce:Platform-mediated sales with age verification and delivery compliance burdens. Amazon and specialized spirits retailers compete on selection depth and subscription model innovation.
- Supermarkets:Grocery chains with spirits licenses in jurisdictions permitting such sales. Private-label development and category management discipline compress branded supplier margins.
Wholesale maintains volume concentration while direct sales deliver the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's specialty solvent channels exceeds margins available to Indian commodity blenders by substantial multiples. Rotterdam-Antwerp refining corridors anchor European supply security while Mumbai-Gujarat manufacturing clusters drive volume absorption.
United States
Architectural coatings manufacturers in Ohio and Pennsylvania consume solvent-grade white spirits for industrial wood finishing and automotive refinish applications. EPA enforcement of Clean Air Act volatile organic compound limits forces reformulation timelines that compress margins for conventional aliphatic producers. Houston-Gulf Coast petrochemical complexes concentrate hydrodesulfurization capacity serving domestic coatings demand.
Germany
Automotive OEM coating lines in Bavaria and Baden-Württemberg specify sub-0.1% aromatic white spirits for workplace exposure compliance. ECHA registration completion under REACH guidelines has clarified import pathways for certified European suppliers. Ludwigshafen industrial zone maintains captive solvent finishing infrastructure integrated with coatings R&D facilities.
India
Protective coatings demand from Mumbai-Pune manufacturing corridors and Gujarat chemical parks accelerates solvent consumption for infrastructure and marine applications. BIS certification standards govern solvent purity specifications for domestic industrial procurement. Dahej and Mundra port zones concentrate import-reliant blending capacity serving northern manufacturing demand.
China
Furniture export manufacturing in Guangdong and Zhejiang provinces sustains solvent consumption for lacquer and varnish finishing despite waterborne substitution pressures. NMPA-aligned occupational exposure standards tighten aromatic content limits in coastal manufacturing zones. Yangtze River Delta petrochemical clusters integrate solvent refining with downstream coatings production.
Japan
Precision electronics coatings and automotive refinish applications in Aichi and Kanagawa prefectures sustain demand for high-purity aliphatic solvents. METI-administered chemical substance regulations mandate hazard communication and substance tracking for industrial solvent distribution. Chubu-Nagoya manufacturing belt concentrates metal finishing solvent consumption serving automotive component suppliers.
White Spirits Market Vendor Landscape
Concentration sits with integrated petroleum refiners controlling upstream feedstock access and captive hydroprocessing infrastructure. The competitive structure tiers between global majors with full value chain integration, regional specialists serving geographic demand clusters, and independent blenders dependent on merchant naphtha supply. Strategic moves center on capacity rationalization in mature European markets and qualification partnerships with coatings formulators seeking certified low-aromatic supply.
Within the integrated refiner tier, ExxonMobil Corporation and Shell plc exemplify archetypes leveraging controlled distribution networks and refining scale. Hindustan Petroleum Corporation Limited occupies a position representing geographic proximity specialists serving South Asian manufacturing demand. DHC Solvent Chemie GmbH anchors the European specialty blender segment with proximity to German coatings R&D corridors.
| Leading Market Players |
|---|
| CEPSA |
| BP p.l.c. |
| ExxonMobil Corporation |
| JX Nippon Oil & Energy Corporation |
| Hindustan Petroleum Corporation Limited |
| Shell plc |
| Neste Oyj |
| DHC Solvent Chemie GmbH |
| TotalEnergies SE |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day inventory cycles at Rotterdam-Antwerp storage terminals concentrate pricing power with integrated refiners holding captive hydrodesulfurization capacity, while merchant blenders absorbing naphtha spot volatility face margin compression during feedstock price spikes. This lead-time band separates solvent-grade procurement into contract-of-take arrangements for automotive OEM coating lines versus spot-market purchasing by small-scale architectural formulators lacking storage infrastructure.
Pricing Analysis
The customization-premium spread between sub-0.1% aromatic solvent grades and conventional aliphatic products runs three-to-four price bands apart, with REACH-certified low-aromatic supply commanding sustained premiums from German automotive coating clusters. Contract-based long-term offtake dominates procurement for integrated coatings manufacturers, while spot-market transactions concentrate among independent blenders serving fragmented construction applications. Price differentiation hinges on certification grade and volume scale, with BIS-compliant Indian imports facing cost compression from domestic hydroprocessing capacity additions. Margins are tightening due to naphtha feedstock volatility, and small-to-mid-scale formulators exhibit the highest price sensitivity as they lack inventory hedging mechanisms.
Supply Chain Analysis
Strategic-stockpile preferences among German automotive OEMs contrast with just-in-time delivery mandates from North American metal fabrication clusters, fragmenting inventory strategies across end-use segments. Geographic supply concentration centers on the United States, Germany, and India, with Houston-Gulf Coast and Rotterdam-Antwerp corridors anchoring Atlantic basin availability. Raw material dependencies draw from C7-C12 naphtha fractions, hydrodesulfurization catalysts, and specialized adsorbent media for aromatic removal. Single-source vulnerability concentrates around merchant naphtha supply for non-integrated blenders lacking backward integration into refining. Distribution runs through qualified supplier programs bundling technical service and waste recovery, displacing traditional chemical distributor intermediaries in automotive and metal finishing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White spirits procurement is consolidating around service-attach models where solvent recovery and reclamation services expand faster than virgin solvent volumes, rewarding suppliers with closed-loop distillation capabilities. This service layer captures recurring revenue attachment while insulating margin pressure on commodity aliphatic sales.
For Market Incumbents: Fortify positions by deepening captive hydrodesulfurization capacity in South Asian manufacturing corridors and securing REACH certification maintenance for European supply continuity. Waterborne coating substitution threatens solvent-borne architectural volumes, demanding accelerated qualification partnerships with formulators seeking low-VOC exempt alternatives. Channel control through qualified supplier programs represents the critical defensive lever against distributor disintermediation. For New Entrants and Emerging Players: Differentiate on bio-based hydrocarbon feedstock certification aligned with EU Green Deal procurement preferences, targeting sustainability-premium positioning in public infrastructure coatings. Southeast Asian manufacturing migration into Vietnam and Indonesia industrial zones presents the most penetrable geography, with metal finishing and automotive refinish solvents showing underpenetrated demand. Direct technical service embedding with coatings R&D facilities offers the essential go-to-market angle against established distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated petroleum majors seeking to divest non-core specialty solvent assets, particularly European hydroprocessing units with stranded conventional aliphatic capacity. Long-term viability over the coming decade hinges on low-aromatic and bio-derived product mix transition rather than commodity solvent exposure. The signal to watch as inflection indicator is the pace of waterborne coating penetration in protective and marine applications previously resistant to substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrodesulfurization Capacity | Captive processing of naphtha feedstocks insulates margin volatility from merchant market exposure. |
| REACH Certification Maintenance and Expansion | ECHA compliance completion reduces import friction and secures European coatings manufacturer procurement. |
| Recycled Solvent Recovery Service Launch | Closed-loop distillation offerings attach recurring revenue streams to virgin solvent sales relationships. |
| Joint Venture in Southeast Asian Manufacturing Zones | Vietnam and Indonesia industrial corridors present underpenetrated demand for metal finishing solvents. |
| Bio-Based Hydrocarbon Feedstock Certification | EU Green Deal alignment opens public procurement channels and sustainability-premium positioning. |
Methodological Framework
The analysis maps solvent-grade aliphatic production, low-aromatic specialty refining, and recycled solvent recovery services, each validated through coatings formulators, refinery operations managers, and chemical distribution channel partners. Primary interviews with procurement leads at automotive OEM coating lines, plant managers at integrated petrochemical complexes, and technical R&D directors at specialty solvent blenders combined with secondary validation from ECHA registration databases, EPA Clean Air Act enforcement records, and BIS certification filings. Customs and trade data from Indian DGFT, SEC 10-K disclosures from listed refiners, and Cefic solvent market reports anchored bottom-up volume triangulation against top-down demand modeling across end-use segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation spanning grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from trend extrapolation of solvent consumption intensity in coatings applications, cross-referenced with construction and automotive production forecasts. Feedstock naphtha price trajectories, hydrodesulfurization capacity expansion timelines, and regulatory compliance cost burdens informed industry-specific forecast inputs without assuming discrete technology substitution rates.
Material uncertainties — crude-linked naphtha volatility, waterborne coating substitution acceleration, and multi-jurisdiction certification timeline delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding REACH enforcement continuity, EPA VOC limit stability, and BIS standard adherence without projecting discrete regulatory amendments. Revision becomes warranted when waterborne coating penetration in protective applications crosses thresholds that compress solvent consumption intensity faster than infrastructure expansion can offset.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Asia-Pacific Craft Beer Market
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Stout Market